
 Peanut Flour Market | 2026-2036
Peanut Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Peanut Flour Market Outlook
Food science talent is rotating toward plant-protein specialization as manufacturers reformulate legacy wheat-based products. ADM leverages its oilseed processing infrastructure to co-produce peanut flour with controlled fat profiles. Golden Peanut and Tree Nuts anchors supply from the southeastern United States through integrated shelling and milling operations. Protein Plus, LLC specializes in defatted grades targeting sports nutrition and clinical food applications.
Peanut flour consists of ground peanuts with variable oil content, typically ranging from 12% to 28% fat depending on whether mechanical pressing or solvent extraction precedes milling; manufacturers produce roasted, raw, blanched, and organic variants to match thermal stability and allergen-management requirements across baking, snack, sauce, and protein supplement applications. Roasted peanut flour dominates commercial volume due to its flavor intensity and Maillard-reaction stability in high-temperature processing, while organic peanut flour commands premium positioning through certified supply chains. Protein supplements represent the fastest-growing application as endurance athletes and aging populations seek complete amino-acid profiles from legume sources.
The FDA enforces aflatoxin limits under the Food Safety Modernization Act, requiring hazard analysis and preventive controls for domestic and imported peanut ingredients, while USDA grading standards for shelled peanuts indirectly shape flour quality tiers through lot consistency requirements. The EPA monitors solvent residues from hexane extraction processes used in defatted flour production. Stakeholders must monitor evolving FDA guidance on major allergen labeling for peanut-derived ingredients used in composite foods.
Market Dynamics
Domestic peanut processors in the United States are consolidating oilseed milling capacity to capture premium positioning in clean-label protein sourcing, redirecting supply chain investment toward defatted flour grades that meet FDA preventive control requirements.
Growth Catalysts
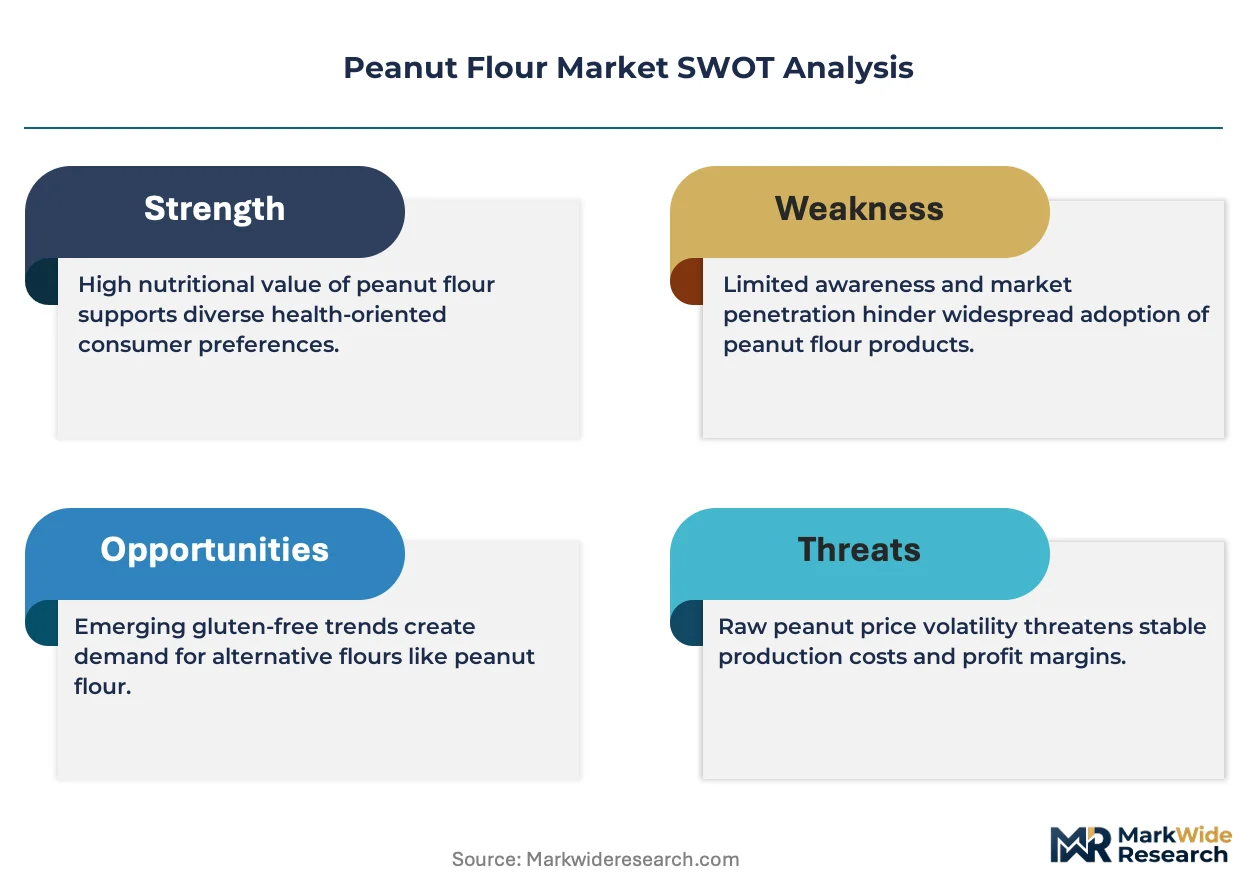
- FSMA preventive controls:The FDA's hazard analysis mandates for aflatoxin testing are standardizing quality tiers, rewarding processors with certified lot consistency and pushing marginal suppliers toward exit.
- Sports nutrition formulation:Endurance athletes and aging populations are demanding complete amino-acid profiles from legume sources, expanding volume for defatted grades in protein supplements.
- Maillard-reaction stability:Roasted peanut flour's thermal performance in high-temperature baking applications is displacing raw variants in commercial bakery procurement specifications.
Market Restraints
- Input cost volatility:Peanut shelling margins compress when domestic crop yields fluctuate, exposing flour processors to raw material price swings without forward-contract coverage.
- Solvent residue compliance:EPA monitoring of hexane extraction processes imposes capital burdens on defatted flour lines, constraining capacity expansion for mid-tier producers.
- Allergen labeling friction:Evolving FDA guidance on major allergen declarations for composite foods creates formulation uncertainty for manufacturers using peanut-derived ingredients.
Strategic Opportunities
- Clinical food applications:Defatted grades targeting medical nutrition and dysphagia management represent underdeveloped volume for processors with pharmaceutical-grade certification capabilities.
- Organic certification premiums:USDA organic supply chains command price separation through certified handling protocols, rewarding backward integration into controlled-origin shelling operations.
- Protein-fortified snack expansion:Extruded snack manufacturers are reformulating legacy wheat-based matrices with peanut flour to achieve clean-label protein claims.
Industry Challenges
- Food science specialization shortage:Plant-protein formulation expertise is rotating from animal-based research programs, creating recruitment competition among manufacturers reformulating legacy products.
- Preventive control documentation burden:FSMA compliance timelines require hazard analysis records spanning multiple processing stages, straining quality assurance staffing at smaller milling operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanut Flour Market |
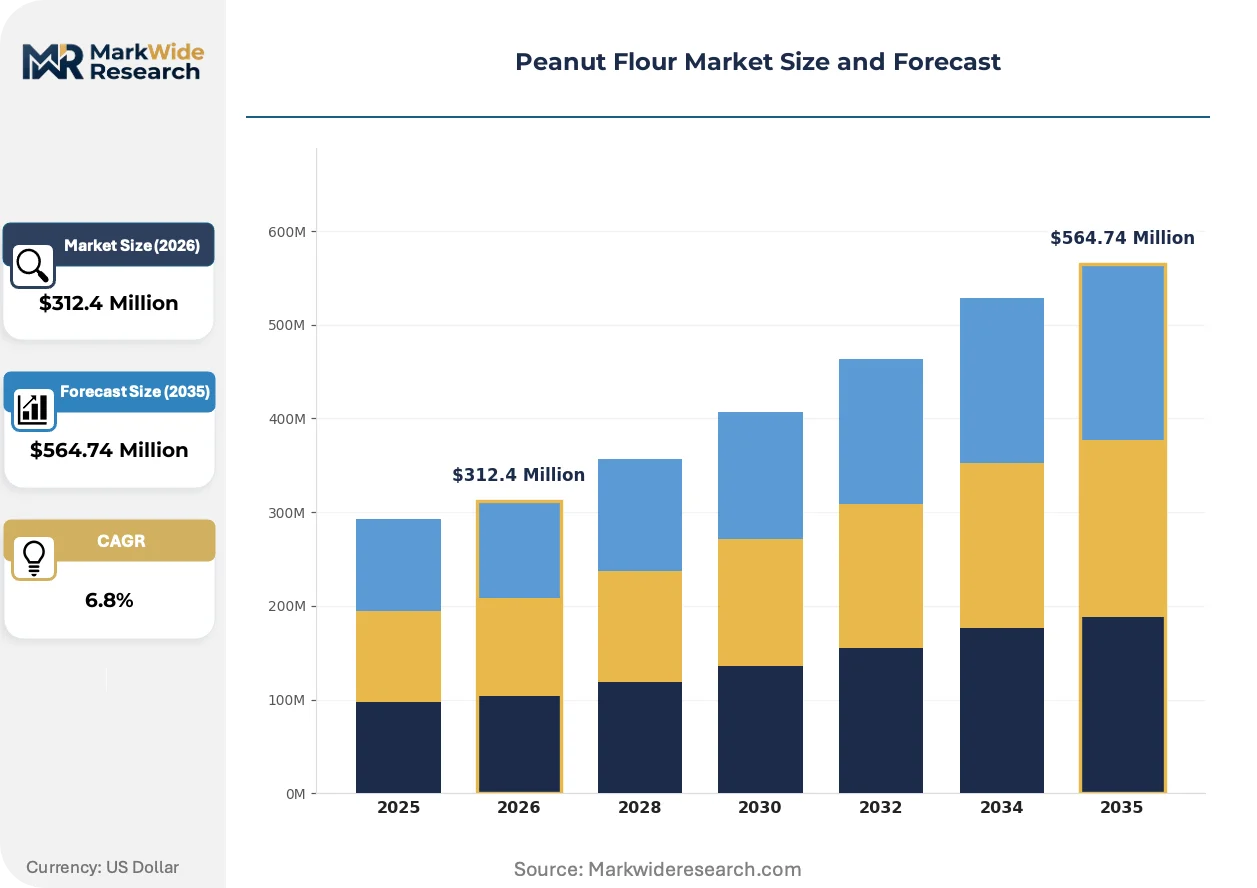
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roasted Peanut Flour, Raw Peanut Flour, Blanched Peanut Flour, Organic Peanut Flour Application: Baking, Snacks, Sauces, Protein Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Restaurants, Home Cooks, Health Enthusiasts |
| Companies Covered | ADM, Puyang Tianli Company Ltd., CUKRA, Amanda, Vinay Industries, Golden Peanut and Tree Nuts, Protein Plus, LLC, Qingdao Changshou, Shandong Chinut, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanut Flour Market Strategic Shifts
Mechanical pressing technology is compressing fat-content variability in peanut flour production, enabling precise protein standardization that matches end-use thermal stability requirements.
Supercritical CO2 extraction systems are miniaturizing for mid-scale oilseed processors, allowing localized defatting operations without solvent infrastructure. Regional cooperatives in the southeastern United States are piloting these units to retain value from crop origin through finished flour. The technology is miniaturizing capital requirements for quality-tier separation, fragmenting supply concentration among integrated shelling conglomerates.
The EPA's residual solvent monitoring protocols are tightening documentation requirements for hexane-derived defatted flour, forcing processors to validate extraction efficiency through third-party laboratory certification. Domestic manufacturers are responding by accelerating mechanical pressing adoption to eliminate regulatory exposure entirely. Imported flour volumes face heightened scrutiny at port-of-entry inspection points.
Direct-procurement relationships between flour mills and protein supplement brands are displacing traditional ingredient distributor networks, compressing margin layers and demanding lot-traceability documentation from origin. Sports nutrition contract manufacturers in the western United States are leading this channel restructuring, requiring certificate-of-analysis packages with every shipment. This pattern concentrates procurement leverage among volume buyers with technical specification expertise.
Peanut Flour Market Segmentation
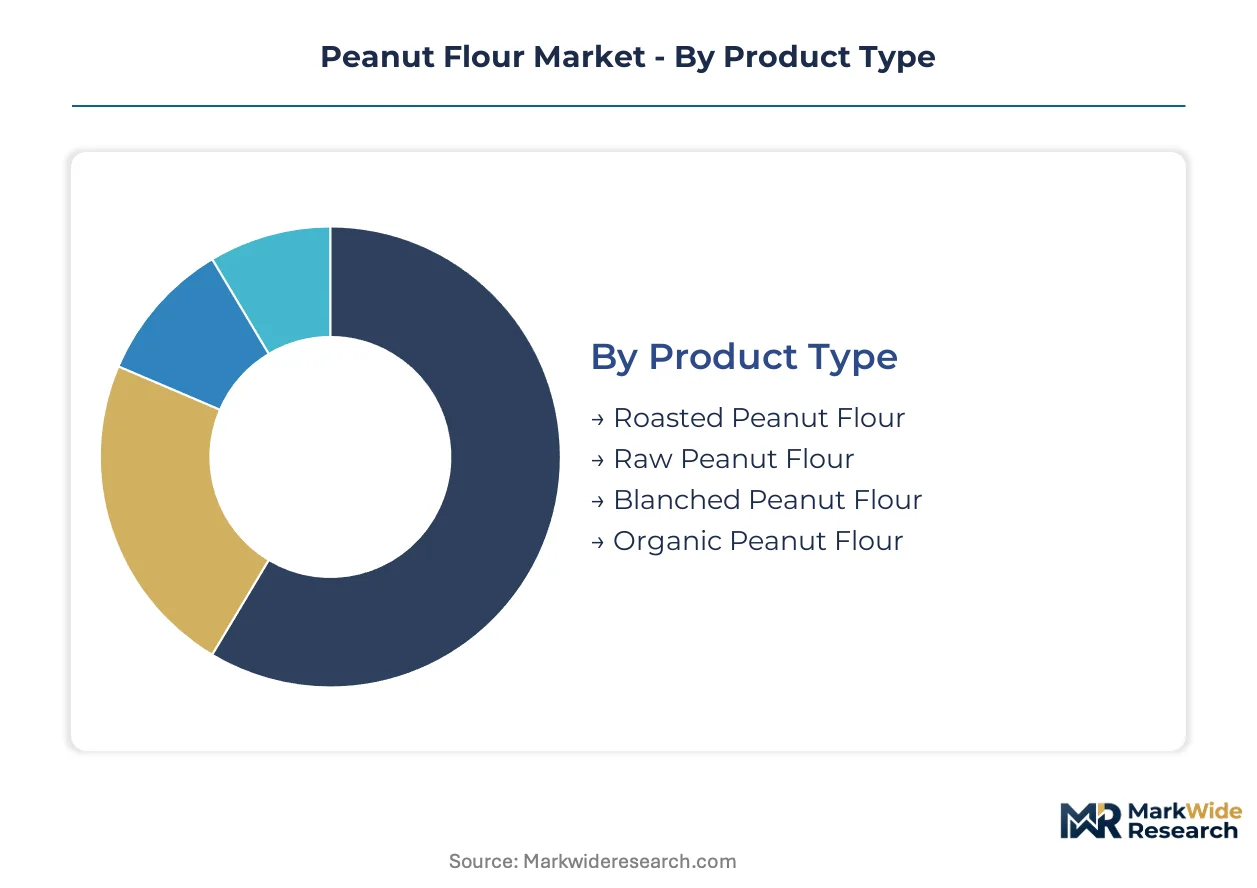
Peanut flour segmentation reflects divergent supply chain configurations across thermal processing grades and channel structures. Product type and application splits determine whether processors pursue commodity volume or premium positioning through certification tiers.
Product Type:
Domestic processors dominate roasted and blanched grades through integrated southeastern shelling operations, while organic variants rely on certified import streams from Argentina and China.
- Roasted Peanut Flour:Thermal processing develops Maillard-reaction compounds that stabilize flavor under high-temperature baking conditions. Commercial bakeries in the United States specify this grade for protein-fortified bread matrices, displacing raw alternatives in procurement contracts.
- Raw Peanut Flour:Unroasted peanuts retain native enzyme activity and milder flavor profiles suited to cold-process applications. European plant-based dairy formulators source this grade for neutral-taste protein enrichment where heat denaturation must be avoided.
- Blanched Peanut Flour:Skin removal prior to milling reduces astringency and improves color consistency in confectionery coatings.
- Organic Peanut Flour:USDA or EU organic certification requires segregated handling from shelling through packaging, commanding price premiums through audited supply chains.
Roasted peanut flour commands the established base. The steepest expansion runs through organic peanut flour.
Application:
Cost tier separation distinguishes commodity baking volume from clinical-grade protein positioning, with sports nutrition applications absorbing defatted premiums.
- Protein Supplements:Defatted grades deliver 40-50% protein concentration with complete amino-acid profiles competitive with whey isolates. Contract manufacturers in Utah and Colorado are reformulating legacy animal-based powders to capture endurance athlete demand.
- Baking:Partial fat retention in roasted grades improves moisture retention and crumb structure in gluten-free formulations. Regional commercial bakeries in the southeastern United States are the primary volume purchasers.
- Snacks:Extruded protein puffs and coated nuts utilize peanut flour for clean-label protein claims without synthetic additives.
- Sauces:Raw grades provide emulsification and thickening in Asian-style cooking sauces where peanut flavor must remain subtle.
Baking absorbs the highest tonnage. Protein supplements are climbing the fastest.
Distribution Channel:
Volume concentration favors direct sales to food manufacturers, while margin capture shifts toward specialty retail channels with technical specification support.
- Direct Sales:Flour mills negotiate annual contracts with protein supplement brands and commercial bakeries, bypassing distributor margins. Certificate-of-analysis documentation with every shipment is now standard.
- Specialty Stores:Health food retailers stock organic and defatted SKUs for home bakers and fitness consumers seeking small-batch procurement.
- Supermarkets:Mass retail carries conventional roasted grades in baking aisles, competing on price with almond and coconut flour alternatives.
- Online Retail:E-commerce platforms enable direct-to-consumer sales of niche variants with subscription models for recurring protein supplement purchases.
Direct sales anchor manufacturer procurement. Specialty stores are gaining share fastest.
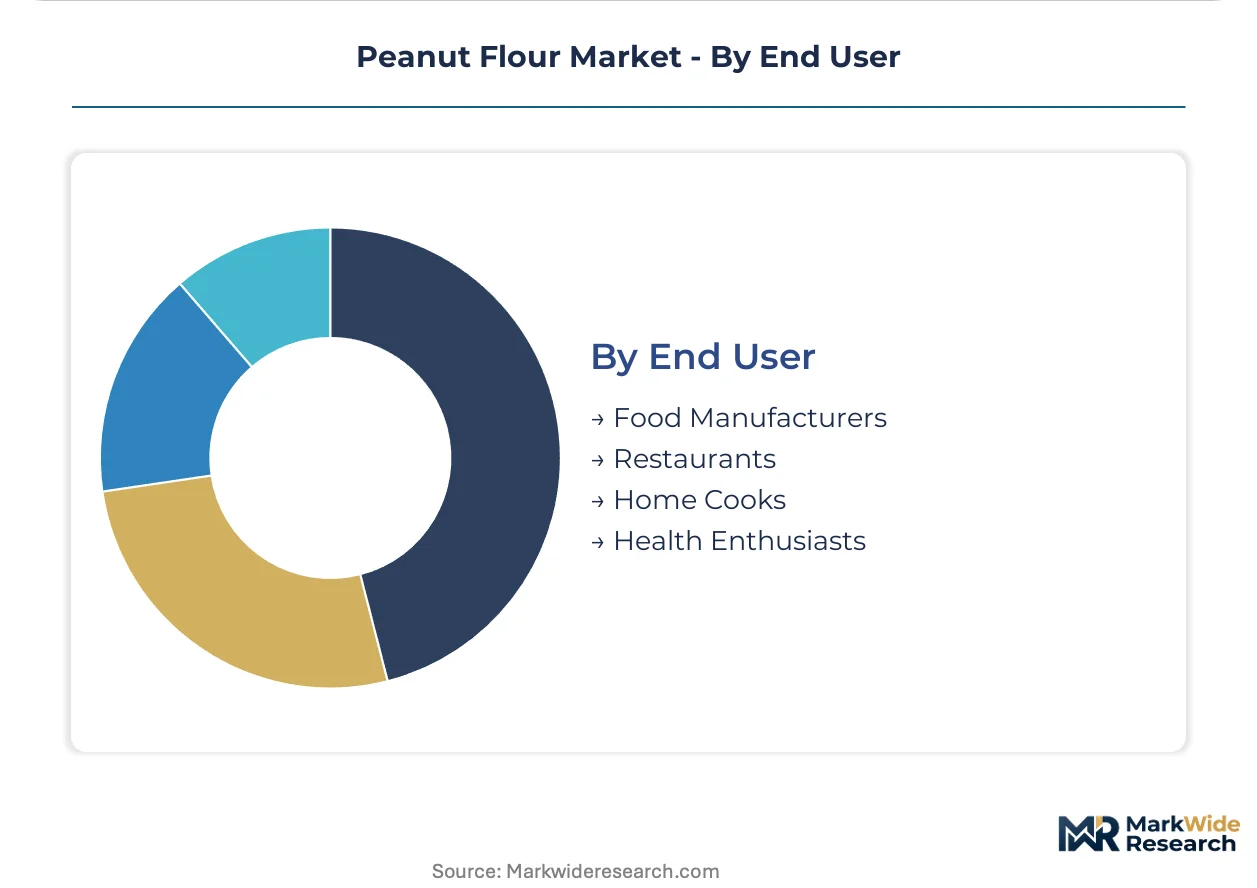
End User:
Customer type determines specification complexity, with food manufacturers demanding lot-traceability while home cooks prioritize convenience packaging.
- Food Manufacturers:Large-scale bakeries and snack producers require FSMA-compliant hazard analysis documentation and consistent protein standardization across 40,000-pound bulk shipments.
- Health Enthusiasts:Individual consumers purchasing through online channels drive demand for single-serve organic packaging with macronutrient labeling transparency.
- Restaurants:Chef-driven procurement favors raw and blanched grades for sauce applications in Asian and African cuisine segments.
- Home Cooks:Retail-sized packages in supermarkets serve gluten-free baking experimentation with recipe-support content marketing.
Food manufacturers dominate volume absorption. Health enthusiasts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize defatted grades for protein fortification, while European and Asian markets favor raw and roasted variants for traditional culinary applications.
United States
Domestic processors anchor supply through integrated southeastern shelling operations. The FDA's Food Safety Modernization Act mandates hazard analysis and preventive controls for aflatoxin testing across all peanut-derived ingredients. Georgia and Alabama host concentrated milling capacity where Golden Peanut and Tree Nuts operates captive defatting lines.
China
Raw peanut flour dominates export volume to European plant-based dairy formulators seeking neutral-taste protein enrichment. The national food safety regulator enforces mycotoxin limits through GB standards for shelled peanuts entering processing channels. Shandong Province clusters mechanical pressing operations supplying defatted grades to domestic sports nutrition brands.
Germany
European plant-protein manufacturers source organic-certified peanut flour for clean-label bakery reformulation. EFSA guidelines on major allergen labeling create compliance complexity for composite food manufacturers. Hamburg and Rotterdam serve as import consolidation points where traders manage certified organic supply chains from Argentina.
Argentina
Organic peanut cultivation expands through certified handling protocols commanding premium export positioning. The national agricultural regulator oversees phytosanitary certification for EU-bound shipments. Cordoba Province concentrates shelling and milling operations integrated with European organic certification bodies.
India
Domestic snack manufacturers absorb roasted grades for traditional confectionery and extruded protein products. FSSAI standards govern aflatoxin limits and labeling requirements for peanut-derived ingredients. Gujarat hosts oilseed processing clusters where mechanical pressing capacity serves both domestic baking and regional export demand.
Peanut Flour Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier controls captive shelling-through-milling operations with FSMA-compliant preventive control documentation. The specialist tier concentrates on defatted grades for sports nutrition and organic certification premiums. Strategic differentiation runs through backward integration into controlled-origin supply chains and pharmaceutical-grade certification capabilities for clinical food applications.
Within the integrated processor tier, ADM and Golden Peanut and Tree Nuts exemplify scale-driven positioning through oilseed infrastructure co-production. Protein Plus, LLC occupies the specialist position targeting defatted grades for sports nutrition and clinical applications. These three anchors represent divergent strategic bets on volume efficiency versus premium certification capture.
| Leading Market Players |
|---|
| ADM |
| Puyang Tianli Company Ltd. |
| CUKRA |
| Amanda |
| Vinay Industries |
| Golden Peanut and Tree Nuts |
| Protein Plus, LLC |
| Qingdao Changshou |
| Shandong Chinut |
| Others |
Value Chain & Pricing Dynamics
Captive shelling-through-milling operations in Georgia and Alabama generate scale economies that compress unit costs for defatted grades while establishing price floors through FSMA-compliant certification overhead. Domestic processors leverage integrated infrastructure to undercut fragmented importers on lot-traceability premiums, concentrating procurement leverage among volume buyers with technical specification expertise.
Pricing Analysis
Annual offtake contracts between flour mills and protein supplement brands dominate commercial volume, displacing spot-market transactions as certificate-of-analysis documentation becomes standard. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified supply chains from conventional roasted grades and commodity raw variants. Cost compression in mid-tier defatted flour is intensifying because EPA hexane-residue monitoring imposes third-party laboratory certification burdens. Regional commercial bakeries in the southeastern United States exhibit highest price sensitivity, while sports nutrition contract manufacturers in Utah and Colorado absorb premiums for pharmaceutical-grade certification capabilities.
Supply Chain Analysis
Port congestion at Savannah and Charleston elevates inbound logistics costs for Argentine organic peanuts entering southeastern shelling operations, compressing margins on certified supply chains. Production gravity centers on the United States, China, and Argentina, with mechanical pressing capacity in Shandong Province and Cordoba Province feeding export demand for defatted grades. Raw material dependencies include runner peanut seedstock, hexane solvent for extraction lines, and organic certification audit services. Single-source vulnerability concentrates in southeastern U.S. shelling infrastructure, where Golden Peanut and Tree Nuts controls captive defatting capacity. Distribution runs through direct-procurement relationships displacing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in peanut flour reflects accelerating reformulation of legacy wheat-based products by endurance athletes and aging populations seeking complete amino-acid profiles from legume sources.
For Market Incumbents: Compound defensive positioning by deepening backward integration into controlled-origin shelling operations in Georgia and Alabama, and accelerate mechanical pressing adoption to eliminate EPA hexane-exposure entirely. FSMA preventive control documentation burdens strain quality assurance staffing at smaller competitors, creating consolidation opportunity through certified lot-consistency acquisition. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade certification capabilities for clinical food applications targeting medical nutrition and dysphagia management, the most penetrable segment given underdeveloped volume among existing processors. Supercritical CO2 extraction miniaturization enables localized defatting without solvent infrastructure, offering a capital-efficient go-to-market angle through regional cooperatives in the southeastern United States. For Investors and Strategic Acquirers: Specialist processors with USDA organic supply chain integration and sports nutrition brand relationships represent the priority acquisition archetype for long-term viability in a market where clean-label protein sourcing commands sustained premium positioning. Watch FDA guidance evolution on major allergen labeling for composite foods as the critical inflection indicator for formulation risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shelling Operations | Captive supply from Georgia and Alabama plantations locks in quality-tier separation through controlled-origin handling protocols. |
| Mechanical Pressing Capacity Expansion | Elimination of hexane extraction removes EPA residual-solvent monitoring exposure entirely for defatted flour lines. |
| Pharmaceutical-Grade Certification Investment | Clinical food applications for medical nutrition and dysphagia management open underdeveloped volume with premium capture potential. |
| Direct-Procurement Channel Development | Bypassing distributor networks compresses margin layers while demanding lot-traceability documentation from origin. |
| Organic Certification Supply Chain Integration | USDA organic handling protocols from shelling through packaging command price separation through audited supply chains. |
Study Parameters
A spread of perspectives from food science formulation directors, FSMA compliance officers at milling operations, sports nutrition contract manufacturing procurement leads, and commercial bakery category managers converged on the working assumptions shaping volume and value trajectories. Primary interview intelligence combined with secondary validation from FDA guidance documents, USDA organic certification databases, EPA residual solvent monitoring protocols, and customs trade records for shelled peanut imports. Bottom-up capacity assessments across southeastern U.S. shelling operations triangulated against top-down protein supplement demand modeling.
Segmentation dimensions modeled include thermal processing grade, fat content tier, application category, certification status, and distribution channel structure across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating sports nutrition penetration rates and clinical food application expansion. Industry-specific forecast inputs captured FSMA compliance timeline acceleration and mechanical pressing technology adoption curves among mid-scale processors.
The analysis sits within stated boundaries; outcomes outside sustained FDA preventive control enforcement or abrupt peanut crop yield disruption would require recalibration. Forecasts reflect documented assumptions regarding allergen labeling guidance evolution and supercritical CO2 extraction miniaturization adoption. Practitioners should keep alternative scenarios live as EPA hexane-monitoring protocols and organic certification audit backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Based Ingredients Market
Ingredients
Soy Derivatives Market
Ingredients
Cacao Extracts Market
Ingredients
Thinned Starch Market
Ingredients
Pea Peptones Market
Ingredients
GCC Egg Powder Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Dried Beet Pulp Market
Ingredients
Egg Free Premix Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Avocado Oil Market
Ingredients
Isoamyl Laurate Market
Ingredients
Instant Starches Market
Ingredients
Millet Protein Market
Ingredients
Drum to Hopper Blends Market
Ingredients
North America Milk Protein Market