
 Sri Lanka Starch and Starch Derivative Market | 2026-2036
Sri Lanka Starch and Starch Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Starch and Starch Derivative Market Analytics
Market Dynamics
Asset-light leasing arrangements for processing equipment are reshaping competitive entry in Sri Lanka's starch sector. Lanka Starch Mills leverages captive sourcing from domestic tapioca cooperatives to sustain margin stability. Angel Starch & Food Pvt Ltd specializes in modified starch grades for pharmaceutical binding applications. Essmark Worldwide Pvt. Ltd. controls distribution networks linking Colombo processors to regional wholesale channels.
Product Segmentation
Starch and starch derivatives comprise carbohydrate polymers extracted from botanical sources through wet milling, enzymatic conversion, or chemical modification, serving as thickeners, binders, and stabilizers across industrial formulations. Native starch retains original granule structure with amylose-amylopectin ratios dictating gel strength and retrogradation behavior, while modified starch undergoes physical or chemical alteration to enhance process tolerance under shear and temperature stress. Modified starch commands premium positioning in Sri Lanka's pharmaceutical and personal care segments where SLS compliance and functional consistency justify higher formulation costs. Liquid starch occupies volume leadership in Colombo's textile and paper industries due to ease of handling and direct-injection compatibility with existing process lines.
Regulatory Environment
Sri Lanka Standards Institution (SLSI) certification governs food-grade starch specifications, while the country's national pharmaceutical regulator enforces GMP-aligned excipient standards for drug applications. Import tariff structures under Sri Lanka Customs and DGFT-linked duty frameworks influence raw material sourcing economics for tapioca and corn feedstock. Stakeholders must monitor evolving SLSI harmonization with Codex Alimentarius protocols and anticipate how bioeconomy policy shifts could redirect cassava cultivation incentives toward industrial starch rather than ethanol feedstock.
Market Dynamics
Asset-light leasing arrangements for processing equipment are reshaping competitive entry in Sri Lanka's starch sector, allowing new processors to bypass capital-intensive fixed-asset commitments while established players like Lanka Starch Mills leverage captive sourcing from domestic tapioca cooperatives to sustain margin stability.
Growth Catalysts
- Processed food manufacturing corridor expansion:Colombo's food and beverage manufacturers drive starch derivative adoption as ready-meal and convenience product lines multiply.
- BIS-aligned import quality protocols:Harmonized standards with India's Bureau of Indian Standards reduce technical barriers for cross-border raw material flows.
- Pharmaceutical excipient upgrading:Sri Lanka's national pharmaceutical regulator enforces GMP-aligned standards that elevate local modified starch specifications for tablet binding applications.
Market Restraints
- Tapioca feedstock volatility:Domestic cassava cultivation competes with ethanol feedstock demand, creating input cost instability for native starch processors.
- Import tariff structures:Sri Lanka Customs and DGFT-linked duty frameworks elevate landed costs for corn-based raw materials, compressing formulation margins.
- Modified starch technical limitations:Heat-shear tolerance gaps in certain pharmaceutical grades force reliance on imported specialty products.
Strategic Opportunities
- Southern Province cultivation incentives:Bioeconomy policy shifts could redirect cassava farming toward industrial starch rather than fuel ethanol.
- Textile sizing application expansion:Colombo's garment sector presents underpenetrated demand for liquid starch in fabric finishing operations.
- SLSI-Codex harmonization:Alignment with Codex Alimentarius protocols would unlock export qualification for Sri Lankan food-grade derivatives.
Industry Challenges
- Specialized process engineering talent scarcity:Wet milling and enzymatic conversion expertise remains concentrated among a limited technical workforce.
- Dual certification timeline compression:Simultaneous SLSI food-grade and pharmaceutical excipient approvals extend product commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Starch and Starch Derivative Market |
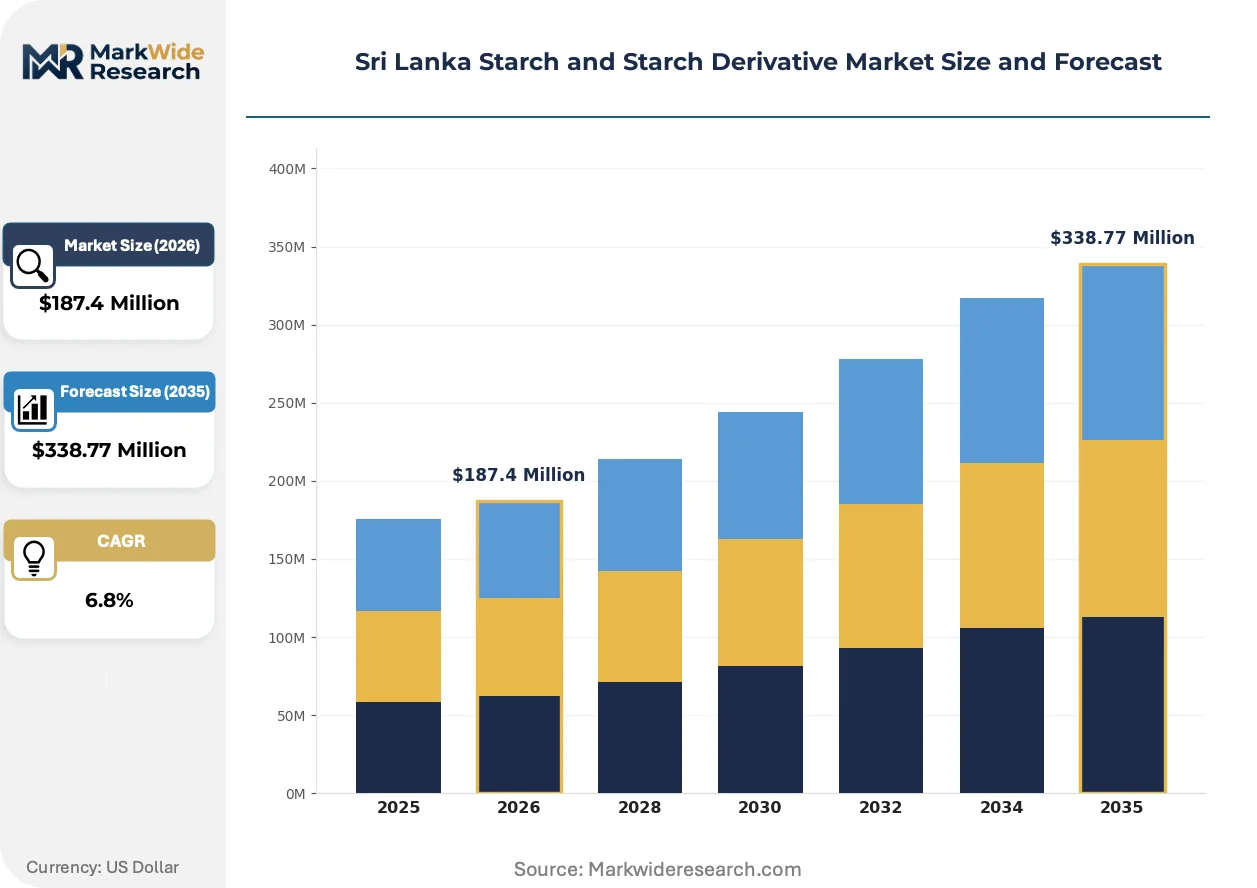
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Liquid Starch, Starch Syrup Application: Food & Beverage, Pharmaceuticals, Personal Care, Industrial Adhesives Source: Corn, Potato, Tapioca, Wheat Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | One Capital Global Private Limited, Essmark Worldwide Pvt. Ltd., Lions Roar Trading Private Limited, Angel Starch & Food Pvt Ltd, KMC, Krishnasamy Rajendran, Iceylon Commodities Pvt. Ltd., Lanka Starch Mills, Thambili Exports LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Starch and Starch Derivative Market Evolving Landscape
Digital process control systems and enzymatic conversion refinements are compressing batch-to-batch variability while regulatory alignment pressures force simultaneous compliance upgrades across food and pharmaceutical grades.
Enzymatic starch modification is virtualizing traditional acid-thinning processes in Sri Lanka's pharmaceutical-grade production. Local excipient manufacturers deploy precision enzyme dosing to achieve targeted viscosity profiles without harsh chemical residues. This technology is virtualizing quality assurance workflows by embedding real-time molecular weight monitoring into continuous processing lines.
SLSI harmonization with Codex Alimentarius protocols is accelerating specification convergence across Sri Lankan food-grade starch categories. The national standards body mandates updated testing methodologies for amylose-amylopectin ratio verification. Modified starch exporters to Middle Eastern markets face accelerated compliance timelines as destination countries reference Codex-aligned certificates.
Direct-procurement relationships between Colombo textile mills and starch processors are displacing traditional distributor intermediaries. Fabric sizing operations now negotiate volume contracts with modified starch specialists for just-in-time liquid delivery. This pattern concentrates most visibly in Katunayake's export processing zone where garment manufacturers prioritize supply security over price arbitrage.
Sri Lanka Starch and Starch Derivative Market Segmentation
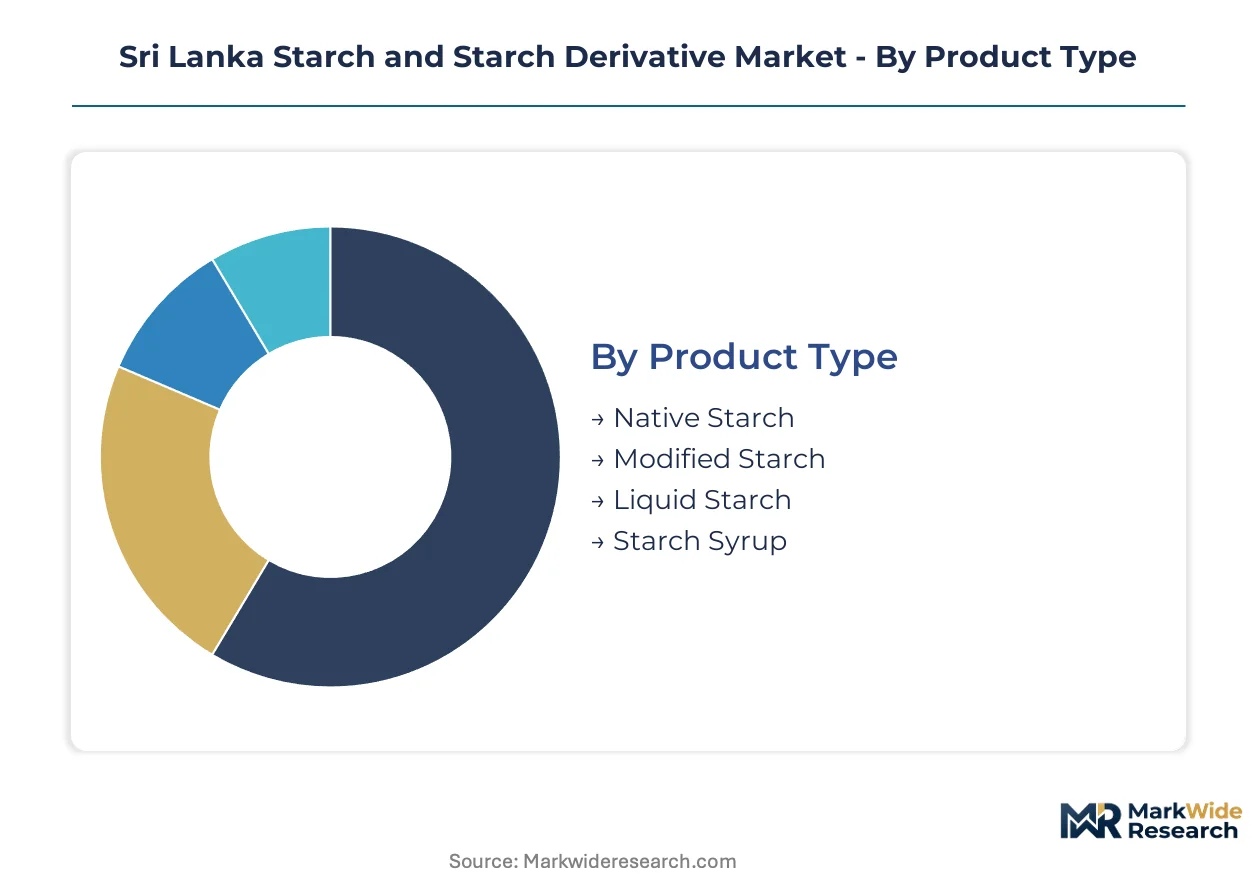
Starch derivative demand in Sri Lanka fragments across functional specifications, regulatory compliance tiers, and feedstock provenance. Each segmentation axis reveals distinct margin structures and procurement patterns that determine competitive positioning.
Product Type:
Mature industrial grades coexist with emerging pharmaceutical-grade specifications across Sri Lanka's processing landscape.
- Native Starch:Unmodified carbohydrate polymers retain original amylose-amylopectin ratios from wet-milled botanical sources. Colombo's traditional food manufacturers source native tapioca starch for cost-sensitive thickening applications where process tolerance demands remain moderate.
- Modified Starch:Physical or chemically altered polymers withstand shear stress and temperature extremes in industrial formulations. Sri Lanka's pharmaceutical excipient manufacturers specify cross-linked and pregelatinized grades for tablet binding under GMP-aligned national regulatory standards.
- Liquid Starch:Pumpable colloidal suspensions enable direct-injection processing without dry-mixing infrastructure. Katunayake garment mills procure liquid starch for textile sizing operations requiring consistent viscosity profiles.
- Starch Syrup:Enzymatically hydrolyzed glucose polymers serve as humectants and sweetening agents. Sri Lankan confectionery processors utilize low-DE syrups for moisture retention in packaged sweets.
Native starch retains volume leadership; modified starch holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity food applications from premium pharmaceutical and personal care specifications.
- Food & Beverage:Thickeners, stabilizers, and texturizers in processed meals, sauces, and convenience foods. Colombo's ready-meal manufacturers drive native and modified starch procurement as product line diversification accelerates.
- Pharmaceuticals:Excipient-grade binders, disintegrants, and coating agents for solid dosage forms. Sri Lanka's national pharmaceutical regulator enforces GMP-aligned standards that elevate local modified starch specifications.
- Personal Care:Rheology modifiers and film-formers in cosmetics and hygiene products. SLS-certified modified starches command premium positioning where functional consistency justifies higher formulation costs.
- Industrial Adhesives:Bio-based binders for paper lamination and corrugated board manufacturing. Sri Lankan packaging converters source oxidized starch grades for water-resistant adhesive formulations.
Food and beverage applications retain volume leadership; pharmaceutical specifications hold the steepest expansion curve.
Source:
Geographic supply concentration and import dependency create divergent feedstock economics across Sri Lankan processors.
- Corn:Import-dependent yellow dent maize supplies high-amylose starch for industrial applications. DGFT-linked duty frameworks elevate landed costs, compressing margins for corn-based native starch processors.
- Potato:Cold-gelling amylopectin-rich starch from tuber sources delivers superior clarity and texture. Sri Lankan sauce manufacturers specify potato starch for premium product lines where visual appeal commands price differentiation.
- Tapioca:Domestic cassava cultivation through cooperative networks supports cost-competitive native starch production. Lanka Starch Mills leverages captive sourcing from Southern Province farmers to sustain margin stability against ethanol feedstock competition.
- Wheat:Gluten-contaminated starch from flour milling byproducts serves lower-specification adhesive applications. Limited local wheat processing constrains availability for food-grade specifications.
Tapioca retains volume leadership; potato starch holds the steepest expansion curve.
Distribution Channel:
Customer type and procurement scale determine channel selection across Sri Lanka's fragmented buyer landscape.
- Online:Digital procurement platforms aggregate small-batch orders from regional food processors. Emerging e-commerce channels serve Colombo-area manufacturers seeking transparent pricing and rapid sample fulfillment.
- Supermarkets:Retail-packaged native starch for household and small commercial kitchens. Urban consumers in Colombo and Kandy drive branded food-grade starch purchases through modern trade outlets.
- Specialty Stores:Technical-grade modified starches for pharmaceutical and personal care formulators. Angel Starch & Food Pvt Ltd maintains dedicated distribution through chemical supply houses serving GMP-certified manufacturers.
- Wholesalers:Bulk liquid and dry starch distribution to textile mills and paper converters. Essmark Worldwide Pvt. Ltd. controls regional wholesale channels linking Colombo processors to up-country industrial users.
Wholesalers retain volume leadership; online channels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioeconomy policy incentives and SLSI certification requirements are concentrating starch processing activity across Sri Lanka's provincial manufacturing corridors. Colombo's food and beverage sector anchors national demand, while regional cultivation patterns determine feedstock economics.
Western Province
Colombo's processed food manufacturing corridor drives modified starch procurement for ready-meal and convenience product lines. SLSI certification mandates govern food-grade specifications for exporters targeting Middle Eastern markets. Katunayake's export processing zone concentrates textile sizing operations sourcing liquid starch through direct-procurement contracts.
Southern Province
Domestic tapioca cultivation through cooperative networks supplies captive feedstock to native starch processors. The country's bioeconomy policy framework could redirect cassava farming toward industrial starch rather than fuel ethanol feedstock. Hambantota's emerging industrial zone attracts starch derivative investments seeking port access for regional distribution.
Central Province
Pharmaceutical excipient upgrading elevates demand for GMP-aligned modified starch specifications in tablet binding applications. The national pharmaceutical regulator enforces quality standards that compress dual certification timelines for local manufacturers. Kandy's chemical supply houses serve as distribution nodes for technical-grade starches.
Sabaragamuwa Province
Rubber and tea plantation adjacencies create niche adhesive applications for oxidized starch grades in packaging converters. DGFT-linked duty frameworks on corn imports disadvantage processors lacking tapioca supply agreements. Ratnapura's wholesale channels connect regional industrial users to Colombo-based distributors.
North Western Province
Coconut processing byproduct streams offer alternative carbohydrate sources for specialty starch formulations. Import tariff structures elevate landed costs for potato starch targeting premium sauce manufacturers. Puttalam's salt and chemical industries generate adjacent demand for industrial starch derivatives.
Sri Lanka Starch and Starch Derivative Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated domestic processors and import-dependent trading specialists. Asset-light leasing arrangements lower barriers for new entrants, while established players secure margin stability through captive sourcing relationships. Three archetypes dominate: cooperative-linked millers, pharmaceutical-grade specialists, and wholesale distribution controllers. Competitive moves concentrate on backward integration into feedstock supply and direct-procurement displacement of traditional intermediaries.
Among cooperative-linked domestic processors, Lanka Starch Mills exemplifies the integrated archetype through captive tapioca sourcing arrangements. Pharmaceutical-grade specialists occupy the premium tier, with Angel Starch & Food Pvt Ltd representing modified starch capabilities for excipient applications. Wholesale distribution controllers anchor regional connectivity, as Essmark Worldwide Pvt. Ltd. occupies a position linking Colombo processors to up-country industrial users through bulk liquid and dry starch channels.
| Leading Market Players |
|---|
| One Capital Global Private Limited |
| Essmark Worldwide Pvt. Ltd. |
| Lions Roar Trading Private Limited |
| Angel Starch & Food Pvt Ltd |
| KMC |
| Krishnasamy Rajendran |
| Iceylon Commodities Pvt. Ltd. |
| Lanka Starch Mills |
| Thambili Exports LLC |
| Others |
Value Network & Pricing Analysis
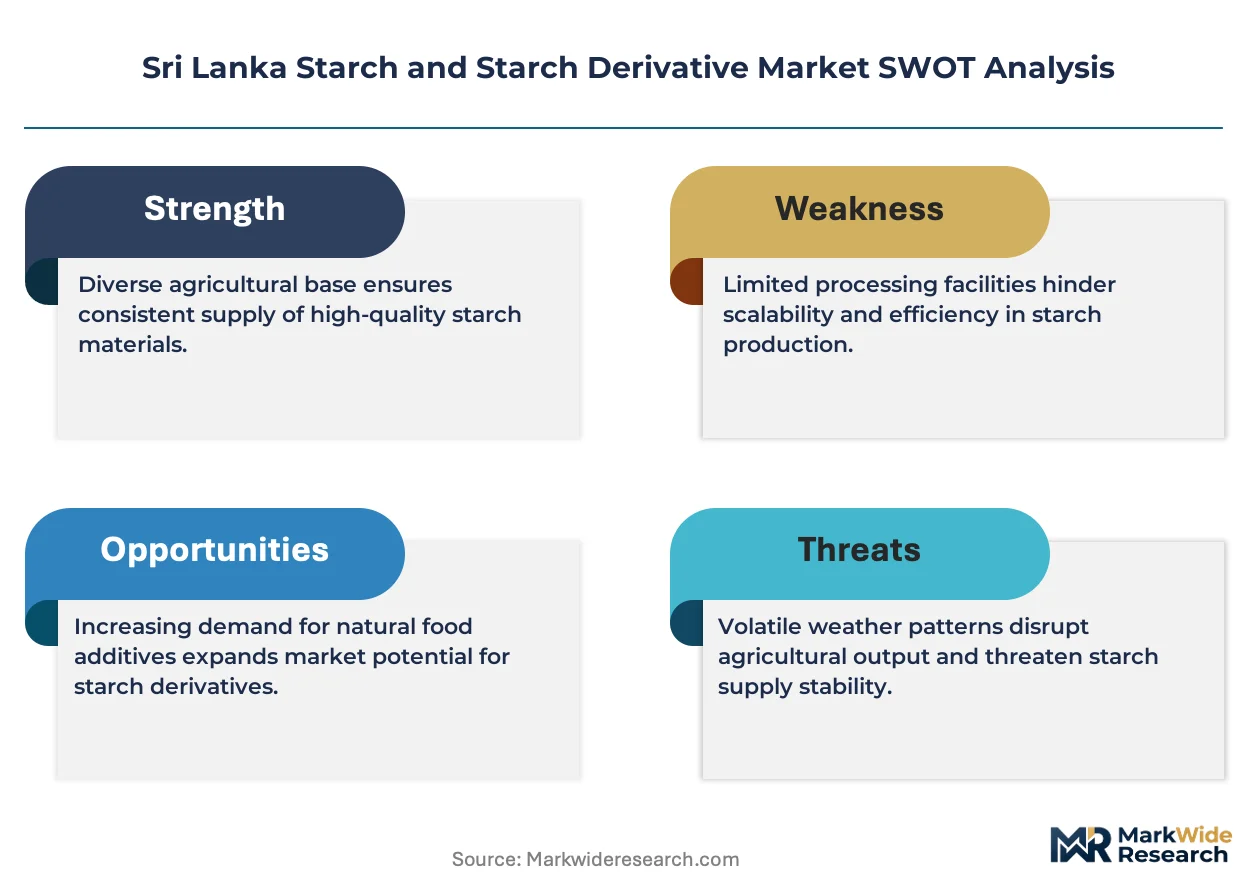
Domestic tapioca cooperative networks in Sri Lanka's Southern Province anchor feedstock economics, concentrating margin pools with processors who command captive sourcing arrangements while import-dependent competitors absorb elevated landed costs for corn-based alternatives.
Pricing Analysis
Certification level creates the primary spread across Sri Lanka's starch derivative tiers, with SLSI food-grade and GMP-aligned pharmaceutical excipient grades commanding substantial premiums over industrial specifications. Three-tier pricing structure separates premium pharmaceutical grades from standard food-certified derivatives from economy-level industrial starches. Pricing pressure stems from DGFT-linked duty frameworks elevating corn starch import costs, compressing margins for non-integrated processors. Small-scale Colombo food manufacturers exhibit highest price sensitivity, while pharmaceutical formulators prioritize functional consistency over unit economics.
Supply Chain Analysis
Bureau of Indian Standards alignment protocols function as de facto export-control mechanisms, restricting non-compliant Sri Lankan derivatives from accessing Indian subcontinent markets. Geographic supply concentrates in India for enzymatic conversion catalysts, Thailand for specialty modified starch reference standards, and domestic Southern Province cooperative networks for tapioca feedstock. Raw material dependencies span tapioca roots, yellow dent maize imports, and precision enzyme formulations for pharmaceutical-grade production. Single-source vulnerability runs through India's BIS-certified specialty additive suppliers. Distribution runs through Colombo-based wholesale controllers linking processors to up-country textile mills and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sri Lanka's starch derivative market fragments across certification tiers and feedstock sourcing models, with pharmaceutical excipient upgrading and bioeconomy policy shifts creating distinct competitive niches for differentiated positioning.
For Market Incumbents: Insulate margin stability by deepening captive tapioca sourcing agreements with Southern Province cooperatives before bioeconomy policy redirects cassava toward ethanol feedstock. Accelerate dual SLSI-Codex harmonization investments to preempt Middle Eastern export qualification requirements. Defensive capacity expansion into Hambantota's emerging industrial zone secures port-advantaged distribution positioning against new entrants. For New Entrants and Emerging Players: Pharmaceutical-grade modified starch for tablet binding applications in Central Province represents the most penetrable entry point, given GMP-aligned regulatory upgrading and limited local enzymatic conversion expertise. Asset-light leasing arrangements for wet milling equipment bypass capital-intensive fixed-asset barriers. Direct-procurement relationships with Katunayake export processing zone textile mills displace traditional distributor intermediaries for liquid starch volume capture. For Investors and Strategic Acquirers: Capital is best deployed toward cooperative-linked domestic processors with backward integration into tapioca supply and demonstrated SLSI certification capabilities, as these archetypes exhibit durable margin structures across commodity cycles. Long-term viability hinges on bioeconomy policy direction and Codex harmonization timelines. The signal to watch is SLSI publication of updated amylose-amylopectin testing methodologies, which would accelerate compliance investment requirements and consolidation pressure on sub-scale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tapioca Cultivation | Captive feedstock supply insulates Lanka Starch Mills from ethanol feedstock competition and import tariff volatility. |
| SLSI-Codex Harmonization Investment | Alignment with Codex Alimentarius protocols unlocks Middle Eastern export qualification for Sri Lankan food-grade derivatives. |
| Enzymatic Conversion Capability Buildout | Precision enzyme dosing technology enables pharmaceutical-grade modified starch production under GMP-aligned national standards. |
| Direct-Procurement Channel Development | Katunayake garment manufacturers prioritize supply security over price arbitrage in fabric sizing liquid starch contracts. |
| Asset-Light Processing Equipment Leasing | Leasing arrangements lower competitive entry barriers for new processors seeking to bypass capital-intensive fixed-asset commitments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wet milling plant managers, pharmaceutical excipient procurement leads, textile mill sizing supervisors, and SLSI certification officers. Secondary validation drew from Sri Lanka Customs import records, SLSI standards documentation, Bureau of Indian Standards technical protocols, and pharmaceutical regulator GMP guidelines. Bottom-up feedstock cultivation estimates and top-down processed food manufacturing demand assessments were triangulated to establish market sizing.
Calibration anchored volume projections to observed capacity utilization across Colombo's processing corridor and announced expansion timelines in Hambantota's emerging industrial zone. Segmentation dimensions modeled include product type tier, application specification, feedstock source provenance, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis of historical price-volume relationships and elasticity estimates for pharmaceutical versus industrial grade demand.
Practitioners should monitor SLSI-Codex harmonization implementation schedules and bioeconomy policy redirection of cassava cultivation incentives for early signals of competitive repositioning. Forecasts reflect documented assumptions regarding import tariff stability and enzymatic conversion technology diffusion rates. Material shifts in DGFT duty frameworks or pharmaceutical regulator GMP stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market