
 Green Gram Powder Market | 2026-2036
Green Gram Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Green Gram Powder Market Insights
Asset-light contract milling and third-party processing arrangements is narrowing the capital barrier for regional brands entering premium organic segments. Tata Sampann leverages backward integration into pulse procurement networks across Maharashtra and Karnataka to secure supply consistency. Patanjali anchors its position through Ayurveda-aligned positioning that commands shelf space in traditional retail. Oziva competes in the direct-to-consumer nutritional space with protein-forward formulation marketing.
Green gram powder consists of dehulled, roasted or raw mung bean (Vigna radiata) kernels ground to fine particle size, typically retaining protein content above 20 percent and fiber at 15-16 percent, serving as a functional ingredient in gluten-free baking, protein fortification, and traditional food systems. The organic product type commands margin premiums through certification overhead and export eligibility to North American and European buyers. Nutritional supplements represent the fastest-growing end-use channel as fitness-oriented consumers shift from whey to legume-derived protein sources. Supermarkets sustain volume throughput for conventional grades, while health food stores concentrate distribution of fortified and specialty variants.
FSSAI fortification standards and India's PLI scheme for food processing infrastructure shape domestic product development and capacity expansion decisions. Organic certification under India's NPOP and equivalency arrangements with USDA NOP and EU 2018/848 determine export market access eligibility for processors. Stakeholders must monitor evolving EU deforestation-free supply chain due diligence requirements and their application to imported legume ingredients.
Market Dynamics
The Green Gram Powder Market pivots on the tension between India's FSSAI fortification mandates and the sourcing scramble for certified organic grades that unlock North American and European export eligibility. Processors must reconcile domestic compliance with international certification overhead.
Growth Catalysts
- FSSAI Fortification Guidelines:India's mandatory micronutrient standards in staple foods are pulling green gram powder into institutional procurement channels for school nutrition and public distribution systems.
- Plant-Based Protein Transition:Nutritional supplement formulators are substituting whey with legume-derived inputs, creating dedicated demand streams for high-protein mung fractions.
- Export-Oriented Processing Clusters:South India's established mung consumption culture supports certified organic capacity that serves EU and North American buyers under equivalency arrangements.
Market Restraints
- Input Cost Volatility:Mung bean prices fluctuate with monsoon-dependent domestic harvests and Myanmar import volumes, compressing processor margins on fixed-price export contracts.
- Certification Overhead:India's NPOP organic certification and USDA NOP equivalency maintenance impose recurring audit costs that exclude small-scale millers from premium segments.
- Technical Limitation:Green gram powder's 15-16 percent fiber content limits application in ultra-processed foods requiring smooth mouthfeel, constraining mainstream food industry adoption.
Strategic Opportunities
- Underpenetrated Geographies:North Indian states with limited traditional mung consumption present white space for fortified flour blends and protein isolate marketing.
- EU Deforestation-Free Supply Chain Rules:Early compliance with due diligence requirements positions Indian exporters for preferential access as European buyers requalify suppliers.
- Direct-to-Consumer Channel Innovation:Subscription-based nutritional supplement models bypass traditional distribution markups and capture margin from fitness-oriented urban consumers.
Industry Challenges
- Skill Gap in Quality Assurance:Shortage of trained personnel for mycotoxin testing and allergen management slows certification timelines for mid-scale processors.
- Integration Complexity:Legacy stone milling equipment requires retrofitting for particle size consistency demanded by pharmaceutical and nutraceutical contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Gram Powder Market |
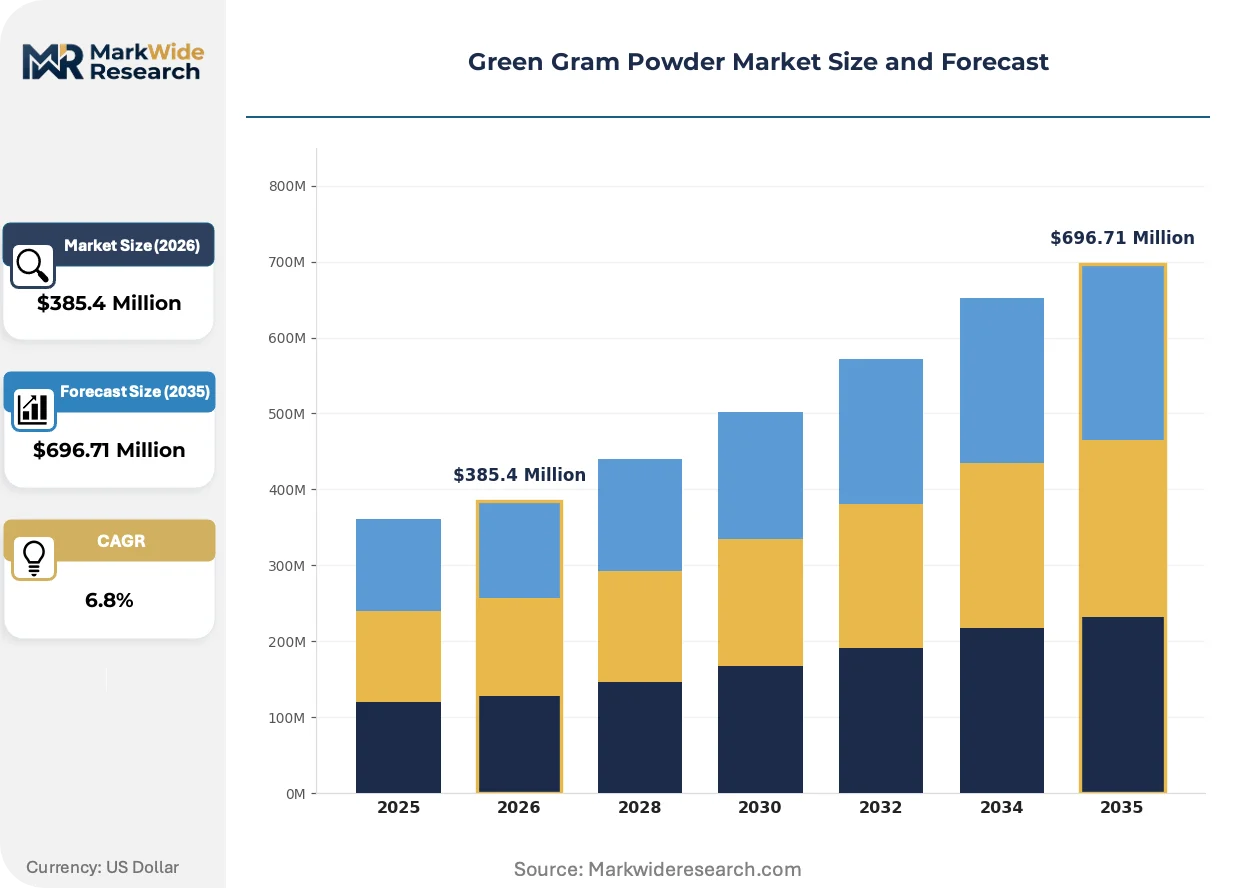
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Gluten-Free, Fortified End Use: Bakery Products, Nutritional Supplements, Snack Foods, Beverages Sales Channel: Online Retail, Supermarkets, Health Food Stores, Distributors Packaging Type: Bags, Pouches, Jars, Bulk Containers |
| Companies Covered | Tata Sampann, Oziva, Sri Tattva, Patanjali, Bob's Red Mill, Nirmal Ayurvedic Products, Kerala Naturals, Kayamantra, Neo Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Gram Powder Market Trends and Innovations
Processing technology and certification protocols are reconfiguring competitive advantage in green gram powder, separating capital-intensive integrated players from fragmented traditional millers. The market is witnessing deliberate convergence between food safety compliance and export market access engineering.
Spray-drying technology for protein isolate production is migrating from conventional drum-drying methods that degrade heat-sensitive amino acids. Nutraceutical contract manufacturers in Bangalore and Hyderabad are adopting these systems to serve European sports nutrition brands. This migration from low-capital drying to precision thermal processing is compressing the supplier base toward processors with capex capacity.
EU Regulation 2018/848 on organic production and labeling is tightening traceability requirements for imported legume ingredients. Indian exporters must now demonstrate full supply chain documentation from farm to finished powder. The regulation most affects processors serving German and Dutch buyers, who are consolidating supplier relationships toward vertically integrated operations with captive organic farms.
Clean-label formulation preferences among millennial consumers are displacing additive-laden protein fortification in bakery and snack applications. Food technologists in Mumbai and Delhi are reformulating with green gram powder as a natural emulsifier and protein source. This shift concentrates demand in metropolitan retail channels where ingredient transparency commands shelf placement premiums.
Green Gram Powder Market Segmentation
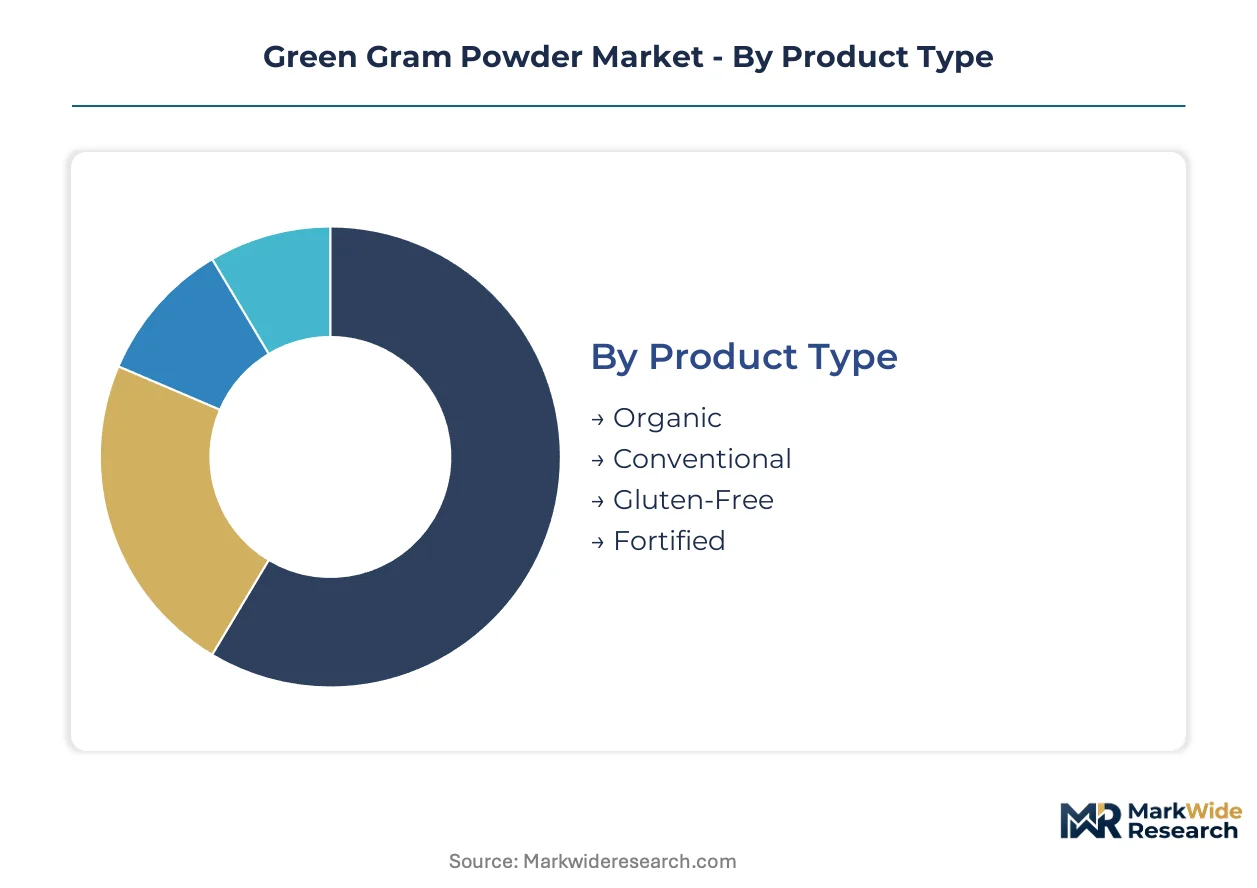
Green gram powder segmentation reveals distinct velocity profiles across product tiers, with certified organic grades commanding extended procurement cycles while conventional bulk flows through commodity channels. Understanding these turnover differentials enables processors to align working capital deployment with margin capture opportunities.
Product Type:
Certification overhead creates the widest divergence in inventory velocity, with audited organic lots moving through extended validation pipelines while conventional grades rotate rapidly through institutional procurement.
- Organic:Certification under India's NPOP with USDA NOP equivalency requires 36-month transition periods and annual audit maintenance. Export eligibility to German and Dutch buyers concentrates demand in South Indian processing clusters with captive farm networks. Margin premiums of 40-60 percent over conventional grades justify the compliance burden for integrated players.
- Conventional:Dehulled mung bean powder without certification overhead serves price-sensitive institutional buyers and mainstream food manufacturers. Volume concentrates in Maharashtra and Karnataka procurement networks supplying domestic fortification programs under FSSAI guidelines.
- Gluten-Free:Dedicated processing lines with allergen segregation protocols target celiac-safe bakery applications. Demand clusters in metropolitan Mumbai and Delhi retail channels where clean-label positioning commands shelf placement.
- Fortified:Micronutrient-enhanced grades align with India's mandatory fortification standards for school nutrition and public distribution systems. Procurement flows through government tender channels with elongated payment cycles.
Conventional grades dominate installed base volume. Organic certification is where expansion concentrates.
End Use:
Application maturity varies sharply, with traditional food systems absorbing steady volume while nutraceutical formulators drive specification intensity.
- Nutritional Supplements:Protein isolate fractions exceeding 80 percent concentration serve sports nutrition and meal-replacement formulations. Bangalore and Hyderabad contract manufacturers supply European brands demanding spray-dried amino acid preservation. This segment is climbing the fastest as fitness-oriented consumers shift from whey to legume-derived inputs.
- Bakery Products:Partial wheat replacement in gluten-free formulations leverages green gram powder's emulsification properties at 10-15 percent inclusion rates. Mumbai food technologists are reformulating traditional snack applications for clean-label positioning.
- Snack Foods:Extruded and puffed applications utilize the powder's binding characteristics in savory formats. Regional brands in Tamil Nadu and Andhra Pradesh anchor penetration in South Indian consumption strongholds.
- Beverages:Plant-based milk alternatives and protein-fortified drinks utilize soluble fractions with particle sizes below 100 microns. Processing complexity limits supplier participation to capital-intensive operations.
Bakery applications dominate installed base. Nutritional supplements are where expansion concentrates.
Sales Channel:
Channel economics separate high-touch advisory sales from velocity-driven throughput, with margin structure inversely correlated to inventory turns.
- Online Retail:Direct-to-consumer subscription models capture urban fitness demographics with protein-forward marketing. Oziva and similar brands bypass traditional distribution markups through proprietary digital platforms.
- Supermarkets:Conventional grade volume flows through modern trade chains with standardized packaging and promotional funding requirements. Patanjali leverages Ayurveda-aligned positioning for shelf space in traditional retail formats.
- Health Food Stores:Specialty retailers concentrate distribution of fortified and organic variants with trained staff providing ingredient transparency. Premium positioning supports margin capture from educated consumers.
- Distributors:Institutional and export procurement runs through established trading networks with credit terms and logistics consolidation. Bulk container shipments to European buyers require documentation compliance under EU 2018/848 traceability mandates.
Distributor channels dominate installed base. Online retail is where expansion concentrates.
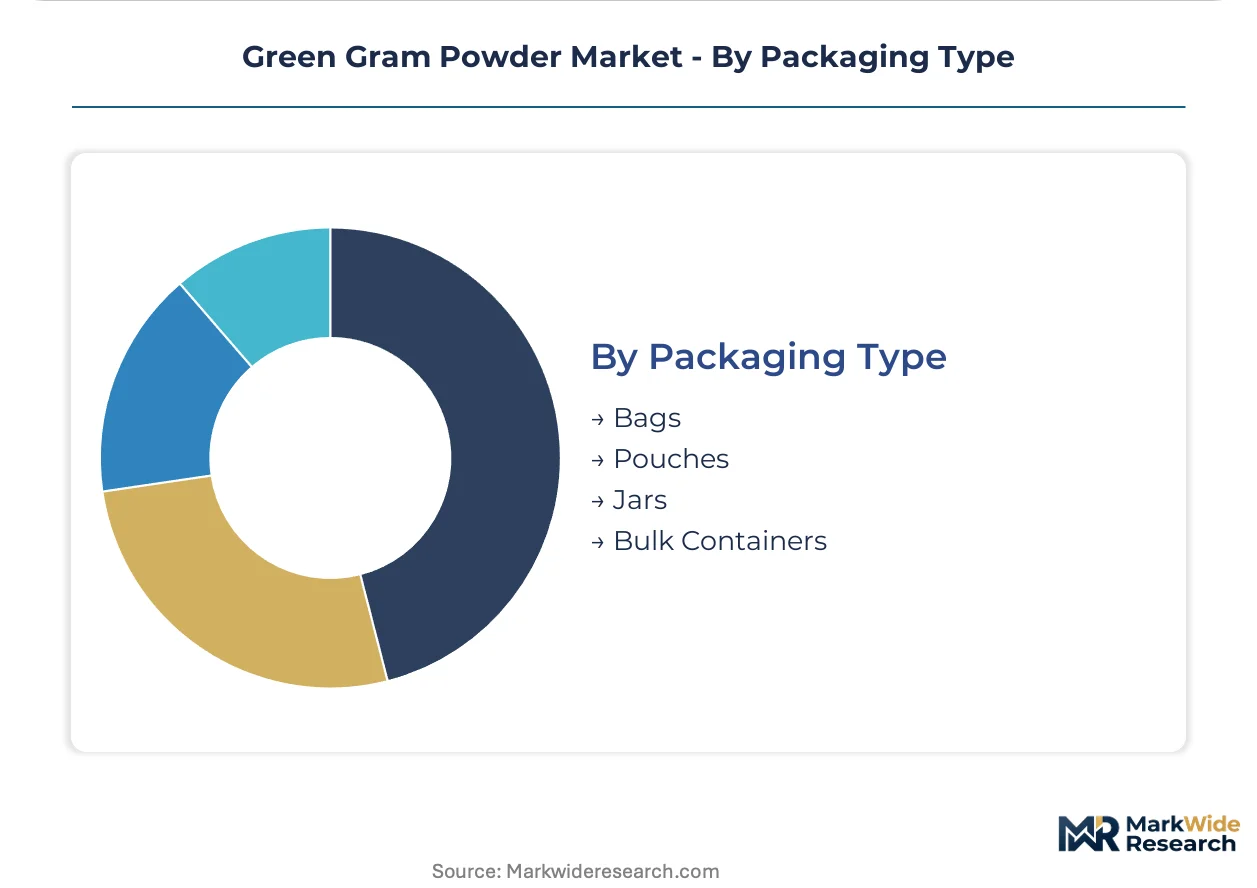
Packaging Type:
Packaging selection signals end-use sophistication, with barrier properties and convenience features scaling with value per kilogram.
- Bulk Containers:25-50 kg food-grade drums serve industrial bakery and supplement manufacturers with dedicated material handling systems. Export shipments to North American buyers utilize UN-certified containers with nitrogen flushing.
- Pouches:Resealable flexible packaging dominates retail nutritional supplement positioning with single-serve and family-size configurations. Digital printing enables brand differentiation in crowded shelf environments.
- Jars:Rigid packaging supports premium organic grades in health food stores with moisture-resistant closures and label space for certification logos. Higher unit economics justify glass or PET material selection.
- Bags:Woven polypropylene with polyethylene liners serves conventional grade institutional procurement with palletized logistics efficiency. Lowest unit cost supports price-competitive tender participation.
Bulk containers dominate installed base. Pouch formats are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export eligibility under organic certification regimes is redrawing procurement geography, with supply chain documentation requirements favoring processors in established agricultural clusters over dispersed small-scale millers.
India
FSSAI fortification mandates and PLI scheme subsidies are pulling green gram powder into institutional nutrition channels and modernized processing infrastructure. South Indian states with traditional mung consumption anchor certified organic capacity serving EU buyers under equivalency arrangements. Karnataka and Tamil Nadu processing clusters concentrate spray-drying investments for protein isolate exports.
United States
FDA dietary supplement regulations and clean-label preferences among fitness demographics are driving demand for plant-based protein inputs. USDA NOP organic certification requirements filter import eligibility toward Indian and Southeast Asian suppliers with documented supply chains. West Coast nutraceutical formulators in California and Oregon lead reformulation away from whey derivatives.
Germany
EU 2018/848 organic traceability mandates and deforestation-free supply chain due diligence are consolidating supplier relationships toward vertically integrated Indian exporters. EFSA novel food consultations shape ingredient approval timelines for mung-derived protein fractions. Hamburg and Rotterdam trading hubs concentrate documentation compliance for North European buyers.
Netherlands
Green Deal sustainability criteria and circular economy procurement standards favor legume ingredients with verified carbon footprints in food processing applications. Amsterdam and Utrecht food tech clusters pilot precision fermentation and plant-protein hybrid formulations. Dutch buyers are requalifying suppliers ahead of stricter 2025 due diligence enforcement.
United Kingdom
Post-Brexit UK organic regulation divergence from EU standards creates parallel certification overhead for exporters serving British buyers. FSA novel food guidance and allergen labeling requirements shape formulation decisions in bakery and snack applications. London-based health food retail chains concentrate distribution of premium organic grades with Ayurveda-aligned positioning.
Green Gram Powder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and certification management. The vendor base spans integrated food conglomerates with backward integration into pulse procurement, direct-to-consumer nutritional brands with proprietary digital distribution, and regional Ayurveda-aligned processors with traditional retail penetration. Three archetypes dominate: certification-heavy organic exporters, subscription-model wellness brands, and heritage-positioned traditional players. Competitive moves concentrate on M&A for captive farm networks and capacity expansion in spray-drying infrastructure.
Among India-based integrated food groups, Tata Sampann occupies a position exemplifying procurement network control across Maharashtra and Karnataka growing regions. Patanjali anchors the Ayurveda-aligned archetype with shelf-space concentration in traditional retail formats. Oziva represents the direct-to-consumer wellness brand model with protein-forward digital marketing. These three players illustrate the strategic divergence between upstream supply control, heritage positioning, and channel innovation.
| Leading Market Players |
|---|
| Tata Sampann |
| Oziva |
| Sri Tattva |
| Patanjali |
| Bob's Red Mill |
| Nirmal Ayurvedic Products |
| Kerala Naturals |
| Kayamantra |
| Neo Products |
| Others |
Pricing and Supply Chain Analysis
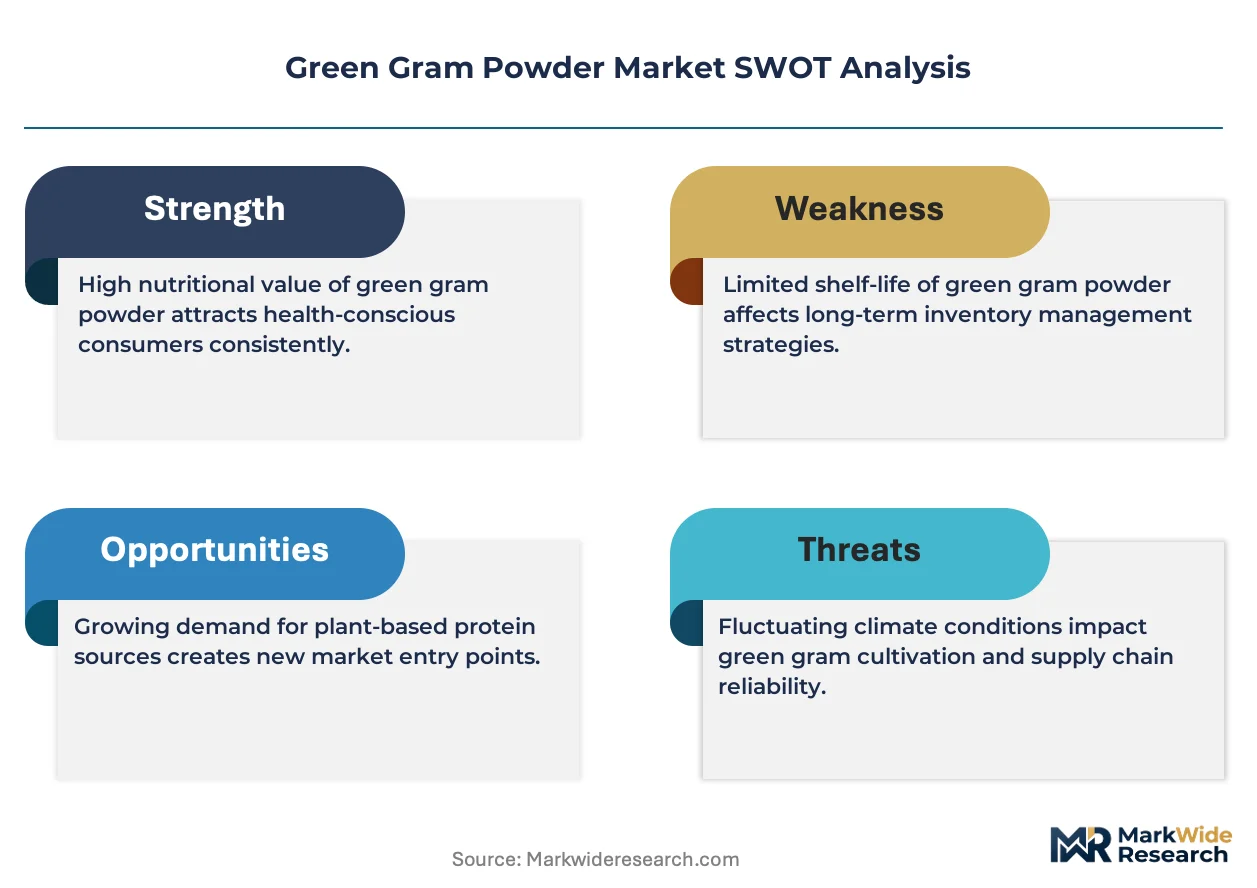
Overcapacity in conventional milling infrastructure across Maharashtra and Karnataka is compressing spot-market pricing for ungraded powder while tightening premiums for certified organic lots. This utilization divergence rewards processors who have deployed working capital into audit maintenance and traceability systems, while marginalizing asset-light millers from export eligibility.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that separates certified organic grades from conventional bulk. Price differentiation rests on NPOP certification status and particle size consistency for nutraceutical applications. Cost compression in conventional tiers is intensifying because monsoon-dependent harvest volatility transmits directly into spot-market softness. Institutional procurement teams at government nutrition programs exhibit highest price sensitivity, while European sports nutrition formulators absorb premium positioning for spray-dried isolates.
Supply Chain Analysis
Upstream mung bean cultivation draws from Maharashtra, Karnataka, and Tamil Nadu growing belts with Myanmar import volumes filling deficit periods. Raw material flows depend on monsoon timing, FSSAI procurement schedules, and EU 2018/848 traceability documentation. Single-source vulnerability concentrates in organic seed stock and certified farm networks. Distribution runs through distributor-led institutional channels for bulk grades, with direct-to-consumer platforms capturing margin in nutritional supplement positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings for small-scale millers represent a faster-expanding recurring layer than commodity powder sales, with audit maintenance and documentation compliance generating multi-year retainer relationships.
For Market Incumbents: Build captive farm network moats through long-term organic conversion contracts with Karnataka and Tamil Nadu growing cooperatives. Defensive consolidation should concentrate spray-drying capacity additions in Bangalore and Hyderabad to preempt contract manufacturer competition. FSSAI fortification mandate expansion poses substitution risk from alternate legume inputs; preemptive R&D into protein isolate fractionation preserves specification leadership.
For New Entrants and Emerging Players: Pursue white-space penetration in North Indian states where traditional mung consumption remains underdeveloped. Target direct-to-consumer subscription models for urban fitness demographics with protein-forward digital marketing. Go-to-market execution should leverage third-party organic certification services rather than capital-intensive farm integration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certification-heavy processors with multi-year European supply agreements. Long-term viability over a five-to-ten year horizon favors vertically integrated operations with demonstrated EU 2018/848 compliance. Acquisition screening should prioritize mid-scale processors with underutilized spray-drying assets. The signal to monitor is EU deforestation-free due diligence enforcement tightening, which will disqualify non-compliant suppliers and concentrate volume among documented operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farm Networks | Captive supply of NPOP-certified raw material secures export eligibility to German and Dutch buyers. |
| Spray-Drying Capacity Expansion | Precision thermal processing infrastructure serves Bangalore and Hyderabad nutraceutical contract manufacturers. |
| Direct-to-Consumer Platform Launch | Subscription models bypass traditional distribution markups and capture urban fitness demographics. |
| EU Deforestation-Free Compliance Program | Early traceability documentation positions Indian exporters for preferential access ahead of enforcement tightening. |
| Fortified Grade Development for FSSAI Channels | Micronutrient-enhanced formulations align with mandatory school nutrition procurement flows. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with organic certification auditors, pulse procurement managers at integrated food groups, spray-drying equipment vendors, and nutraceutical contract manufacturing executives. Secondary validation drew from FSSAI fortification guidelines, EU 2018/848 regulatory texts, NPOP certification databases, and Indian customs trade data for mung bean and derivative shipments. Bottom-up volume estimates from processing capacity utilization were triangulated against top-down demand segmentation by end-use application.
Calibration against historical price series and procurement volume patterns anchored projection assumptions across the analysis window. Segmentation modeling incorporated product type, end-use application, sales channel, and packaging format dimensions with regional regulatory cluster overlays. CAGRs were derived from fitted growth curves applied to segment-specific demand elasticities, with spray-drying adoption rates and organic certification penetration serving as primary forecast inputs.
Sensitivities concentrate around monsoon variability affecting raw material costs, EU due diligence enforcement timing, and FSSAI mandate expansion scope. Forecasts reflect documented assumptions on certification maintenance rates and export market access continuity. Cross-checking against Indian agricultural ministry crop estimates and European organic import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Protein Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
South America Agar Market
Ingredients
Cognitive Ingredients Market
Ingredients
Middle East and Africa Pea Starch Market
Ingredients
Cholesterol API Market
Ingredients
Lactase Enzyme Market
Ingredients
Carotenoids Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
North America Carrageenan Market
Ingredients
Honey Powder Market
Ingredients
Glucuronolactone Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Potato Flour Market
Ingredients
Borage Oil Market