
 Automatic Composter Market | 2026-2036
Automatic Composter Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Composter Market Outlook
China's manufacturing base for small appliance motors and heating elements is reconfiguring supply availability for automatic composter producers worldwide. Bokashicycle leverages its fermentation-focused design heritage to anchor niche commercial kitchen segments. FoodCycler specializes in compact countertop units for residential users across North American markets. Oklin competes through industrial-grade continuous systems that dominate high-volume food service installations.
An automatic composter is a mechanized decomposition unit that accelerates organic waste breakdown through controlled aeration, temperature management, and moisture regulation, typically processing material within 24 hours to 30 days depending on technology configuration. The device serves municipalities, commercial kitchens, and agricultural operations seeking to reduce landfill diversion costs and comply with organic waste mandates. Electric composter units command attention in residential channels where space constraints and odor control priorities shape purchasing decisions. Continuous composter systems capture margin pools in commercial establishments processing steady food waste streams. Sensor-based technology leads innovation investment as operators demand real-time fill-level monitoring and automated cycle optimization.
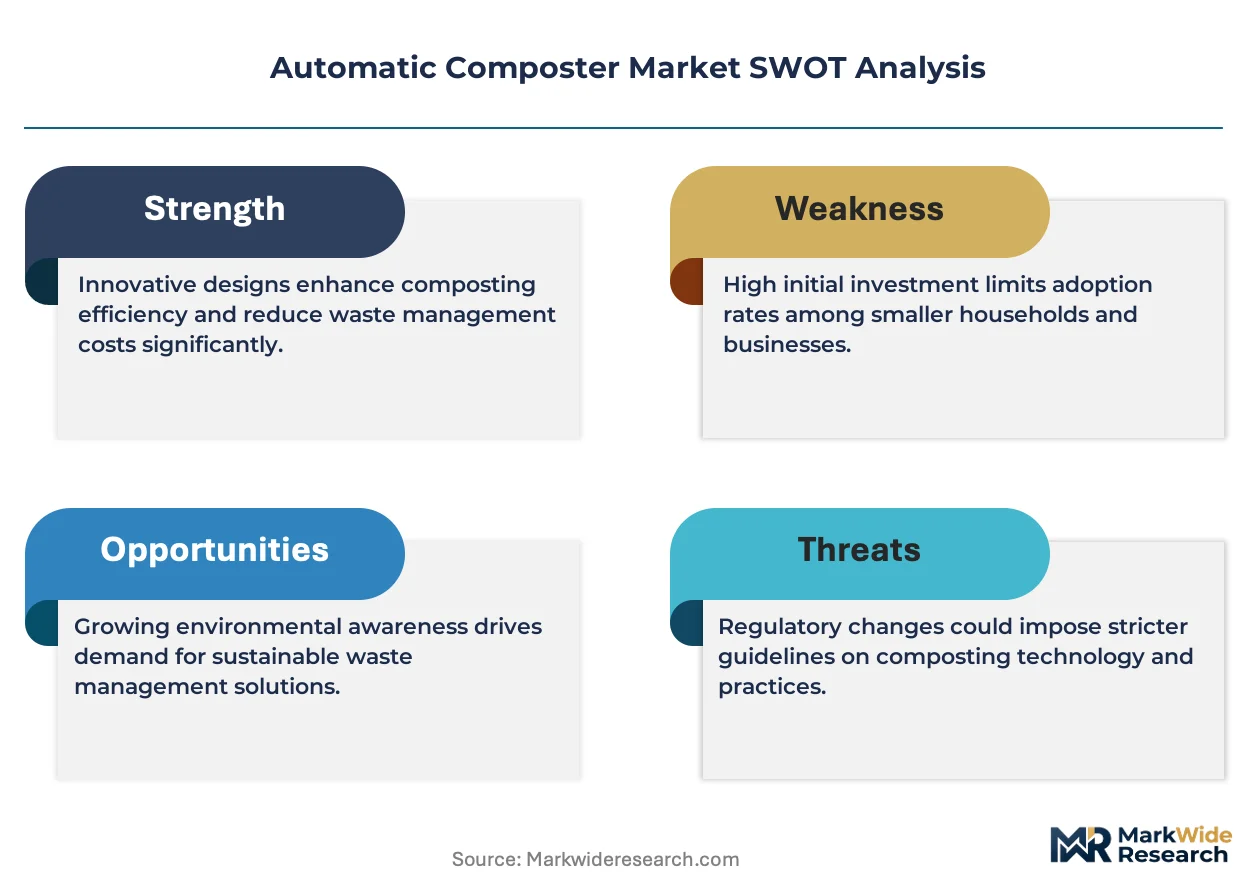
The EPA's food recovery hierarchy and state-level organic waste bans in California, Vermont, and Massachusetts shape product standards and demand pull across the United States. The EU Green Deal and F-Gas Regulation indirectly influence composter design by restricting refrigerant-dependent dehydration systems in favor of thermophilic aerobic processing. ISO 14040 life-cycle assessment frameworks guide procurement specifications for municipal buyers evaluating carbon footprint claims. Stakeholders must monitor evolving compost quality certification requirements and electricity grid carbon intensity as these factors determine total cost of ownership calculations and technology selection criteria.
Market Dynamics
Sensor-based aerobic technology is compressing cycle times from weeks to hours, forcing equipment refresh cycles in municipal and commercial installations that purchased passive drum systems within the past decade.
Growth Catalysts
- EU Green Deal organic waste mandates:Germany's national packaging ordinances and separate collection requirements are accelerating procurement of continuous processing units by municipal waste authorities.
- State-level organic waste bans:California, Vermont, and Massachusetts have enacted disposal restrictions that pull commercial kitchens and food service operators toward on-site decomposition equipment.
- Curbside program expansion:Municipalities across North America are rolling out residential organic collection, creating pull-through demand for electric countertop units in single-family housing segments.
Market Restraints
- Heating element supply concentration:China's dominance in small appliance motor manufacturing creates input availability constraints for electric composter producers during trade flow disruptions.
- Refrigerant-dependent system obsolescence:The EU F-Gas Regulation is rendering dehydration-based units structurally non-compliant, forcing write-downs of installed base and R&D redirection.
- Compost quality certification friction:Divergent national standards for pathogen reduction and maturity testing fragment procurement specifications across border markets.
Strategic Opportunities
- Agricultural operations integration:On-farm food waste processing for nutrient recovery remains underpenetrated in North American dairy and greenhouse sectors.
- IoT-enabled predictive maintenance:Convergence of fill-level sensors with cloud-based cycle optimization creates service revenue pools beyond equipment sales.
- High-volume food service:Stadiums, hospital systems, and university campuses with steady waste streams represent whitespace for industrial-grade continuous installations.
Industry Challenges
- Electromechanical technician scarcity:Maintenance of sensor arrays and aeration motors requires skills that diverge from traditional waste equipment servicing.
- Legacy infrastructure integration:Retrofitting continuous systems into existing waste handling workflows demands custom engineering for site-specific material flows.
- Carbon accounting verification:Electricity grid intensity variation complicates life-cycle footprint claims under ISO 14040 frameworks.
Report Scope
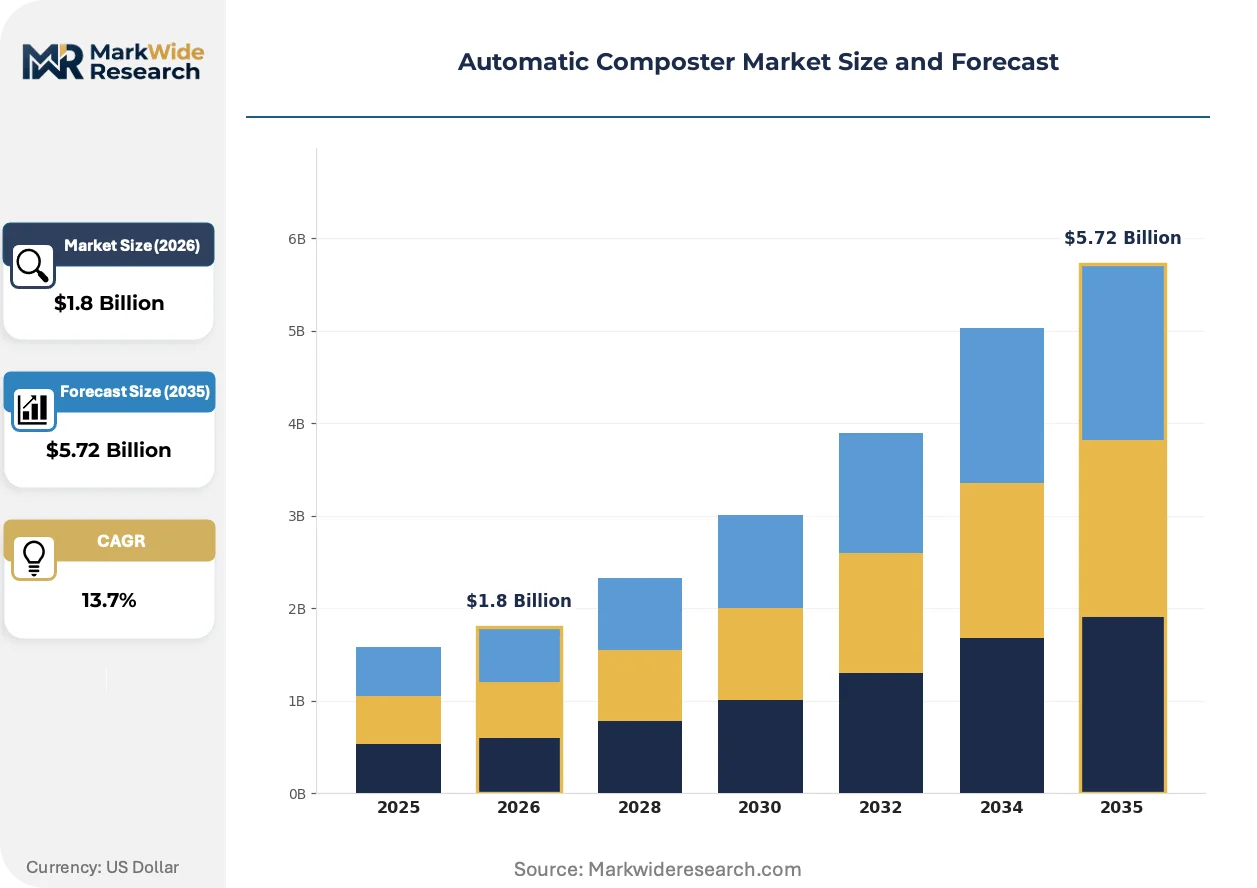
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Composter Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Composter, Continuous Composter, Tumble Composter, Electric Composter End User: Residential Users, Commercial Establishments, Agricultural Sector, Municipalities Material Type: Food Waste, Yard Waste, Agricultural Residues, Organic Waste Technology: Sensor-Based, Aerobic, Anaerobic, Thermophilic |
| Companies Covered | Bokashicycle, FoodCycler, Oklin, Whirlpool Corporation, Emerson Electric Co, Komposta, Green Planet, NatureMill, Tidy Planet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Composter Market Strategic Shifts
Thermophilic aerobic processing is overtaking passive decomposition as the dominant technical architecture, with real-time monitoring systems now standard in commercial-tier equipment.
Thermophilic aerobic reactors maintain temperatures between 55°C and 65°C to accelerate microbial activity and achieve pathogen reduction without external energy-intensive drying. Municipal buyers in Germany and the Netherlands are specifying these systems for curbside collection hubs. This thermal approach is rendering obsolete refrigerant-dependent dehydration units that dominated early commercial installations.
The EPA's food recovery hierarchy has cascaded into state procurement guidelines that prioritize source reduction and on-site processing over centralized composting facilities. Equipment specifications now embed diversion rate verification requirements. California's Department of Resources Recycling and Recovery has tightened enforcement timelines, compressing vendor qualification cycles for public sector contracts.
Food service operators are unbundling equipment purchase from maintenance contracts, shifting toward performance-based arrangements where vendors guarantee throughput and output quality metrics. This restructuring transfers operational risk from kitchen staff to equipment suppliers. The model is most visible in North American contract food service management companies operating across multiple institutional sites.
Automatic Composter Market Segmentation
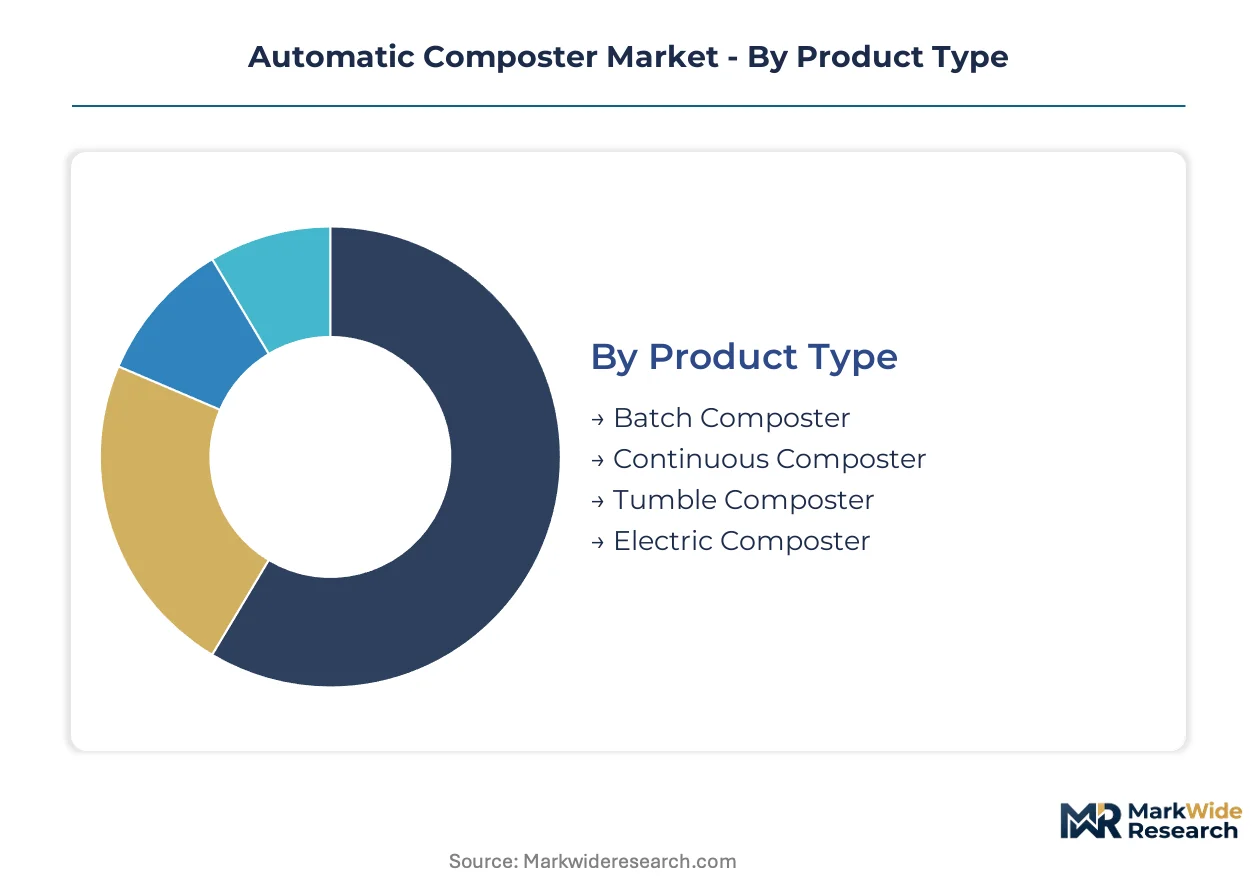
Automatic composter procurement diverges sharply across use-case contexts, with municipal buyers prioritizing throughput volume while residential purchasers emphasize footprint and odor containment. Technology selection, material compatibility, and end-user operational capacity create distinct product-positioning requirements that vendors must navigate.
Product Type:
Product architecture determines processing cadence, labor intensity, and energy requirements across the use-case spectrum from household kitchens to industrial food service.
- Continuous Composter:These systems process waste through automated feed mechanisms that maintain constant microbial activity without batch cycling. High-volume food service installations in Germany and the Netherlands specify these units for steady organic streams under EU Green Deal procurement guidelines.
- Electric Composter:Compact countertop units integrate heating elements and aeration motors to accelerate decomposition within 24 hours. North American single-family housing segments favor these for space-constrained kitchens where curbside collection remains unavailable.
- Batch Composter:Discrete chamber systems process fixed waste loads through complete decomposition cycles before unloading.
- Tumble Composter:Rotating drum designs rely on manual or motorized turning to aerate material without powered heating elements.
The dominant share belongs to Continuous Composter systems in commercial procurement, while Electric Composter units are gaining share fastest in residential channels.
End User:
Customer operational scale shapes equipment specifications from countertop footprint limits to tonnage throughput requirements.
- Commercial Establishments:Restaurants, hotels, and institutional food service operators require continuous processing capacity with minimal staff intervention. California's organic waste ban enforcement has accelerated equipment procurement by contract food service management companies operating across hospital and university campus networks.
- Municipalities:Waste authorities procure industrial-grade systems for curbside collection hubs and centralized processing facilities. German packaging ordinance compliance deadlines have compressed vendor qualification timelines for public sector contracts.
- Residential Users:Individual households prioritize odor control, noise reduction, and countertop footprint over processing speed.
- Agricultural Sector:Dairy operations and greenhouse facilities seek nutrient recovery from on-farm organic waste streams.
Commercial Establishments command the largest equipment value per installation, though Municipalities are expanding procurement volume most aggressively.
Material Type:
Feedstock composition determines moisture management requirements, carbon-to-nitrogen ratios, and preprocessing needs.
- Food Waste:High-moisture organic material including pre-consumer scraps and post-consumer leftovers demands aeration systems that prevent anaerobic conditions. Massachusetts disposal restrictions have pulled commercial kitchens toward on-site processing of this stream.
- Yard Waste:Carbon-heavy material including leaves, grass clippings, and woody debris requires extended processing cycles or supplemental nitrogen sources.
- Agricultural Residues:Crop byproducts and livestock bedding materials present scale and contamination challenges for standard equipment configurations.
- Organic Waste:Mixed municipal streams combining food, paper, and compostable packaging demand flexible system designs with contamination tolerance.
Food Waste processing dominates commercial equipment specifications, while Yard Waste applications are climbing fastest in suburban municipal programs.
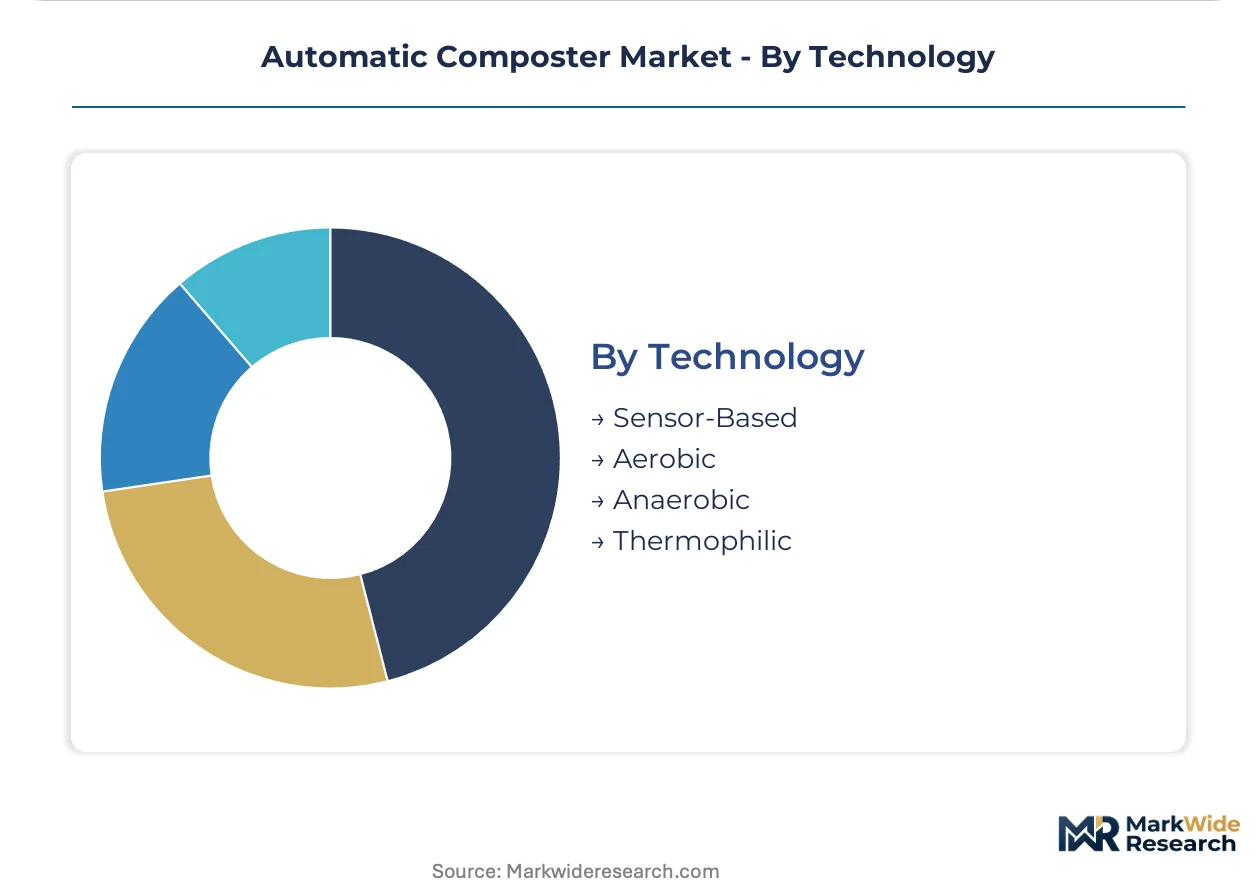
Technology:
Decomposition methodology determines cycle duration, energy consumption, and pathogen reduction certification eligibility.
- Sensor-Based:IoT-enabled systems monitor fill levels, temperature, and moisture in real time to automate aeration and heating cycles. These units are displacing passive drum installations in European municipal procurement under ISO 14040 life-cycle assessment frameworks.
- Thermophilic:High-temperature aerobic processing maintains 55°C to 65°C to accelerate microbial activity and achieve pathogen reduction without refrigerant-dependent dehydration. The EU F-Gas Regulation has rendered thermophilic systems structurally compliant where dehydration units face obsolescence.
- Aerobic:Oxygen-dependent decomposition through forced aeration or mechanical turning without precise temperature control.
- Anaerobic:Oxygen-excluded digestion producing biogas alongside compost output, requiring sealed vessel construction.
Sensor-Based technology leads municipal and commercial procurement, with Thermophilic systems showing the steepest expansion trajectory as refrigerant regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys continuous processing systems for municipal curbside hubs, while the United States splits demand between electric countertop units in residential channels and industrial-grade installations for commercial food service.
Germany
Municipal waste authorities procure thermophilic aerobic systems for centralized organic processing under national packaging ordinance deadlines. The EU Green Deal mandates separate collection streams by 2025, compressing vendor qualification timelines. Bavaria and North Rhine-Westphalia host the densest concentration of curbside collection hub deployments.
United States
California, Vermont, and Massachusetts enforce organic waste bans that pull commercial kitchens toward on-site decomposition equipment. The EPA's food recovery hierarchy shapes state procurement guidelines prioritizing source reduction. Contract food service management companies across hospital and university campus networks in California represent the fastest-expanding commercial installation base.
Netherlands
Waste authorities specify sensor-based systems with real-time fill-level monitoring for urban curbside collection points. ISO 14040 life-cycle assessment frameworks guide municipal procurement specifications evaluating carbon footprint claims. The Randstad metropolitan cluster leads deployment density for continuous processing installations serving mixed organic streams.
Canada
Municipalities in Ontario and British Columbia expand residential organic collection programs, creating pull-through demand for electric countertop units where curbside service remains unavailable. Health Canada and PMRA guidelines influence pathogen reduction certification requirements for output quality. The Greater Toronto Area exhibits the steepest procurement growth for commercial-grade continuous systems in institutional food service.
China
Manufacturing concentration for small appliance motors and heating elements reconfigures supply availability for electric composter producers worldwide. The country's dual carbon goals and MEE regulations indirectly shape export-oriented production standards. Yangtze River Delta industrial clusters supply thermal management components to equipment assemblers across North American and European markets.
Automatic Composter Market Competitive Environment
Capability concentration sits with fermentation-focused design specialists; scale advantage sits with diversified appliance manufacturers possessing captive distribution networks. The vendor base spans three tiers: industrial-grade continuous system fabricators, compact residential unit specialists, and diversified home appliance conglomerates with white-label capacity. Strategic moves center on backward integration into thermal component supply and technology licensing arrangements for sensor-software stacks.
Within the fermentation-design tier, Bokashicycle anchors niche commercial kitchen positioning through anaerobic pre-processing heritage. FoodCycler exemplifies the compact residential specialist archetype with countertop footprint optimization for North American single-family housing. Oklin occupies a position among industrial-grade continuous system providers targeting high-volume food service installations. Whirlpool Corporation and Emerson Electric Co represent diversified appliance conglomerates with manufacturing scale and existing channel relationships in residential markets.
| Leading Market Players |
|---|
| Bokashicycle |
| FoodCycler |
| Oklin |
| Whirlpool Corporation |
| Emerson Electric Co |
| Komposta |
| Green Planet |
| NatureMill |
| Tidy Planet |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing clusters anchor thermal component supply for electric composter producers, with capacity utilization swings in Jiangsu and Zhejiang provinces directly transmitting into downstream pricing power for North American and European equipment assemblers. This geographic concentration creates asymmetric bargaining dynamics where component shortages in China immediately compress margins for countertop unit specialists while continuous system fabricators with captive heating element inventories maintain pricing stability.
Pricing Analysis
North American residential channels command 40-60% premiums over European municipal procurement for equivalent electric countertop units, driven by freight costs and after-sales service bundling. Three-tier pricing structure across premium sensor-enabled, standard thermophilic, and economy passive drum configurations dominates commercial segments. Cost compression in economy tiers intensifies because Chinese motor suppliers are prioritizing industrial automation contracts over small appliance orders. Residential users in single-family housing exhibit highest price sensitivity, while German waste authorities under EU Green Deal deadlines show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Heating element feedstock draws from nickel-chromium alloy production concentrated in China, South Korea, and Japan, with rare earth magnet dependencies for aeration motors tethered to Chinese processing facilities. Stainless steel vessel fabrication rests on Indonesian nickel and Australian iron ore inputs. Single-source vulnerability concentrates in Guangdong Province for IoT sensor modules. Distribution runs through contract food service management companies for commercial installations, while residential channels rely on big-box retail and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic composter market is approaching a platform-economics inflection where sensor-software stacks from industrial-grade vendors achieve interoperability with municipal waste management systems, creating ecosystem lock-in effects that reshape competitive boundaries.
For Market Incumbents: Insulate core continuous system margins through backward integration into thermophilic reactor vessel fabrication, neutralizing stainless steel cost volatility from Indonesian nickel supply. Secure ISO 14040 certification pre-qualification status with German and Dutch municipal buyers before EU Green Deal deadlines compress vendor pools. Counter emerging compact residential specialists by licensing sensor-software stacks to appliance conglomerates with existing North American retail distribution.
For New Entrants and Emerging Players: Agricultural operations in North American dairy and greenhouse sectors represent the most penetrable entry point, with nutrient recovery value propositions underserved by incumbent fermentation-design specialists. Stadium and hospital campus networks in California offer whitespace for performance-based service contracts where operational risk transfers create sticky revenue streams. Pursue equipment-as-a-service go-to-market positioning to bypass capital expenditure barriers among mid-volume food service operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance conglomerates with dormant composter product lines and captive thermal component supply but lacking municipal channel relationships. Long-term viability hinges on sensor-data monetization capabilities rather than hardware shipment volumes. Watch for inflection signals in electricity grid carbon intensity reporting requirements, as jurisdictions adopting stringent ISO 14040 enforcement will accelerate thermophilic system replacement of refrigerant-dependent installed base.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Platform Integration | IoT-enabled fill-level monitoring creates recurring service revenue beyond equipment sales for FoodCycler and Oklin. |
| Backward Integration into Thermal Components | Captive heating element production insulates margin from Yangtze River Delta supply disruptions affecting Whirlpool. |
| Performance-Based Service Contracts | Risk transfer models align vendor incentives with Massachusetts and California organic waste ban compliance outcomes. |
| EU Green Deal Certification Pre-Qualification | ISO 14040 framework compliance secures vendor status for German packaging ordinance procurement deadlines. |
| Agricultural Sector Partnership | Nutrient recovery integration penetrates underdeveloped dairy and greenhouse segments in Ontario and British Columbia. |
Study Parameters
Cross-validation between primary interviews with municipal waste authority procurement directors, commercial kitchen operations managers, and agricultural facility engineers anchors the qualitative findings against secondary validation from EPA food recovery hierarchy documentation, EU Green Deal implementation reports, and ISO 14040 life-cycle assessment frameworks. Customs data on small appliance motor trade flows and SEC filings from diversified appliance manufacturers provide supply-side calibration. Bottom-up equipment shipment estimates from identified vendor production facilities triangulate against top-down organic waste mandate-driven demand projections across the analysis window.
Calibration against historical enforcement timelines for California, Vermont, and Massachusetts organic waste bans refines adoption curve assumptions throughout the forecast period. Segmentation dimensions modeled include product architecture, end-user operational scale, feedstock material composition, and technology decomposition methodology. CAGRs derive from regression analysis of procurement volume against regulatory milestone dates, with carbon accounting verification requirements and electricity grid intensity variations incorporated as scenario-weighted inputs.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity prices, Chinese export tariff regimes, or EU F-Gas Regulation enforcement intensity would shift the trajectory. Forecasts embed assumptions around municipal budget continuity and curbside program expansion timelines. Cross-checking against state-level organic waste ban compliance rate reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Electric Pruning Shears Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Rotavator Market