
 Automated Pest Monitoring System Market | 2026-2036
Automated Pest Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Pest Monitoring System Market Analysis
China's Yangtze River Delta manufacturing cluster is reshaping sensor cost curves for automated pest monitoring hardware. Syngenta AG leverages its crop science heritage to anchor integrated pest management platforms that bundle monitoring with intervention protocols. BASF SE competes through precision agriculture R&D intensity, while Rentokil Initial plc extends its service-network density into digital monitoring subscriptions across European food processing clients.
An automated pest monitoring system combines electromechanical traps, multispectral imaging sensors, and edge-computing nodes to detect, classify, and quantify pest populations in real time, typically operating at detection thresholds below five insects per trap per day for early intervention triggering. Its primary commercial purpose is to replace calendar-based pesticide applications with condition-triggered responses, cutting chemical input volumes while preserving yield. IoT-enabled sensor networks dominate hardware shipment volumes, yet cloud-based analytics layers capture disproportionate margin pools through recurring software licensing. AI-driven image recognition for species classification represents the fastest-expanding technology segment, while wireless connectivity infrastructure remains a mature, cost-commoditized enabler.
The EPA regulates pesticide application thresholds that automated systems must document for compliance, while the EU Green Deal's pesticide reduction targets create mandatory demand for verified non-chemical monitoring across member state agricultural operations. ISO 17025 accreditation requirements for pest monitoring data used in export certification shape product design priorities for traceability and audit trails. Stakeholders must weigh hardware margin compression against software retention economics when allocating capital between sensor manufacturing and predictive analytics development.
Market Dynamics
Pesticide reduction mandates under the EU Green Deal's Farm to Fork strategy are compressing calendar-based spraying schedules into condition-triggered interventions, forcing agricultural operations to document pest thresholds through verified sensor networks rather than visual scouting.
Growth Catalysts
- EU Green Deal pesticide mandates:The Farm to Fork strategy's reduction targets create mandatory demand for verified non-chemical monitoring across member state agricultural operations, eliminating calendar-based application exemptions.
- Precision agriculture adoption:Large-scale farming cooperatives in Germany's Rhine-Ruhr agtech corridor are accelerating hardware deployment to meet sustainability certification requirements for export markets.
- Edge-computing node proliferation:Real-time classification at the trap level enables sub-five-insect-per-day detection thresholds that trigger intervention before population explosions.
Market Restraints
- Sensor cost volatility:Multispectral imaging component prices fluctuate with semiconductor foundry capacity allocation, compressing hardware margins for trap manufacturers.
- Supply concentration risk:Electromechanical trap assembly clusters in China's Yangtze River Delta create single-point vulnerability for European and North American system integrators.
- Wireless connectivity commoditization:Mature LoRaWAN and cellular module markets eliminate differentiation, forcing vendors toward software layers for margin retention.
Strategic Opportunities
- Underpenetrated food processing segment:European food processing facilities lack digitized pest monitoring despite strict HACCP documentation requirements, creating subscription revenue potential for service-network extensions.
- AI-driven species classification convergence:Machine vision algorithms trained on regional pest libraries enable automated identification that reduces entomologist review labor.
- ISO 17025 accreditation tailwind:Export certification requirements for traceable monitoring data shape product design toward audit-trail architectures that command premium positioning.
Industry Challenges
- Entomology-AI hybrid skill scarcity:System deployment requires personnel who combine insect taxonomy expertise with sensor network configuration, a combination rarely found in agricultural extension services.
- Legacy farm management software integration:Proprietary data formats from established agronomy platforms resist API connectivity, forcing costly middleware development for unified dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Pest Monitoring System Market |
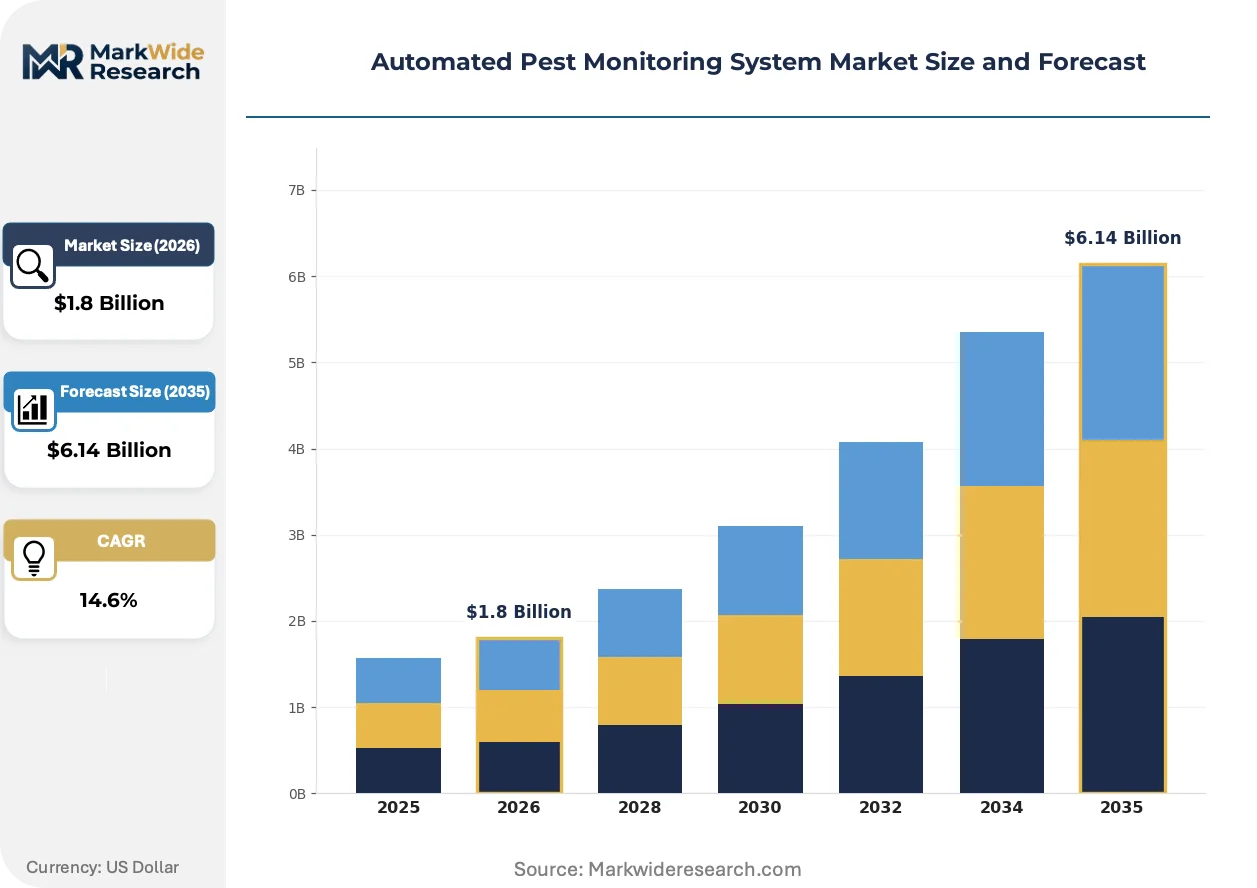
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traps, Sensors, Cameras, Software Application: Agriculture, Horticulture, Livestock, Greenhouses Technology: IoT, AI, Wireless, Cloud-Based End User: Farmers, Agronomists, Research Institutions, Pest Control Companies |
| Companies Covered | Syngenta AG, Anticimex, BASF SE, Cargill, Incorporated, Rentokil Initial plc, Terminix Global Holdings, Inc., Ecolab Inc., Russell IPM Ltd, EFOS d.o.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Pest Monitoring System Market Emerging Trajectories
Cloud-based analytics layers are capturing margin pools that hardware manufacturers surrender, while AI classification engines compress the timeline between detection and intervention decision-making.
Multispectral imaging sensors are collapsing the cost curve for species-level pest identification. Germany's precision agriculture cooperatives deploy these sensors at density levels impossible five years prior. The technology is collapsing the distinction between research-grade entomological surveys and operational farm monitoring, enabling daily population tracking that replaces weekly manual trap checks.
REACH chemical authorization restrictions are tightening permissible pesticide actives, forcing documented justification for every application. The EU Green Deal's pesticide reduction targets require verified non-chemical monitoring data for compliance. Specialty crop operations in Spain and Italy face the steepest adaptation curves as their spray-intensive horticulture models confront audit requirements.
Subscription-based monitoring services are displacing capital-intensive hardware purchases among mid-scale farming operations. European food processing clients now procure pest monitoring as bundled facility management rather than standalone equipment. This shift concentrates vendor relationships with service-network incumbents who can guarantee response-time SLAs across national territories.
Automated Pest Monitoring System Market Segmentation
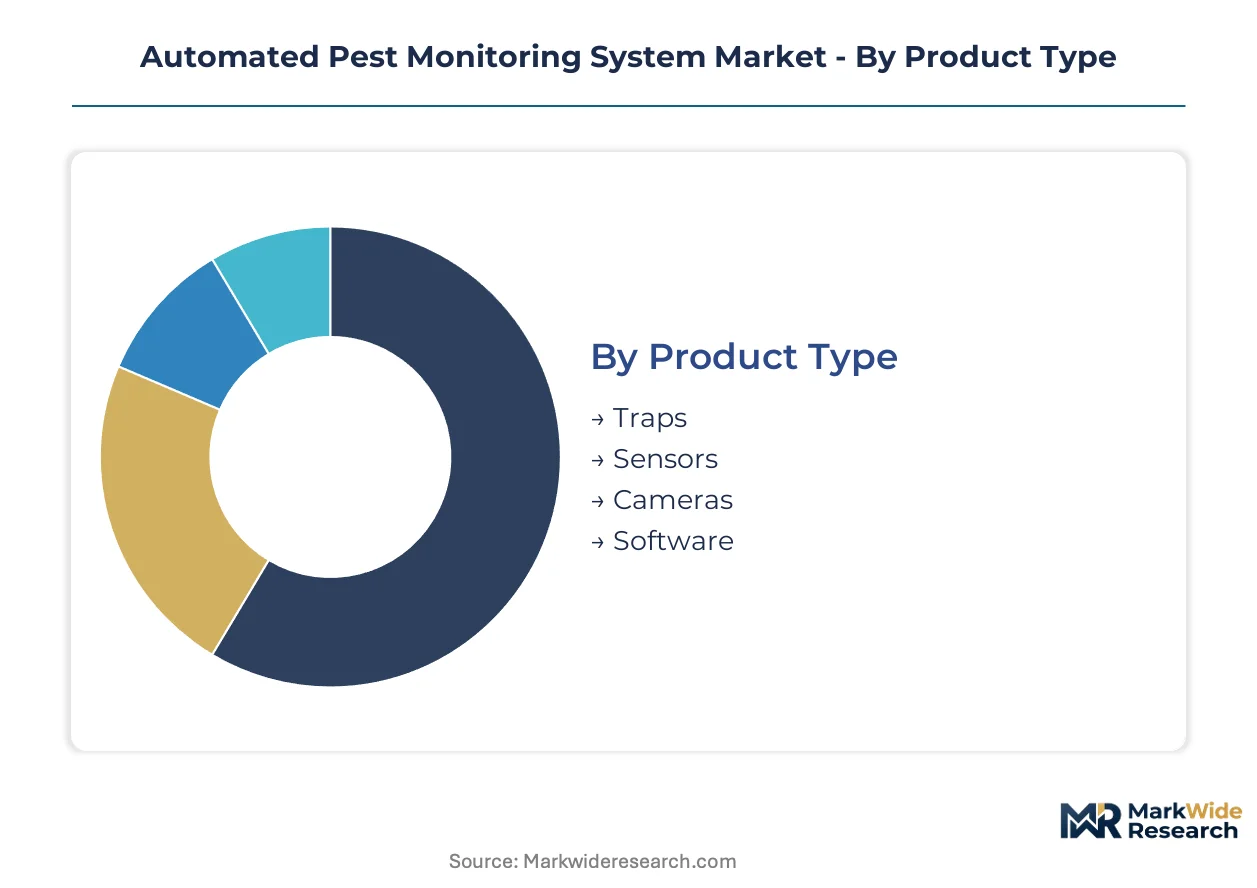
Segmentation in automated pest monitoring reveals how hardware commoditization and software retention economics split vendor strategies. Each dimension exposes different margin pools and integration complexities for system deployers.
Product Type:
After-sales-service intensity varies dramatically across product categories, with electromechanical traps demanding field calibration while software layers monetize through remote updates alone.
- Sensors:Multispectral imaging units integrate edge-computing capability for real-time classification at the trap level. Germany's Rhine-Ruhr agtech corridor deploys these at density levels impossible five years prior, driven by EU Green Deal documentation mandates that eliminate calendar-based spraying exemptions.
- Software:Cloud-based analytics platforms capture recurring licensing revenue through predictive population modeling and intervention timing algorithms. Large-scale farming cooperatives in export-dependent regions prioritize ISO 17025-accredited audit trail architectures that command premium positioning.
- Traps:Electromechanical capture devices with pheromone lures remain the volume foundation, though margin compression from Yangtze River Delta assembly concentration forces vendors toward bundled service contracts.
- Cameras:Machine vision hardware enables species-level identification that reduces entomologist review labor, with AI training on regional pest libraries improving accuracy for localized pest complexes.
By volume, Traps leads. By growth pace, Software is ahead.
Application:
Cost tier stratification separates capital-intensive broad-acre deployment from subscription-friendly protected cultivation environments.
- Agriculture:Row-crop operations span thousands of hectares requiring cellular-connected sensor grids with multi-year amortization horizons. The EPA's pesticide application documentation requirements drive adoption among US Midwest corn-soy rotations seeking compliance automation.
- Horticulture:Specialty crop operations in Spain and Italy face the steepest adaptation curves as spray-intensive models confront REACH chemical authorization restrictions and audit requirements for every application.
- Greenhouses:Controlled-environment agriculture concentrates pest pressure and enables dense sensor networks with wired power infrastructure, reducing wireless connectivity commoditization pressures.
- Livestock:Feed storage and animal housing applications prioritize rodent and fly monitoring with different detection thresholds than crop-focused systems, creating distinct hardware specifications.
Agriculture dominates absolute deployment volume. Horticulture climbs the fastest as regulatory compression forces documentation upgrades.
Technology:
Technology maturity curves determine whether vendors compete on specification or integration capability.
- AI:Image recognition engines for species classification represent the steepest expansion trajectory, with training data scarcity for regional pest biotypes creating differentiation barriers.
- IoT:Sensor network hardware dominates shipment volumes but surrenders margin to analytics layers, with LoRaWAN and cellular module markets fully commoditized.
- Cloud-Based:Centralized data architectures enable cross-farm population modeling and predictive intervention timing that edge-only systems cannot match.
- Wireless:Connectivity infrastructure remains a mature cost-commoditized enabler, forcing differentiation toward software stack depth.
IoT leads by installed base. AI gains share fastest through labor substitution in entomology review workflows.
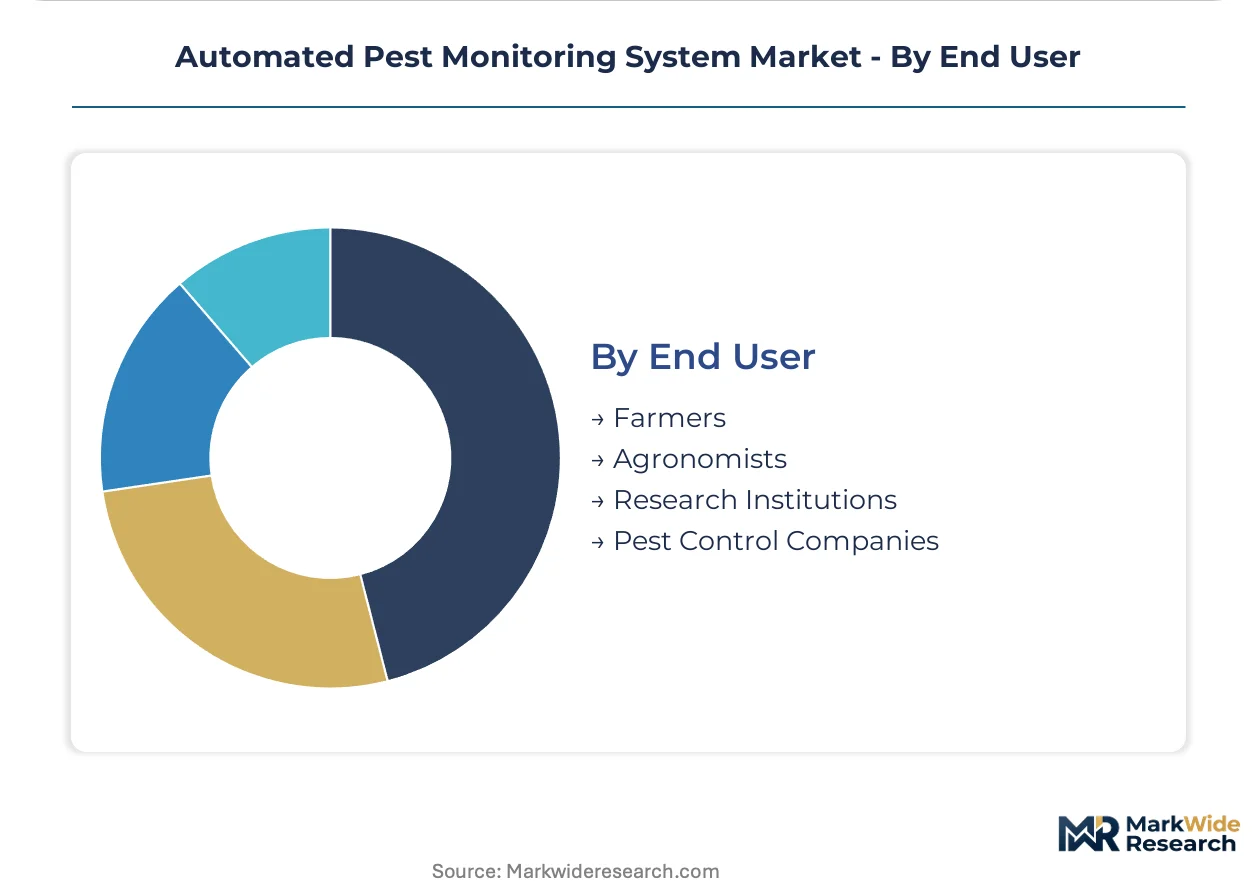
End User:
Customer type dictates procurement modality, from capital purchase to managed service subscription.
- Farmers:Owner-operators prioritize payback period visibility and integration with existing farm management software, facing legacy platform API resistance that forces costly middleware development.
- Pest Control Companies:Service-network incumbents like Rentokil Initial extend digital monitoring subscriptions across European food processing clients, guaranteeing response-time SLAs that equipment vendors cannot match.
- Agronomists:Crop consultants leverage monitoring data for prescription services, requiring dashboard export capabilities that feed into recommendation engines.
- Research Institutions:Academic and government entomology programs drive algorithm training data generation and validation studies for commercial AI classification accuracy claims.
Farmers represent the largest addressable population. Pest Control Companies expand most quickly through service-model conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA pesticide documentation mandates anchor United States demand, while EU Green Deal reduction targets reshape European procurement patterns. China's Yangtze River Delta manufacturing clusters supply sensor hardware at compressed cost curves. Brazil's expanding precision agriculture sector and India's horticulture modernization complete the geographic demand matrix.
United States
Midwest corn-soy rotations drive adoption to automate EPA compliance documentation for pesticide applications. The Farm Bill conservation programs incentivize precision agriculture investments that reduce chemical inputs. California's Central Valley specialty crop operations deploy dense sensor networks to meet export market traceability requirements.
Germany
Rhine-Ruhr agtech corridor cooperatives accelerate hardware deployment for sustainability certification compliance. REACH chemical authorization restrictions tighten permissible pesticide actives, forcing documented justification for every application. Bavaria's precision farming clusters integrate monitoring systems with farm management software platforms.
China
Yangtze River Delta manufacturing concentration reshapes global sensor cost curves for multispectral imaging hardware. The Ministry of Ecology and Environment's dual carbon goals pressure agricultural regions toward input reduction technologies. Jiangsu Province electromechanical assembly clusters supply trap components to European and North American system integrators.
Brazil
Cerrado and Mato Grosso broad-acre operations adopt cellular-connected sensor grids for soybean pest management at scale. ANVISA pesticide registration requirements increasingly demand integrated monitoring data for chemical authorization renewals. São Paulo state's agribusiness conglomerates pilot subscription-based monitoring services to reduce capital deployment.
India
Maharashtra and Karnataka horticulture belts confront export market ISO 17025 accreditation requirements for pesticide residue documentation. The PLI scheme for precision agriculture equipment subsidizes domestic sensor assembly capacity. Gujarat's specialty crop operations face steepest adaptation curves as EU-bound produce confronts audit requirements.
Automated Pest Monitoring System Market Vendor Landscape
Crop science conglomerates and facility service networks split the market into distinct capability orbits. The vendor base organizes around three strategic archetypes: integrated pest management platform bundlers, precision agriculture R&D specialists, and service-network incumbents extending digital subscriptions. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion through acquisition of regional monitoring service providers.
Among Swiss and German agrochemical heritage players, Syngenta AG and BASF SE occupy positions as integrated platform bundlers that combine monitoring hardware with intervention protocols. Rentokil Initial plc anchors the service-network archetype, extending facility management relationships into digital monitoring subscriptions. These three exemplify how crop science legacy and service infrastructure density respectively command differentiated margin pools in a market where hardware commoditization pressures intensify.
| Leading Market Players |
|---|
| Syngenta AG |
| Anticimex |
| BASF SE |
| Cargill, Incorporated |
| Rentokil Initial plc |
| Terminix Global Holdings, Inc. |
| Ecolab Inc. |
| Russell IPM Ltd |
| EFOS d.o.o. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta sensor foundries is compressing multispectral imaging component prices, forcing European system integrators to absorb margin erosion while repositioning around software retention economics and ISO 17025 certification premiums.
Pricing Analysis
Geographic price spreads between German Rhine-Ruhr precision agriculture deployments and Indian horticulture belt installations exceed three-to-one, driven by certification-grade differentiation and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited audit-trail architectures from basic sensor hardware. Cost compression in electromechanical trap assembly is intensifying because Yangtze River Delta manufacturing concentration eliminates regional labor arbitrage. Mid-scale farming cooperatives exhibit highest price sensitivity, while export-dependent large-scale operations prioritize compliance-grade premiums.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for electromechanical trap assemblers sourcing pheromone lure substrates. Manufacturing gravity centers on Jiangsu Province for sensor components, Germany's Rhine-Ruhr corridor for system integration, and India's Maharashtra belt for domestic horticulture hardware. Component dependencies include semiconductor foundry capacity for edge-computing nodes, rare-earth magnets for trap mechanisms, and specialized optical glass for multispectral lenses. Single-source vulnerability concentrates in Yangtze River Delta electromechanical assembly. Distribution runs through agronomy service networks for farmer-facing sales and direct facility management contracts for food processing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
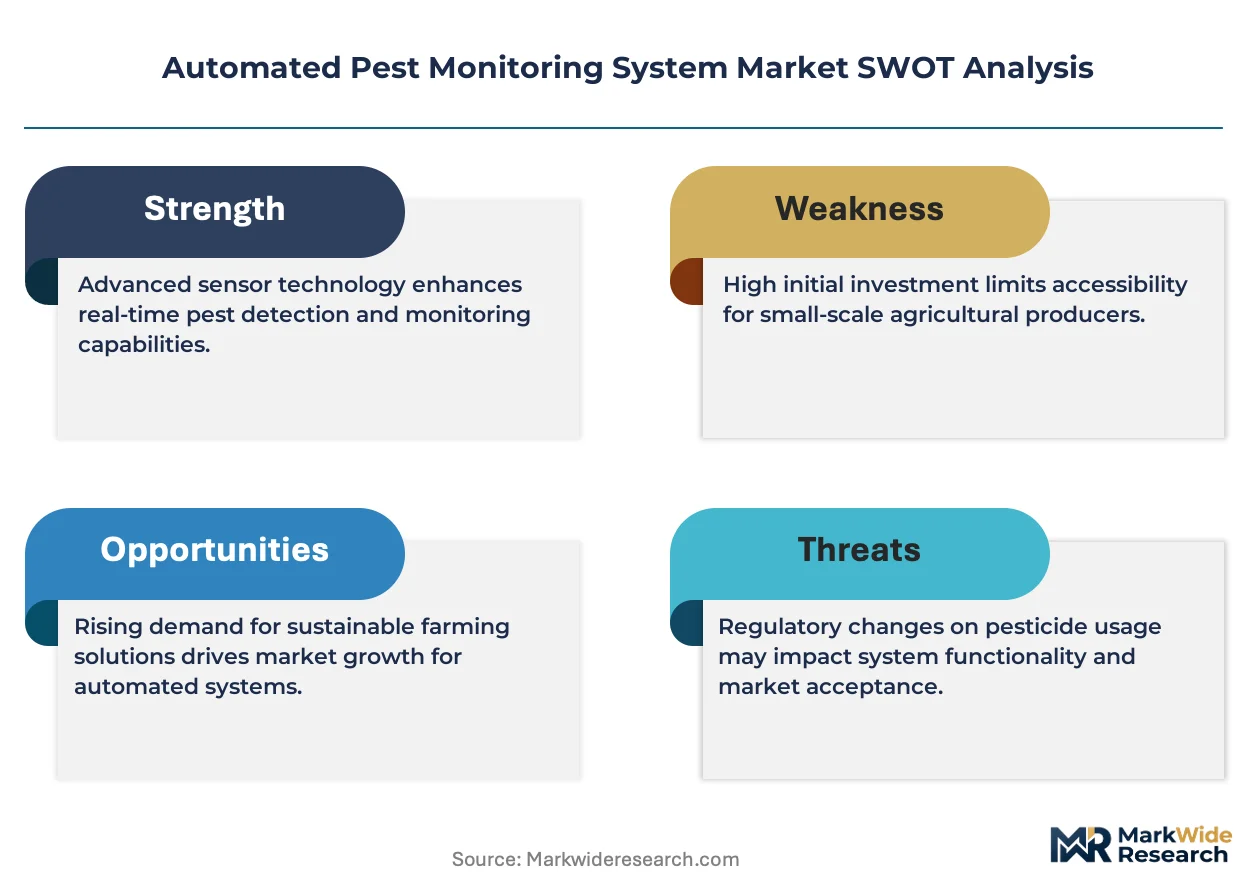
This market's defensive moat rests on regulatory entrenchment: EU Green Deal pesticide reduction mandates create mandatory demand that locks in verified monitoring data providers through compliance dependency and switching-cost architecture.
For Market Incumbents: Pre-empt margin compression in hardware tiers by accelerating backward integration into Yangtze River Delta sensor assembly capacity and securing captive supply of multispectral imaging components. Lock in entomology-AI hybrid talent pools before agricultural extension services recognize the skill scarcity. The priority lever centers on ISO 17025 accreditation investment that commands premium positioning in export certification workflows. For New Entrants and Emerging Players: Establish a beachhead in European food processing facilities where HACCP documentation requirements outpace digitization penetration and Rentokil Initial's service-network density remains underdeveloped in Southern Europe. Target Spain and Italy specialty crop operations confronting steepest REACH chemical authorization adaptation curves. The go-to-market angle emphasizes subscription-based facility management bundling rather than capital-intensive hardware sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software analytics layers as cloud-based platforms capture recurring licensing revenue without field service infrastructure. Long-term viability favors vendors with data-network effects from cross-farm population modeling. Acquisition target archetype: regional monitoring service providers with entomologist-staffed validation capabilities. The signal to watch is AI classification accuracy claims backed by research institution validation studies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Yangtze River Delta assembly capacity secures supply continuity for EU Green Deal compliance hardware. |
| ISO 17025 Accreditation Investment | Audit-trail architectures command premium positioning in Germany's export-dependent cooperative sector. |
| AI Training Data Partnerships | Research institution collaborations validate species classification accuracy for regional pest biotype libraries. |
| Service-Network Geographic Expansion | Response-time SLA coverage gaps in Southern Europe create subscription revenue capture opportunities. |
| Cloud Analytics Platform Development | Predictive population modeling software captures margin pools surrendered by commoditized IoT hardware. |
Methodological Framework
Operator-level perspectives from precision agriculture cooperative managers, pest control service network directors, agricultural entomologists, and food processing facility compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from EPA pesticide application documentation databases, EU Green Deal regulatory filings, ANVISA registration requirements, and ISO 17025 accreditation body records. Bottom-up sensor shipment modeling and top-down agricultural input spend analysis provided triangulation discipline.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application, technology maturity, and end-user procurement modality. CAGRs derived from installed base expansion rates and recurring software licensing attach rates. Industry-specific forecast inputs included EU pesticide reduction mandate compliance deadlines and REACH chemical authorization restriction timelines.
Sensitivities concentrate around semiconductor foundry capacity allocation volatility, tariff regime adjustments between China and the European Union, and AI classification accuracy validation standards. Forecasts reflect documented assumptions on regulatory enforcement intensity and cooperative consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Precision Agriculture Market