
 MSW Bag Opener Market | 2026-2036
MSW Bag Opener Market Size, Share, and Industry Trends Forecast 2026-2036
MSW Bag Opener Market Outlook
The EU Green Deal is recalibrating waste infrastructure investment across member states. BOA RECYCLING EQUIPMENT BV leverages its Dutch manufacturing base to supply high-throughput bag openers for continental recycling networks. BRT HARTNER anchors Central European demand with specialized hydraulic systems engineered for mixed municipal streams. Vecoplan LLC competes through modular electric designs that accommodate retrofit installations at aging transfer stations.
An MSW bag opener is a mechanical device that ruptures sealed refuse bags to liberate contents for downstream sorting, typically processing 5–30 tons per hour through rotating drum or ripping claw configurations. Electric openers lead the product type category due to lower operating noise and energy precision, while hydraulic variants retain share in high-contamination industrial waste applications where torque requirements exceed electric motor limits. Automated technology segments attract capital as single-stream recycling facilities pursue reduced manual presorting labor.
EMA and ECHA frameworks govern equipment safety and chemical exposure limits in European waste handling operations, while REACH compliance affects polymer blade coatings and lubricant specifications. Germany's KBA and France's ANSM enforce national implementation of EU directives through facility permitting and operator certification. Buyers should monitor how the EU AI Act and pending machine-vision standards reshape integration requirements for sensor-equipped automated bag openers.
Market Dynamics
EU landfill diversion mandates under the Waste Framework Directive are compressing installation timelines for automated bag openers at municipal transfer stations, forcing equipment buyers to prioritize throughput-per-square-meter over capital cost minimization.
Growth Catalysts
- EU Green Deal Implementation:Member state recycling targets are mandating mechanized front-end processing at single-stream facilities, particularly in Germany and France where landfill diversion deadlines are tightening.
- Rotating Drum Configurations:Electric motor precision is enabling 15–25 ton-per-hour throughput with noise profiles below 75 decibels, satisfying urban siting restrictions in dense Dutch and Belgian recycling hubs.
- Labor Cost Arbitrage:Scandinavian municipalities facing presorter wage premiums are accelerating automated bag opener procurement to reduce manual sorting headcount at material recovery facilities.
Market Restraints
- Hydraulic Fluid Input Volatility:Biodegradable hydraulic oil prices fluctuate with rapeseed and synthetic ester feedstock markets, squeezing margin on high-torque industrial waste variants.
- Blade Supply Concentration:Hardened steel and polymer-composite cutting surfaces depend on German and Austrian specialty metallurgy suppliers, creating single-source vulnerability for maintenance cycles.
- REACH Compliance Friction:Polymer blade coatings and synthetic lubricants face ECHA authorization delays, extending equipment qualification timelines by 8–14 months for non-EU manufacturers.
Strategic Opportunities
- Eastern European Retrofit Wave:Polish and Romanian transfer stations built in the 1990s lack mechanized bag opening, creating replacement demand as EU cohesion funds flow to waste infrastructure.
- Machine Vision Convergence:Integration of near-infrared sensors with automated bag openers enables real-time contamination detection, unlocking premium pricing for sensor-equipped installations.
- Service Contract Unbundling:Blade replacement and drum reconditioning are splitting from equipment sales, creating recurring revenue streams for specialized maintenance providers.
Industry Challenges
- Electromechanical Technician Scarcity:Maintenance of servo-driven electric openers requires PLC programming skills that remain concentrated in German and Swiss industrial training pipelines.
- Legacy Hydraulic Integration:Aging Central European facilities with existing pneumatic infrastructure face costly compressed air-to-electric retrofitting to accommodate modern bag opener architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MSW Bag Opener Market |
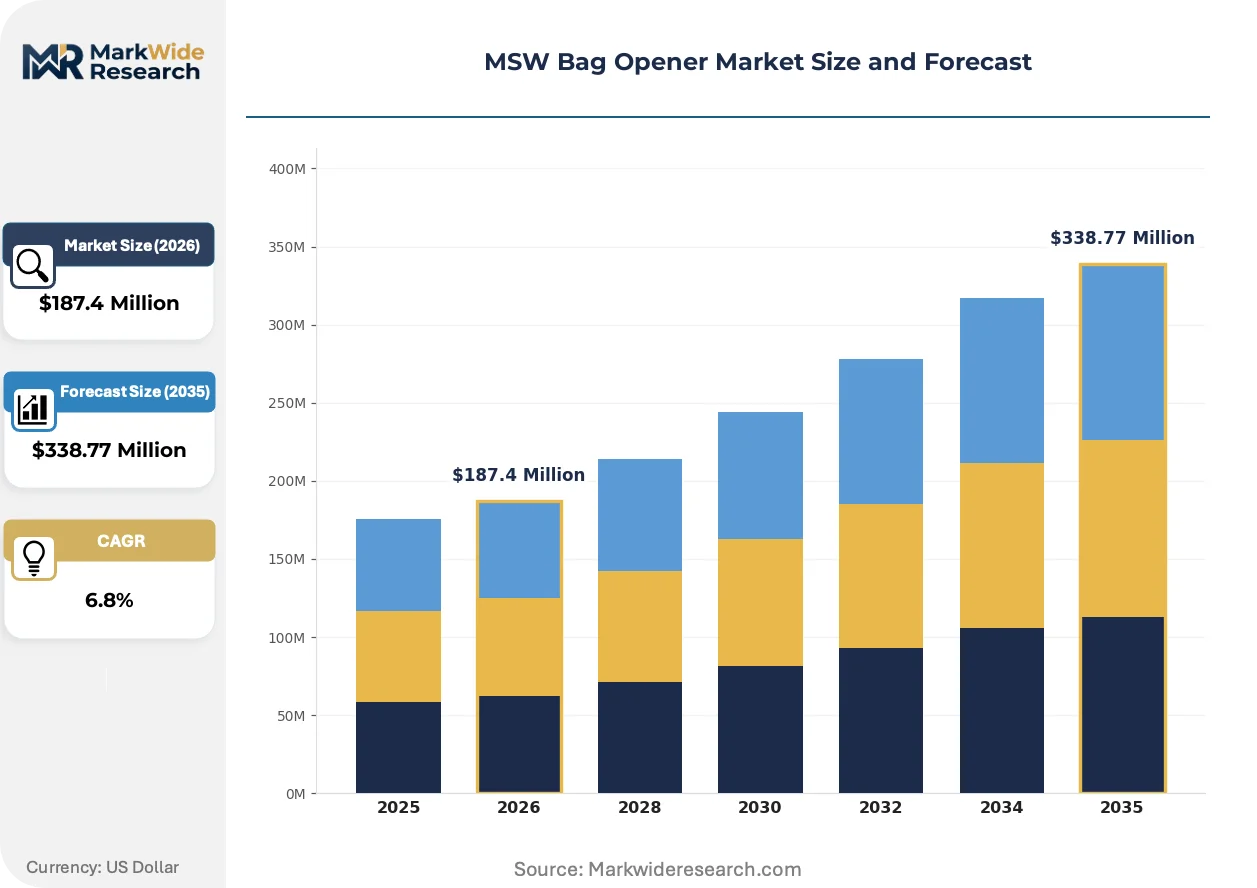
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Openers, Electric Openers, Hydraulic Openers, Pneumatic Openers Application: Waste Management, Recycling Facilities, Municipal Services, Industrial Waste End User: Contractors, Municipalities, Waste Disposal Companies, Recycling Centers Technology: Mechanical, Pneumatic, Electrical, Automated |
| Companies Covered | BOA RECYCLING EQUIPMENT BV, BRT HARTNER, Coparm Srl, WAMGROUP S.p.A, Riggs Auto Pack Ltd, CP Manufacturing, Bulk Handling Systems, Van Dyk Recycling Solutions, Vecoplan LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MSW Bag Opener Market Strategic Shifts
Permanent magnet synchronous motor technology is compressing energy consumption curves for high-throughput bag openers, while EU regulatory pressure on noise emissions and chemical exposure is accelerating design iteration cycles among equipment manufacturers.
Permanent magnet motor architecture is electrifying the electric bag opener segment by delivering torque density previously achievable only through hydraulic systems. Dutch and German single-stream recyclers are specifying these configurations for new-build facilities. The technology is electrifying competitive positioning by enabling modular, containerized installations that bypass concrete foundation requirements.
REACH authorization timelines for polymer blade coatings are extending equipment qualification periods, forcing manufacturers to maintain dual lubricant inventories. ECHA's evolving substance restrictions are compressing formulation flexibility for cutting surface materials. Automated bag opener vendors with pre-qualified coating suppliers are capturing municipal procurement contracts that exclude late-qualifying competitors.
Performance-based service agreements are displacing traditional time-and-materials maintenance contracts for high-availability installations. German municipal waste associations are piloting throughput-guarantee contracts that bundle blade replacement with uptime penalties. This model concentrates in North Rhine-Westphalia, where landfill diversion penalties create acute reliability requirements for sorting line front-ends.
MSW Bag Opener Market Segmentation
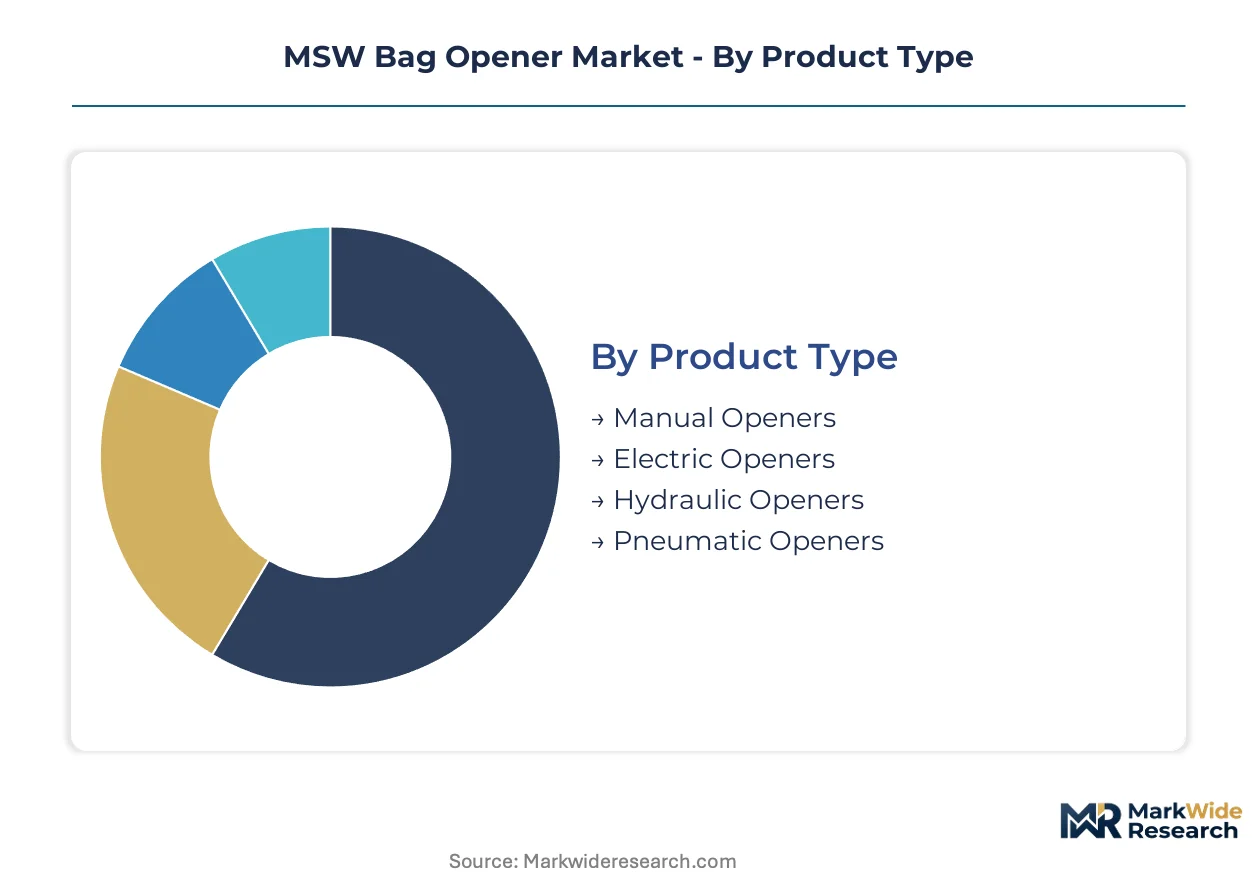
MSW bag opener procurement patterns diverge sharply between standalone retrofit installations and integrated sorting line architectures. Equipment specification varies by contamination profile, labor availability, and downstream automation requirements. Understanding these segment boundaries enables vendors to align torque specifications, control systems, and service models with actual deployment contexts.
Product Type:
Standalone bag openers dominate greenfield single-stream facilities where concrete foundations and electrical infrastructure accommodate purpose-built designs. Embedded pneumatic and compact electric units serve constrained transfer stations requiring containerized or skid-mounted deployment.
- Manual Openers:Hand-operated cutting stations with fixed or reciprocating blade configurations serve low-volume rural transfer stations below 2 tons per hour. Demand concentrates in Romanian and Bulgarian municipalities where EU cohesion fund access remains limited and labor costs suppress automation justification.
- Electric Openers:Servo-driven rotating drum systems deliver 15–25 ton-per-hour throughput with noise profiles below 75 decibels. Dutch and Belgian recycling hubs specify these for urban siting where acoustic restrictions apply and grid stability supports precision motor control.
- Hydraulic Openers:High-torque ripping claw configurations process contaminated industrial waste streams exceeding electric motor limits. German steel-to-recycling facilities and French construction debris processors maintain procurement preference where puncture resistance and variable load tolerance outweigh energy efficiency priorities.
- Pneumatic Openers:Compressed-air actuated systems leverage existing infrastructure at aging Central European facilities. Polish transfer stations built during the 1990s specify these for compatibility with legacy pneumatic conveying networks, though retrofit costs to electric architectures are rising.
Volume placements concentrate in Electric Openers; the faster expansion belongs to Automated technology convergence within this category.
Application:
Front-end processing intensity varies by waste stream heterogeneity and downstream sorting automation level. Facilities with near-infrared separation downstream prioritize gentle bag rupture to preserve material integrity; manual-sorting-dependent operations tolerate more aggressive tearing.
- Waste Management:Integrated transfer station operations where bag opening precedes compaction or direct landfill diversion. Demand clusters in German municipalities facing Waste Framework Directive diversion deadlines with limited sorting infrastructure budgets.
- Recycling Facilities:Single-stream material recovery facilities requiring consistent liberated material presentation to ballistic separators and optical sorters. Swedish and Danish operators specify automated bag openers to reduce presorter headcount amid Nordic labor cost premiums.
- Municipal Services:City-owned collection and processing operations with civil servant staffing constraints and public procurement transparency requirements. French municipal waste associations pilot throughput-guarantee contracts that bundle equipment with uptime penalties.
- Industrial Waste:Manufacturing and demolition waste streams with high puncture risk from metal, glass, and construction debris. Specialized hydraulic systems engineered by BRT HARTNER anchor this segment with hardened claw configurations.
Revenue concentration sits with Recycling Facilities; the steepest expansion trajectory belongs to Municipal Services amid EU Green Deal implementation.
End User:
Procurement authority fragmentation shapes specification priorities: contractors prioritize mobility and rapid deployment; municipalities emphasize total cost of ownership and local content requirements; waste disposal companies optimize for throughput density.
- Contractors:Mobile and containerized bag openers for temporary waste processing at demolition sites and event venues. Specifications prioritize rapid commissioning and transportability over energy efficiency.
- Municipalities:Public sector procurement with multi-year capital planning horizons and EU funding compliance requirements. German KBA facility permitting and French ANSM operator certification govern equipment selection.
- Waste Disposal Companies:Private landfill and incineration operators seeking front-end homogenization to improve combustion efficiency or compaction density. Margin pressure favors hydraulic reliability over electric precision.
- Recycling Centers:Material recovery facility operators with sensor-equipped sorting lines requiring consistent feed presentation. Vecoplan LLC competes for this segment with modular electric designs accommodating retrofit installations.
Contract volume concentrates in Municipalities; Recycling Centers are climbing the fastest amid single-stream infrastructure expansion.
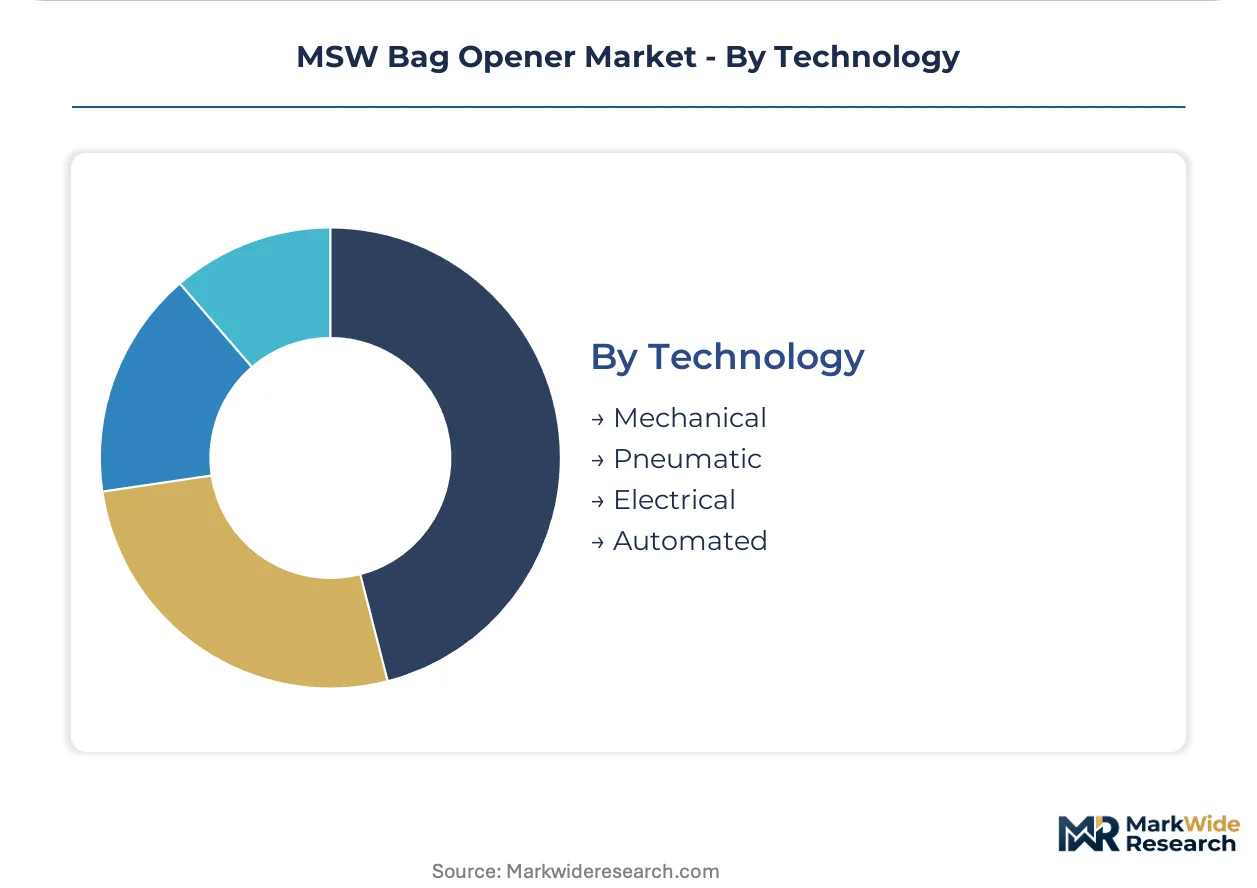
Technology:
Control system sophistication determines integration depth with downstream sorting automation. Mechanical and pneumatic architectures suit isolated operations; electrical and automated configurations enable machine-vision convergence and real-time contamination detection.
- Mechanical:Direct-drive rotating drums and fixed blade arrays without electronic control systems. Lowest capital cost segment serving budget-constrained Eastern European facilities with limited technical maintenance capacity.
- Pneumatic:Compressed-air actuation with simple valve control logic. Compatibility with legacy infrastructure at Polish and Romanian transfer stations built during pre-EU accession periods sustains residual demand.
- Electrical:Variable frequency drive motor control with programmable logic for torque modulation and jam detection. BOA RECYCLING EQUIPMENT BV leverages Dutch manufacturing to supply these for continental recycling networks.
- Automated:Sensor-integrated systems with near-infrared contamination detection and adaptive drum speed adjustment. EU AI Act and pending machine-vision standards are reshaping integration requirements for this segment.
Installed base concentrates in Electrical systems; Automated configurations are gaining share fastest through machine vision convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European bag opener procurement, with Dutch and Belgian recycling hubs driving electric system specifications for urban-constrained facilities.
Germany
Municipalities in North Rhine-Westphalia and Bavaria are expanding automated bag opener procurement to meet EU landfill diversion targets under the Waste Framework Directive. Germany's KBA enforces facility permitting and operator certification for waste handling equipment. The Rhine-Ruhr corridor concentrates demand where landfill diversion penalties create acute reliability requirements for sorting line front-ends.
France
French municipal waste associations pilot throughput-guarantee contracts that bundle blade replacement with uptime penalties for automated installations. ANSM enforces national implementation of EU directives through facility permitting and operator certification. The Île-de-France region drives specification of low-noise electric configurations for urban material recovery facilities.
Netherlands
Dutch single-stream recyclers specify permanent magnet synchronous motor configurations for new-build facilities in the Randstad region. The EU Green Deal recalibrates waste infrastructure investment across member states, with Dutch recycling networks prioritizing mechanized front-end processing. Rotterdam and Amsterdam anchor continental demand for containerized electric installations that bypass concrete foundation requirements.
Sweden
Scandinavian municipalities facing presorter wage premiums are accelerating automated bag opener procurement to reduce manual sorting headcount. REACH compliance affects polymer blade coatings and lubricant specifications for equipment operating in Nordic conditions. Stockholm and Gothenburg material recovery facilities specify automated technology segments as single-stream recycling facilities pursue reduced manual presorting labor.
Poland
Polish transfer stations built in the 1990s lack mechanized bag opening, creating replacement demand as EU cohesion funds flow to waste infrastructure. ECHA authorization timelines for polymer blade coatings extend equipment qualification periods for non-EU manufacturers. The Silesian and Greater Poland regions concentrate pneumatic-to-electric retrofit activity as facilities modernize aging compressed air infrastructure.
MSW Bag Opener Market Competitive Environment
The competitive structure tilts toward specialized European fabricators with established recycling equipment lineages. Market concentration remains moderate, with regional specialists commanding premium positioning in high-throughput municipal segments while broader environmental equipment conglomerates compete on bundled sorting line economics. Three archetypes dominate: Dutch-German precision engineering houses, Italian bulk materials specialists, and North American integrated recycling system providers. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as vendors race to qualify permanent magnet motor and machine-vision configurations under evolving EU standards.
Among Dutch-German engineering houses, BOA RECYCLING EQUIPMENT BV and BRT HARTNER occupy positions as archetype anchors for high-throughput municipal applications. Vecoplan LLC represents the North American integrated system provider archetype with modular design positioning. These three exemplify the geographic and technological specialization that fragments competitive positioning across the European recycling infrastructure build-out.
| Leading Market Players |
|---|
| BOA RECYCLING EQUIPMENT BV |
| BRT HARTNER |
| Coparm Srl |
| WAMGROUP S.p.A |
| Riggs Auto Pack Ltd |
| CP Manufacturing |
| Bulk Handling Systems |
| Van Dyk Recycling Solutions |
| Vecoplan LLC |
| Others |
Value Chain & Pricing Dynamics
EU landfill diversion mandates under the Waste Framework Directive are compressing municipal procurement timelines, forcing equipment buyers to prioritize throughput-per-square-meter and uptime guarantees over capital cost minimization. This specification shift concentrates pricing power with vendors offering performance-based service contracts and pre-qualified REACH-compliant blade coatings.
Pricing Analysis
Throughput-guarantee contracts that bundle blade replacement with uptime penalties anchor value-based pricing in German and French municipal procurement. Three-tier pricing structure across premium automated, standard electric, and economy hydraulic configurations differentiates offerings by noise profile, energy efficiency, and integration depth with downstream sorting automation. Pricing pressure stems from REACH authorization delays extending equipment qualification timelines for non-EU manufacturers, compressing margin on late-qualifying entrants. Municipalities exhibit highest price sensitivity due to multi-year capital planning horizons and EU funding compliance requirements, while recycling centers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Electromechanical technician scarcity in German and Swiss industrial training pipelines constrains production scaling for servo-driven electric opener manufacturers. Supply concentrates in the Netherlands, Germany, and Austria, where specialty metallurgy suppliers dominate hardened steel and polymer-composite cutting surfaces. Raw material dependencies include rare earth permanent magnets for synchronous motor architectures, biodegradable hydraulic oils derived from rapeseed and synthetic ester feedstocks, and REACH-compliant polymer blade coatings. Single-source vulnerability for specialty blade suppliers creates maintenance cycle risk. Distribution runs through direct municipal procurement channels and bundled sorting line integrators serving material recovery facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
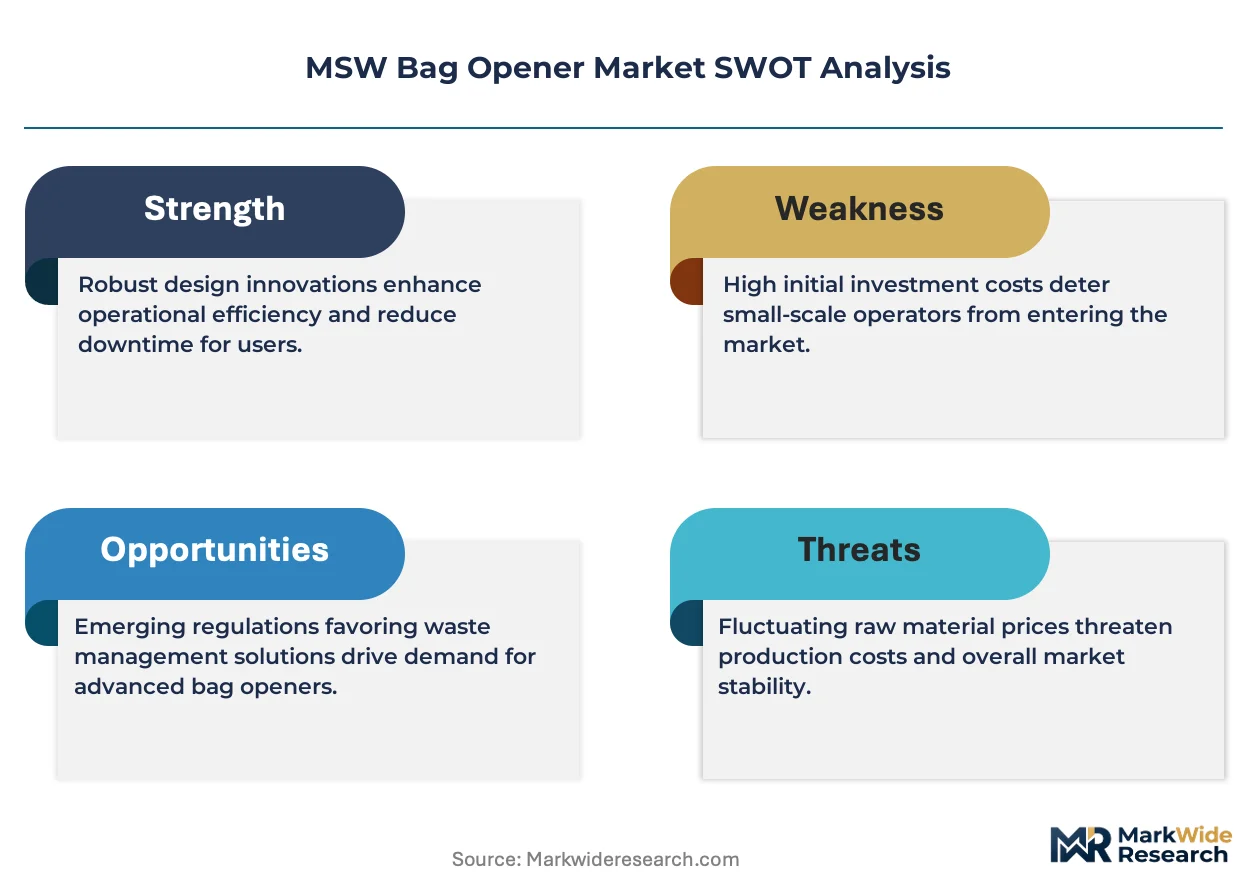
REACH compliance and ECHA authorization timelines function as a cost-of-compliance moat, excluding non-EU manufacturers from premium municipal procurement contracts and consolidating competitive positioning among pre-qualified European fabricators.
For Market Incumbents: Deploy permanent magnet motor technology licensing to defend share against modular electric entrants targeting retrofit installations. Capacity expansion in the Randstad region captures Dutch single-stream recycling hub demand. Certification investment in EU AI Act machine-vision standards preempts regulatory displacement of sensor-equipped automated configurations.
For New Entrants and Emerging Players: Machine vision convergence with near-infrared contamination detection offers technology-first entry into the automated segment where incumbents lag sensor integration. Polish and Romanian pneumatic-to-electric retrofit demand represents the most penetrable geography given EU cohesion fund availability and legacy infrastructure replacement cycles. Go-to-market through specialized maintenance providers unbundling blade replacement and drum reconditioning from equipment sales bypasses direct competition with established OEMs.
For Investors and Strategic Acquirers: Re-rating potential sits with Dutch-German precision engineering houses given EU Green Deal implementation accelerating waste infrastructure investment across member states. Long-term viability centers on vendors with pre-qualified REACH coating suppliers and permanent magnet motor architectures. Monitor ECHA substance restriction announcements as inflection indicators for equipment qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Adoption | Dutch recyclers specify these configurations for containerized installations bypassing concrete foundations. |
| Machine Vision Integration | Near-infrared sensor convergence enables real-time contamination detection and premium pricing capture. |
| Performance-Based Service Contracts | German municipal associations pilot throughput-guarantee agreements bundling blade replacement with uptime penalties. |
| Eastern European Retrofit Expansion | Polish transfer stations modernize aging pneumatic infrastructure with EU cohesion fund support. |
| REACH Pre-Qualification Investment | Dual lubricant inventories and pre-qualified coating suppliers secure municipal procurement contract exclusion of late entrants. |
Study Parameters
Independent corroboration across equipment procurement directors at material recovery facilities, maintenance heads at municipal transfer stations, and aftermarket service providers underwrites the qualitative findings. Primary interviews with plant engineers, OEM procurement teams, and recycling facility operators combined with secondary validation from ECHA authorization databases, EU customs equipment import records, and national waste association procurement disclosures. Bottom-up installation tracking and top-down infrastructure investment flow analysis triangulate market sizing.
Comparable-period anchoring to historical landfill diversion compliance deadlines and cohesion fund disbursement cycles structured the forecast window. Segmentation modeling spans product type, application intensity, end-user procurement authority, and technology sophistication across the projection horizon. CAGRs derive from throughput expansion trajectories at single-stream facilities and retrofit penetration rates at aging transfer stations. Inputs include EU Green Deal implementation timelines and ECHA substance restriction evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH authorization delays or permanent magnet supply disruptions. Forecasts reflect documented assumptions regarding landfill diversion penalty enforcement and cohesion fund allocation continuity. Material deviation in EU AI Act machine-vision standard finalization or ECHA polymer coating authorization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Compression Baggers Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Craft Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Leno Bags Market