
 Household and Cleaning Container Market | 2026-2036
Household and Cleaning Container Market Size, Share, and Industry Trends Forecast 2026-2036
Household and Cleaning Container Market Foresight
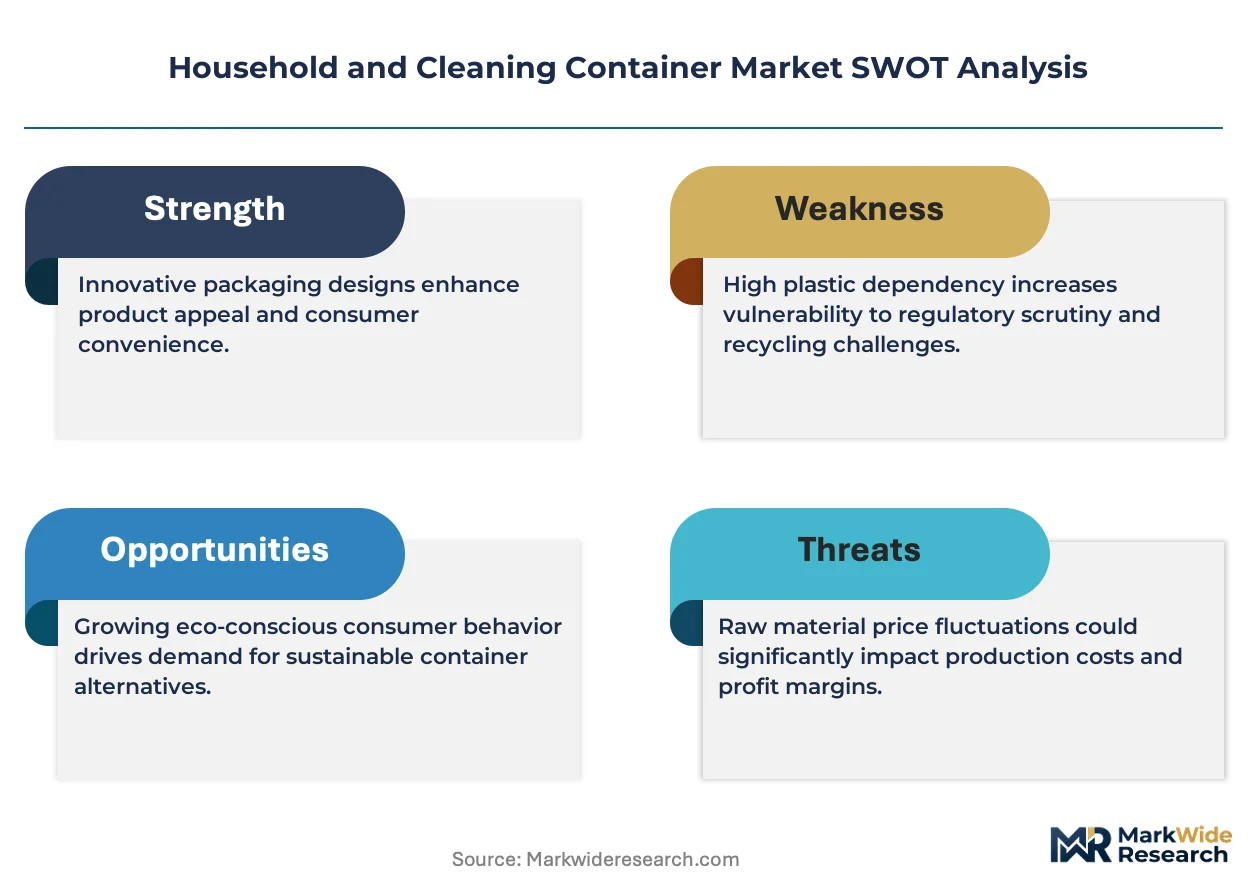
REACH compliance is expanding the cost-of-entry calculus for household and cleaning container manufacturers targeting European distribution. Procter & Gamble leverages captive polymer compounding facilities to manage regulatory certification costs internally. Henkel anchors its container sourcing strategy through long-term supplier partnerships in Germany and the Netherlands. SC Johnson differentiates via concentrated refill formats that reduce per-unit plastic mass.
Household and cleaning containers are receptacles engineered from thermoplastics, coated metals, or engineered composites, typically specifying wall thicknesses of 1.5–4 mm and closure tolerances that prevent vapor transmission or spillage during transport and storage. Their primary commercial purpose is to preserve chemical stability, enable measured dispensing, and support closed-loop logistics for concentrated and ready-to-use formulations. Plastic material grades dominate volume production due to injection molding scalability and lightweight logistics economics, though metal containers retain margin concentration in industrial solvent applications where thermal resistance and grounding safety are mandatory. The residential application segment leads absolute unit demand, while commercial cleaning contracts represent the fastest-growing channel as facility management outsourcing expands across hospitality and healthcare sectors.
The EPA regulates volatile organic compound emissions from cleaning product packaging under 40 CFR Part 59, while FDA maintains jurisdiction over sanitizing containers making residual efficacy claims in food-contact environments. OSHA hazard communication standards mandate specific labeling geometries and durability thresholds that directly shape container design specifications for industrial applications. Stakeholders must monitor how emerging state-level extended producer responsibility frameworks in California and New York will alter cost allocation between brand owners and packaging converters.
Market Dynamics
REACH compliance is forcing reformulation of polymer stabilizers and colorants across European supply chains, compressing margins for converters lacking captive compounding capabilities. The EU's Single-Use Plastics Directive is accelerating migration toward recycled-content resins, creating asymmetric cost burdens between integrated and non-integrated manufacturers.
Growth Catalysts
- Commercial janitorial outsourcing:Facility management contracts across hospitality and healthcare sectors are expanding procurement of specialized cleaning caddies and mobile dispensing systems.
- REACH polymer certification:Regulatory pressure is concentrating demand among converters with pre-certified resin streams, locking in supplier relationships.
- Concentrated refill formats:Down-gauging of per-unit plastic mass is reducing logistics costs and enabling closed-loop distribution economics for brand owners.
Market Restraints
- Post-consumer resin price volatility:rPET and rHDPE feedstock costs fluctuate with collection infrastructure gaps in Germany and the Netherlands.
- Injection mold tooling concentration:High-precision closure molds for vapor-tight seals concentrate among a limited base of European toolmakers.
- Metal substitution ceiling:Industrial solvent applications retain metal containers where thermal resistance and grounding safety remain non-negotiable.
Strategic Opportunities
- Industrial cleaning protocols in Germany:Premium container specifications for chemical stability and measured dispensing remain underpenetrated by specialized converters.
- Extended producer responsibility frameworks:California and New York state-level EPR legislation is creating first-mover advantage for take-back infrastructure investors.
- Smart dispensing convergence:Integration of RFID-enabled inventory tracking with ergonomic container design is opening premium positioning in commercial contracts.
Industry Challenges
- Polymer compounding talent scarcity:Formulation chemists capable of certifying recycled-content resins under REACH are concentrated among legacy German and Dutch suppliers.
- Multi-jurisdiction labeling compliance:OSHA hazard communication standards for industrial applications conflict with FDA food-contact efficacy claims, requiring parallel container SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household and Cleaning Container Market |
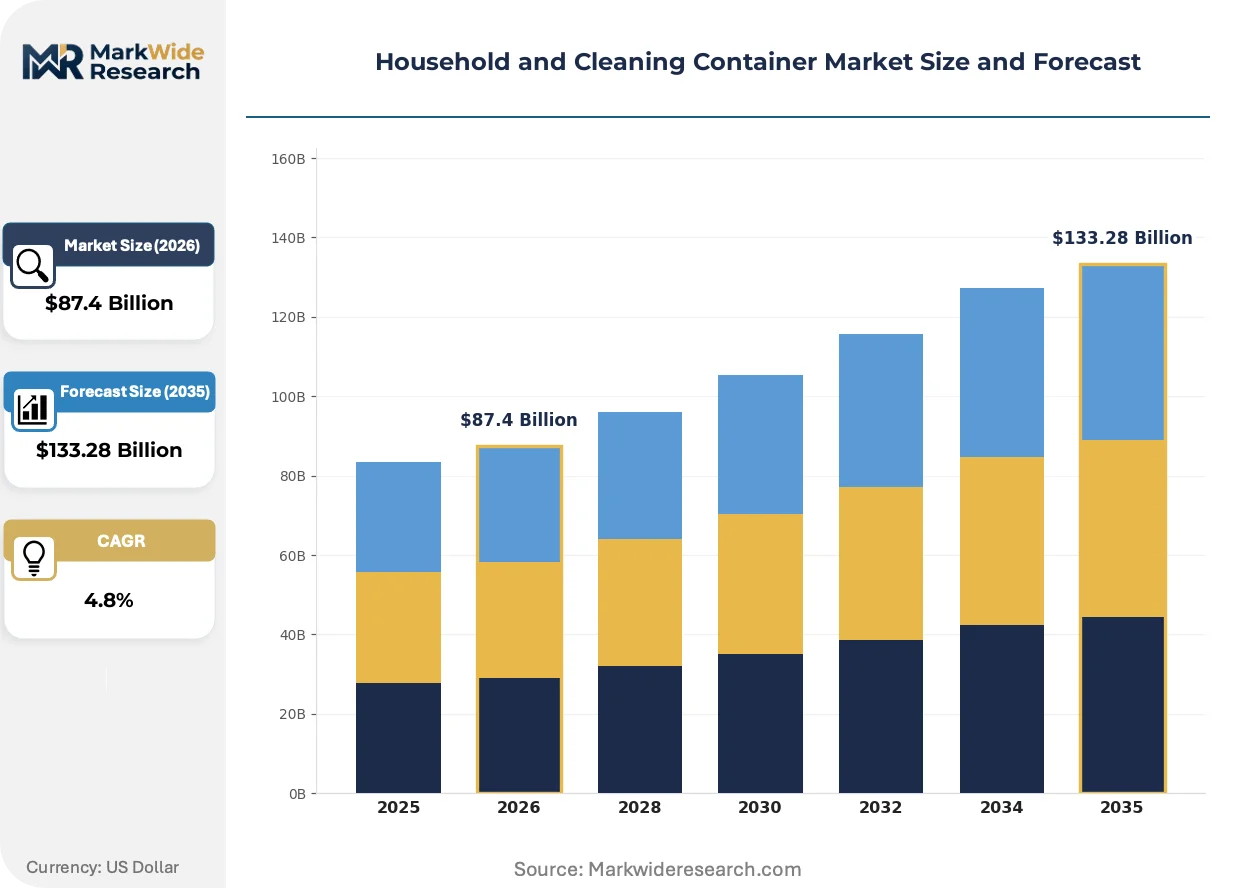
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trash Bins, Storage Totes, Recycling Containers, Cleaning Caddies Material: Plastic, Metal, Wood, Glass Application: Residential, Commercial, Industrial, Automotive Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Procter & Gamble, Unilever, Henkel, Reckitt Benckiser, Colgate-Palmolive, SC Johnson, Newell Brands, 3M Company, Freudenberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household and Cleaning Container Market Shifts & Advancements
Material science advances and regulatory stringency are compressing design cycles while fragmenting procurement authority between sustainability officers and operations managers. Three forces are actively restructuring competitive positioning.
Monomaterial polyethylene designs are decentralizing sorting and recycling infrastructure requirements across European reverse logistics networks. Retail chains and commercial cleaning contractors are accelerating adoption to preempt EPR cost allocation. This architecture is decentralizing converter margins away from complex multi-layer specialists toward single-resin molders with certified recycled streams.
ECHA's SVHC candidate list expansion is forcing substitution of phthalate plasticizers and certain UV stabilizers in polypropylene containers. Industrial compounders are reformulating additive packages to maintain clarity and impact resistance. Food-contact and childcare cleaning segments are most affected, with German brand owners advancing supplier qualification timelines by eight to twelve months.
Direct procurement relationships between facility management groups and specialized molders are compressing distributor margins in North American commercial channels. Group purchasing organizations are consolidating volume and mandating sustainability certifications that exclude legacy trading relationships. This disintermediation is most visible in healthcare and hospitality verticals where ESG reporting requirements penetrate procurement scorecards.
Household and Cleaning Container Market Segmentation
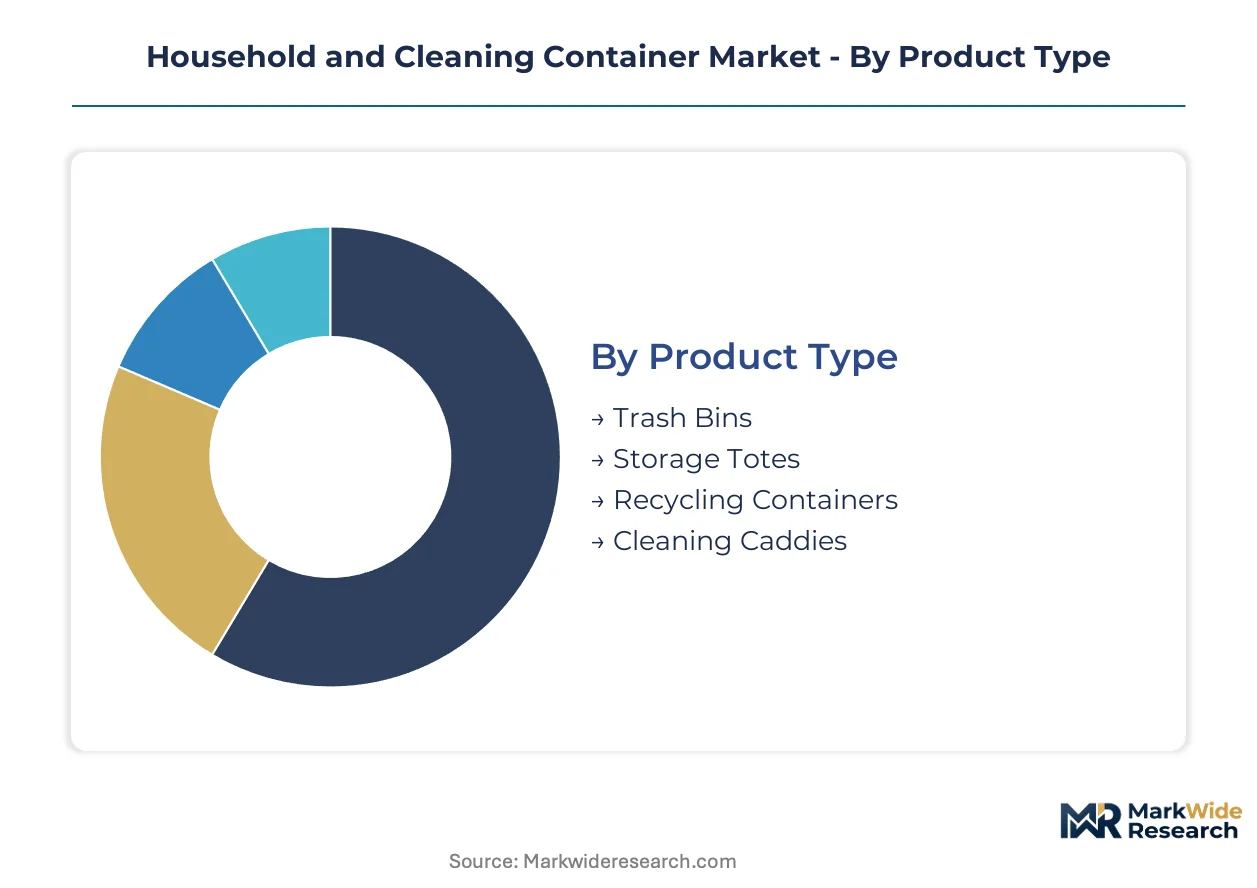
Segmentation in household and cleaning containers reveals divergent margin structures across material grades and procurement channels. Volume concentration in residential plastics contrasts with premium capture in specialized commercial formats. Understanding these splits enables targeted capacity planning and certification investment.
Product Type:
Trash bins dominate absolute unit volumes while cleaning caddies command premium pricing in commercial contracts.
- Trash Bins:High-density polyethylene and polypropylene constructions with wall thicknesses of 2.5–4 mm support mechanical durability for municipal and residential waste streams. Demand concentrates in North American suburban housing developments where roll-out cart specifications are standardized by waste hauler contracts. Lidded designs with integrated wheels face procurement consolidation among municipal purchasing cooperatives.
- Cleaning Caddies:Injection-molded polypropylene or engineered composites with compartmentalized storage and ergonomic handles enable mobile dispensing for janitorial crews. Demand clusters in German healthcare facility management contracts where DIN-certified chemical resistance is mandatory. Specialized converters with REACH-certified resin streams are locking in multi-year supply agreements.
- Storage Totes:Stackable designs with reinforced corners serve residential organization and light commercial inventory.
- Recycling Containers:Color-coded polypropylene formats align with single-stream municipal sorting protocols.
Today's leader: Trash bins. Tomorrow's challenger: Cleaning caddies.
Material:
Plastic commands production scale while metal retains irreplaceable positions in safety-critical applications.
- Plastic:Thermoplastic grades—primarily HDPE, PP, and PET—enable injection molding economies and lightweight logistics with specific gravity below 1.2 g/cm³. Demand concentrates in residential channels where cost-per-unit drives procurement decisions. EPR frameworks in California and New York are accelerating rHDPE and rPP qualification timelines.
- Metal:Coated steel and aluminum constructions provide thermal resistance and electrical grounding for flammable solvent storage. Industrial solvent applications in German chemical processing facilities mandate UN-certified metal drums where plastic substitution remains prohibited by safety codes.
- Wood:Aesthetic-driven segments in premium residential décor with limited chemical exposure tolerance.
- Glass:Specialty sanitizer bottles with UV stability for premium retail positioning.
Plastics generate volume economics. Metal defends niche premiums.
Application:
Residential channels absorb capacity while commercial contracts rewrite margin structures through sustainability specifications.
- Residential:Mass-market distribution through big-box retailers and e-commerce platforms with price elasticity driving standardization around 32–96 gallon capacities. Demand clusters in US suburban markets where HOA covenants mandate uniform curb aesthetics.
- Commercial:Facility management outsourcing across hospitality and healthcare sectors is expanding procurement of specialized caddies with RFID tracking compatibility. Group purchasing organizations are consolidating volume and mandating recycled-content certifications that exclude non-compliant converters.
- Industrial:Chemical stability requirements for concentrated solvent storage with OSHA hazard communication labeling.
- Automotive:Detail shop provisioning with space-optimized footprints for mobile service operations.
Residential owns current volume. Commercial owns expanding share.
Capacity:
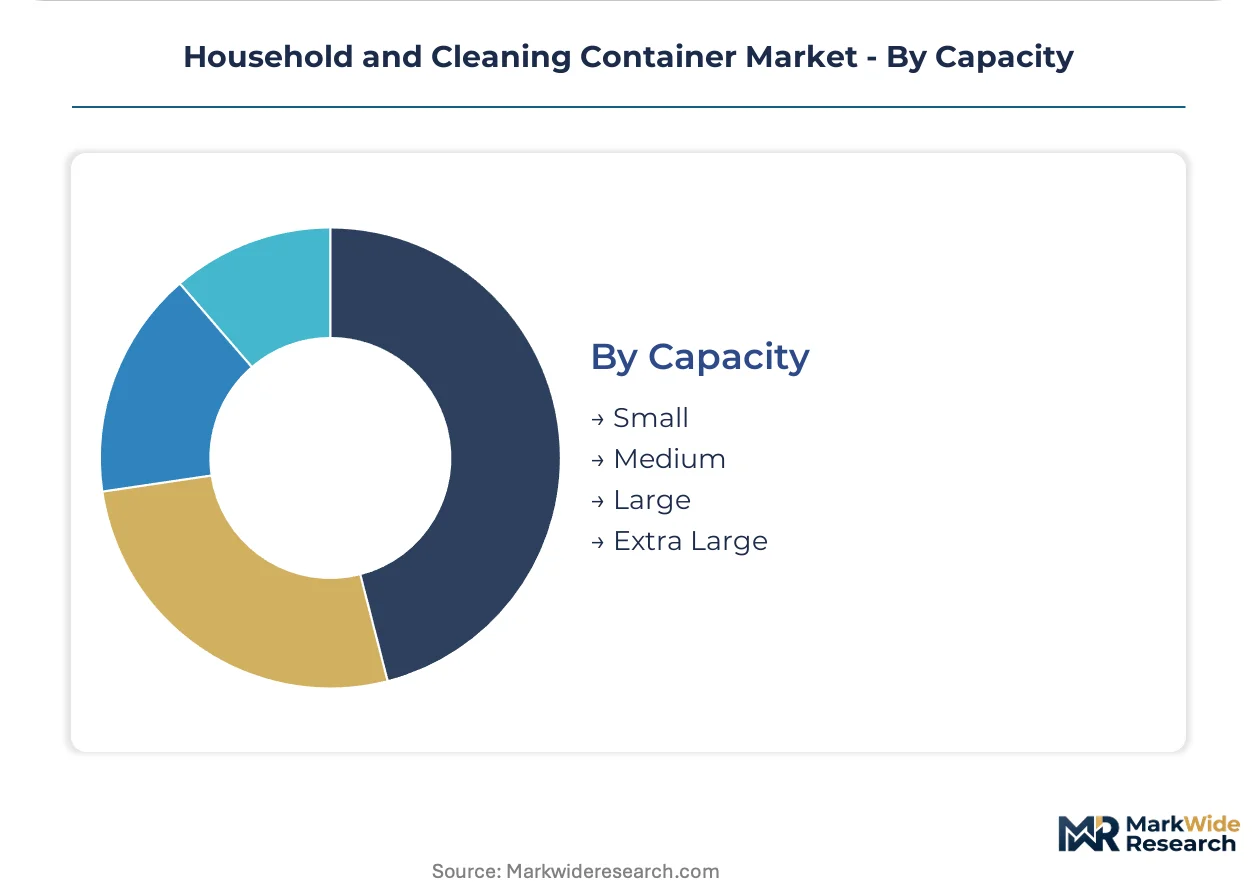
Medium formats balance handling ergonomics with logistics cube efficiency across last-mile distribution.
- Medium:10–20 gallon polypropylene totes and caddies optimize weight-to-volume ratios for manual transport in commercial cleaning workflows. Demand concentrates in German industrial cleaning protocols where DIN 30700 handling standards govern ergonomic design.
- Large:32–50 gallon roll-out carts and recycling containers maximize payload for municipal collection cycles. US waste hauler contracts in California and Texas specify automated lift-arm compatibility.
- Small:Under-sink and countertop formats for residential kitchen and bathroom organization.
- Extra Large:65+ gallon municipal carts and industrial drum formats for centralized collection points.
Medium captures commercial mobility. Large captures municipal consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding chemists with REACH certification credentials concentrate disproportionately in Germany and the Netherlands, anchoring European container supply chains. This talent distribution shapes where brand owners qualify new resin streams and where specialized converters secure multi-year contracts.
United States
Municipal waste hauler contracts in California and Texas standardize roll-out cart specifications around automated lift-arm compatibility. EPA regulations under 40 CFR Part 59 govern volatile organic compound emissions from cleaning product packaging. Manufacturing clusters in the Midwest and Southeast serve big-box retail distribution networks with high-volume HDPE injection molding capacity.
Germany
Industrial cleaning protocols in healthcare and chemical processing facilities drive demand for DIN-certified chemical resistance specifications. REACH compliance mandates pre-certified resin streams, compressing supplier qualification timelines. The Rhine-Ruhr and Baden-Württemberg regions host legacy compounders with captive polymer stabilization capabilities.
China
Injection molding scale economics support cost-competitive production for export-oriented brand owners. GB standards and evolving environmental regulations under MEE supervision govern food-contact and industrial container applications. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta with integrated resin-to-mold supply chains.
Netherlands
Rotterdam port logistics enable efficient rPET and rHDPE feedstock sourcing for recycled-content container production. ECHA regulatory proximity accelerates SVHC compliance documentation for EU distribution. The Randstad region clusters specialized converters serving Benelux facility management contractors with REACH-certified supply agreements.
India
Rising facility management outsourcing in hospitality and healthcare sectors expands commercial cleaning caddy demand. BIS standards govern plastic container specifications for domestic distribution, while export-oriented producers navigate customer-mandated sustainability certifications. Manufacturing concentrates in Maharashtra and Gujarat with growing technical compounding capabilities.
Household and Cleaning Container Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base organizes around three strategic archetypes: integrated resin-to-container manufacturers with captive compounding, specialized molders serving commercial cleaning contracts, and diversified consumer goods houses with internal packaging operations. Competitive moves concentrate on securing REACH-certified resin supply agreements and qualifying post-consumer recycled content streams ahead of EPR implementation timelines.
Among diversified consumer goods houses, Procter & Gamble, Unilever, and Henkel occupy positions that exemplify backward integration into polymer compounding and long-term supplier partnership strategies. These structures enable internal management of regulatory certification costs while locking in qualified resin streams for European distribution. Their procurement scale shapes converter investment priorities around recycled-content capabilities and smart dispensing integration.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel |
| Reckitt Benckiser |
| Colgate-Palmolive |
| SC Johnson |
| Newell Brands |
| 3M Company |
| Freudenberg Group |
| Others |
Supply & Pricing Matrix
Captive polymer compounding in Germany and the Netherlands anchors supply positions and pricing power for REACH-certified converters serving European brand owners. This integration choice insulates qualified suppliers from rPET and rHDPE feedstock volatility while compressing margins for non-integrated competitors.
Pricing Analysis
Service bundling separates container-only transactions from closed-loop logistics packages with take-back infrastructure. Pricing stratifies across REACH-certified premium tiers, standard DIN-compliant mid-tiers, and economy grades for residential retail. Cost compression in standard tiers is intensifying because municipal purchasing cooperatives consolidate volume. Residential retail channels exhibit highest price sensitivity; German healthcare facility management contracts show lowest elasticity due to chemical stability mandates.
Supply Chain Analysis
Single-source vulnerability sits with European toolmakers for high-precision closure molds requiring vapor-tight tolerances. Manufacturing concentrates in Germany, the Netherlands, and China's Yangtze River Delta. Feedstock draws from Rotterdam rPET/rHDPE streams and virgin resin producers in the Rhine-Ruhr region. Tariff exposure on Chinese injection-molded components threatens cost structures. Distribution runs through facility management group purchasing organizations consolidating commercial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through concentrated refill formats that down-gauge per-unit plastic mass while capturing premium positioning in commercial contracts.
For Market Incumbents: Extend REACH-certified resin stream qualifications ahead of California and New York EPR implementation timelines. Lock in multi-year supply agreements with German healthcare facility management contractors before specialized converters consolidate relationships. Counter disintermediation by integrating RFID-enabled inventory tracking into container design specifications.
For New Entrants and Emerging Players: Smart dispensing convergence with ergonomic caddy design offers technology-first entry into underpenetrated German industrial cleaning protocols. Target medium-capacity commercial formats where DIN 30700 handling standards create certification barriers for commodity molders. Pursue direct procurement relationships with hospitality group purchasing organizations mandating sustainability scorecards.
For Investors and Strategic Acquirers: Roll-up economics work for specialized commercial cleaning container converters because EPR frameworks and REACH compliance are fragmenting procurement toward certified suppliers. Focus on mid-cap molders with captive compounding in the Randstad or Rhine-Ruhr regions. Watch for inflection when California EPR cost allocation rules trigger brand owner switching from legacy trading relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH certification costs internalize for converters serving Henkel and Procter & Gamble supply chains. |
| Recycled-Content Resin Qualification | rHDPE and rPP streams from Rotterdam port infrastructure preempt EU Single-Use Plastics Directive penalties. |
| Smart Dispensing Technology Integration | RFID-enabled caddies capture premium positioning in healthcare facility management contracts. |
| Direct Procurement Channel Development | Bypassing distributors aligns with group purchasing organization consolidation in North American hospitality. |
| Extended Producer Responsibility Infrastructure | Take-back systems in California and New York secure first-mover advantage under emerging state frameworks. |
Research Methodology
Direct dialogue with polymer compounding chemists, injection molding operations managers, facility management procurement directors, and brand owner sustainability officers grounded qualitative insights. Secondary validation drew from ECHA SVHC candidate list updates, EPA 40 CFR Part 59 filings, EU Single-Use Plastics Directive implementation guidance, and municipal waste hauler contract specifications. Bottom-up segment sizing triangulated against top-down market envelope checks.
Top-down macroeconomic drivers and bottom-up capacity-by-facility analysis converged across the projection horizon. Segmentation modeled material grade tiers, application channels, capacity formats, and regional regulatory clusters. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends. Forecast inputs incorporated rPET/rHDPE feedstock price volatility assumptions and EPR implementation pace scenarios.
The model holds under stable REACH certification timelines and gradual EPR phase-in; deviation in polymer stabilizer substitution mandates or sudden feedstock supply disruptions would shift trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Gusseted Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Trash Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Piping Bags Market
Bags and Containers
Slider Bags Market