
 Bag-On-Valve Laminates Market | 2026-2036
Bag-On-Valve Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Bag-On-Valve Laminates Market Analysis
Asset-light leasing arrangements for high-barrier film extrusion equipment are reshaping competitive entry in bag-on-valve laminates. Aptar Group leverages captive aluminum sourcing to sustain margin control across European pharmaceutical contracts. Amcor plc anchors its position through backward integration into ethylene vinyl alcohol copolymer resin supply. Lindal Group specializes in multilayer lamination for compressed gas propellant systems, competing on seal integrity under pressure cycling.
Bag-on-valve laminates constitute multilayer flexible structures—typically aluminum foil bonded to polyethylene, polypropylene, or polyethylene terephthalate films via polyurethane adhesives—that form collapsible inner bags within rigid aerosol cans, enabling complete product evacuation without propellant contamination. These structures achieve oxygen transmission rates below 0.1 cc per square meter per day, satisfying oxygen-sensitive pharmaceutical and cosmetic formulations. The aerosol product type dominates current laminate consumption due to established filling infrastructure and consumer familiarity, though airless technology applications are expanding fastest as brands eliminate hydrocarbon propellants. Cosmetics and pharmaceuticals together occupy the deepest margin pools, with household applications remaining price-competitive through thinner gauge constructions.
REACH restricts certain phthalate plasticizers in laminate adhesives across Europe, while FDA 21 CFR 177.1390 governs laminate food-contact compliance in the United States; both frameworks elevate testing costs but advantage suppliers with pre-certified material platforms. The EU Green Deal's packaging waste directives are pressuring single-use aerosol formats, redirecting R&D toward recyclable mono-material laminates. Stakeholders must monitor polymer recycling infrastructure development and propellant phase-out timelines to align capacity investments with regulatory trajectory.
Market Dynamics
Propellant phase-out mandates are compressing laminate development cycles as brands race to validate compressed gas and mechanical pump alternatives before hydrocarbon bans take effect in core European markets.
Growth Catalysts
- EU MDR sterility requirements:Pharmaceutical packaging specifications now mandate oxygen transmission rates below 0.1 cc per square meter per day, accelerating qualification of high-barrier aluminum-polymer laminates for inhalable drug delivery.
- Germany's precision aerosol corridor:Concentrated filling infrastructure around Stuttgart and Frankfurt enables rapid prototype-to-production scaling for laminate suppliers serving pharmaceutical contract manufacturers.
- Ethylene vinyl alcohol copolymer advances:Improved coextrusion compatibility with polyethylene terephthalate films is extending shelf life for oxygen-sensitive cosmetic serums without aluminum foil layers.
Market Restraints
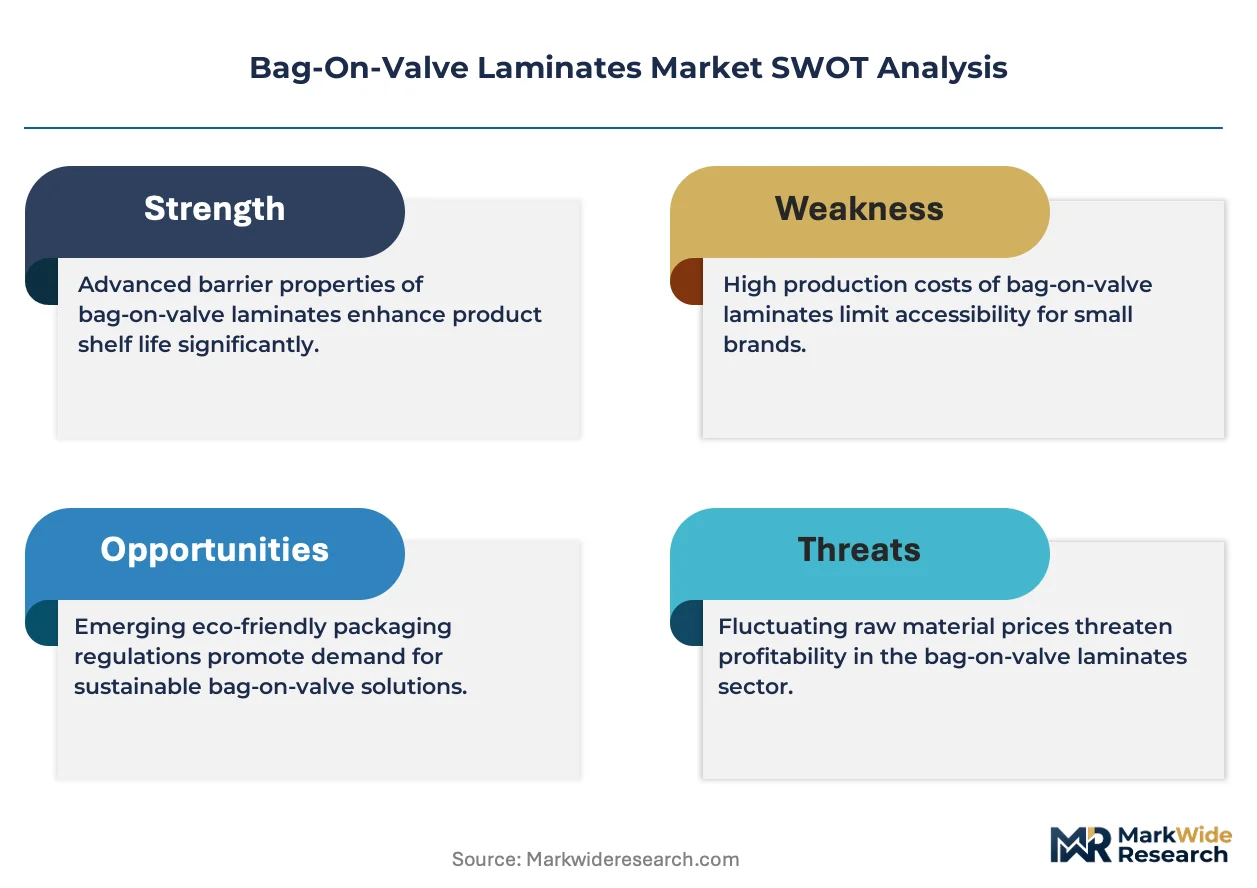
- Aluminum foil supply concentration:European rolling mill capacity concentrates in Germany and France, exposing laminate converters to energy cost volatility and allocation risk during peak pharmaceutical contract seasons.
- Polyurethane adhesive certification delays:REACH substance evaluation timelines for isocyanate-based chemistries extend qualification periods by 8-14 months for new laminate constructions.
- Pump spray substitution:Mechanical airless systems eliminate propellant compatibility requirements entirely, threatening laminate demand in mid-tier cosmetic applications where barrier performance is secondary.
Strategic Opportunities
- India's pharmaceutical export expansion:CDSCO alignment with ICH Q1 stability guidelines creates demand for validated barrier packaging among Mumbai and Hyderabad formulation houses targeting EU markets.
- EU Green Deal packaging waste directives:Recyclable mono-material laminate mandates redirect R&D spending toward polyethylene-only constructions compatible with existing film recycling streams.
- Compressed gas propellant convergence:Nitrous oxide and carbon dioxide system validation requires multilayer laminates with enhanced seal integrity under pressure cycling, opening premium specification tiers.
Industry Challenges
- Multilayer coextrusion technician scarcity:Specialized die design and layer thickness control expertise concentrates among aging workforces in German and Swiss film extrusion facilities.
- Legacy filling line retrofit complexity:Crimp diameter and seam geometry incompatibilities between traditional bag-on-valve and next-generation compressed gas formats force parallel qualification campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag-On-Valve Laminates Market |
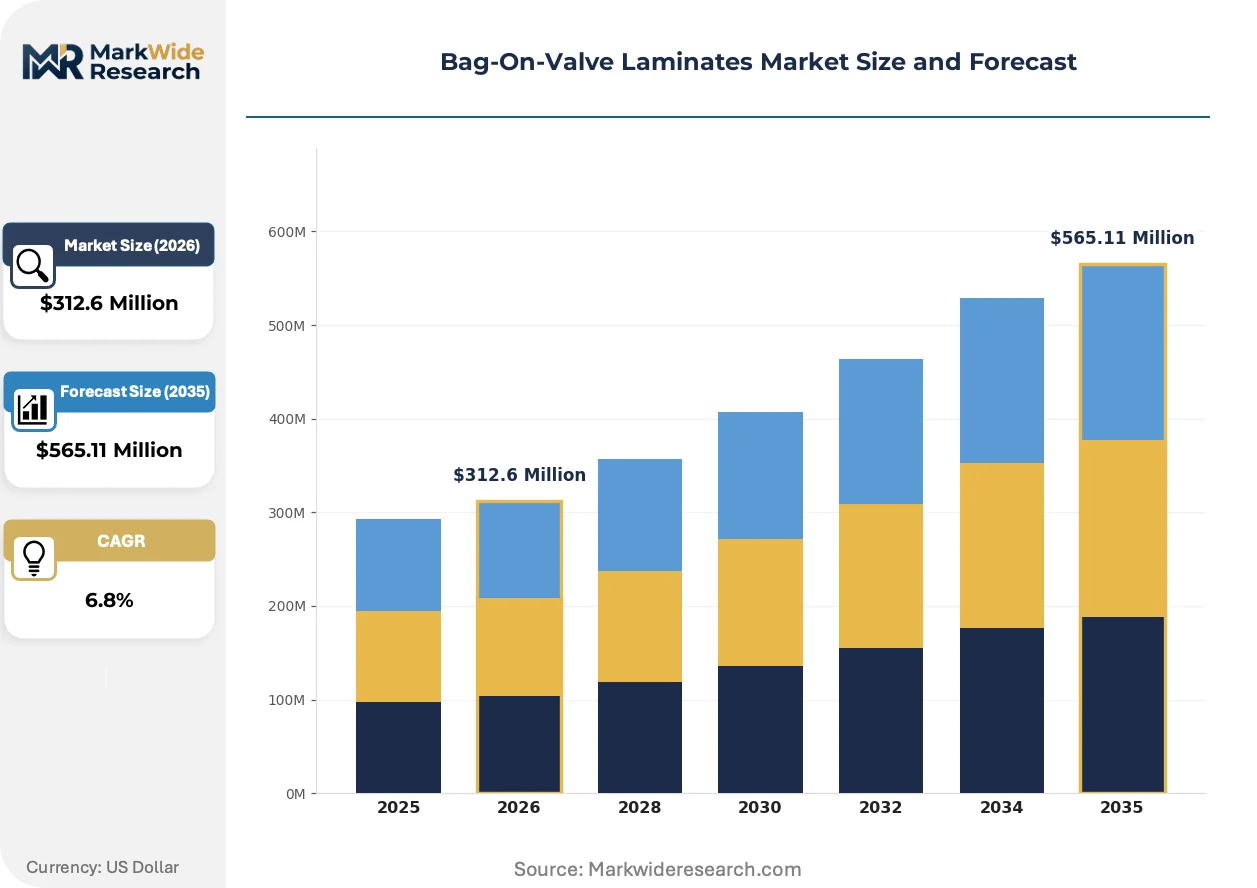
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Pump, Spray, Dispensing Application: Cosmetics, Pharmaceuticals, Household, Food & Beverage End User: Manufacturers, Retailers, Distributors, Consumers Technology: Electrostatic Spray, Airless Technology, Compressed Gas, Mechanical |
| Companies Covered | Aptar Group, Amcor plc, Precision Valve Corporation, Lindal Group, TUNAP Group, Summit Packaging Systems, Gualapack S.p.A., Coster Tecnologie Speciali S.p.A., Wipf Doypak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag-On-Valve Laminates Market Emerging Trajectories
Laminate architecture is diverging along propellant compatibility lines as compressed gas systems demand fundamentally different seal and flex-crack resistance profiles than legacy hydrocarbon formats.
Aluminum-polymer hybrid laminates are migrating from standard three-layer constructions toward five- and seven-layer coextrusions incorporating ethylene vinyl alcohol and polyamide tie layers. Pharmaceutical contract manufacturers in Germany and Switzerland are qualifying these structures for oxygen-sensitive biologics. This migration from simpler formats is compressing development timelines and forcing laminate suppliers to maintain parallel product platforms.
REACH restrictions on phthalate plasticizers in polyurethane adhesives are eliminating certain legacy chemistries from European pharmaceutical packaging supply chains. Laminate converters must reformulate bonding layers while maintaining peel strength and aging performance. Cosmetic applications face less stringent ECHA scrutiny, creating a two-speed compliance environment across end-use segments.
Brand procurement teams are consolidating laminate suppliers to reduce qualification burden and secure volume commitments for compressed gas transition programs. Direct contracting between pharmaceutical marketers and film extruders is displacing distributor-mediated purchasing in Germany and France. This concentration is most visible among mid-scale generic drug manufacturers seeking packaged stability data packages for EU MDR submissions.
Bag-On-Valve Laminates Market Segmentation
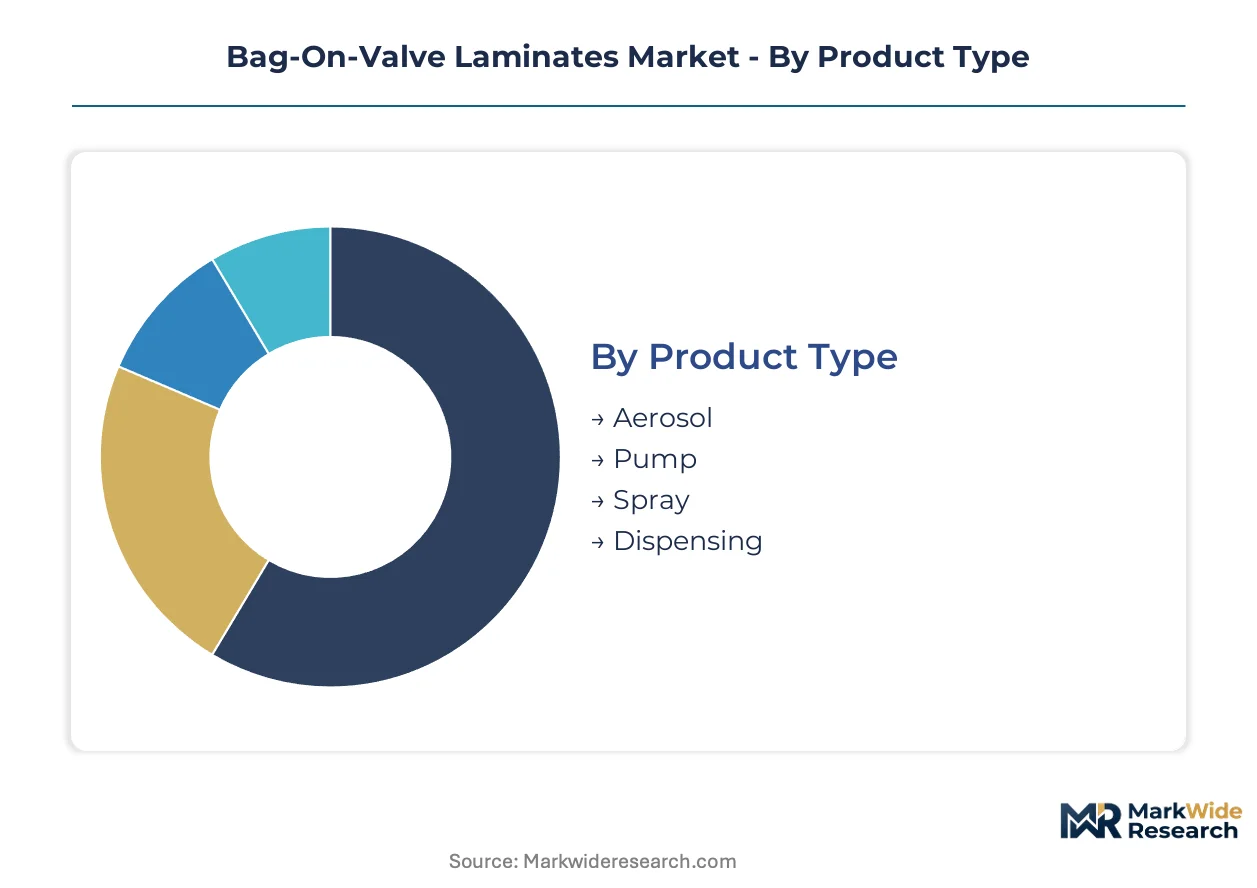
Bag-on-valve laminate specifications diverge sharply across propellant systems and barrier requirements, forcing suppliers to maintain parallel qualification tracks for pharmaceutical sterility versus cosmetic convenience. Segment boundaries are hardening as EU MDR compliance costs fragment the supplier base between certified pharmaceutical specialists and commodity cosmetic converters.
Product Type:
Aerosol and compressed gas systems span distinct pressure regimes, seal geometries, and flex-crack resistance profiles that dictate laminate architecture choices.
- Aerosol:Hydrocarbon propellant compatibility demands aluminum-polymer multilayers with polyurethane adhesive bonding, achieving oxygen transmission rates below 0.1 cc per square meter per day. German pharmaceutical contract manufacturers around Stuttgart anchor demand for these high-barrier constructions as EU MDR sterility mandates tighten.
- Pump:Mechanical actuation eliminates propellant compatibility requirements entirely, permitting thinner gauge laminates with reduced aluminum foil content. Mid-tier cosmetic brands in France are migrating toward pump formats to bypass REACH adhesive certification delays.
- Spray:Fine mist generation requires controlled bag collapse rates, typically served by polyethylene-polypropylene bilayers with tailored stiffness gradients.
- Dispensing:Viscous product evacuation demands enhanced seam integrity under repeated compression cycles, favoring polyamide tie layer constructions.
The dominant share belongs to Aerosol, while Compressed Gas (within Technology) is closing the gap fastest.
Application:
Margin pools stratify by regulatory burden, with pharmaceutical and cosmetic end-uses commanding premium specifications against price-competitive household segments.
- Cosmetics:Oxygen-sensitive serums and natural formulations drive adoption of ethylene vinyl alcohol copolymer coextrusions, particularly for airless technology transitions eliminating hydrocarbon propellants. Swiss and German prestige brands are qualifying five-layer laminates for extended shelf life claims.
- Pharmaceuticals:Inhalable drug delivery and sterile barrier packaging mandate aluminum-polymer hybrids with documented aging performance under ICH Q1 stability guidelines. Mumbai and Hyderabad formulation houses targeting EU markets are accelerating validation programs for these constructions.
- Household:Cleaning and care products tolerate thinner gauge constructions with reduced barrier performance, sourced through distributor-mediated channels.
- Food & Beverage:FDA 21 CFR 177.1390 compliance requirements elevate testing costs, restricting viable supplier pools for edible oil and condiment dispensing applications.
Cosmetics commands the largest revenue pool, though Pharmaceuticals is expanding most quickly on regulatory tailwinds.
End User:
Procurement authority is consolidating upstream as direct contracting between pharmaceutical marketers and film extruders displaces traditional distributor relationships.
- Manufacturers:Pharmaceutical contract manufacturers in Germany and Switzerland now require packaged stability data packages for EU MDR submissions, forcing laminate suppliers to invest in analytical capabilities. This segment concentrates purchasing power through multi-year volume commitments.
- Retailers:Private label cosmetic brands are consolidating supplier bases to reduce qualification burden, favoring converters with pre-certified REACH adhesive platforms.
- Distributors:Price-competitive household and industrial applications remain their core volume, though margin compression is accelerating disintermediation.
- Consumers:Direct purchasing is negligible for laminate materials, though end-user preferences for sustainable packaging are transmitting upstream through brand sustainability mandates.
Manufacturers hold decisive procurement leverage, while Retailers are gaining negotiating power fastest through supplier consolidation programs.
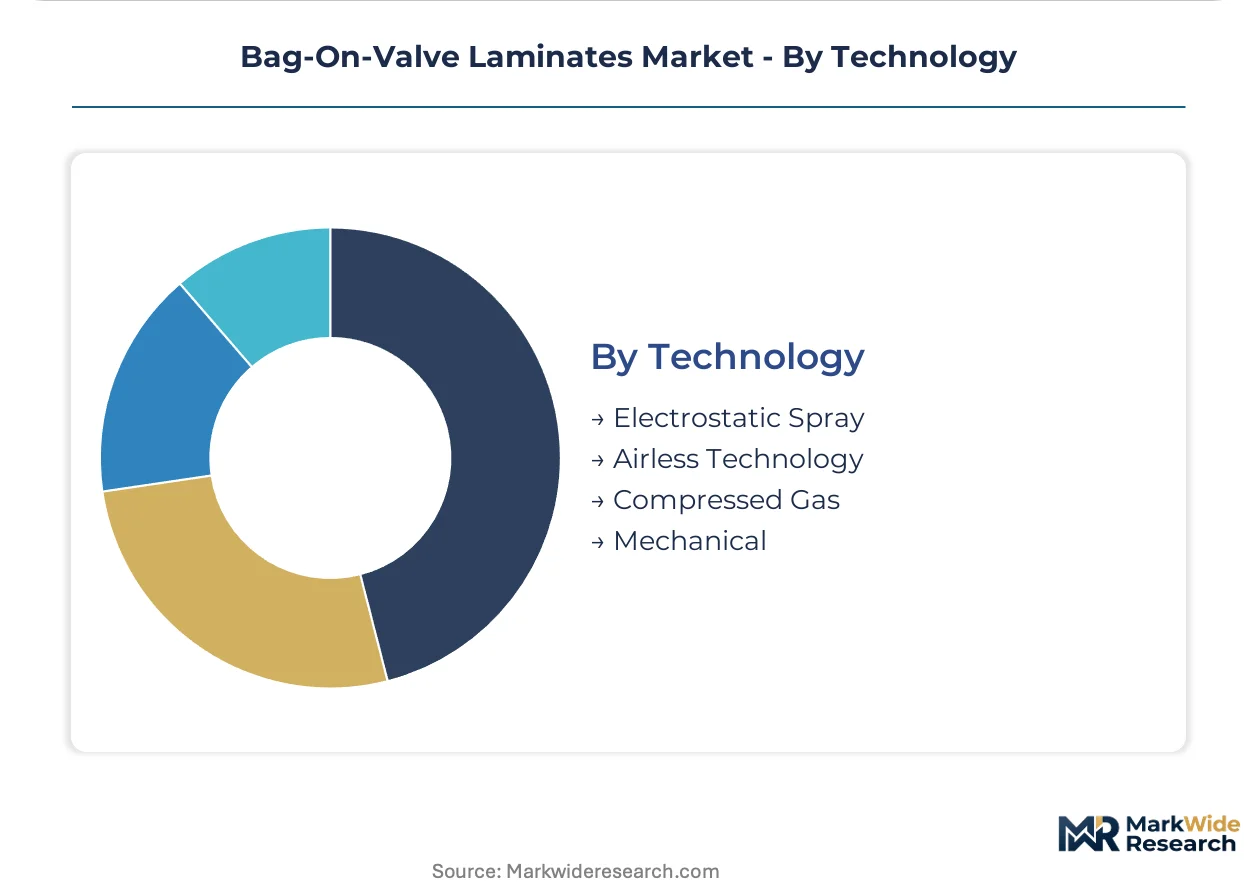
Technology:
Propellant phase-out timelines are compressing development cycles as brands validate alternatives before hydrocarbon bans take effect in core European markets.
- Compressed Gas:Nitrous oxide and carbon dioxide systems demand multilayer laminates with enhanced seal integrity under pressure cycling and thermal expansion. Lindal Group's specialized lamination expertise targets this premium specification tier.
- Airless Technology:Mechanical pump elimination of propellants permits mono-material polyethylene constructions aligned with EU Green Deal recycling directives. This format is climbing fastest as brands seek to satisfy packaging waste regulations.
- Electrostatic Spray:Charged particle deposition requires controlled surface resistivity in laminate films, a niche specification with limited qualified suppliers.
- Mechanical:Simple squeeze-tube alternatives bypass bag-on-valve complexity entirely, threatening laminate demand in low-barrier cosmetic applications.
Compressed Gas captures the premium specification tier, though Airless Technology is gaining share fastest on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers in Germany and Switzerland concentrate purchasing power through multi-year volume commitments, while cosmetic brands in France and the United States consolidate supplier bases to reduce qualification burden.
Germany
Stuttgart and Frankfurt host precision aerosol manufacturing corridors where pharmaceutical contract manufacturers demand packaged stability data packages for EU MDR submissions. REACH restrictions on phthalate plasticizers in polyurethane adhesives extend qualification periods for new laminate constructions. Bavaria's film extrusion facilities concentrate specialized die design expertise among aging workforces.
Switzerland
Swissmedic sterility requirements for inhalable drug delivery mandate oxygen transmission rates below 0.1 cc per square meter per day, accelerating qualification of high-barrier aluminum-polymer hybrids. Prestige cosmetic brands in Geneva and Zurich are qualifying five-layer laminates for extended shelf life claims. Basel's pharmaceutical cluster drives demand for validated barrier packaging with documented aging performance under ICH Q1 stability guidelines.
France
Mid-tier cosmetic brands migrate toward pump formats to bypass REACH adhesive certification delays, though compressed gas propellant convergence requires multilayer laminates with enhanced seal integrity. ANSM pharmaceutical packaging specifications align with EU MDR sterility mandates. The Lyon-Grenoble corridor concentrates laminate converter capacity serving fragrance and personal care applications.
United States
FDA 21 CFR 177.1390 governs laminate food-contact compliance, elevating testing costs but advantaging suppliers with pre-certified material platforms. New Jersey and Pennsylvania host filling infrastructure for pharmaceutical aerosol applications. California's cosmetic brands transmit sustainability mandates upstream, pressuring mono-material polyethylene constructions compatible with existing film recycling streams.
India
CDSCO alignment with ICH Q1 stability guidelines creates demand for validated barrier packaging among Mumbai and Hyderabad formulation houses targeting EU markets. Pharmaceutical export expansion accelerates as domestic manufacturers seek EU MDR compliance for inhalable drug delivery. Gujarat's chemical processing corridor supplies polymer raw materials to laminate converters serving contract manufacturing organizations.
Bag-On-Valve Laminates Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base stratifies between pharmaceutical-certified specialists and commodity cosmetic converters, with segment boundaries hardening as EU MDR compliance costs fragment participation. Three archetypes dominate: backward-integrated resin suppliers, captive aluminum sourcers, and multilayer lamination specialists. Competitive moves concentrate on strategic partnerships for compressed gas validation and capacity expansion in Germany's precision aerosol corridor.
Within the pharmaceutical-certified tier, Aptar Group and Amcor plc exemplify divergent sourcing strategies. Aptar leverages captive aluminum supply relationships to sustain margin control across European contracts. Amcor anchors positioning through upstream control over ethylene vinyl alcohol copolymer resin. Lindal Group occupies a specialist position in multilayer lamination for pressure-cycling applications. These three represent the dominant competitive archetypes: material-integrated, resin-integrated, and process-specialized.
| Leading Market Players |
|---|
| Aptar Group |
| Amcor plc |
| Precision Valve Corporation |
| Lindal Group |
| TUNAP Group |
| Summit Packaging Systems |
| Gualapack S.p.A. |
| Coster Tecnologie Speciali S.p.A. |
| Wipf Doypak |
| Others |
Supply Flow & Price Mechanics
Stuttgart's precision aerosol manufacturing corridor concentrates pharmaceutical contract manufacturing capacity, translating upstream laminate supply tightness into sustained pricing power for certified converters serving EU MDR compliance programs. REACH adhesive certification delays and aluminum foil allocation risk during peak contract seasons amplify cost pass-through to downstream buyers.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and cosmetic-grade laminates. Three-tier pricing structure across premium, standard, and economy levels segments by barrier performance, with oxygen transmission rates below 0.1 cc per square meter per day commanding substantial premiums. Cost compression in mid-tier cosmetic applications is intensifying because pump spray substitution eliminates propellant compatibility requirements entirely. Household product manufacturers exhibit highest price sensitivity, while German pharmaceutical contract manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Pharmaceutical contract manufacturers in Germany and Switzerland hold decisive capacity for high-barrier laminate qualification and volume commitment. Raw material flows draw from Bavarian film extrusion facilities, French aluminum rolling mills, and Belgian polyurethane adhesive suppliers. Single-source vulnerability concentrates in specialized multilayer coextrusion die design expertise among aging German and Swiss workforces. Distribution runs through direct contracting between pharmaceutical marketers and film extruders, displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bag-on-valve laminates sit in early-cycle expansion as compressed gas propellant convergence and EU MDR sterility mandates accelerate qualification demand for high-barrier constructions. Penetration remains shallow outside German and Swiss pharmaceutical corridors.
For Market Incumbents: Build regulatory certification moats by securing REACH-compliant adhesive platforms and ICH Q1 stability documentation capabilities before hydrocarbon propellant bans tighten. Prioritize capacity addition in Stuttgart-Frankfurt corridor to capture pharmaceutical contract manufacturing consolidation. Defend against pump spray substitution threat by embedding laminate suppliers early in compressed gas validation programs.
For New Entrants and Emerging Players: Build out airless technology laminate capabilities targeting California cosmetic brands transmitting sustainability mandates upstream. India's pharmaceutical export expansion offers the most penetrable geography, with Mumbai and Hyderabad formulation houses seeking EU MDR-compliant barrier packaging. Go-to-market through packaged stability data partnerships with contract manufacturing organizations accelerates qualification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-certified laminate converters with multi-year volume commitments from German contract manufacturers. Long-term viability hinges on positioning for compressed gas propellant transition and mono-material recyclability mandates. Target acquisition archetype: specialized multilayer lamination players with pressure-cycling expertise. Monitor EU Green Deal packaging waste directive implementation timelines as inflection signal for recyclable laminate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin Supply | Amcor plc's upstream control secures margin stability across oxygen-sensitive cosmetic formulations. |
| Compressed Gas System Validation Partnership | Lindal Group's seal integrity expertise captures premium specification tiers in nitrous oxide propellant transition. |
| REACH-Compliant Adhesive Platform Certification | Pre-certified polyurethane bonding layers reduce qualification periods for EU MDR pharmaceutical submissions. |
| Mono-Material Polyethylene Construction R&D | EU Green Deal alignment positions converters for recyclable laminate mandates in cosmetic airless applications. |
| Direct Contracting with Pharmaceutical CMs | Bypassing distributor mediation secures multi-year volume commitments and packaged stability data revenue streams. |
Methodological Framework
Initial hypotheses were tested against primary input from laminate converters, pharmaceutical contract manufacturing procurement leads, multilayer film extrusion engineers, and REACH regulatory consultants, then refined through secondary validation. Primary fieldwork encompassed structured interviews across German precision aerosol corridors and Swiss pharmaceutical clusters. Secondary sources included ECHA substance evaluation databases, EU MDR technical documentation requirements, SEC filings from listed packaging suppliers, and trade flow data from European aluminum rolling associations. Bottom-up capacity modeling and top-down demand segmentation were triangulated for convergence.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed propellant system type, barrier performance tier, end-use regulatory burden, and regional compliance cluster. CAGRs were derived from installed filling line capacity expansion plans and propellant phase-out timeline elasticity. Industry-specific forecast inputs incorporated ICH Q1 stability guideline adoption rates and EU Green Deal packaging waste directive implementation pacing.
Stress conditions across aluminum foil energy cost volatility, REACH adhesive certification timeline extension, and compressed gas propellant validation failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and technology substitution elasticity. Quarterly review of EU MDR submission volumes and propellant transition program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Piping Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
Leno Bags Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
MSW Bag Opener Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Side Weld Bags Market