
 Bulk Bag Unloaders Market | 2026-2036
Bulk Bag Unloaders Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Bag Unloaders Market Outlook
Automation integration with PLC-controlled discharge mechanisms is tilting engineering priorities toward precision flow control and dust containment. Flexicon leverages vertical integration across its conveyor and unloader portfolios to capture repeat orders from multinational food processors. Hapman anchors its position through specialized tubular drag conveyor pairings that extend system value beyond standalone unloading. Dynamic Air competes on pneumatic conveying integration, offering turnkey packages that reduce interface risk for chemical plant operators.
Bulk bag unloaders are industrial material handling systems designed to discharge granular, powder, or pelletized products from flexible intermediate bulk containers with controlled flow rates, typically incorporating agitation frames, spout clamping mechanisms, and dust collection interfaces to maintain containment below permissible exposure limits. Their primary purpose centers on transferring bulk materials into downstream process equipment—mixers, extruders, reactors, or packaging lines—while minimizing product loss and operator exposure. Automated unloaders lead the product type category due to labor cost pressures and batch consistency requirements in pharmaceutical applications, while vacuum unloaders represent the fastest-growing segment as hygroscopic and toxic material handling protocols tighten across chemical manufacturing. Stationary installations dominate the installation type landscape, though integrated configurations command premium positioning by eliminating transfer points and reducing contamination risk in food-grade environments.
OSHA enforces permissible exposure limits for respirable dust that directly shape unloader specification requirements in US manufacturing facilities, particularly in chemical and construction material processing. The EPA's National Emission Standards for Hazardous Air Pollutants further constrain venting designs, pushing OEMs toward sealed spout interfaces and negative-pressure containment systems. In Europe, ATEX directives and REACH compliance obligations compound engineering complexity for equipment serving solvent-laden or explosive dust applications. Stakeholders must weigh total cost of ownership against regulatory retrofit timelines when evaluating equipment replacement cycles and supplier qualification criteria.
Market Dynamics
OSHA dust exposure enforcement and ATEX compliance mandates are compressing replacement cycles for manual handling equipment, forcing chemical processors toward sealed containment architectures that eliminate operator exposure points.
Growth Catalysts
- OSHA permissible exposure limits:US chemical manufacturers face stepped-up respirable dust enforcement, accelerating capital allocation toward negative-pressure unloader systems with integrated dust collection interfaces.
- Continuous processing adoption:Pharmaceutical batch operations in Germany's chemical corridor are converting to 24/7 discharge configurations, driving demand for automated agitation frames and PLC-controlled flow modulation.
- Toxic material handling protocols:Hygroscopic and solvent-laden powder processing across specialty chemical applications is expanding specification requirements for vacuum-assisted discharge mechanisms with nitrogen purging capability.
Market Restraints
- Stainless steel input volatility:Food-grade and pharmaceutical unloader fabrication depends on 304/316L sheet and tubular components, with mill lead times extending procurement cycles for OEMs.
- Component supply concentration:Precision pneumatic valves and explosion-proof actuators for ATEX-rated equipment concentrate among German and Italian suppliers, creating single-source vulnerability for North American fabricators.
- REACH compliance friction:European chemical processors face extended equipment qualification timelines as OEMs document material composition and surface treatment compliance across full supply chains.
Strategic Opportunities
- Modular retrofit architectures:Existing manual unloader installations across US Midwest chemical plants present upgrade pathways through drop-in automation kits that preserve structural frames while adding sealed spout interfaces.
- ATEX Zone 20/21 expansion:Solvent recovery and battery material processing operations are extending explosion protection requirements into previously unclassified powder handling environments.
- Converged weighing and discharge:Integration of gravimetric loss-in-weight feeding with bulk bag discharge is compressing transfer points and enabling direct reactor loading in pharmaceutical synthesis operations.
Industry Challenges
- Controls engineering scarcity:PLC programming and hazardous area electrical design expertise for integrated dust collection and pneumatic conveying systems remains concentrated among specialized system integrators.
- Legacy equipment interface complexity:Brownfield chemical plants require custom mechanical and control adaptations to connect modern sealed unloaders with existing downstream mixers and extruders from disparate vintage equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Bag Unloaders Market |
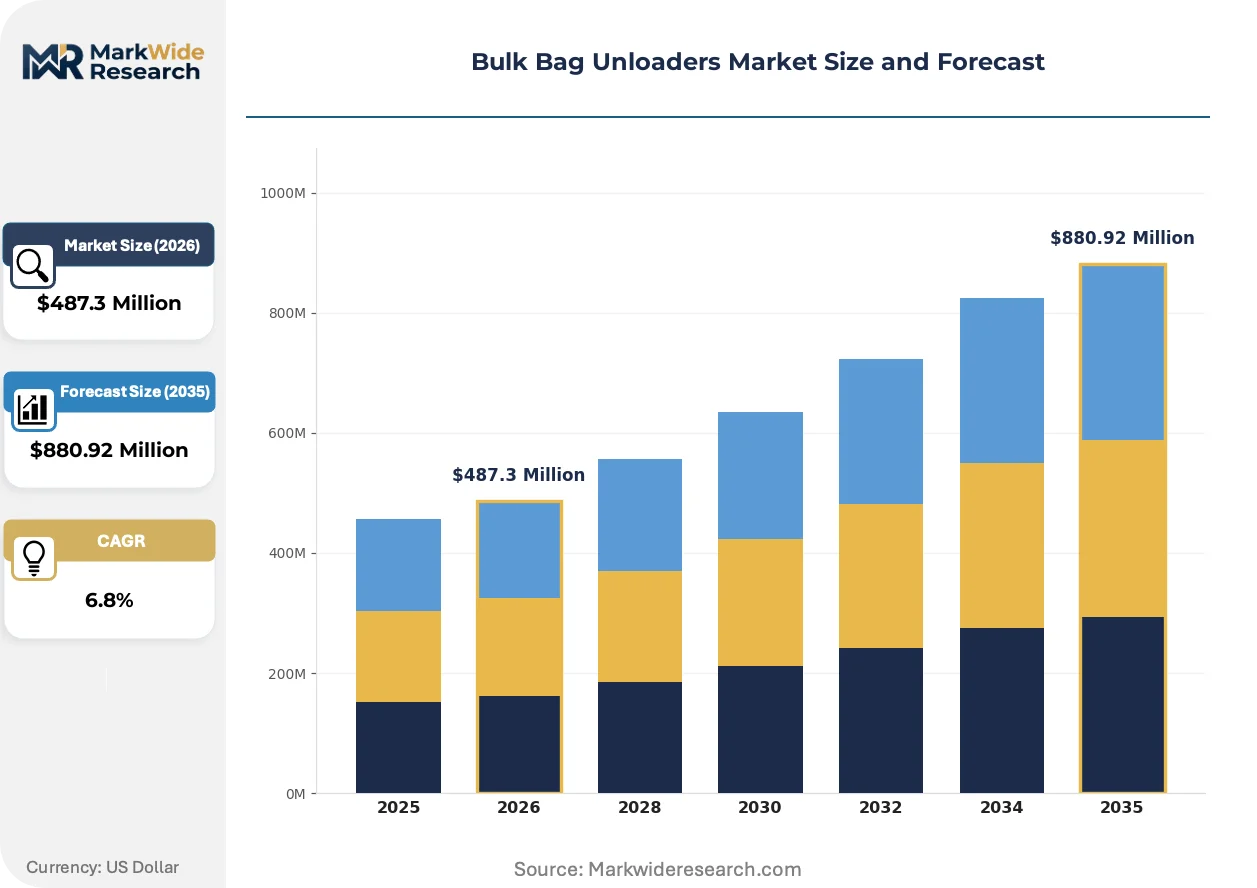
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Unloaders, Automated Unloaders, Vacuum Unloaders, Gravity Unloaders End User: Food Industry, Pharmaceutical, Chemicals, Construction Installation Type: Stationary, Portable, Integrated, Standalone Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | APEC, Palmetto Industries, Hapman, Acrison, FormPak, Dynamic Air, Flexicon, Airmatic, Metalfab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Bag Unloaders Market Strategic Shifts
Equipment architecture is converging around closed-loop containment systems that eliminate open powder transfer, with engineering priorities shifting toward real-time flow monitoring and predictive maintenance integration.
Pneumatic conveying integration with bulk bag discharge is hybridizing traditional material handling boundaries. Chemical plant operators in the US Gulf Coast region are specifying turnkey packages that combine vacuum unloading with dense-phase transfer to reactors, collapsing multiple equipment procurement decisions into single-source accountability. This convergence compresses interface risk and accelerates commissioning timelines for greenfield installations.
REACH and ATEX directive harmonization is reshaping equipment documentation requirements. European OEMs must now certify surface coatings, lubricants, and elastomeric seals for chemical compatibility and explosive atmosphere suitability across unified technical files. Specialty chemical processors in Germany's Rhine-Ruhr industrial cluster are demanding extended material traceability that extends upstream to raw steel mill certificates.
Service contract unbundling is altering aftermarket revenue structures. Pharmaceutical manufacturers in Switzerland and Ireland are separating mechanical maintenance from controls calibration and validation documentation, sourcing each element through distinct qualified suppliers. This fragmentation creates opening positions for specialized controls integrators and third-party validation consultants that previously operated at equipment vendor margins.
Bulk Bag Unloaders Market Segmentation
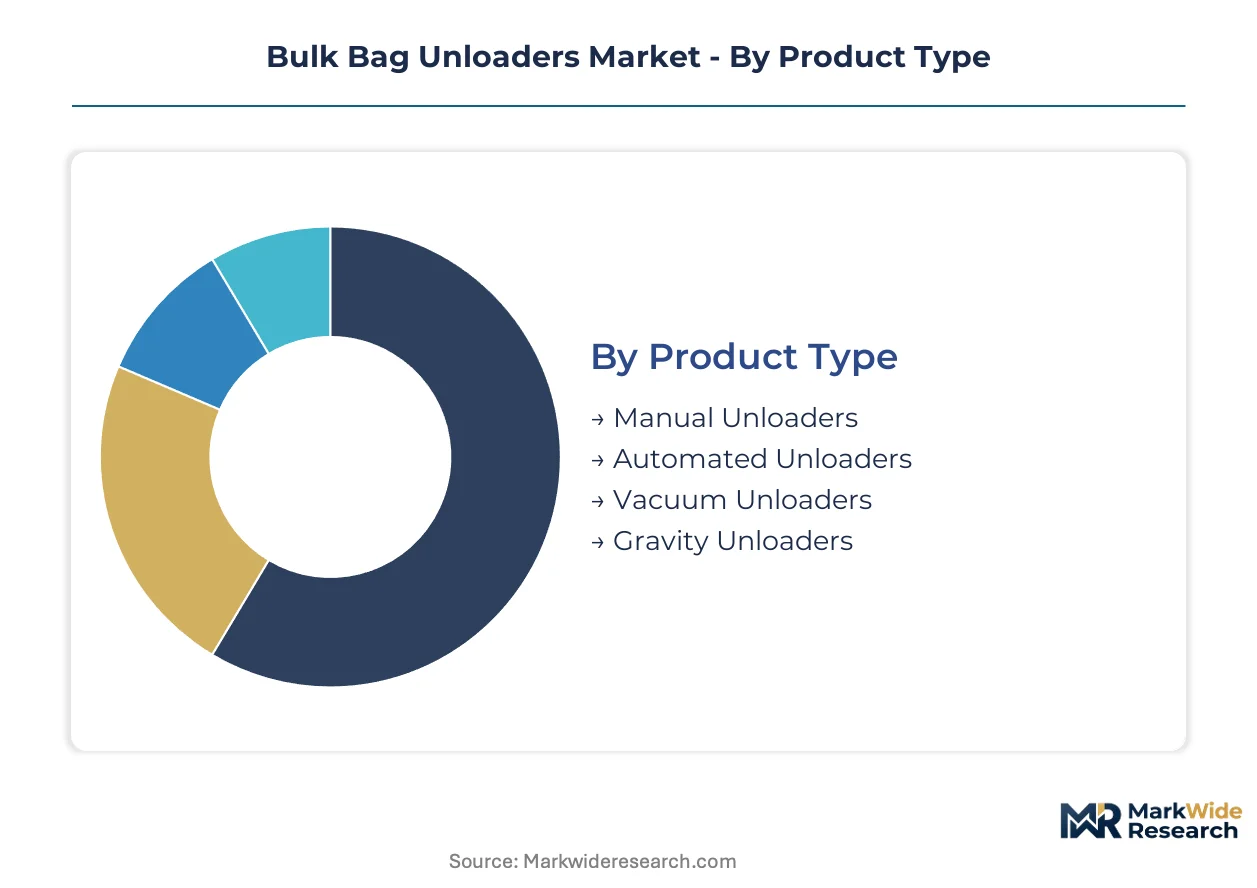
Segmentation in bulk bag unloaders reveals how engineering specifications diverge across contamination sensitivity, throughput requirements, and regulatory exposure. Equipment selection varies sharply between food-grade stainless steel configurations and chemical-resistant carbon steel alternatives.
Product Type:
Mature mechanical designs dominate installed base volumes, while emerging pneumatic and automated architectures capture specification momentum in high-containment applications.
- Automated Unloaders:PLC-controlled discharge mechanisms incorporate agitation frames and spout clamping systems for precise flow modulation. Pharmaceutical batch operations in Germany's chemical corridor specify these for 24/7 continuous processing to eliminate operator exposure points.
- Vacuum Unloaders:Negative-pressure discharge systems with nitrogen purging capability handle hygroscopic and toxic powders. Specialty chemical processors across solvent-laden applications are accelerating procurement as OSHA dust enforcement tightens permissible exposure limits.
- Manual Unloaders:Basic frame-and-spout configurations without powered components serve low-throughput construction material sites where labor costs permit operator-dependent discharge.
- Gravity Unloaders:Simple chute-based designs rely on elevation differentials for free-flowing granular products in agricultural and mineral processing operations.
Automated unloaders handle the majority of throughput; vacuum unloaders are gaining share fastest in chemical manufacturing.
End User:
Cost tiers separate capital-intensive pharmaceutical installations from price-sensitive construction material handling, with food and chemical sectors occupying intermediate specification territory.
- Chemicals:ATEX-rated equipment with explosion-proof actuators and sealed containment architectures serves solvent recovery and battery material processing. BASF and LANXESS operations in Germany's Rhine-Ruhr cluster drive specification requirements for Zone 20/21 protection.
- Pharmaceutical:316L stainless steel fabrication with surface finish documentation and validation protocols supports API synthesis and formulation operations. Swiss and Irish manufacturers separate mechanical maintenance from controls calibration through unbundled service contracts.
- Food Industry:USDA-compliant designs with quick-clean features and allergen containment address dairy, bakery, and ingredient handling across multinational processor networks.
- Construction:Carbon steel frames with basic dust collection serve cement, lime, and mineral additive discharge where regulatory exposure remains minimal.
Chemical applications absorb the largest equipment value; pharmaceutical represents the steepest expansion trajectory on regulatory retrofit timelines.
Installation Type:
Volume concentration favors permanent infrastructure, though margin structures favor integrated configurations that collapse transfer points and contamination risk.
- Stationary:Fixed-frame installations with dedicated downstream connections dominate brownfield chemical plants and high-throughput processing lines where equipment mobility provides no operational benefit.
- Integrated:Converged weighing and discharge systems compress transfer points by combining gravimetric loss-in-weight feeding with bulk bag discharge for direct reactor loading.
- Portable:Castor-mounted or forklift-compatible frames serve contract manufacturers and multi-product facilities requiring rapid redeployment between production campaigns.
- Standalone:Self-contained units with independent dust collection and control systems operate where downstream equipment from disparate vintage requires custom interface adaptation.
Stationary configurations anchor installed base volumes; integrated systems are climbing the fastest on premium positioning in food-grade environments.
Distribution Channel:
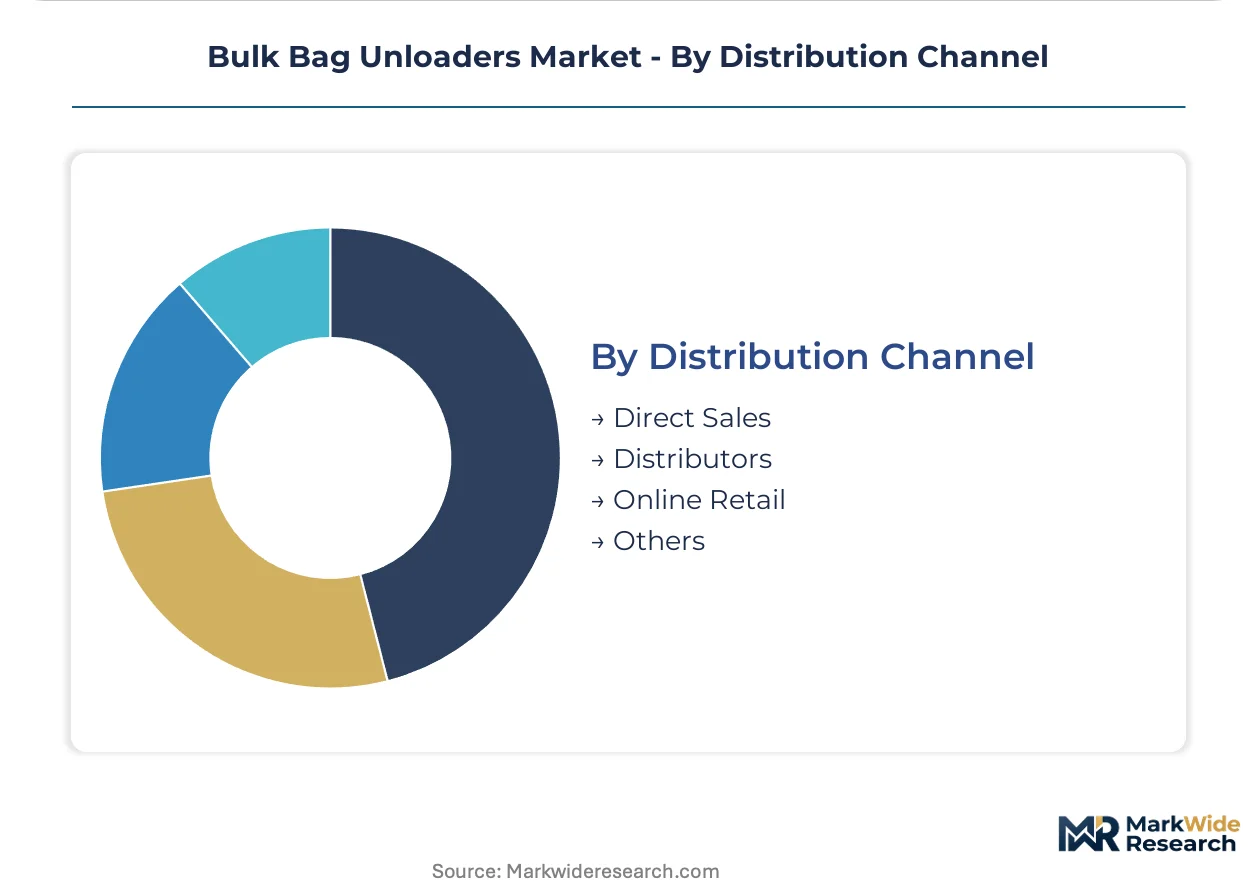
Customer type and application complexity determine channel selection, with direct relationships dominating engineered systems and distributor networks capturing standard equipment.
- Direct Sales:OEM field engineers specify integrated turnkey packages combining unloaders with pneumatic conveying for chemical plant operators seeking single-source accountability.
- Distributors:Regional stocking dealers serve maintenance-replacement markets and smaller food processors with standardized frame configurations and faster delivery timelines.
- Online Retail:E-commerce platforms capture accessory sales, spare agitation frames, and replacement dust collection components for existing installations.
- Others:System integrators and engineering-procurement-construction firms bundle unloader procurement within larger material handling infrastructure projects.
Direct sales channels command the largest transaction values; distributor networks are expanding most quickly in aftermarket replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical processors and pharmaceutical manufacturers concentrate equipment procurement in industrial corridors with stringent dust exposure enforcement. Buyers prioritize ATEX-rated and OSHA-compliant architectures in Germany, the United States, Switzerland, and Ireland.
United States
OSHA respirable dust enforcement drives chemical manufacturers toward negative-pressure containment systems with sealed spout interfaces. EPA National Emission Standards constrain venting designs, pushing fabricators toward integrated dust collection. Texas and Louisiana Gulf Coast petrochemical clusters specify turnkey packages combining vacuum unloading with dense-phase pneumatic transfer.
Germany
BASF and LANXESS operations in the Rhine-Ruhr industrial cluster demand continuous 24/7 discharge configurations with Zone 20/21 explosion protection. ATEX directives and REACH compliance obligations extend equipment qualification timelines. Bavarian pharmaceutical synthesis facilities gravitate toward gravimetric loss-in-weight feeding integrated directly with bulk bag discharge.
Switzerland
Swissmedic-regulated API manufacturers unbundle mechanical maintenance from controls calibration and validation documentation. Specialty chemical processors in Basel's pharmaceutical corridor require extended material traceability upstream to raw steel mill certificates. Precision pneumatic valve sourcing concentrates procurement attention on German and Italian component suppliers.
Ireland
Pharmaceutical manufacturers near Dublin and Cork separate service contracts into distinct qualified supplier relationships for mechanical, controls, and validation elements. IDA Ireland-supported greenfield investments specify automated agitation frames with PLC-controlled flow modulation. Contract manufacturing organizations demand portable configurations for rapid redeployment between production campaigns.
United Kingdom
Construction material processors across the Midlands and North England retain manual unloader installations where labor costs permit operator-dependent discharge. Food-grade stainless steel fabrication for dairy and bakery applications concentrates specification activity in the Southeast. Brexit-related supply friction extends procurement cycles for 304/316L sheet components.
Bulk Bag Unloaders Market Competitive Environment
Channel-controlling players compete with product-specialist players across a fragmented vendor base. Distributor networks capture standardized frame configurations in aftermarket replacement segments, while direct sales relationships dominate engineered turnkey packages. Three archetypes anchor competitive positioning: full-line material handling conglomerates, pneumatic conveying integrators, and specialized containment fabricators. M&A activity concentrates on controls engineering capabilities, and strategic partnerships with system integrators accelerate brownfield retrofit penetration.
Among US-based fabricators, Flexicon Corporation and Hapman exemplify divergent strategic vectors within the material handling segment. Flexicon anchors a position through captive supply of complementary conveyor portfolios that capture repeat orders from multinational food processors. Hapman occupies a specialist tier through tubular drag conveyor pairings that extend system value beyond standalone unloading functionality. Dynamic Air Inc. represents the pneumatic conveying integration archetype, competing on turnkey packages that collapse interface risk for chemical plant operators in the Gulf Coast region.
| Leading Market Players |
|---|
| APEC |
| Palmetto Industries |
| Hapman |
| Acrison |
| FormPak |
| Dynamic Air |
| Flexicon |
| Airmatic |
| Metalfab |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European precision pneumatic valve manufacturing is compressing lead times for ATEX-rated actuators and tilting contract negotiations toward index-linked pricing clauses that pass through stainless steel mill surcharges.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement agreements for food-grade and pharmaceutical unloader fabricators. Three-tier pricing structure across premium, standard, and economy levels separates 316L stainless steel ATEX-certified systems from carbon steel chemical-grade alternatives and basic manual frames. Pricing pressure stems from extended mill lead times for 304/316L sheet components, particularly affecting Swiss and Irish pharmaceutical manufacturers with validation-documented surface finish requirements. Construction material processors exhibit highest price sensitivity due to minimal regulatory exposure, while German chemical corridor buyers prioritize Zone 20/21 certification over unit cost.
Supply Chain Analysis
Export-control restrictions on precision motion control technology limit flows of explosion-proof servo actuators from German and Italian suppliers to North American fabricators. Component sourcing concentrates in Germany, Italy, and China, with tubular drag conveyor chains and pneumatic valve assemblies drawing from specialized European machine-tool clusters. Raw material dependencies center on 304/316L stainless steel sheet, precision-machined aluminum extrusions, and industrial-grade elastomeric seals. Single-source vulnerability pervades ATEX-rated electrical enclosures and nitrogen-purging valve manifolds. Distribution runs through OEM direct sales for engineered turnkey packages and regional distributor networks for standardized frame configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling is expanding faster than hardware shipments, with Swiss and Irish pharmaceutical manufacturers now sourcing controls calibration and validation documentation through distinct qualified suppliers rather than bundled OEM agreements.
For Market Incumbents: Harden aftermarket revenue streams by captive supply of spare agitation frames and dust collection components that lock in replacement demand. Defend against specialized controls integrators by acquiring PLC programming capabilities for hazardous area electrical design. Prioritize certification investment for REACH-compliant surface coatings and lubricants that extend material traceability upstream to raw steel mill certificates. For New Entrants and Emerging Players: US Midwest brownfield chemical plants present underpenetrated retrofit opportunities through drop-in automation kits that preserve existing structural frames. Target contract manufacturing organizations in Ireland with portable castor-mounted configurations enabling rapid redeployment between production campaigns. Enter through modular retrofit architectures that eliminate transfer points while reducing contamination risk. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across converged weighing and discharge systems as gravimetric loss-in-weight feeding integration standardizes. Five-to-ten year viability favors fabricators with backward integration into precision pneumatic valve sourcing or captive conveyor portfolio supply. Watch for OSHA enforcement intensity signals in Texas and Louisiana Gulf Coast petrochemical clusters as inflection indicators for negative-pressure containment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Valve Sourcing | Mitigates single-source vulnerability from German and Italian component suppliers for ATEX-rated equipment. |
| Modular Retrofit Architecture Development | Captures upgrade pathways across US Midwest chemical plants without requiring full equipment replacement. |
| Gravimetric Loss-in-Weight Feeding Integration | Compresses transfer points for direct reactor loading in Bavarian pharmaceutical synthesis operations. |
| REACH-Compliant Surface Treatment Certification | Extends equipment qualification timelines but locks out competitors lacking full supply chain documentation. |
| Controls Engineering Capability Acquisition | Addresses scarcity in PLC programming expertise for integrated dust collection and pneumatic conveying systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from material handling conglomerates, and OSHA enforcement action databases. Plant engineers, procurement leads at chemical processors, aftermarket service heads, and technical R&D directors at OEMs provided operational perspectives. Bottom-up unit economics triangulate against top-down sector expenditure patterns from Cefic and ACC chemical industry reports.
Forecast inputs incorporate product type segmentation by automation level, installation type by mobility configuration, and end-use industry by regulatory exposure tier. Modeled dimensions span containment architecture, downstream integration depth, and regional enforcement intensity across the projection horizon. CAGRs derive from trajectory analysis of capital expenditure cycles and replacement timeline compression under tightened dust exposure limits.
Practitioners should monitor OSHA respirable dust enforcement intensity, ATEX directive harmonization timelines, and stainless steel mill capacity utilization for early signals of forecast deviation. Material shifts in REACH compliance documentation requirements or export-control restrictions on precision motion control technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Compression Bags Market
Bags and Containers
Slider Bags Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Counter Bags Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Type-C Bulk Bags Market