
 Packaging Peanuts Market | 2026-2036
Packaging Peanuts Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Peanuts Market Analytics
Asset-light leasing models for protective packaging equipment are narrowing the capital barrier for mid-sized fulfillment operators seeking automated loose-fill systems. Sealed Air leverages its global manufacturing footprint to sustain volume leadership across multiple regions. Ranpak specializes in paper-based cushioning technologies that compete directly with conventional peanut formats. Uline anchors North American distribution through extensive catalog and direct-ship channel control.
Packaging peanuts are engineered void-fill materials, typically manufactured from expanded polystyrene resin or biodegradable starches, designed to cushion fragile goods during transit by absorbing shock and preventing item migration within shipping containers. The product serves essential protective functions across e-commerce fulfillment, industrial parts distribution, and consumer electronics shipping workflows. Biodegradable variants are capturing the fastest expansion trajectory as corporate sustainability mandates displace expanded polystyrene demand. The e-commerce end-user segment concentrates the largest volume pull, though electronics applications sustain premium pricing for anti-static formulations. Distribution through wholesale channels dominates bulk procurement patterns, while online ordering is gaining share among smaller fulfillment operations.
The EPA regulates expanded polystyrene manufacturing emissions under Clean Air Act provisions, while the EU Green Deal and F-Gas Regulation constrain hydrocarbon blowing agent use in foam production. These frameworks elevate compliance costs for conventional peanut manufacturers while creating preferential market access for biodegradable and paper-based alternatives. Stakeholders must monitor evolving extended producer responsibility schemes and material bans to align product portfolios with tightening waste management requirements.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for expanded polystyrene peanuts while starch-based and paper alternatives capture displaced volume across European fulfillment networks.
Growth Catalysts
- E-commerce order velocity:Fulfillment centers handling fragile goods require reliable void-fill systems that prevent damage during last-mile transit. Automated loose-fill dispensing equipment is penetrating mid-sized operations previously limited to manual packing stations.
- REACH chemical restrictions:The European Chemicals Agency's evolving substance restrictions are elevating compliance costs for hydrocarbon-blown foam production. Manufacturers are redirecting capital toward biodegradable starch fermentation capacity.
- Anti-static formulations:Electronics shippers demand conductive peanut variants that dissipate electrostatic discharge. Premium pricing for these specialized grades sustains margin pools unavailable in commodity loose-fill segments.
Market Restraints
- Feedstock cost volatility:Corn and potato starch prices fluctuate with agricultural commodity cycles. Biodegradable peanut margins compress when grain markets spike.
- Chinese polystyrene resin concentration:Global supply of expandable polystyrene beads depends on concentrated Asian petrochemical capacity. Geopolitical friction or shipping disruptions transmit rapidly downstream.
- Compression resistance limits:Starch-based peanuts absorb moisture and lose cushioning performance in humid climates. This technical constraint blocks adoption in tropical logistics corridors.
Strategic Opportunities
- German packaging waste enforcement:The country's strictest extended producer responsibility schemes in Europe are forcing brand owners to eliminate non-recyclable protective materials. Local starch peanut producers gain preferential access.
- Direct-to-consumer subscription boxes:Curated unboxing experiences favor aesthetically neutral, dye-free cushioning. Paper-based interleaving and molded pulp formats are penetrating this channel.
- Closed-loop return systems:Reusable peanut collection infrastructure at parcel lockers and retail drop-points enables circular material flows. Pilot programs in Benelux urban corridors demonstrate operational viability.
Industry Challenges
- Composting infrastructure gaps:Starch peanuts require industrial composting facilities to achieve claimed biodegradability timelines. Municipal waste systems in most markets lack adequate capacity.
- Legacy equipment retrofit costs:Automated filling systems calibrated for polystyrene density and electrostatic properties require mechanical recalibration for starch alternatives. Capital expenditure timelines extend replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Peanuts Market |
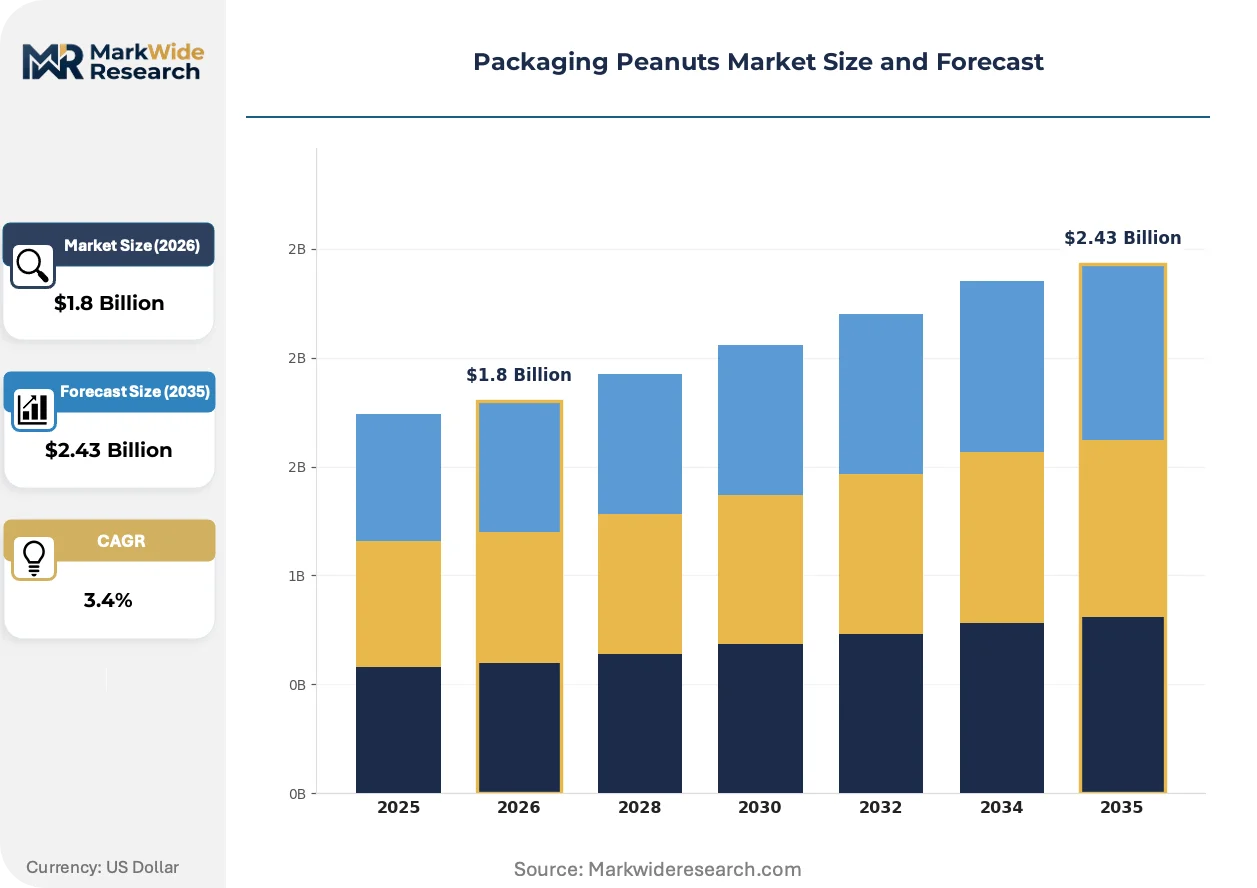
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable, Expanded Polystyrene, Packing Foam, Paper End User: E-Commerce, Retail, Food Industry, Electronics Distribution Channel: Online, Hypermarkets, Specialty Stores, Wholesale Packaging Type: Box, Bag, Bulk, Custom |
| Companies Covered | Rocket Industrial, Air Sea Containers, Sealed Air, Sonoco, Huhtamaki, Ranpak, Uline, WestRock, Puffy Stuff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Peanuts Market Evolving Landscape
Material science advances and regulatory compression are converging to restructure protective packaging procurement criteria. Sustainability verification is becoming a gatekeeping requirement rather than a premium differentiator.
Mushroom-derived mycelium cushioning is collapsing the performance gap between biological materials and synthetic foams. Luxury furniture and consumer electronics brands are piloting mycelium formats for high-value shipments. The technology is collapsing conventional assumptions about biodegradable protection durability.
The EU F-Gas Regulation is restricting hydrofluorocarbon and hydrocarbon blowing agents in expanded polystyrene manufacturing. Foam producers are investing in CO2-based physical foaming or exiting peanut production entirely. German and French converters face the steepest compliance cost escalations.
Consolidated e-commerce platforms are mandating supplier sustainability scorecards that weight protective material circularity. Third-party logistics providers serving Amazon and Zalando networks are switching to certified-compostable void-fill to maintain preferred vendor status. This procurement pattern shift is most visible in Central European fulfillment clusters.
Packaging Peanuts Market Segmentation
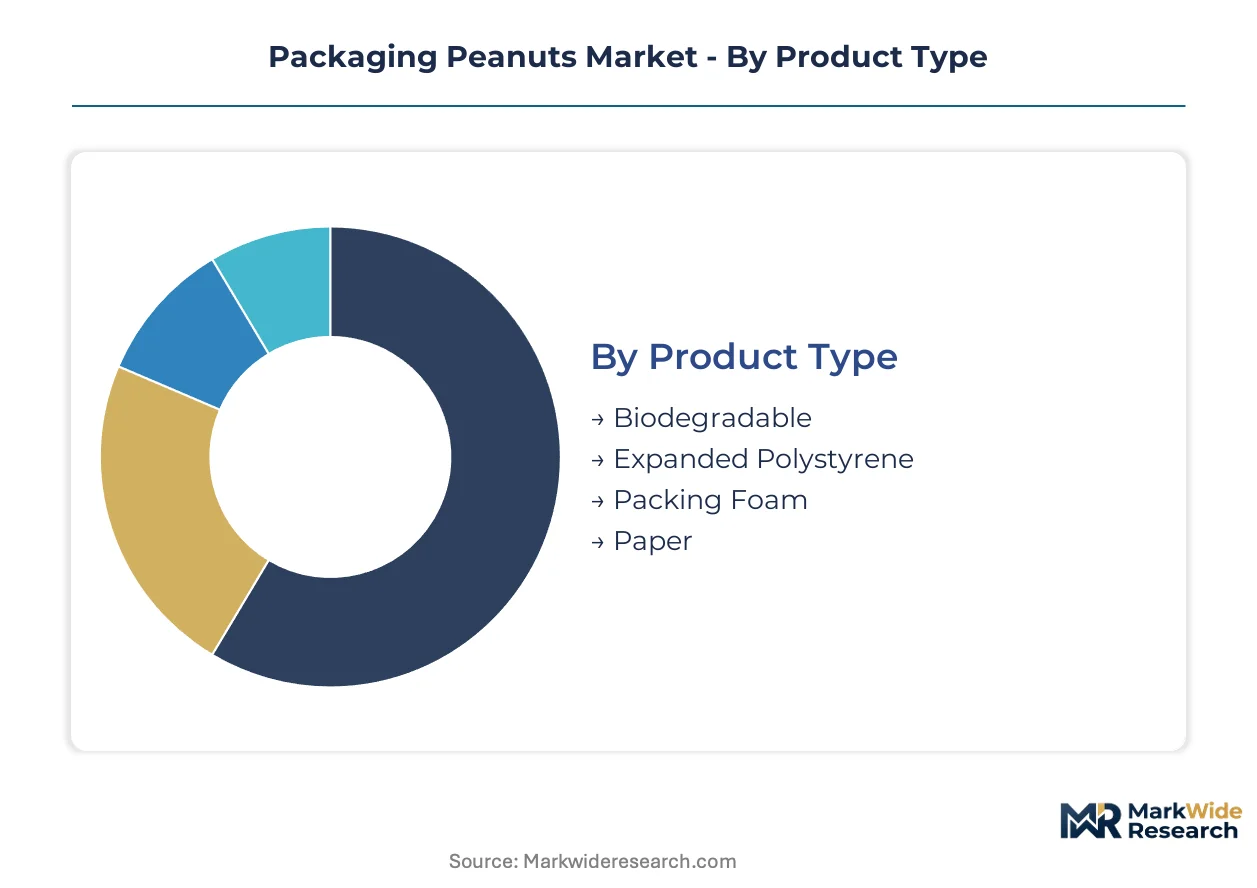
Packaging peanuts procurement patterns diverge sharply across material chemistry, fulfillment workflow, and channel economics. Stakeholders configure sourcing strategies around biodegradability mandates, damage-rate tolerances, and automated dispensing compatibility rather than commodity pricing alone.
Product Type:
Mature petroleum-derived formats coexist with emerging biological alternatives as regulatory pressure restructures manufacturing investment.
- Biodegradable:Starch-based formulations derived from corn or potato feedstock decompose in industrial composting environments. German fulfillment networks and Benelux urban corridors are mandating certified-compostable void-fill for preferred vendor status under extended producer responsibility schemes.
- Expanded Polystyrene:Hydrocarbon-blown foam beads deliver superior compression resistance and moisture immunity. The EU F-Gas Regulation and REACH chemical restrictions are elevating compliance costs for European converters while Asian petrochemical capacity sustains residual demand in less regulated markets.
- Packing Foam:Polyurethane and polyethylene sheet formats serve specialized cushioning applications requiring molded conformity.
- Paper:Crumpled kraft and molded pulp interleaving competes for lightweight void-fill demand in subscription box and luxury unboxing channels.
Expanded Polystyrene retains volume leadership; Biodegradable holds the steepest expansion curve.
End User:
Customer type stratification tracks damage liability exposure and sustainability disclosure requirements.
- E-Commerce:Automated fulfillment centers processing high-velocity fragile orders require reliable loose-fill systems compatible with robotic dispensing equipment. Third-party logistics providers serving consolidated platforms are switching to certified-compostable formats to maintain preferred vendor scorecards.
- Electronics:Anti-static formulations dissipating electrostatic discharge command premium pricing for semiconductor and consumer electronics shipments. REACH substance restrictions constrain legacy additive chemistries while conductive starch variants penetrate lower-value device categories.
- Retail:Brick-and-mortar distribution centers balance cost containment with brand-aligned unboxing aesthetics.
- Food Industry:Temperature-sensitive shipments require moisture-resistant cushioning compatible with cold chain logistics.
E-Commerce concentrates procurement volume; Electronics sustains margin premiums through specialized formulations.
Distribution Channel:
Channel selection reflects order scale, inventory velocity, and technical specification complexity.
- Wholesale:Bulk procurement through industrial distributors dominates mid-sized fulfillment operations seeking pallet-scale pricing and consolidated logistics. Uline's North American catalog control and European packaging cooperatives anchor this channel's structural position.
- Online:Direct ordering platforms penetrate smaller fulfillment operators and seasonal demand spikes. Asset-light leasing models for protective packaging equipment are narrowing capital barriers through this channel.
- Hypermarkets:Limited SKU breadth serves consumer and small-business incidental demand.
- Specialty Stores:Technical specification support for anti-static and custom-formulation requirements.
Wholesale channels handle the largest tonnage flows; Online ordering is gaining fastest among sub-scale operators.
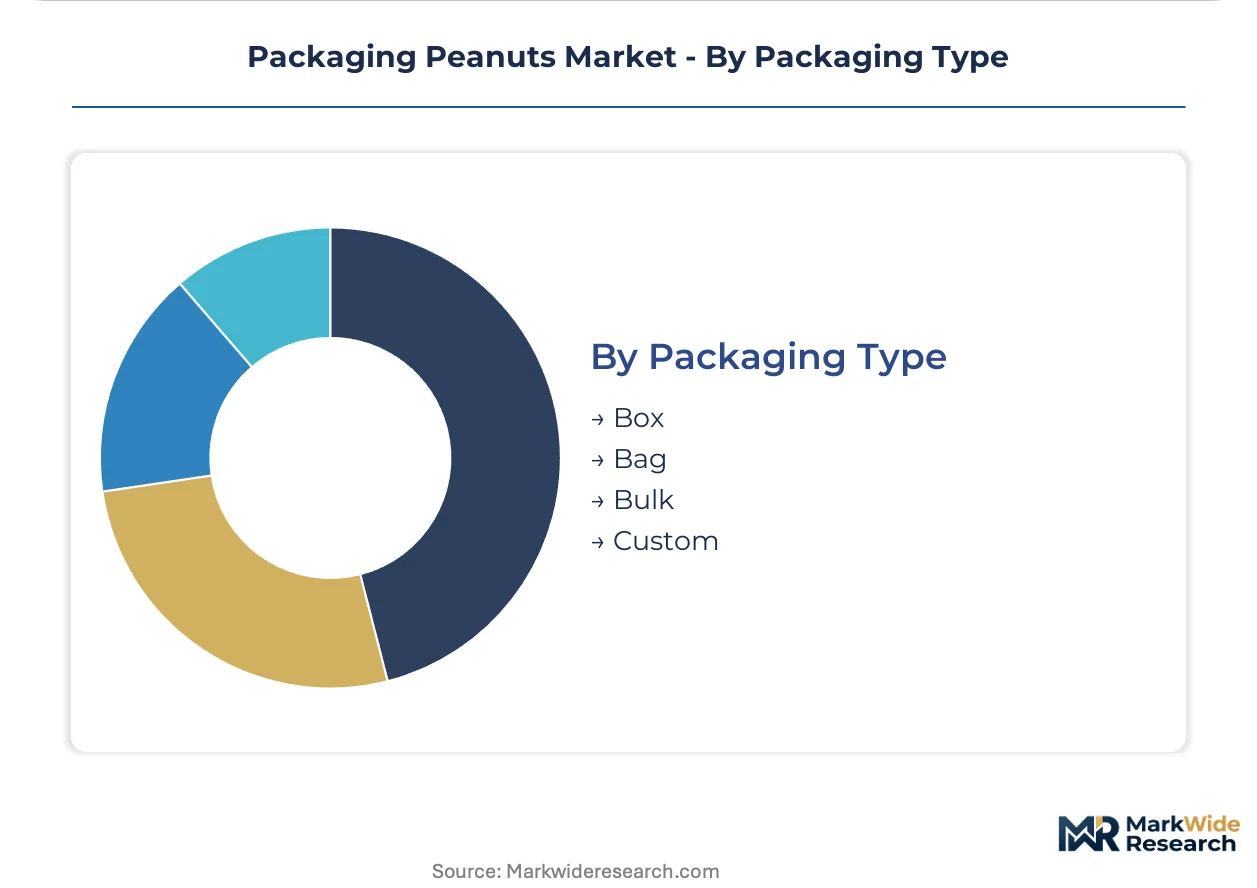
Packaging Type:
Format configuration balances material efficiency against handling automation and unboxing experience.
- Box:Standard corrugated containment with loose-fill dispensing remains the dominant configuration for mixed-SKU fulfillment. German packaging waste regulations are accelerating shifts from non-recyclable formats toward closed-loop compatible box systems.
- Custom:Molded pulp and engineered starch formats tailored to specific product geometries reduce material waste and damage rates. Luxury furniture and consumer electronics brands are piloting mycelium-derived cushioning in this category.
- Bag:Flexible containment for pre-measured void-fill dispensing in manual packing stations.
- Bulk:Loose material streams for high-volume automated filling systems without intermediate containment.
Box formats dominate operational deployment; Custom configurations are climbing fastest on sustainability differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Single-Use Plastics Directive and Germany's Packaging Act are accelerating material transitions across European fulfillment networks. Brand owners face escalating compliance costs for non-recyclable void-fill, redirecting procurement toward certified-compostable alternatives.
Germany
Fulfillment centers serving Zalando and Amazon networks are mandating biodegradable loose-fill for preferred vendor status. The country's extended producer responsibility scheme under the Verpackungsgesetz imposes strict recyclability quotas on protective materials. Stuttgart and Hamburg host the densest clusters of starch-peanut converters retrofitting automated dispensing systems.
United States
E-commerce volume concentrated in Chicago and Dallas-Fort Worth metro areas sustains demand for high-throughput loose-fill systems. The EPA regulates expanded polystyrene manufacturing emissions under Clean Air Act provisions, elevating compliance burdens for domestic foam producers. California's SB 54 plastic pollution reduction requirements are compressing polystyrene peanut demand on the West Coast.
China
Domestic petrochemical capacity supplies expandable polystyrene beads to Asian fulfillment networks, though dual carbon goals under MEE frameworks are constraining hydrocarbon-intensive foam expansion. Yangtze River Delta logistics hubs in Shanghai and Suzhou concentrate automated packaging equipment deployment. NMPA-aligned sustainability disclosures are pressuring exporters toward biodegradable alternatives for EU-bound shipments.
Netherlands
Rotterdam's port-centric distribution infrastructure positions the country as a Benelux gateway for sustainable packaging materials. The EU Green Deal's circular economy action plan mandates industrial composting infrastructure development that starch-peanut producers require for biodegradability claims. Amsterdam's urban logistics corridors host pilot programs for closed-loop peanut collection at parcel locker networks.
India
BIS certification requirements for packaging materials are tightening quality standards for imported void-fill. Maharashtra's Mumbai-Pune industrial corridor concentrates e-commerce fulfillment investment from Flipkart and Amazon India operations. The PLI scheme for manufacturing is attracting domestic starch-fermentation capacity to serve regional protective packaging demand.
Packaging Peanuts Market Competitive Landscape
On the supply side, the industry is consolidating around diversified packaging conglomerates with integrated material science capabilities. Mid-sized specialists occupy niche positions in biodegradable formulations and regional distribution. Three archetypes dominate: petrochemical-anchored foam producers pivoting toward sustainable portfolios, paper-based cushioning specialists capturing subscription-box demand, and catalog-driven distributors controlling wholesale channel access. Capacity expansion in starch-fermentation facilities and strategic partnerships with composting infrastructure operators represent the dominant competitive moves.
Among North American distributors, Uline anchors wholesale channel control through catalog dominance and direct-ship logistics. Sealed Air represents the diversified conglomerate archetype with global manufacturing footprints spanning multiple protective material categories. Ranpak exemplifies the paper-based specialist positioning, competing directly with conventional peanut formats through kraft-based cushioning technologies. These three occupy distinct strategic positions without direct overlap in core competencies.
| Leading Market Players |
|---|
| Rocket Industrial |
| Air Sea Containers |
| Sealed Air |
| Sonoco |
| Huhtamaki |
| Ranpak |
| Uline |
| WestRock |
| Puffy Stuff |
| Others |
Value Network & Pricing Analysis
Chinese polystyrene resin concentration determines both pricing tier spreads and supply chain shape, compressing margins for converters dependent on Asian petrochemical feedstock while elevating premiums for starch-based alternatives with localized fermentation capacity.
Pricing Analysis
Certification level under EU compostability standards creates the primary spread between commodity polystyrene peanuts and certified-compostable starch variants. Three-tier pricing structure across premium anti-static formulations, standard biodegradable grades, and economy polystyrene tiers reflects material chemistry and automation compatibility. Pricing pressure stems from REACH chemical restrictions elevating compliance costs for hydrocarbon-blown foam production. E-commerce fulfillment centers exhibit highest price sensitivity, while electronics shippers absorbing damage liability tolerate premium conductive grades.
Supply Chain Analysis
Extended payment terms from German packaging cooperatives and supply-chain finance facilities at Rotterdam port distributors shape working capital requirements for starch-fermentation entrants. Manufacturing concentrates in China, Germany, and the United States, with expandable polystyrene bead production anchored in Asian petrochemical complexes. Corn and potato starch feedstocks draw from agricultural commodity markets subject to harvest volatility. Single-source vulnerability to Chinese resin supply disruptions represents the dominant structural risk. Distribution runs through industrial catalog wholesalers and direct-ship platforms serving mid-sized fulfillment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaging peanuts market sits in a cyclical recovery phase driven by e-commerce order velocity rebounding through fulfillment network expansion.
For Market Incumbents: Harden supply security through backward integration into corn-starch fermentation capacity in the Midwest United States or Central European agricultural corridors. Deepen channel control by acquiring catalog distributors with installed base relationships among mid-sized 3PL operators. The threat of mycelium-derived cushioning substitutes demands accelerated R&D in biological material performance enhancement. For New Entrants and Emerging Players: Pursue white-space opportunity in closed-loop peanut collection infrastructure for Benelux urban logistics corridors, where pilot programs demonstrate operational viability. The most penetrable segment is direct-to-consumer subscription boxes demanding dye-free, aesthetically neutral cushioning. A go-to-market angle through composting facility partnerships enables verified sustainability claims that satisfy extended producer responsibility schemes. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified packaging conglomerates with integrated material science capabilities. Long-term viability over the next decade hinges on portfolio breadth spanning biodegradable, paper-based, and next-generation mycelium formats. Acquisition targets should display fermentation capacity scale or composting infrastructure partnerships. The signal to watch is Amazon and Zalando supplier sustainability scorecard tightening that accelerates procurement switching.| Strategic Initiative | Industry Significance |
|---|---|
| Starch-Fermentation Capacity Expansion | Captures volume migrating from polystyrene under EU Single-Use Plastics Directive enforcement. |
| Composting Infrastructure Partnership | Secures industrial composting access required for biodegradable peanut biodegradability claims in Germany. |
| Anti-Static Formulation R&D Investment | Sustains margin premiums in electronics shipping segments vulnerable to electrostatic discharge damage. |
| Automated Dispensing Equipment Leasing | Lowers capital barriers for mid-sized fulfillment operators adopting loose-fill systems. |
| Mycelium Cushioning Pilot Programs | Positions early movers for luxury furniture and consumer electronics unboxing experience differentiation. |
Research Methodology
Operator-level perspectives from fulfillment center managers, protective packaging procurement leads at 3PL providers, starch-fermentation plant engineers, and composting facility operators anchored the qualitative base. Primary fieldwork combined with secondary validation against EPA emissions filings, EU ECHA substance restriction updates, customs trade data on expandable polystyrene bead flows, and SEC disclosures from diversified packaging conglomerates. Bottom-up demand modeling across e-commerce, electronics, and retail end-use segments triangulated against top-down market sizing.
Scenario-bracketing around regulatory implementation timelines and e-commerce penetration trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, end-use industry workflow, distribution channel structure, and regional regulatory cluster. CAGRs derived from trend extrapolation validated against historical displacement patterns from polystyrene to biodegradable alternatives. Forecast inputs incorporated REACH chemical restriction compliance cost trajectories and composting infrastructure buildout schedules.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, ocean freight rates, or EU packaging waste enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation pace and substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Archive Boxes Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Ziplock Food Bags Market