
 Refuse Bags Market | 2026-2036
Refuse Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Refuse Bags Market Outlook
Municipalities are redrawing procurement priorities across the Refuse Bags Market, shifting volume toward compostable and high-durability specifications. Berry Global Inc. leverages vertical integration across resin and film production to secure cost positions in polyethylene-based refuse bags. Novolex anchors North American supply through extensive blown-film manufacturing infrastructure and direct retail partnerships.
Refuse bags are engineered containment products manufactured from polyethylene films, biopolymers, or multi-layer laminates, designed to meet specified load-bearing capacities and puncture resistance thresholds for waste collection and transport. HDPE remains the dominant material segment due to its stiffness and cost efficiency in high-volume can liner applications, though bioplastics represent the fastest-expanding category as composting infrastructure spreads. The residential end-user segment generates the largest revenue pool, while commercial users command higher per-unit pricing through specialized odor-control and antimicrobial specifications.
EPA guidelines on sustainable materials management and the EU Single-Use Plastics Directive shape product compliance requirements across major supply corridors, with California's SB 54 imposing recycled content minimums that ripple through national formulation standards. BIS certification requirements in India and REACH chemical compliance in Europe add layered testing obligations for exporters. Stakeholders must track evolving extended producer responsibility frameworks and compostability certification protocols to anticipate which material platforms will secure preferential procurement status.
Market Dynamics
Municipal procurement departments are rewriting supplier specifications to mandate certified compostable liners, forcing polyethylene-heavy portfolios into rapid reformulation cycles. This regulatory-driven material pivot compresses margins for conventional resin-dependent producers while opening premium pricing tiers for certified biopolymer alternatives.
Growth Catalysts
- EU Single-Use Plastics Directive:France, Italy, and Spain have transposed this framework into national mandates requiring compostable liners for food waste collection, accelerating biopolymer bag procurement by municipal sanitation departments.
- Composting infrastructure buildout:Germany's dual-bin separation systems now cover over 90 percent of households, creating guaranteed offtake for certified compostable refuse bags in residential applications.
- California SB 54 recycled content minimums:This statute imposes 30 percent post-consumer resin thresholds on refuse bags sold in-state, forcing national suppliers to reconfigure supply chains toward recycled polyethylene feedstock.
Market Restraints
- Ethylene price volatility:Naphtha-derived ethylene costs swing with crude oil benchmarks, compressing margins for HDPE liner producers unable to pass through input spikes to municipal contracts locked at fixed pricing.
- Biopolymer supply concentration:PLA and PBAT resin production clusters in Thailand and China, exposing Western converters to freight cost surges and currency fluctuation risks on imported feedstock.
- Industrial composting capacity gaps:Many US municipalities lack certified composting facilities capable of processing ASTM D6400-compliant bags, creating performance failures that erode consumer confidence in biopolymer alternatives.
Strategic Opportunities
- India's urban waste management modernization:Swachh Bharat Mission funding is expanding door-to-door collection systems in tier-2 cities, creating first-mover advantages for durable multi-layer bag suppliers.
- Odor-control antimicrobial specifications:Healthcare and hospitality end-users are specifying silver-ion or zeolite-embedded films for medical and food-service waste containment, commanding 40-60 percent price premiums over standard liners.
- Extended producer responsibility frameworks:France's Citeo system and similar schemes in Netherlands and Belgium assign waste management fees to packaging producers, incentivizing lightweighting and recyclable material transitions.
Industry Challenges
- Compostability certification timelines:BPI and TUV Austria OK Compost HOME certifications require 6-12 month testing cycles, delaying product launches and freezing R&D budgets during validation periods.
- Blown-film equipment reconfiguration:Transitioning from polyethylene to biopolymer extrusion demands screw-design modifications and temperature-profile recalibration, idling production lines for 2-4 weeks per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refuse Bags Market |
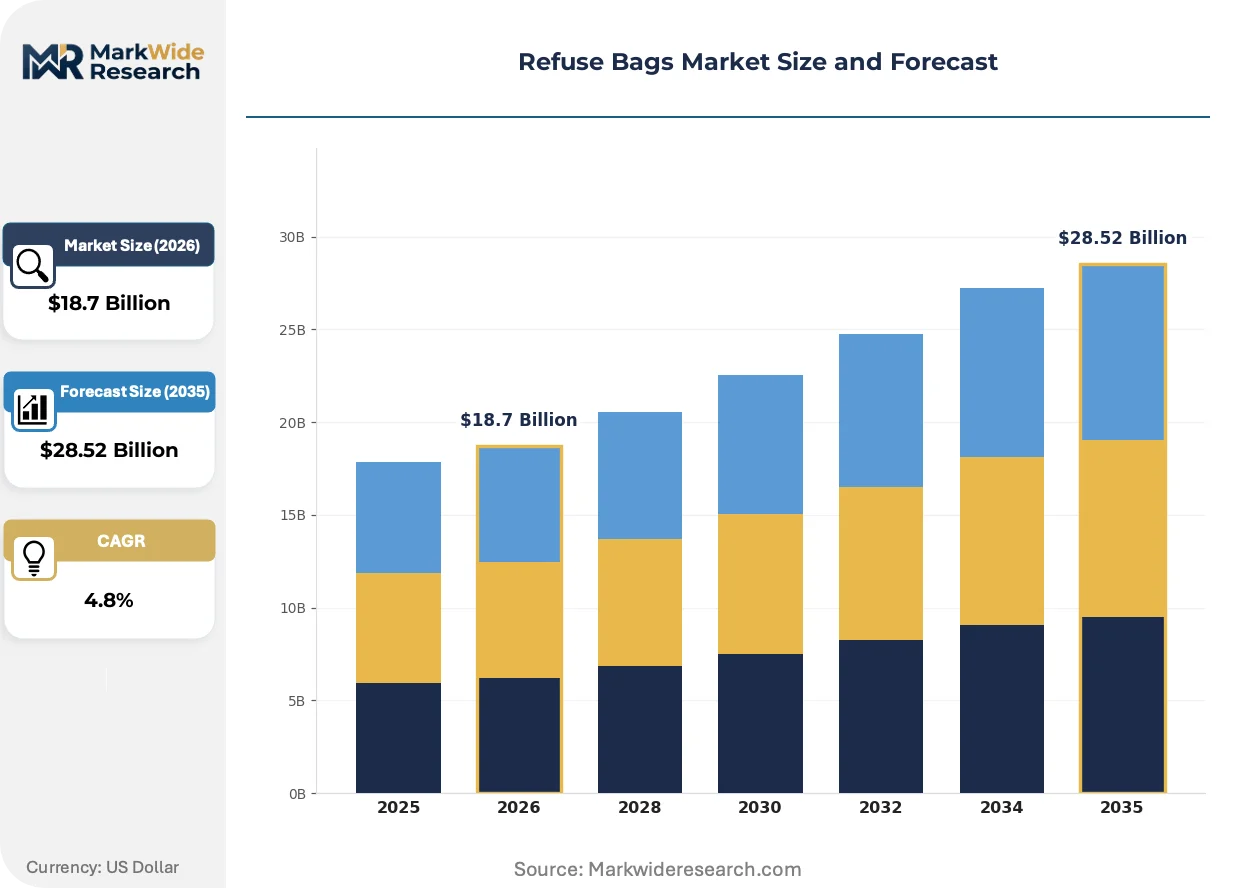
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Bags, Compostable Bags, Plastic Bags, Reusable Bags End User: Residential Consumers, Commercial Users, Industrial Facilities, Municipalities Material: HDPE, LDPE, Polylactic Acid, Bioplastics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Berry Global Inc., The Clorox Company, Novolex, Reynolds Consumer Products, Poly-America, L.P., Inteplast Group, Polykar Industries Inc., Aluf Plastics, BioBag International AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refuse Bags Market Strategic Shifts
Material science advances and regulatory ratchets are converging to fragment the once-homogeneous polyethylene refuse bag market into specialized performance tiers. Suppliers now compete on certification credentials rather than unit cost alone.
Multi-layer coextrusion technology incorporating EVOH oxygen barriers is displacing conventional monolayer HDPE in food waste applications. Municipal composting programs in Seattle, San Francisco, and Toronto specify these structures to prevent leakage and odor escape during curbside collection. The displacement is compressing volumes for basic high-density polyethylene can liners in premium residential segments.
REACH chemical compliance requirements in Europe are restricting certain phthalate plasticizers and heavy-metal colorants previously standard in refuse bag formulations. German and Dutch converters are reformulating masterbatch recipes to meet SVHC disclosure thresholds. The industrial and commercial bag segment bears the heaviest compliance burden, with many smaller suppliers exiting export markets rather than absorbing testing costs.
Direct-to-municipality contracting is consolidating purchasing power away from traditional distribution intermediaries. Sanitation departments in Copenhagen, Amsterdam, and Vienna now run centralized procurement portals specifying certified compostable grades with multi-year volume commitments. This channel shift is visible most acutely in Northern European markets where waste management services remain municipally operated rather than privatized.
Refuse Bags Market Segmentation
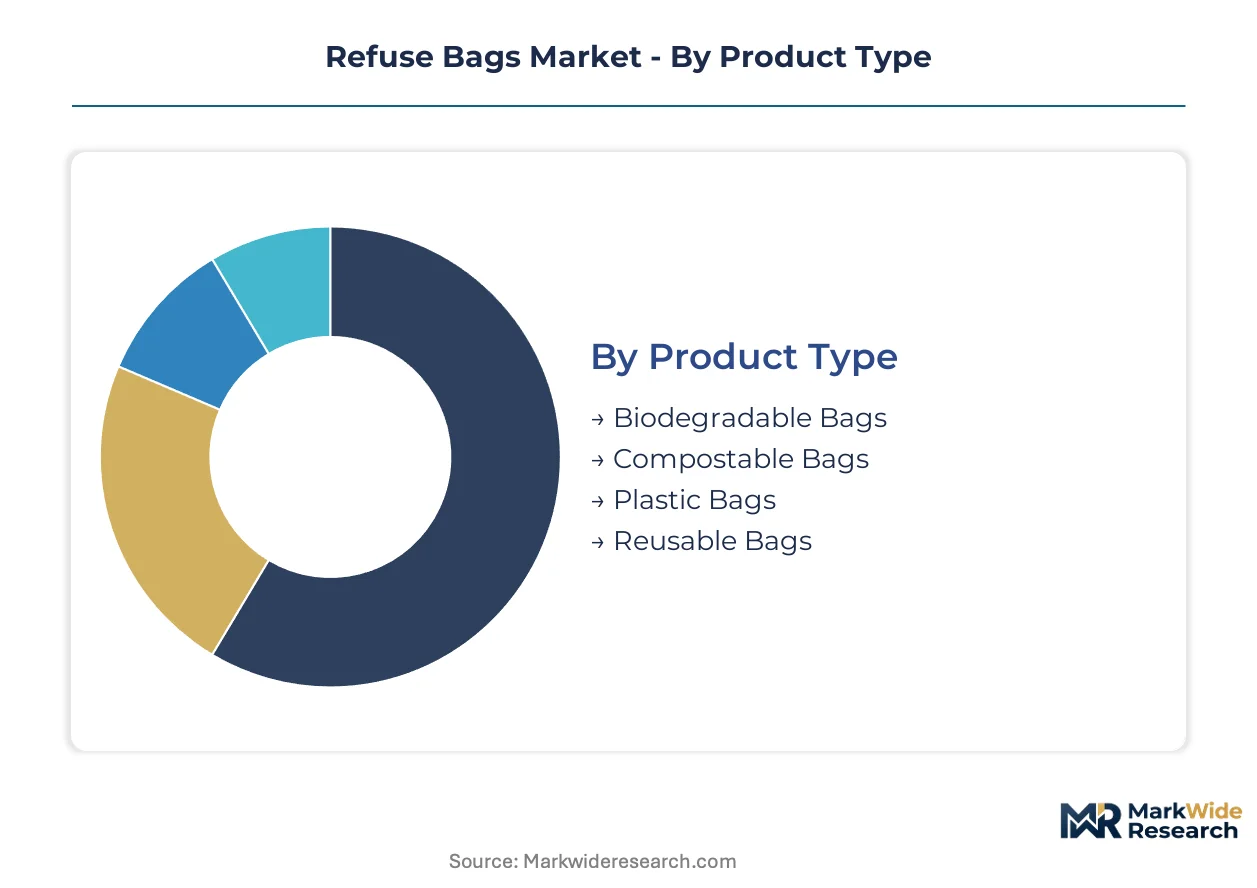
Refuse bag procurement splits sharply across material certification grades and institutional buyer types. Municipal tender specifications now override consumer preference in volume allocation, while compostability credentials determine margin capture.
Product Type:
Margin pools concentrate in certified compostable and biodegradable specifications where regulatory compliance creates pricing power.
- Compostable Bags:Engineered from PLA-PBAT blends meeting ASTM D6400 or EN 13432 standards for industrial composting breakdown. France, Italy, and Spain mandate these for organic waste collection under EU Single-Use Plastics Directive transpositions, locking in municipal procurement premiums.
- Plastic Bags:Conventional polyethylene constructions dominate unit volume through HDPE can liners and LDPE contractor sacks. California SB 54 recycled content minimums are forcing reformulation toward post-consumer resin blends, compressing margins on legacy virgin formulations.
- Biodegradable Bags:Oxo-degradable and soil-biodegradable variants serve markets lacking industrial composting infrastructure. BIS certification requirements in India favor these specifications for urban collection systems.
- Reusable Bags:Heavy-gauge woven polypropylene or canvas constructions target zero-waste retail and hospitality segments. REACH chemical compliance restricts certain plasticizers in European formulations.
Plastic bags hold installed capacity. Compostable bags are rotating up the share rankings.
End User:
Commercial and municipal buyers command per-unit premiums through specialized odor-control and antimicrobial specifications absent in residential channels.
- Municipalities:Centralized procurement portals in Copenhagen, Amsterdam, and Vienna specify certified compostable grades with multi-year volume commitments. Direct contracting bypasses traditional distribution intermediaries.
- Commercial Users:Healthcare and hospitality operators specify silver-ion or zeolite-embedded films for medical and food-service waste containment. These antimicrobial specifications capture 40-60 percent price premiums over standard liners.
- Residential Consumers:Price-sensitive household purchasing concentrates in supermarket and online retail channels. Germany's dual-bin separation systems now cover over 90 percent of households, creating guaranteed offtake for certified compostable alternatives.
- Industrial Facilities:Heavy-duty multi-layer constructions serve manufacturing and construction waste streams. Swachh Bharat Mission funding in India is expanding door-to-door collection systems in tier-2 cities.
Municipalities anchor volume commitment. Commercial users are climbing the fastest on margin contribution.
Material:
Feedstock cost volatility and certification timelines fragment competitive position across resin platforms.
- HDPE:High-density polyethylene delivers stiffness and cost efficiency in high-volume can liner applications. Naphtha-derived ethylene cost swings compress margins for producers locked into fixed-price municipal contracts.
- Bioplastics:PLA and PBAT resin production clusters in Thailand and China, exposing Western converters to freight cost surges. These materials represent the steepest expansion trajectory as composting infrastructure spreads.
- LDPE:Low-density polyethylene offers puncture resistance and flexibility in contractor and yard waste applications. Recycled content integration is accelerating under extended producer responsibility frameworks.
- Polylactic Acid:Corn-starch derived PLA serves food-contact and organic waste collection where industrial composting facilities exist. BPI and TUV Austria OK Compost HOME certifications require 6-12 month testing cycles.
HDPE holds installed capacity. Bioplastics are rotating up the share rankings.
Distribution Channel:
Channel power is consolidating toward direct municipal contracting and institutional procurement portals.
- Wholesale:Distributors serving janitorial supply and facility management sectors bundle refuse bags with broader sanitation product portfolios. Volume discounts dominate pricing negotiation.
- Online Retail:E-commerce platforms capture residential replenishment purchasing and subscription-model bulk orders. Private-label penetration is highest in this channel.
- Supermarkets:Mass retail chains stock standard-grade HDPE liners as commodity basket-fillers. Shelf space allocation favors price-competitive national brands.
- Specialty Stores:Eco-focused retailers and zero-waste shops curate certified compostable and reusable bag assortments. Premium positioning supports higher gross margins.
Wholesale holds installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's biopolymer import terminals anchor Europe's compostable bag supply chain, channeling Thai and Chinese PLA-PBAT feedstock into continental converter networks. This infrastructure asset underwrites the region's pivot from virgin polyethylene toward certified compostable specifications.
Germany
Dual-bin separation systems now cover over 90 percent of German households, creating guaranteed offtake for certified compostable refuse bags. The country's Packaging Act mandates extended producer responsibility fees that incentivize lightweighting and material transitions. Bavaria's industrial corridor hosts blown-film converters reconfiguring extrusion lines for biopolymer processing.
United States
California's SB 54 statute imposes 30 percent post-consumer resin thresholds on refuse bags sold in-state, forcing national suppliers toward recycled polyethylene feedstock. EPA guidelines on sustainable materials management shape compliance requirements across major supply corridors. The Pacific Northwest's composting infrastructure cluster in Seattle and Portland specifies EVOH oxygen-barrier multi-layer structures for curbside collection.
France
The Citeo extended producer responsibility system assigns waste management fees to packaging producers, accelerating transitions toward recyclable and compostable materials. ANSM chemical compliance requirements restrict certain phthalate plasticizers in refuse bag formulations. The Île-de-France region's municipal procurement portals specify certified compostable grades with multi-year volume commitments.
India
Swachh Bharat Mission funding expands door-to-door collection systems in tier-2 cities, creating first-mover advantages for durable multi-layer bag suppliers. BIS certification requirements favor soil-biodegradable specifications for urban collection systems. Maharashtra's Mumbai-Pune industrial belt concentrates blown-film manufacturing capacity serving western Indian sanitation departments.
China
Dual carbon goals and provincial waste sorting mandates in Shanghai and Beijing drive demand for multi-layer compostable liners in municipal collection. GB standards on biodegradable plastics shape domestic formulation requirements. The Yangtze River Delta's polymer processing cluster supplies both domestic converters and export markets with PLA-PBAT resin compounds.
Refuse Bags Market Competitive Environment
Concentration sits with vertically integrated resin-to-film producers and specialized blown-film converters serving municipal procurement channels. The market structure fragments across polyethylene-dependent legacy portfolios and emerging biopolymer specialists racing to secure compostability certifications. Two strategic archetypes dominate: multinational packaging conglomerates with backward integration into resin production, and regional converters leveraging proximity to municipal sanitation departments. Competitive moves center on blown-film equipment reconfiguration for biopolymer extrusion and direct-to-municipality contracting bypassing traditional distribution intermediaries.
Within the integrated multinational tier, Berry Global Inc. and Novolex occupy positions exemplifying divergent strategic postures. Berry Global Inc. anchors North American supply through captive resin and film production assets. Novolex represents the blown-film infrastructure-heavy archetype with extensive manufacturing footprints serving retail and institutional channels. BioBag International AS sits within the certified compostable specialist tier, its positioning tied to European municipal organic waste mandates. These three company profiles illustrate the market's bifurcation between polyethylene scale players and biopolymer certification-focused challengers.
| Leading Market Players |
|---|
| Berry Global Inc. |
| The Clorox Company |
| Novolex |
| Reynolds Consumer Products |
| Poly-America, L.P. |
| Inteplast Group |
| Polykar Industries Inc. |
| Aluf Plastics |
| BioBag International AS |
| Others |
Value Chain & Pricing Dynamics
EU Single-Use Plastics Directive compliance gates both supplier qualification and price differentiation simultaneously, as municipal procurement portals in France, Italy, and Spain mandate certified compostable liners that command 40-60 percent premiums over conventional polyethylene alternatives while excluding uncertified producers from tender participation.
Pricing Analysis
Volume-discount tiering structures dominate municipal contracting, with three-tier pricing stratification separating antimicrobial medical-grade specifications from standard commercial liners and economy residential grades. Price differentiation rests on certification tier—ASTM D6400 and EN 13432 credentials unlock municipal premiums—and customization depth for odor-control formulations. Cost compression in virgin HDPE tiers intensifies because naphtha-derived ethylene swings compress margins on fixed-price contracts. Residential consumers exhibit highest price sensitivity, while healthcare and hospitality buyers accept premium positioning for specialized containment performance.
Supply Chain Analysis
Inventory lead times stretch 6-12 months for BPI and TUV Austria compostability certifications, freezing working capital during validation cycles. Feedstock production clusters in Thailand and China for PLA-PBAT resins, with Germany and the United States anchoring blown-film conversion capacity. Raw material dependencies center on naphtha-derived ethylene, corn-starch feedstock for PLA, and imported PBAT compounds. Single-source vulnerability runs through Asian biopolymer resin supply. Distribution feeds from direct municipal procurement portals bypassing traditional wholesale intermediaries in Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compostable extrusion capability scarcity defines competitive advantage, as blown-film equipment reconfiguration demands screw-design modifications and temperature-profile recalibration that idles production lines for weeks.
For Market Incumbents: Consolidate backward integration into resin supply to hedge ethylene price volatility and biopolymer import exposure. Lock multi-year municipal volume commitments through direct procurement portal participation before certification backlogs freeze out polyethylene-dependent portfolios.
For New Entrants and Emerging Players: Lead with soil-biodegradable specifications targeting India's tier-2 cities under Swachh Bharat Mission expansion, where BIS certification pathways offer faster market entry than EU compostability timelines. Pursue odor-control antimicrobial formulations for healthcare white-space.
For Investors and Strategic Acquirers: California SB 54 reshapes the acquisition landscape by mandating 30 percent post-consumer resin thresholds that favor converters with recycled polyethylene processing infrastructure. Target blown-film specialists with municipal certification pipelines and existing EPR framework participation. Watch composting infrastructure buildout rates as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | BPI and TUV Austria credentials unlock municipal procurement premiums in France, Italy, and Spain. |
| Backward Integration into Resin Supply | Captive PLA-PBAT feedstock hedges freight cost surges from Thai and Chinese production clusters. |
| Direct Municipal Contracting | Copenhagen, Amsterdam, and Vienna portals bypass wholesale intermediaries for volume commitment security. |
| Antimicrobial Film Development | Silver-ion and zeolite-embedded specifications capture 40-60 percent premiums in healthcare channels. |
| Recycled Content Reformulation | California SB 54 compliance positions suppliers for national recycled polyethylene feedstock reconfiguration. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with municipal procurement officers, blown-film plant managers, biopolymer resin technical directors, and janitorial supply distributors; and secondary validation through customs trade records, EPA sustainable materials management guidelines, EU Single-Use Plastics Directive transposition documents, and BPI certification registries. Bottom-up volume triangulation across material-grade segments converged with top-down value estimates anchored to disclosed municipal contract values.
Across the projection horizon, the analytical framework modeled material platform transitions, end-user procurement channel shifts, and regional regulatory cluster adoption patterns. CAGRs were derived from segment-level volume build-ups weighted by pricing tier trajectories. Forecast inputs incorporated composting infrastructure deployment timelines and extended producer responsibility fee structures.
The analysis sits within stated boundaries; outcomes outside sustained municipal procurement commitment to certified compostable specifications would require recalibration. Forecasts reflect assumptions on biopolymer resin supply expansion and certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Crates Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Net Bags Market
Bags and Containers
Leno Bags Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Inflatable Bags Packaging Market