
 Nonwoven Containers Market | 2026-2036
Nonwoven Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Containers Market Intelligence
EU REACH is hardening the cost-of-entry calculus for nonwoven container manufacturers seeking European market access. Berry Global Inc. leverages its integrated spunbond capacity across multiple continents to sustain supply security for retail clients. Freudenberg Performance Materials anchors its position through specialized filtration-grade nonwovens repurposed for food-safe container applications. DuPont differentiates via advanced polymer science that extends durability thresholds in reusable tote segments.
Nonwoven containers are engineered textile products manufactured through mechanical, thermal, or chemical bonding of staple fibers or continuous filaments, typically achieving basis weights between 15 and 150 gsm for packaging applications. These structures provide breathable, lightweight containment for retail distribution, food transport, and consumer storage without woven interlacing. Polypropylene dominates material throughput due to its thermoformability and cost structure, while biodegradable bags represent the fastest-expanding product category as compostability certification becomes a procurement gate. The e-commerce end-user segment commands widening share as fulfillment networks prioritize lightweight, collapsible secondary packaging.
FDA food-contact regulations in the United States, EU REACH and the Packaging and Packaging Waste Directive in Europe, and China's GB standards for plastic products collectively shape material selection, migration testing protocols, and circularity claims across major supply corridors. Manufacturers must navigate divergent compostability certification schemes—BPI in North America, TÜV OK Compost in Europe, and country-specific soil biodegradability tests in Asia—to maintain market access. Stakeholders should monitor evolving extended producer responsibility frameworks, as these programs will determine which container formats retain cost competitiveness against conventional plastics and paperboard alternatives.
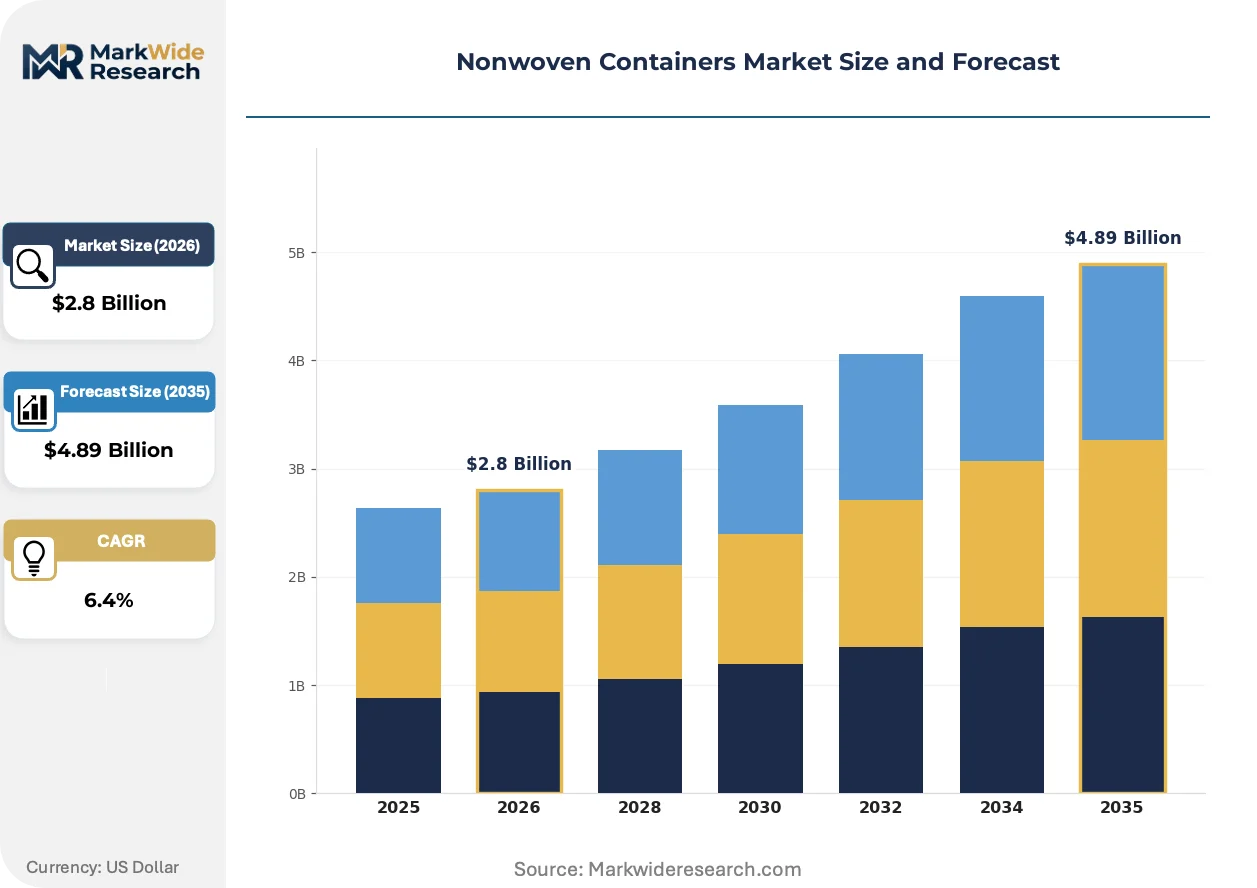
Market Dynamics
EU REACH compliance costs are restructuring competitive entry conditions for nonwoven container manufacturers targeting European markets. Material substitution mandates under the EU Single-Use Plastics Directive are compressing demand timelines for certified compostable formats.
Growth Catalysts
- EU Single-Use Plastics Directive:Member states are accelerating bans on conventional plastic takeaway containers, redirecting food service procurement toward certified compostable nonwoven alternatives.
- Spunbond-meltblown-spunbond (SMS) lamination:Advanced bonding technology is enabling liquid-resistant food containers that meet FDA and EFSA migration limits without polymer film liners.
- German retail consolidation:National grocery chains and hospitality groups are standardizing compostable container specifications, creating volume pull-through for certified suppliers.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings directly compress margin structures for commodity-grade spunbond container producers.
- Composting infrastructure gaps:Industrial composting facility coverage remains uneven across EU member states, undermining end-of-life claims for biodegradable bag formats.
- Paperboard substitution:Kraft-based clamshells and molded fiber containers compete aggressively in premium takeaway segments with established recycling pathways.
Strategic Opportunities
- Indian quick-service restaurant expansion:Domestic food delivery platforms are scaling sustainable packaging mandates, opening demand for cost-optimized nonwoven takeaway solutions.
- Reusable tote convergence with RFID:Integration of track-and-return logistics with durable polypropylene containers enables deposit-system economics for grocery retail.
- China dual carbon policy:Provincial emissions trading schemes and plastic intensity caps are incentivizing lightweight nonwoven alternatives in e-commerce secondary packaging.
Industry Challenges
- TÜV OK Compost HOME certification timelines:Soil biodegradability testing protocols require 12-18 month validation cycles, delaying product launches for seasonal retail windows.
- Migration testing capex:Food-contact compliance laboratories demand substantial capital outlay for extractables analysis under EU 10/2011 and FDA 21 CFR frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Containers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Bags, Reusable Totes, Shopping Bags, Storage Solutions Material: Polypropylene, Polyester, Cotton, Spunbond End User: Retail, Food Service, Consumer Goods, E-commerce Size: Small, Medium, Large, Extra Large |
| Companies Covered | Berry Global Inc., Freudenberg Performance Materials, DuPont, Kimberly-Clark Worldwide, Inc., Johns Manville Corporation, Glatfelter, Ahlstrom, Fitesa S.A. and Affiliates, Thrace Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Containers Market Strategic Shifts & Innovations
Active material science breakthroughs are compressing performance gaps between single-use and durable nonwoven containers. Regulatory chemistry restrictions and logistics optimization are simultaneously reshaping specification standards.
Polylactic acid (PLA) spunbond nonwovens are electrifying food-contact applications with heat-seal integrity comparable to conventional polymers. European meal-kit distributors and Nordic grocery chains are adopting PLA-laminated containers for ready-meal segments. This material transition is electrifying investment flows toward fermentation-based lactide supply chains and away from fossil-derived staple fiber capacity.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating grease-resistant coatings from food-contact nonwovens. Manufacturers are reformulating barrier layers with bio-based wax emulsions and mineral fillers to maintain oil repellency. Bakery and fried-food container segments in Germany, France, and the Netherlands are most affected, with suppliers accelerating BPI and TÜV certification submissions ahead of 2025 enforcement windows.
Consolidated buying by third-party logistics providers is displacing fragmented distributor networks for e-commerce secondary packaging. Amazon, Zalando, and regional fulfillment platforms are specifying collapsible nonwoven totes with standardized dimensions for automated sortation. This channel compression is most visible in German and Polish distribution hubs, where packaging engineering teams now coordinate directly with spunbond manufacturers rather than intermediaries.
Nonwoven Containers Market Segmentation
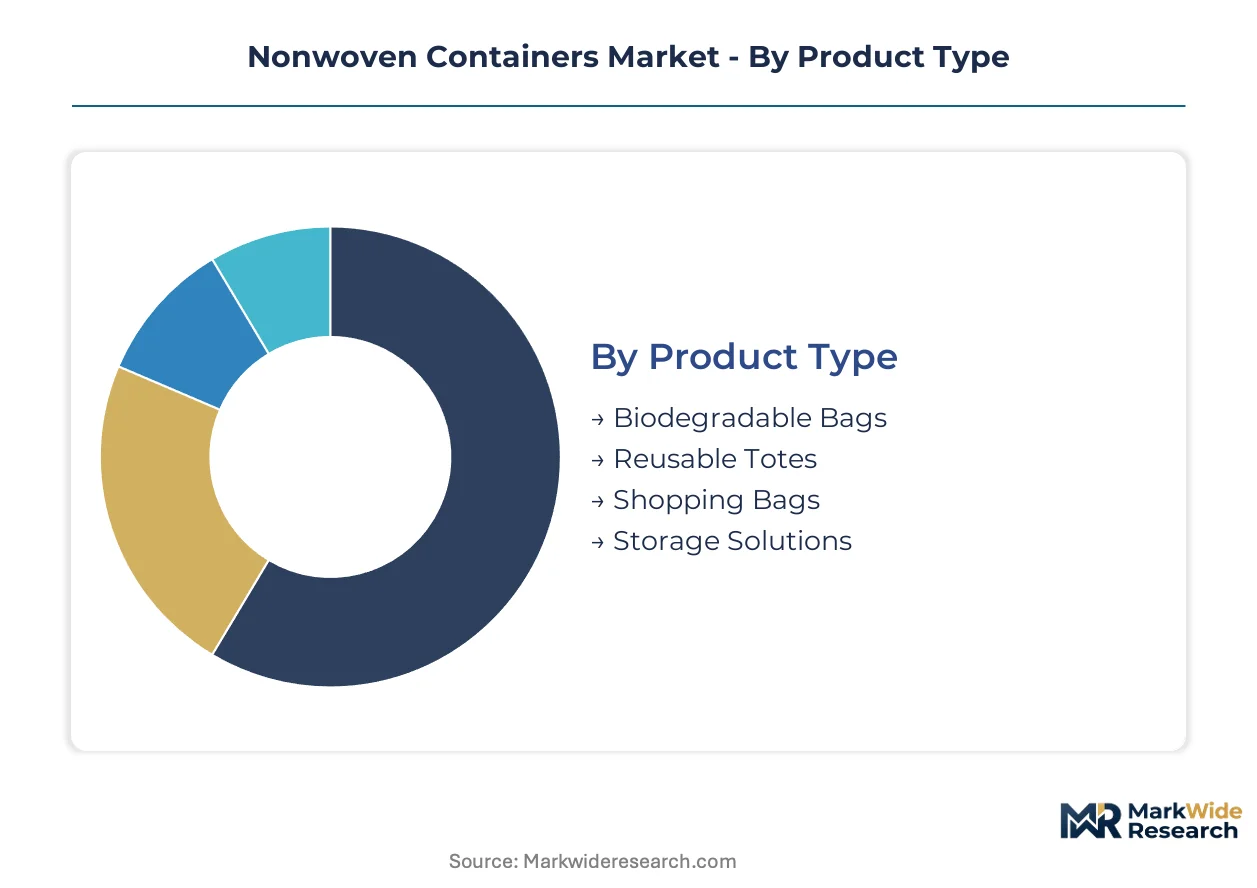
Nonwoven container specifications diverge sharply across end-use applications, with material bonding technologies and compostability certifications determining procurement eligibility. Container geometry, basis weight, and barrier properties are engineered to match fulfillment velocity, food-contact compliance, and retail branding requirements.
Product Type:
Spunbond lamination depth and end-of-life certification status define commercial positioning within each format.
- Biodegradable Bags:PLA and starch-blend spunbond structures achieve TÜV OK Compost HOME certification for soil biodegradability. German meal-kit distributors and Nordic grocery chains are standardizing these formats for ready-meal segments despite 12-18 month validation timelines.
- Reusable Totes:Heavy-duty polypropylene containers with 80-150 gsm basis weights integrate RFID tracking for deposit-system logistics. Amazon and Zalando fulfillment networks in Germany and Poland specify collapsible geometries for automated sortation compatibility.
- Shopping Bags:Lightweight spunbond totes with 30-60 gsm weights serve retail branding and impulse purchase containment.
- Storage Solutions:Zippered and gusseted configurations organize household and commercial inventory.
Reusable totes lead on scale; biodegradable bags lead on momentum.
Material:
Feedstock selection governs thermoformability, cost structure, and regulatory compliance across major supply corridors.
- Polypropylene:Dominates throughput due to thermoformability and cost structure. Propylene monomer price volatility directly compresses margin structures for commodity-grade spunbond producers.
- Spunbond:Continuous filament bonding achieves 15-150 gsm range for packaging applications. SMS lamination enables liquid-resistant food containers meeting FDA and EFSA migration limits without polymer film liners.
- Polyester:Higher tenacity fibers serve durable tote applications requiring extended reuse cycles.
- Cotton:Natural fiber blends target premium retail segments with compostability marketing claims.
Polypropylene dominates volume throughput; spunbond variants are climbing the fastest on technology differentiation.
End User:
Procurement specifications diverge across fulfillment velocity, food-contact exposure, and branding requirements.
- E-commerce:Third-party logistics consolidation is displacing fragmented distributor networks. Collapsible totes with standardized dimensions enable automated sortation at Amazon, Zalando, and regional fulfillment platforms in German and Polish hubs.
- Food Service:EU Single-Use Plastics Directive bans are redirecting takeaway procurement toward certified compostable formats. German hospitality chains are adopting specifications at scale.
- Retail:Grocery and specialty store branding requirements drive customized print and handle configurations.
- Consumer Goods:Household organization and personal storage applications prioritize durability and aesthetics.
E-commerce commands widening share; food service is gaining share fastest on regulatory displacement.
Size:
Dimensional standardization enables logistics optimization while custom formats serve specialized containment needs.
- Medium:Standard grocery and retail tote dimensions align with automated checkout and fulfillment bin specifications. German retail consolidation is standardizing procurement around this tier.
- Large:Bulk retail and e-commerce secondary packaging formats accommodate multi-item fulfillment. Zalando and regional platforms specify collapsible geometries for this tier.
- Small:Single-item and impulse purchase containment for specialty retail.
- Extra Large:Industrial and commercial storage applications requiring reinforced handles and gusseted bases.
Medium sizes anchor procurement volumes; large formats show steepest expansion trajectory on e-commerce fulfillment scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer scientists and nonwoven process engineers concentrate in Germany, China, and the United States, anchoring the industry's technical workforce. These talent pools cluster around spunbond research centers and pilot-scale production facilities. Their geographic distribution shapes where next-generation container formats achieve commercial scale first.
Germany
Retail consolidation among national grocery chains and hospitality groups is standardizing compostable container procurement specifications. EU REACH compliance costs and the Single-Use Plastics Directive are accelerating material substitution mandates. The Rhine-Ruhr industrial corridor hosts spunbond manufacturers serving food-contact applications with certified biodegradable formats.
United States
FDA food-contact migration testing requirements are structuring entry barriers for imported nonwoven containers. E-commerce fulfillment networks prioritize lightweight, collapsible secondary packaging for automated sortation. The Southeast manufacturing belt—particularly Georgia and the Carolinas—concentrates spunbond capacity serving retail and logistics clients.
China
Provincial emissions trading schemes and plastic intensity caps under the dual carbon policy are incentivizing lightweight packaging alternatives. GB standards for plastic products govern material selection and circularity claims. The Yangtze River Delta cluster around Shanghai anchors spunbond production for domestic e-commerce and export markets.
India
Domestic food delivery platforms are scaling sustainable packaging mandates for quick-service restaurant expansion. BIS certification requirements and FSSAI food-contact regulations shape import and local production standards. The Maharashtra-Gujarat industrial corridor hosts emerging nonwoven fabricators targeting cost-optimized takeaway solutions.
France
ANSM enforcement of EU REACH Annex XVII PFAS restrictions is eliminating grease-resistant coatings from food-contact applications. Bakery and fried-food container segments are accelerating reformulation with bio-based barrier layers. The Lyon-Grenoble polymer research cluster supports biodegradable spunbond development for ready-meal distributors.
Nonwoven Containers Market Key Industry Players
The competitive structure tilts toward integrated polymer producers with captive spunbond capacity. Consolidation among multinational material science firms coexists with regional specialists serving certified compostable niches. Three archetypes dominate: integrated chemical-to-fiber conglomerates, specialized nonwoven converters, and private-label fabricators for retail chains. Capacity expansion and certification acceleration represent the two dominant competitive moves as manufacturers race to secure TÜV and BPI validations ahead of regulatory deadlines.
Among integrated material science conglomerates, Berry Global Inc., DuPont, and Freudenberg Performance Materials occupy anchor positions. Berry Global exemplifies the multi-continent spunbond producer archetype, while DuPont represents advanced polymer science differentiation. Freudenberg sits within the specialized filtration-to-food-contact repurposing tier. These three firms illustrate how technical depth and geographic footprint combine to structure supply security for retail and hospitality procurement.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Freudenberg Performance Materials |
| DuPont |
| Kimberly-Clark Worldwide, Inc. |
| Johns Manville Corporation |
| Glatfelter |
| Ahlstrom |
| Fitesa S.A. and Affiliates |
| Thrace Group |
| Others |
Cost & Logistics Intelligence
SMS lamination technology migration from batch to continuous production lines simultaneously compresses unit economics and consolidates manufacturing scale among German and Chinese producers with capital access for reactor upgrades. This process transition concentrates cost leadership with integrated spunbond operators while fragmenting pricing power among commodity-grade converters dependent on spot propylene purchases.
Pricing Analysis
Certification-bundled versus unbundled supply splits the market into two pricing models. Three-tier pricing structure across TÜV-certified premium, BPI-standard mid-tier, and uncertified economy levels separates procurement eligibility for EU food service from generic retail applications. Cost compression in commodity polypropylene totes intensifies because propylene monomer volatility feeds directly through spot-indexed feedstock contracts. Quick-service restaurant chains in India exhibit highest price sensitivity, while German meal-kit distributors accept premium tiers for compostable PLA formats.
Supply Chain Analysis
Reverse-logistics flows for reusable totes with RFID tracking create closed-loop supply networks between Amazon and Zalando fulfillment hubs and regional cleaning facilities in Germany and Poland. Manufacturing gravity centers on China, Germany, and the United States for spunbond capacity, with the Yangtze River Delta and Rhine-Ruhr corridor anchoring export supply. Raw material dependencies rest on propylene monomer, PLA lactide resin, and spunbond-grade polyester staple. Single-source vulnerability concentrates in fermentation-based lactide supply chains. Distribution runs through consolidated third-party logistics platforms rather than fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance costs elevating European production economics and China's dual carbon policy incentives compressing manufacturing overhead in the Yangtze River Delta cluster.
For Market Incumbents: Deepen backward integration into PLA lactide fermentation capacity to secure supply security against propylene volatility and emerging biopolymer competition. Anchor certification investment in TÜV OK Compost HOME validation pipelines ahead of EU Single-Use Plastics Directive enforcement windows. Defend margin position by locking long-term offtake agreements with German retail consolidators before capacity additions from Chinese competitors reach European ports. For New Entrants and Emerging Players: Launch via direct supply contracts to Indian quick-service restaurant platforms scaling sustainable packaging mandates for food delivery expansion. Target the biodegradable bag segment for ready-meal applications where 12-18 month certification timelines create incumbent vulnerability. Penetrate through cost-optimized spunbond formulations that meet FSSAI food-contact standards without European certification overhead. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with TÜV or BPI certifications but limited geographic footprint, offering bolt-on acquisition targets for integrated conglomerates. Long-term viability hinges on composting infrastructure buildout pace across EU member states and China's provincial emissions trading scheme expansion. Monitor industrial composting facility coverage ratios in France and the Netherlands as inflection indicators for biodegradable format demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PLA Lactide | Secures fermentation-based supply chains against fossil-derived staple fiber cost volatility. |
| TÜV OK Compost HOME Certification Acceleration | Unlocks German retail procurement specifications ahead of seasonal product launch windows. |
| RFID-Enabled Reusable Tote Networks | Enables deposit-system economics with Amazon and Zalando fulfillment platform integration. |
| Indian Quick-Service Restaurant Direct Supply | Captures food delivery platform sustainable packaging mandates scaling domestic expansion. |
| Continuous SMS Lamination Line Investment | Compresses unit costs for liquid-resistant food containers meeting FDA migration limits. |
Research Approach
Direct dialogue with spunbond plant managers, EU regulatory affairs leads at packaging converters, German grocery chain procurement directors, and Indian food delivery platform sustainability officers grounded qualitative findings. Secondary validation drew from ECHA REACH registration databases, EU Single-Use Plastics Directive implementation reports, BPI and TÜV certification registries, and customs trade data for polypropylene nonwoven shipments. Bottom-up capacity assessments across major production corridors triangulated against top-down demand modeling from end-use procurement specifications.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by product type, material bonding technology, compostability certification tier, end-use application velocity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating propylene feedstock price scenarios and substitution elasticity estimates between nonwoven and paperboard formats. Industry-specific inputs included EU composting infrastructure coverage ratios and Chinese provincial plastic intensity cap enforcement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction timelines or industrial composting facility deployment shortfalls. Practitioners should monitor ANSM enforcement patterns for grease-resistant coating reformulations and Maharashtra-Gujarat corridor spunbond capacity additions for early competitive intensity signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Woven Bags Market
Bags and Containers
Bags and Containers Market