
 Flip-Up Vacuum Pack Market | 2026-2036
Flip-Up Vacuum Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Flip-Up Vacuum Pack Market Foresight
Food processing plants are reorganizing procurement priorities toward equipment that cuts changeover time between protein and produce batches. Sealed Air Corporation leverages its Cryovac heritage to anchor premium positions in protein packaging lines. Amcor plc sustains material science leadership through multilayer coextrusion films engineered for oxygen transmission control. Multivac Group dominates thermoforming system integration, bundling flip-up vacuum chambers with automated loading for European meat cooperatives.
A flip-up vacuum pack is a sealing apparatus with a hinged lid that swings upward to expose a flat chamber bed, typically achieving vacuum levels below 50 mbar through oil-sealed rotary vane pumps or dry scroll systems, designed to evacuate air from barrier bags before heat-sealing for shelf-life extension. Industrial vacuum packs lead installed base across food preservation applications, where chamber dimensions above 800mm accommodate primal cuts and cheese wheels. Medical vacuum packs represent the fastest-growing application segment, driven by sterile barrier validation requirements for surgical kits and implantable device trays.
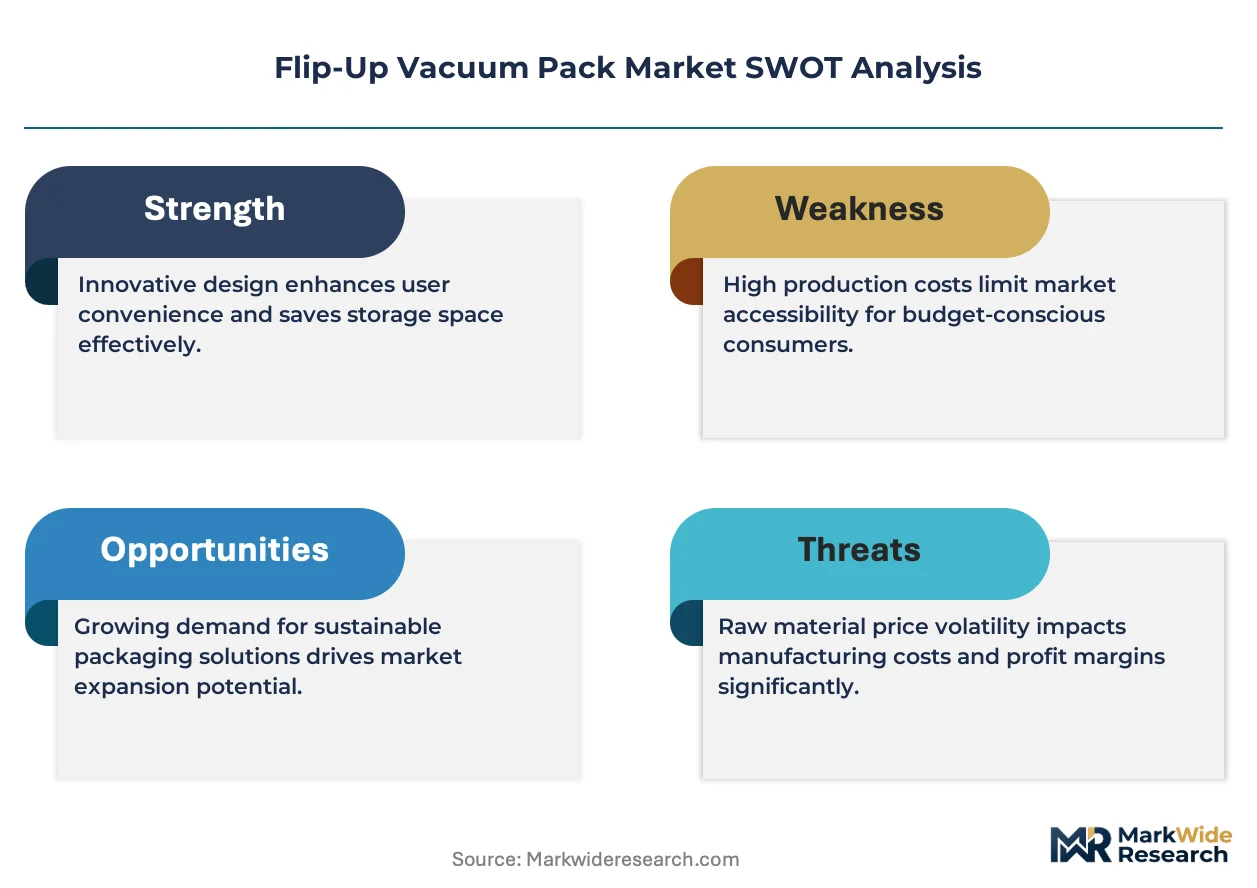
The U.S. FDA governs food contact notifications for plastic composites and polycarbonate chamber components, while EU REACH restricts phthalate plasticizers in sealing gaskets sold across Europe. ISO 11607 governs sterile barrier systems for medical vacuum packs, forcing manufacturers to maintain dual validation protocols for healthcare and food channels. Stakeholders must decide whether to specialize in single-industry certification depth or absorb cross-sector compliance costs as end users consolidate supplier lists.
Market Dynamics
Automated vacuum sealing lines are compressing batch changeover times from hours to minutes, forcing equipment suppliers to engineer modular chamber systems that swap between protein and produce configurations without tool-assisted teardown.
Growth Catalysts
- EU REACH compliance mandates:Phthalate restrictions in sealing gaskets are accelerating validated fluoropolymer adoption across German meat cooperatives and industrial bakeries retrofitting flip-up vacuum systems.
- Oil-sealed rotary vane pump reliability:Mature vacuum technology achieves sub-50 mbar evacuation consistently, reducing spoilage claims in food processing plants running extended preservation cycles.
- Sterile barrier validation requirements:ISO 11607 certification for surgical kits and implantable device trays is pulling medical vacuum pack demand ahead of traditional food preservation applications.
Market Restraints
- Barrier film input volatility:Multilayer coextrusion films depend on ethylene-vinyl alcohol supply concentrated in Asian petrochemical corridors, exposing European packagers to freight and resin cost swings.
- Dry scroll pump technical ceiling:Oil-free vacuum systems struggle to maintain sub-30 mbar consistency in high-throughput protein lines, limiting their penetration in primal cut processing.
- Dual validation protocol burden:Manufacturers serving both healthcare and food channels absorb redundant ISO 11607 and FDA food contact notification compliance costs without volume scale offsets.
Strategic Opportunities
- Medical vacuum pack white space:Sterile barrier systems for implantable device trays remain underpenetrated relative to food preservation, offering margin expansion through healthcare channel specialization.
- Retrofit automation bundling:Thermoforming system integrators can capture European meat cooperative demand by packaging flip-up vacuum chambers with automated loading modules as unified capital projects.
- Validated material substitution:FDA's updated food contact substance notification requirements create first-mover advantage for packagers qualifying alternative barrier composites ahead of enforcement deadlines.
Industry Challenges
- Vacuum pump technician scarcity:Oil-sealed rotary vane and dry scroll system maintenance requires specialized knowledge absent from standard industrial mechanic training programs.
- Legacy chamber integration friction:Retrofitting automated loading into existing flat chamber bed configurations demands custom mechanical interfaces that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip-Up Vacuum Pack Market |
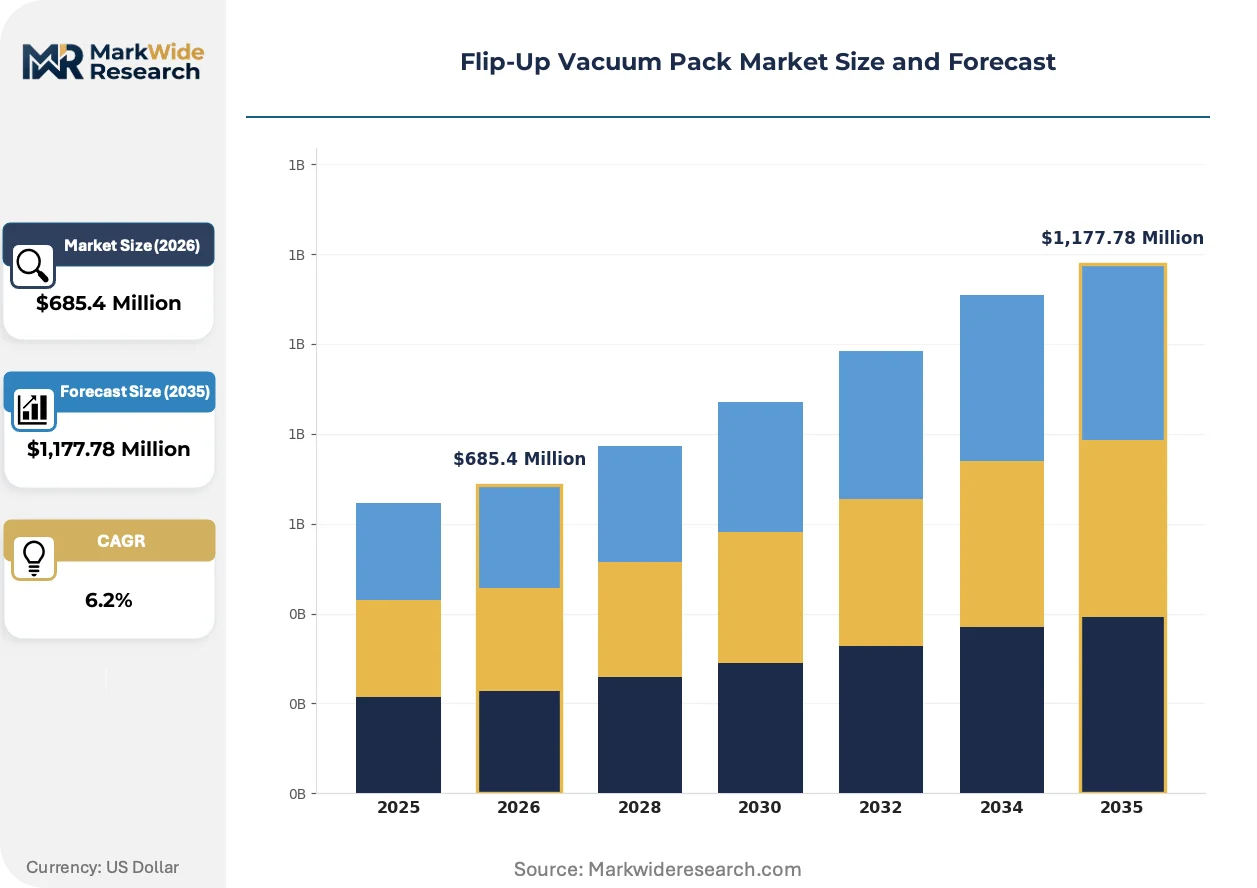
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Vacuum Packs, Industrial Vacuum Packs, Medical Vacuum Packs, Consumer Vacuum Packs Material: Plastic Composite, Aluminum Alloy, Stainless Steel, Polycarbonate Application: Food Preservation, Pharmaceutical Packaging, Electronics Packaging, Automotive Component Packaging End User: Food Processing Plants, Medical Facilities, Electronics Manufacturers, Vehicle Assembly Lines |
| Companies Covered | Sealed Air Corporation, Amcor plc, Berry Global Group, Bemis Company, EI du Pont de Nemours & Co, Coveris Holdings S.A., Winpak Ltd., Schur Flexibles Holding GesmbH, Multivac Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip-Up Vacuum Pack Market Shifts & Advancements
Dry scroll vacuum technology is compressing maintenance intervals and enabling oil-free operation in cleanroom-adjacent medical packaging environments previously dominated by rotary vane systems.
Scroll pump architecture is miniaturizing. Compact dry scroll systems now achieve vacuum levels below 50 mbar in chamber dimensions under 400mm, opening portable and benchtop configurations for surgical kit sterilization workflows. Medical device contract manufacturers in Switzerland and Germany are adopting these reduced-footprint units for just-in-time sterile barrier production. The technology is miniaturizing equipment procurement decisions, shifting capital allocation from centralized high-volume lines toward distributed cell-based packaging.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are pressuring sealing gasket formulations toward perfluoroelastomer alternatives with lower global warming potential. Thermoforming system suppliers must revalidate chamber integrity under revised compound specifications, extending type-approval timelines for European market entry. German industrial bakeries and meat processors face compressed procurement windows as 2027 phase-down deadlines approach.
Batch flexibility requirements are fragmenting equipment specifications. Food processing plants now demand chamber systems that transition from primal cut vacuum sealing to cheese wheel packaging without tooling changes, compressing supplier engineering cycles and fragmenting standardized product lines. This behavioral shift concentrates in Germany, where industrial bakeries and meat cooperatives operate mixed-product facilities requiring hourly batch rotation.
Flip-Up Vacuum Pack Market Segmentation
Flip-up vacuum pack procurement flows through distinct channel configurations, with industrial equipment distributors handling high-capacity systems while specialized medical device suppliers manage sterile barrier validation. Material specification and end-use certification requirements create parallel supply chains that rarely overlap.
Product Type:
Equipment flows through three primary channels: industrial distributors for food processing lines, medical device specialists for sterile barrier systems, and consumer electronics retailers for compact units.
- Industrial Vacuum Packs:Chamber dimensions above 800mm accommodate primal cuts and cheese wheels through oil-sealed rotary vane pumps achieving sub-50 mbar evacuation. Demand concentrates in German meat cooperatives and industrial bakeries retrofitting facilities for batch flexibility between protein and produce configurations.
- Medical Vacuum Packs:Sterile barrier validation under ISO 11607 governs surgical kit and implantable device tray applications, requiring dual protocol maintenance alongside food channel compliance. Swiss and German contract manufacturers are adopting miniaturized dry scroll systems for distributed cell-based production.
- Portable Vacuum Packs:Benchtop configurations under 400mm chamber dimensions serve field operations and small-scale food service.
- Consumer Vacuum Packs:Domestic kitchen units prioritize cost reduction over vacuum depth, typically achieving 100-200 mbar through diaphragm pumps.
By volume, Industrial Vacuum Packs leads. By growth pace, Medical Vacuum Packs is ahead.
Material:
Cost tiers separate validated barrier composites from commodity chamber construction, with premium positions commanding margin through regulatory qualification.
- Stainless Steel:316L grade dominates protein processing lines for corrosion resistance against blood and brine exposure, with German industrial bakeries specifying electropolished surfaces for dairy contact. EU REACH phthalate restrictions are accelerating fluoropolymer gasket adoption in these installations.
- Plastic Composite:Multilayer coextrusion films engineered for oxygen transmission control anchor barrier bag applications, though ethylene-vinyl alcohol supply concentration in Asian corridors exposes European packagers to input volatility.
- Aluminum Alloy:Cast chamber bodies reduce weight for portable configurations while maintaining vacuum integrity.
- Polycarbonate:Transparent lid panels enable visual batch monitoring in medical packaging environments.
Stainless Steel commands the premium tier. Plastic Composite handles the highest unit volumes.
Application:
Application mix reflects end-user consolidation patterns, with food processors bundling vacuum sealing into automated preservation lines while medical channels fragment across contract manufacturers.
- Food Preservation:Automated sealing lines compress batch changeover from hours to minutes, with FDA food contact substance notifications pressuring packagers toward validated barrier materials. German meat processors and industrial bakeries drive retrofit demand for modular chamber systems.
- Pharmaceutical Packaging:Sterile barrier requirements for implantable device trays remain underpenetrated relative to food preservation, offering margin expansion through healthcare specialization.
- Electronics Packaging:Moisture-sensitive component protection drives demand in semiconductor and display manufacturing clusters.
- Automotive Component Packaging:Precision parts and sensor modules require vacuum-sealed transport protection against corrosion.
Food Preservation maintains the largest installed base. Pharmaceutical Packaging is climbing the fastest.
End User:
Customer type determines specification intensity, with food processing plants prioritizing throughput and medical facilities demanding traceable validation documentation.
- Food Processing Plants:Mixed-product facilities in Germany require hourly batch rotation capabilities, forcing equipment suppliers to engineer tool-free chamber reconfiguration between primal cuts and cheese wheels.
- Medical Facilities:Surgical kit sterilization workflows in Switzerland and Germany are shifting capital allocation toward distributed cell-based packaging using compact dry scroll systems.
- Electronics Manufacturers:Cleanroom-adjacent production environments favor oil-free vacuum technology to eliminate contamination risk.
- Vehicle Assembly Lines:Just-in-time component delivery systems integrate vacuum sealing for corrosion-prone parts.
Food Processing Plants account for the dominant share of equipment shipments. Medical Facilities show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in Germany, the United States, and Switzerland dominate supply-side capacity for high-specification flip-up vacuum systems, while demand-side retrofit activity concentrates in German meat cooperatives and industrial bakeries facing compressed procurement windows.
Germany
Industrial bakeries and meat cooperatives in Bavaria and North Rhine-Westphalia drive retrofit demand for modular chamber systems enabling hourly batch rotation between primal cuts and cheese wheels. EU REACH phthalate restrictions accelerate fluoropolymer gasket adoption ahead of 2027 enforcement deadlines. The Stuttgart industrial corridor hosts thermoforming system integrators bundling flip-up vacuum chambers with automated loading modules.
United States
Food processing plants across the Midwest and Southeast prioritize automated sealing lines that compress changeover times from hours to minutes. FDA updated food contact substance notification requirements pressure packagers toward validated barrier materials. The Chicago meatpacking cluster and California Central Valley produce operations anchor equipment procurement volume.
Switzerland
Medical device contract manufacturers in the Basel-Zurich corridor adopt miniaturized dry scroll systems for distributed cell-based sterile barrier production. Swissmedic oversight of implantable device packaging complements ISO 11607 validation requirements. Geneva-area precision engineering firms supply compact vacuum chambers under 400mm for surgical kit sterilization workflows.
China
Domestic food processors in Shandong and Guangdong provinces expand vacuum sealing adoption for seafood and prepared meal preservation. SAMR food contact material standards tighten alongside GB standard updates for plastic composites. The Yangtze River Delta manufacturing belt produces chamber components and barrier films for regional equipment assemblers.
Japan
Electronics manufacturers in the Kanto and Kansai regions specify oil-free vacuum technology for cleanroom-adjacent moisture-sensitive component packaging. METI industrial efficiency guidelines encourage automated preservation line investment. Osaka-area precision machinery builders develop compact systems for semiconductor and display manufacturing clusters.
Flip-Up Vacuum Pack Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized thermoforming system integrators, creating a tiered structure where material science leaders and equipment specialists occupy distinct competitive vectors. Strategic archetypes include barrier film compounders leveraging coextrusion expertise, vacuum chamber fabricators bundling automation modules, and full-line integrators delivering validated sterile barrier systems. Dominant competitive moves encompass retrofit automation bundling for European meat cooperatives and qualification of alternative barrier composites ahead of FDA enforcement timelines.
Among packaging conglomerates with material science depth, Sealed Air Corporation and Amcor plc occupy positions anchoring premium-tier supply relationships through barrier film and chamber component portfolios. Multivac Group exemplifies the thermoforming system integrator archetype, representing European equipment bundling strategies that combine flip-up vacuum chambers with automated loading for mixed-product facilities. These three entities sit within distinct but overlapping competitive spheres, with material suppliers and equipment fabricators increasingly converging on automated preservation line specifications.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor plc |
| Berry Global Group |
| Bemis Company |
| EI du Pont de Nemours & Co |
| Coveris Holdings S.A. |
| Winpak Ltd. |
| Schur Flexibles Holding GesmbH |
| Multivac Group |
| Others |
Supply & Pricing Matrix
Fluoropolymer gasket substitution for phthalate-laden sealing compounds simultaneously redraws raw material sourcing maps toward Japanese and German specialty chemical suppliers and compresses margin structures for European equipment fabricators facing 2027 REACH enforcement deadlines. This input transition forces chamber manufacturers to absorb dual-running costs during qualification periods while German meat cooperatives and industrial bakeries negotiate harder on system pricing amid compressed procurement windows.
Pricing Analysis
EU REACH dictates the pricing tier structure across the flip-up vacuum pack landscape, separating validated fluoropolymer-compliant systems from legacy configurations facing obsolescence. Pricing stratifies across premium certified, standard industrial, and economy portable tiers, with ISO 11607 medical validation commanding substantial premiums over food-channel equivalents. Cost compression in standard industrial tiers is intensifying because German retrofit demand concentrates procurement leverage among meat cooperatives bundling multiple chamber purchases. Small-scale food service operators show highest price sensitivity, while Swiss medical device contract manufacturers exhibit lowest elasticity due to sterile barrier liability exposure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes disrupt ethylene-vinyl alcohol barrier film deliveries, exposing European packagers to input volatility. Supply concentrates in China for chamber component fabrication, Germany for thermoforming system integration, and Japan for precision vacuum pump manufacturing. Raw material dependencies span fluoropolymer resins, 316L stainless steel, and multilayer coextrusion films. Single-source vulnerability sits with Asian petrochemical corridors for EVOH supply. Distribution runs through industrial equipment distributors for food processing lines and specialized medical device suppliers for sterile barrier systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flip-up vacuum pack market operates as a regulatory entrenchment moat, where dual ISO 11607 and FDA validation protocols create switching costs that protect incumbent positions while raising barriers for challengers.
For Market Incumbents: Consolidate certification depth across healthcare and food channels to capture supplier list consolidation among end users. Absorb cross-sector compliance costs through volume scale in German retrofit markets. Defend against emerging dry scroll pump specialists by anchoring oil-sealed rotary vane reliability claims in primal cut processing lines. Channel control through bundling automated loading modules with chamber sales reinforces installed base lock-in. For New Entrants and Emerging Players: Aftermarket service coverage gaps in vacuum pump technician training present immediate white-space opportunity. Target Swiss and German medical device contract manufacturers adopting miniaturized dry scroll systems for distributed cell-based production. Portable surgical kit sterilization workflows remain underpenetrated relative to centralized food preservation lines. A rental-service go-to-market model bypasses capital expenditure barriers among mid-sized food processors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermoforming system integrators holding fragmented European market positions. Long-term viability frames around healthcare channel specialization as sterile barrier validation requirements deepen. Acquisition targets should show ISO 11607 certification depth plus installed base in German meat cooperatives. Watch FDA enforcement timeline acceleration on food contact substance notifications as inflection signal for barrier material substitution plays.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Gasket Qualification | EU REACH compliance secures German meat cooperative retrofit contracts ahead of 2027 deadlines. |
| Dry Scroll Pump Miniaturization | Compact oil-free systems penetrate Swiss medical device cleanroom environments previously closed to entrants. |
| Automated Loading Module Bundling | Thermoforming integrators capture Bavarian industrial bakery demand through unified capital project positioning. |
| Dual Protocol Certification Investment | ISO 11607 plus FDA food contact validation opens consolidated supplier relationships with multinational packagers. |
| Barrier Film Alternative Development | Non-EVOH composites reduce Asian petrochemical corridor exposure for European equipment fabricators. |
Research Methodology
A spread of perspectives from plant engineers at German meat cooperatives, procurement leads at Swiss medical device contract manufacturers, thermoforming system integrators, and aftermarket service technicians converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation through EU REACH regulatory filings, FDA food contact substance notification databases, ISO 11607 certification registries, and German industrial equipment import records. Bottom-up equipment shipment tallies triangulated against top-down end-user capital expenditure surveys.
Segmentation dimensions modeled include chamber size tier, vacuum pump technology type, end-use industry vertical, material specification grade, and geographic regulatory cluster across the projection horizon. CAGRs derived from curve-fitting historical shipment trajectories against announced retrofit project pipelines. Industry-specific forecast inputs encompass EU F-Gas Regulation phase-down schedules and FDA enforcement timeline signals on barrier material qualification.
Underlying assumptions cover sustained German retrofit demand concentration, stable ethylene-vinyl alcohol supply availability, and gradual dry scroll pump technical advancement, with deviation risk concentrated in accelerated REACH enforcement or Asian petrochemical corridor disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Woven Bags Market
Bags and Containers
Cooler Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Drum Liners Market
Bags and Containers
Liquid Packaging Bag Market