
 Jumbo Bags Market | 2026-2036
Jumbo Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Jumbo Bags Market Outlook
Chemical sector procurement is realigning toward multi-trip FIBC solutions as sustainability mandates tighten across OECD jurisdictions. Greif Inc. leverages its North American manufacturing footprint to dominate industrial packaging contracts. Mondi Group differentiates through integrated kraft paper and woven PP operations. Kanpur Plastipack Limited anchors South Asian supply with BIS-certified production lines serving agrochemical exporters.
Jumbo bags are large flexible containers, typically constructed from woven polypropylene fabric with load capacities ranging from 500 kg to 2,000 kg, designed for mechanized filling, lifting, discharge of dry flowable materials. FIBC variants command the largest volume share, while conductive bags capture premium pricing in electrostatic-sensitive chemical handling. Baffle bags sustain structural integrity during palletized stacking, creating margin concentration in food-grade and pharmaceutical-adjacent applications. Coated bags extend moisture protection for hygroscopic construction materials and agricultural commodities.
REACH compliance in Europe mandates full chemical disclosure for polypropylene additives used in food-contact jumbo bags. The EPA's industrial packaging guidelines in the United States shape recycling and reuse protocols for multi-trip containers. India's BIS certification requirements and China's GB/T 10454 standards for FIBC construction collectively raise barriers for uncertified manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional certification investments versus focused specialization in compliant export segments.
Market Dynamics
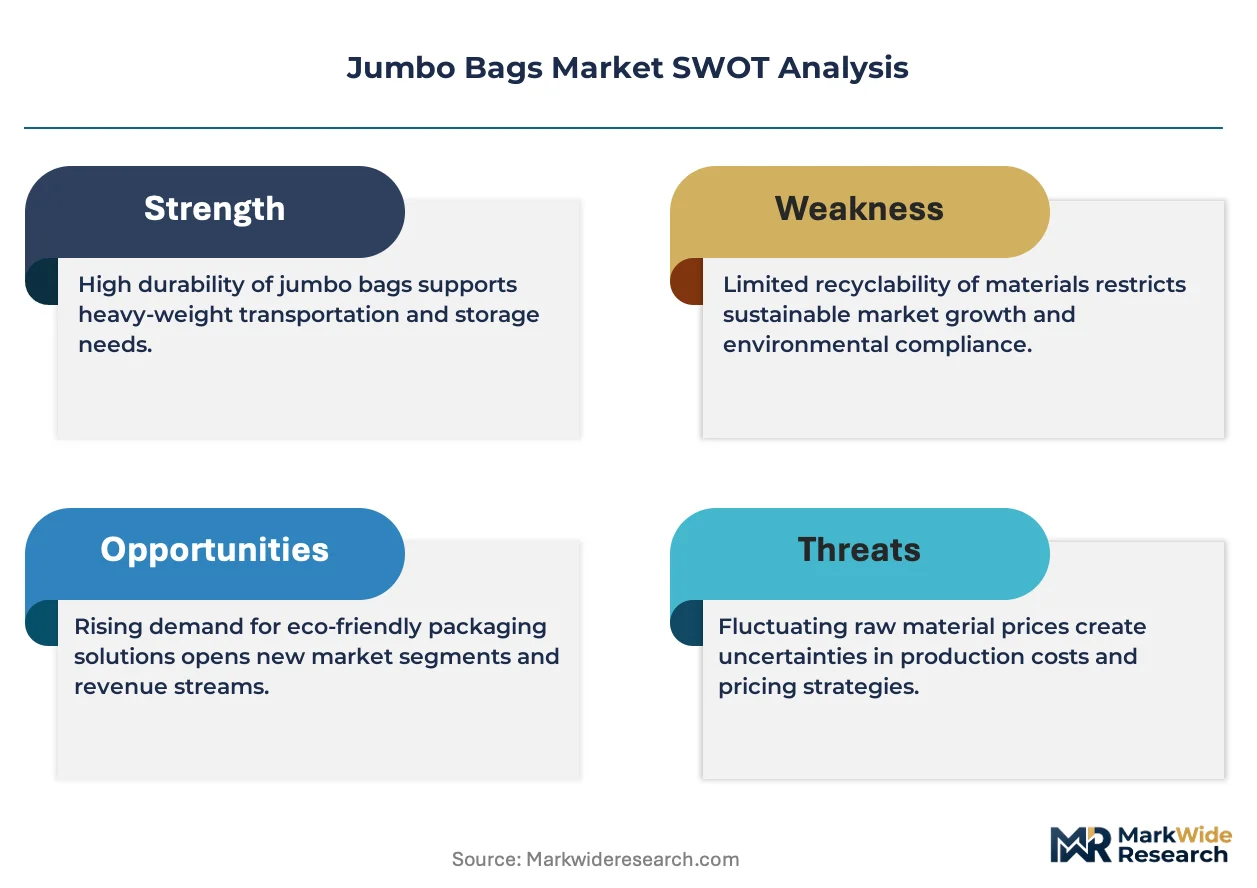
Sustainability mandates across OECD jurisdictions are forcing a structural pivot from single-use to multi-trip FIBC designs, compressing replacement cycles and rewiring procurement criteria toward lifecycle cost accounting.
Growth Catalysts
- REACH compliance mandates:Full chemical disclosure requirements for polypropylene additives in Europe are filtering out non-compliant suppliers and consolidating demand among certified manufacturers with traceable supply chains.
- Agrochemical export expansion:India's BIS certification push is concentrating procurement among Gujarat and Maharashtra producers qualified for regulated markets, creating captive demand pools.
- Conductive bag technology:Electrostatic-sensitive chemical handling applications are commanding premium positioning as pharmaceutical and fine chemical sectors tighten material safety protocols.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to naphtha and propylene monomer markets compress margin predictability for woven fabric converters without backward integration into polymer supply.
- Chinese supply concentration:GB/T 10454 certified production clusters in Jiangsu and Zhejiang provinces dominate export-ready capacity, creating geographic single-point vulnerability for buyers seeking compliance documentation.
- Woven PP substitution ceiling:Rigid intermediate bulk containers and bulk boxes capture share in high-frequency, closed-loop logistics where FIBC durability limits create functional boundaries.
Strategic Opportunities
- Extended producer responsibility frameworks:France's AGEC law and similar EU packaging waste directives are creating first-mover advantage for producers with verified closed-loop collection and reprocessing infrastructure.
- Food-grade baffle bag penetration:Structural integrity during palletized stacking opens pharmaceutical-adjacent and specialty food ingredient applications where bag deformation previously excluded FIBC formats.
- Digital printing integration:High-resolution QR-coded batch tracking is modularizing with woven PP production lines, enabling brand-owner compliance documentation and anti-counterfeiting at marginal cost increments.
Industry Challenges
- Multi-standard certification complexity:Simultaneous BIS, GB, and UN dangerous goods compliance requires dedicated regulatory affairs capacity that mid-scale producers struggle to staff.
- Coating line capex intensity:Moisture-barrier PE or PP lamination equipment demands seven-figure capital commitments that fragment the supplier base between coated and uncoated specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jumbo Bags Market |
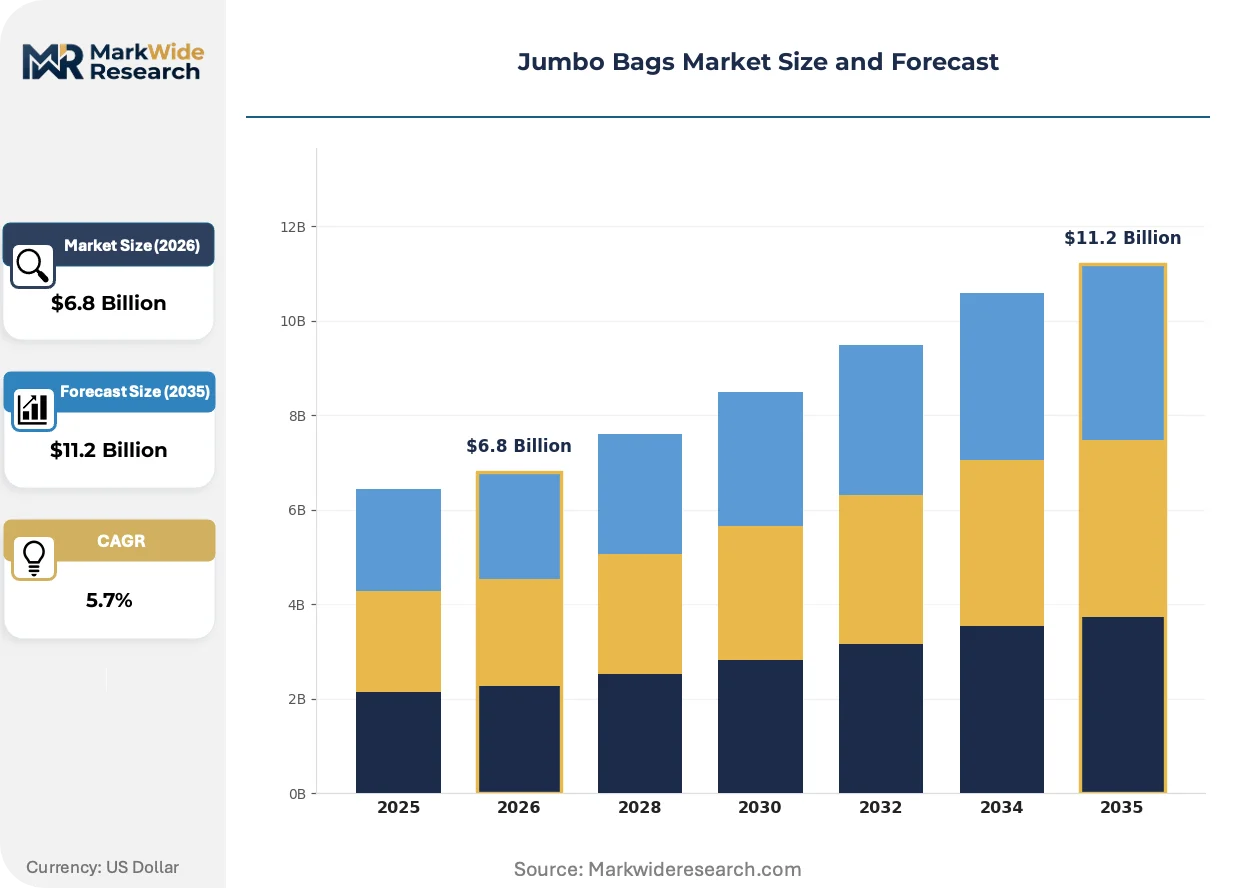
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FIBC, Baffle Bags, Conductive Bags, Coated Bags Material: polypropylene, PE, Cotton, Jute End User: Agriculture, Chemical, Construction, Food Application: Bulk Storage, Transportation, Packaging, Waste Management |
| Companies Covered | Berry Global Group Inc., Greif Inc., Conitex Sonoco, Mondi Group, Flexituff Ventures International Limited, Kanpur Plastipack Limited, Rishi Techtex Limited, Jumbo Bag Limited, EMMBI Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jumbo Bags Market Strategic Shifts
Active materials science and regulatory telemetry are converging to transform jumbo bags from commodity containers into traceable, condition-monitored assets with embedded compliance documentation.
Smart FIBC technology incorporating RFID tags and humidity sensors is modularizing around pharmaceutical and food-grade supply chains. Large chemical distributors in Germany and the Netherlands are piloting sensor-enabled bags for high-value hygroscopic materials. The technology is modularizing inventory management and reducing claims disputes by creating immutable chain-of-custody records.
REACH Article 33 disclosure obligations now extend to full additive manifests for food-contact polypropylene. European converters are requalifying supplier bases to exclude phthalate-based plasticizers and unverified UV stabilizers. Small-scale Asian exporters without in-house testing laboratories face exclusion from EU pharmaceutical and food ingredient supply chains.
Buyers in North American chemical distribution are consolidating vendor lists around full-service packaging partners with regional manufacturing and in-house reconditioning capabilities. Long-term service agreements with guaranteed swap programs are displacing transactional spot purchasing for multi-trip containers. This concentration is most visible in agricultural chemical distribution, where co-op buying groups now specify single-source FIBC management contracts spanning five-year horizons.
Jumbo Bags Market Segmentation
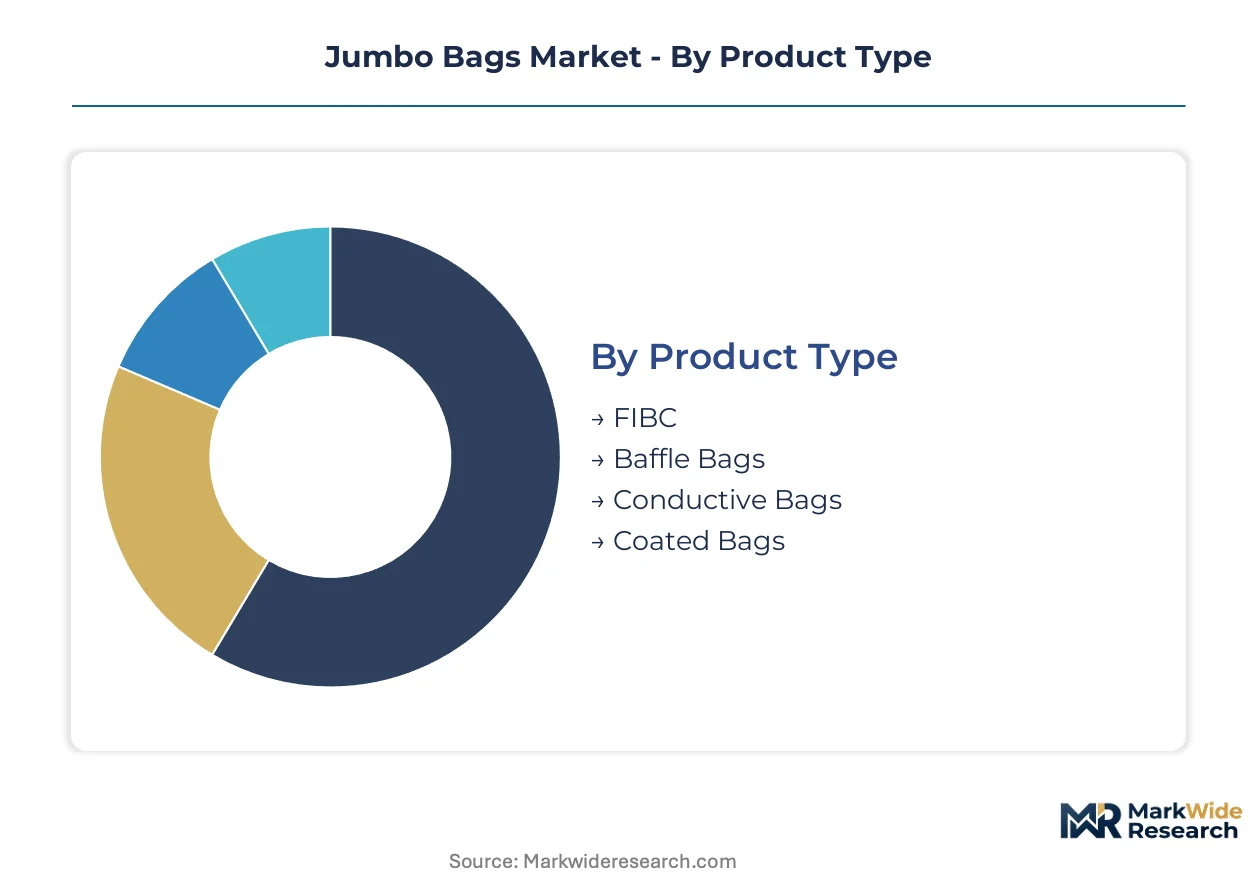
Jumbo bag procurement criteria diverge sharply across chemical handling, food-grade logistics, and construction workflows. Material safety protocols, moisture sensitivity, and stacking requirements create distinct product specifications that reshape supplier selection and margin structures.
Product Type:
Buyers differentiate primarily by electrostatic risk tolerance and structural load requirements rather than base capacity.
- FIBC:Standard woven polypropylene construction supports mechanized filling and discharge of dry flowable materials. Chemical distributors in Germany and the Netherlands specify FIBC for high-volume mineral and polymer handling where conductive properties remain unnecessary.
- Baffle Bags:Internal baffle panels maintain rectangular geometry during filling, enabling stable palletized stacking. Pharmaceutical ingredient suppliers in Switzerland and specialty food processors in Italy command premium positioning where bag deformation previously excluded flexible formats.
- Conductive Bags:Carbon-threaded fabric dissipates electrostatic charge for flammable powder handling. Fine chemical manufacturers in Japan and semiconductor material suppliers in South Korea mandate Type C certification under IEC 61340-4-4.
- Coated Bags:PE or PP lamination creates moisture barriers for hygroscopic construction materials and agricultural commodities. Cement exporters in Vietnam and fertilizer distributors in Brazil require coated specifications for tropical humidity exposure.
FIBC leads volumes today; baffle bags are gaining share fastest.
Material:
Feedstock selection traces directly to load cycling intensity and regulatory compliance burdens in target export markets.
- Polypropylene:Dominates woven fabric construction with tensile strength exceeding 8 grams per denier. REACH Article 33 disclosure mandates in Europe are filtering supplier bases to exclude phthalate-based plasticizers and unverified UV stabilizers.
- PE:Linear low-density formulations provide puncture resistance for abrasive mineral handling. Mining operations in Australia specify PE-coated variants for ore concentrate transport.
- Cotton:Natural fiber construction serves organic food certification requirements where synthetic contact triggers audit failures. Coffee and cocoa cooperatives in Colombia and Ethiopia mandate cotton for EU organic label compliance.
- Jute:Biodegradable alternative captures waste management and agricultural applications with single-use disposal economics. Indian municipal solid waste programs specify jute for compost collection infrastructure.
Polypropylene dominates installed capacity; cotton is climbing the fastest on organic certification premiums.
End User:
Sector procurement maturity ranges from transactional spot purchasing to multi-year service agreements with embedded reconditioning.
- Agriculture:Grain, seed, and fertilizer handling drives seasonal volume spikes with price-sensitive procurement patterns. Indian agrochemical exporters concentrate demand among BIS-certified Gujarat and Maharashtra producers qualified for regulated markets.
- Chemical:Fine chemical and pharmaceutical handling commands strictest material safety protocols with full additive traceability. ECHA REACH compliance filters out Asian exporters lacking in-house testing laboratories.
- Construction:Cement, sand, and aggregate handling prioritizes abrasion resistance over food-grade certification. Chinese GB/T 10454 certified production clusters in Jiangsu and Zhejiang provinces dominate export-ready capacity for Middle East infrastructure projects.
- Food:Ingredient and additive handling requires migration testing and phthalate-free certification. Swissmedic and EFSA alignment creates barrier to entry for uncertified converters.
Agriculture leads volumes today; food-grade applications show steepest expansion trajectory.
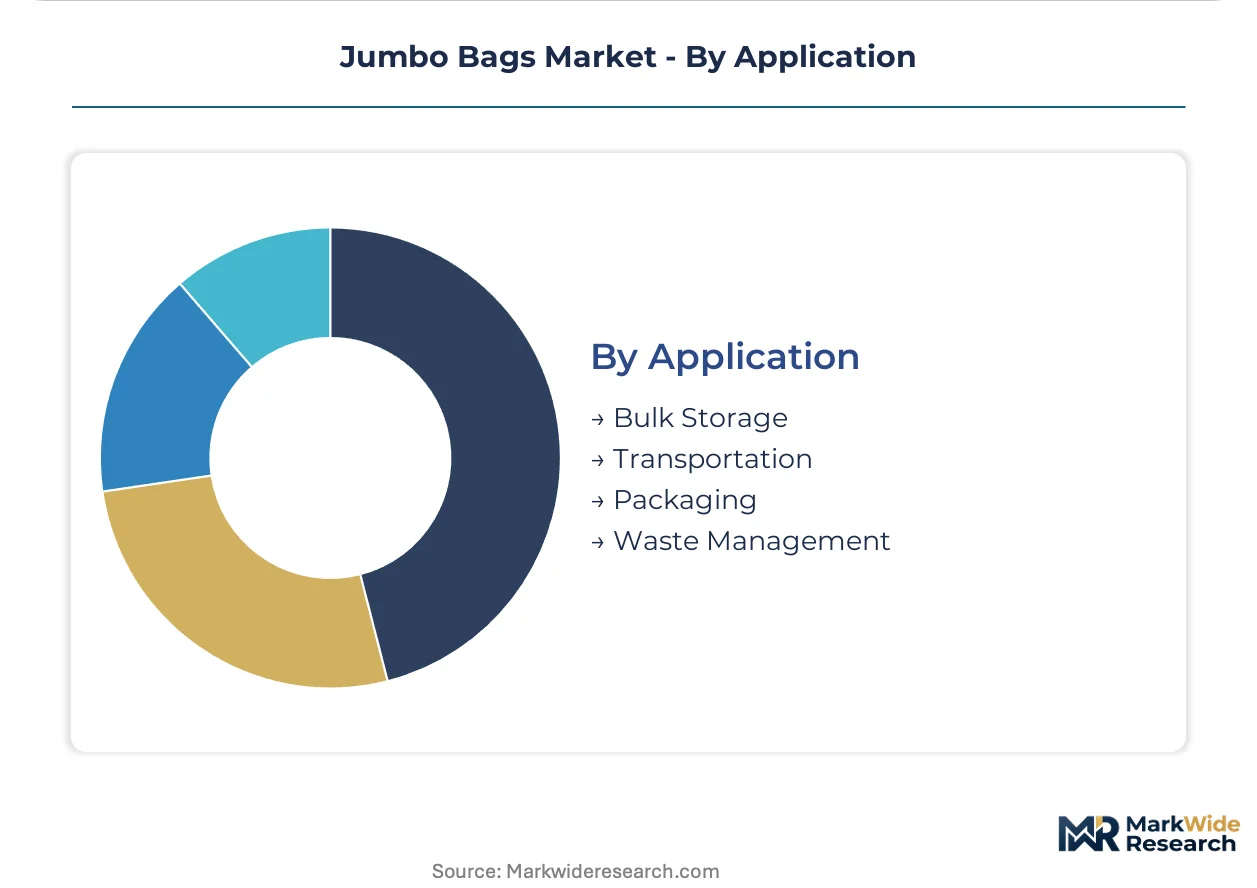
Application:
Workflow integration determines whether bags function as single-use consumables or depreciable assets in closed-loop systems.
- Bulk Storage:Extended warehouse holding demands UV stabilization and rodent-resistant construction. Agricultural cooperatives in the US Midwest specify multi-year storage ratings for grain reserve programs.
- Transportation:Rail and containerized shipping imposes dynamic load requirements and UN dangerous goods certification for hazardous materials. European chemical distributors consolidate vendor lists around full-service partners with regional manufacturing and in-house reconditioning.
- Packaging:Final-product presentation requirements drive digital printing integration for brand-owner compliance documentation. French AGEC law extended producer responsibility frameworks reward producers with verified closed-loop collection infrastructure.
- Waste Management:Single-use disposal economics favor lowest-unit-cost procurement without multi-trip durability specifications. Japanese construction debris regulations mandate specific tear-strength ratings for landfill-bound materials.
Transportation leads volumes today; packaging is expanding most quickly on traceability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as certification costs widen the gap between OECD-compliant and uncertified manufacturing bases. Producers migrate toward jurisdictions offering streamlined compliance pathways without sacrificing export market access.
United States
Agricultural chemical co-ops and industrial mineral distributors drive FIBC procurement through five-year service agreements with embedded reconditioning. EPA industrial packaging guidelines shape recycling protocols for multi-trip containers. Midwest grain reserve programs concentrate demand around UV-stabilized bulk storage specifications in Iowa and Illinois.
Germany
Large chemical distributors pilot sensor-enabled smart FIBC technology for high-value hygroscopic materials. ECHA REACH Article 33 mandates full additive disclosure for food-contact polypropylene, filtering supplier bases to exclude phthalate-based plasticizers. Industrial clusters in North Rhine-Westphalia consolidate vendor lists around full-service packaging partners with regional manufacturing.
China
GB/T 10454 certified production clusters in Jiangsu and Zhejiang provinces dominate export-ready capacity for Middle East infrastructure projects. MIIT enforcement of dual carbon goals pressures design upgrades across flexible intermediate bulk container manufacturing. Yangtze River Delta fabricators face margin compression from propylene monomer price volatility.
India
Agrochemical exporters concentrate procurement among BIS-certified producers in Gujarat and Maharashtra qualified for regulated markets. CDSCO alignment with international pharmaceutical standards creates barrier to entry for uncertified converters. Mumbai-Pune industrial corridor anchors South Asian supply with export-qualified manufacturing lines.
Brazil
Fertilizer distributors require coated bag specifications for tropical humidity exposure during bulk commodity handling. ANVISA pharmaceutical packaging regulations filter imported FIBC suppliers without migration testing documentation. São Paulo state chemical distributors consolidate procurement around regional reconditioning capabilities.
Jumbo Bags Market Competitive Environment
Capacity expansion dominates the current landscape as certified producers scale coating lines and reconditioning infrastructure to capture multi-trip service contracts. The vendor base stratifies between integrated multinational packaging groups and regional specialists with single-certification focus. Three archetypes define competitive positioning: full-service industrial packaging conglomerates with backward polymer integration, mid-scale regional fabricators with BIS or GB-certified export specialization, and niche conductive bag producers serving electrostatic-sensitive chemical handling. Geographic expansion and strategic partnerships represent the dominant competitive moves, with producers seeking regional manufacturing footprints to shorten logistics cycles for chemical distributors.
Among North American industrial packaging groups, Greif Inc. and Berry Global Group Inc. exemplify the integrated conglomerate archetype with captive supply chain control over polymer sourcing and regional reconditioning networks. Mondi Group anchors European positioning through kraft paper and woven PP integration. Kanpur Plastipack Limited represents the export-specialist tier with BIS-certified production serving agrochemical export corridors from Maharashtra.
| Leading Market Players |
|---|
| Berry Global Group Inc. |
| Greif Inc. |
| Conitex Sonoco |
| Mondi Group |
| Flexituff Ventures International Limited |
| Kanpur Plastipack Limited |
| Rishi Techtex Limited |
| Jumbo Bag Limited |
| EMMBI Industries Limited |
| Others |
Value Chain & Pricing Dynamics
REACH Article 33 disclosure mandates gate both qualified supply and premium-tier pricing access by filtering out polypropylene converters lacking full additive traceability. European chemical distributors now pay measurable premiums for REACH-certified FIBC with documented phthalate-free plasticizer content.
Pricing Analysis
Distributor margins absorb certification compliance costs before end-user pricing. Three-tier pricing structure across Type C conductive, food-grade baffle, and standard FIBC levels reflects electrostatic risk and migration testing burdens. Pricing pressure stems from propylene monomer volatility squeezing woven fabric converters without backward polymer integration. Agricultural cooperatives exhibit highest price sensitivity; pharmaceutical ingredient suppliers accept premium positioning for full traceability.
Supply Chain Analysis
Woven polypropylene supply rests on propylene monomer production concentrated in China, Saudi Arabia, and the United States. Fabric conversion draws from specialized tape extrusion lines, circular looms, and coating lamination equipment. Single-source vulnerability concentrates in Jiangsu and Zhejiang province clusters where GB/T 10454 certification dominates export-ready capacity. Distribution runs through chemical distributor networks with embedded reconditioning capabilities rather than spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through multi-trip service contract bundling that captures lifecycle value beyond single-unit transactions. Premium-tier food-grade and conductive bag segments widen spreads as REACH and IEC certification barriers filter competition.
For Market Incumbents: To counter propylene price volatility eroding converter margins, prioritize backward integration into polymer supply or captive coating line capacity in regional manufacturing clusters. Strengthen reconditioning infrastructure to capture five-year service agreement renewals from agricultural chemical co-ops consolidating vendor lists. For New Entrants and Emerging Players: Smart FIBC technology with embedded RFID and humidity sensors offers white-space entry into pharmaceutical and food-grade supply chains where traceability premiums offset higher unit costs. Target Swiss and German chemical distributors piloting sensor-enabled bags for hygroscopic materials with direct OEM partnership models bypassing distributor markup layers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale BIS-certified Indian producers because CDSCO alignment with international pharmaceutical standards creates acquisition currency for export corridor access. Watch ECHA enforcement patterns on REACH Article 33 as inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Greif and Berry Global mitigate propylene volatility through captive resin production. |
| Multi-Trip Service Contract Expansion | Five-year agreements with embedded reconditioning displace spot purchasing in North American agricultural chemical distribution. |
| Smart FIBC Technology Deployment | RFID and sensor integration creates immutable chain-of-custody records for German pharmaceutical distributors. |
| Food-Grade Baffle Bag Capacity Addition | Swissmedic-aligned production captures pharmaceutical-adjacent applications where bag deformation previously excluded flexible formats. |
| Regional Reconditioning Network Buildout | São Paulo and Mumbai-Pune infrastructure supports closed-loop collection under France's AGEC law extended producer responsibility frameworks. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each combining interviews with plant managers at woven fabric converters, procurement leads at chemical distributors, regulatory affairs directors, and aftermarket service heads with secondary validation from customs/trade data, SEC 10-K filings, and BIS certification registries. Bottom-up and top-down triangulation cross-checks capacity utilization rates against end-use demand modeling.
Rate-of-change decomposition across the analysis window segments volume and value by product type, material grade, end-use industry, and regional production hub. CAGRs derive from fitted growth curves applied to base-year consumption data adjusted for propylene price elasticity and certification penetration rates in OECD jurisdictions.
The model holds under stable regulatory enforcement intensity; deviation in ECHA REACH audit frequency or MIIT dual carbon goal acceleration would shift supply concentration and pricing premiums. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Inclusion Bags Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Leno Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Craft Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Packaging Peanuts Market