
 Filler Masterbatch Market | 2026-2036
Filler Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Filler Masterbatch Market Intelligence
Calcium carbonate is rebalancing filler masterbatch economics as compounders reduce virgin polymer loadings without sacrificing tensile performance. Plastika Kritis S.A. leverages integrated quarry-to-pellet operations across the Mediterranean basin to control raw mineral costs. LyondellBasell Industries anchors its position through captive polypropylene supply chains that feed directly into masterbatch compounding lines. Plastiblends India Ltd. specializes in custom color-filler combinations for South Asian packaging converters seeking single-source procurement.
Filler masterbatch denotes a concentrated blend of mineral fillers, typically calcium carbonate, talc, or barium sulfate, dispersed within a thermoplastic carrier resin at loadings of 40-80% by weight, extruded into granules or pellets for downstream dilution. The primary purpose is to reduce material cost, improve dimensional stability, and modify surface properties in injection-molded or extruded plastic articles. Polyethylene-based formulations dominate flexible packaging applications where film clarity and seal strength requirements govern carrier selection, while polypropylene grades lead automotive and appliance segments demanding higher heat deflection temperatures. Granule form maintains handling advantages across high-volume extrusion lines, though powder variants penetrate rotational molding and certain PVC plastisol operations where dry-blend integration matters.
REACH registration requirements under ECHA govern filler surface treatments and additive packages entering European Union plastics value chains, while EPA industrial emissions standards shape compounding facility siting decisions in the United States. China's GB standards for plastic articles in food contact, administered by SAMR, dictate calcium carbonate purity thresholds and extraction limits for masterbatch destined to domestic packaging markets. BIS certification marks on imported filler concentrates create compliance friction for suppliers targeting India's construction piping and cable sheathing sectors. Stakeholders must monitor regulatory divergence between mineral sourcing disclosures and end-product recyclability mandates to anticipate reformulation investments and regional capacity allocation shifts.
Market Dynamics
Automotive lightweighting mandates and packaging circularity targets are compressing virgin polymer consumption, forcing compounders to rebalance mineral loadings against mechanical performance thresholds. REACH registration requirements and evolving food-contact purity standards are simultaneously tightening formulation flexibility and certification timelines.
Growth Catalysts
- Automotive lightweighting programs:Germany's KBA and US NHTSA fuel-economy targets push calcium carbonate-filled compounds into bumper substrates and interior panels, cutting part weight without sacrificing impact resistance.
- REACH surface-treatment compliance:ECHA registration requirements for silane-coated fillers create preferential sourcing relationships between European compounders and certified mineral processors, locking in supply security.
- China's eastern manufacturing corridor:Packaging converters in Jiangsu and Zhejiang provinces dual-source masterbatch for domestic food-grade film exports and regional construction piping, concentrating demand in integrated polymer hubs.
Market Restraints
- Calcium carbonate feedstock volatility:Energy-intensive quarrying operations face natural gas price swings that transmit directly into pellet cost structures, squeezing compounder margins during upstream spikes.
- Single-source talc concentration:High-purity steatite deposits cluster in limited Appalachian and Alpine formations, creating geographic supply vulnerability for automotive heat-deflection formulations.
- Recycled-content contamination limits:FDA and EFSA extraction thresholds for post-consumer polyolefins restrict mineral loading levels in food-contact masterbatch, capping cost-reduction potential.
Strategic Opportunities
- India's construction piping upgrade cycle:BIS certification requirements for pressure-rated PVC compounds create captive demand for barium sulfate-filled masterbatch in cable sheathing and irrigation systems.
- Biodegradable carrier convergence:PLA and PHA matrix compatibility with mineral fillers opens compostable packaging segments previously closed to conventional polyolefin masterbatch.
- Direct-to-converter digital distribution:Specialty compounders bypass traditional distributor networks to serve mid-volume rotational molders via configured-to-order pellet platforms, capturing margin previously lost to intermediaries.
Industry Challenges
- Compounder formulation talent scarcity:Mineral surface chemistry expertise and twin-screw extrusion optimization skills concentrate among retiring specialists, constraining R&D throughput for custom color-filler combinations.
- Multi-certification timeline compression:Simultaneous SAMR food-contact, BIS construction-grade, and REACH additive-package approvals extend product launch cycles, freezing working capital in pre-qualified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filler Masterbatch Market |
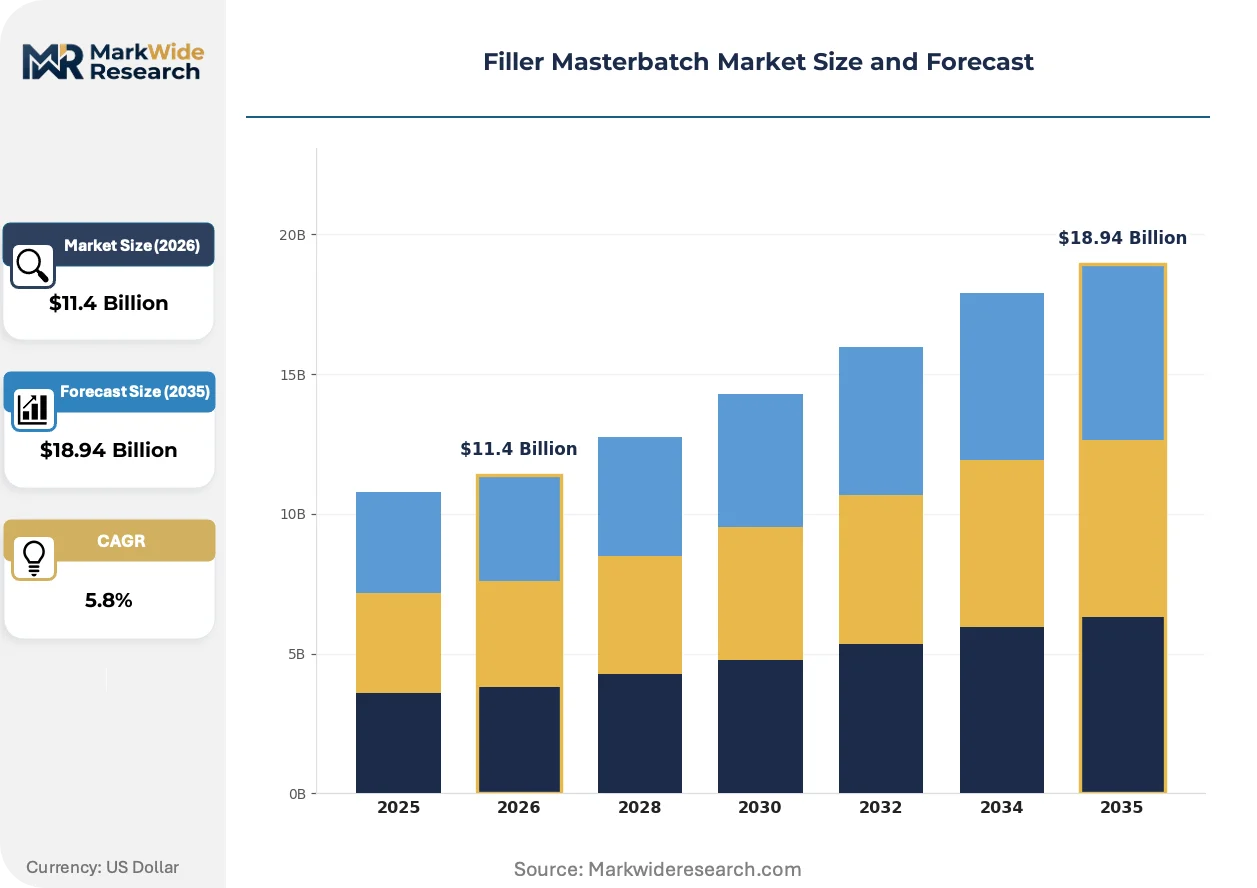
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, PVC, ABS Application: Automotive, Packaging, Construction, Consumer Goods End User: OEMs, Manufacturers, Distributors, Retailers Form: Granules, Powder, Pellets, Liquid |
| Companies Covered | Plastika Kritis S.A., Plastiblends India Ltd., LyondellBasell Industries, Shivam Polychem, Megaplast, GCR Group, European Plastic Company, Alok Masterbatches Pvt. Ltd., Bajaj Superpack India Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filler Masterbatch Market Strategic Shifts & Innovations
Surface-functionalized nanofillers and reactive extrusion processes are rewriting the performance-cost frontier, enabling loadings that previously degraded mechanical properties. Regulatory divergence between jurisdictions is fragmenting formulation portfolios, while procurement centralization among multinational converters is compressing supplier bases.
Surface-modified calcium carbonate with stearic acid and silane treatments is expanding into thin-gauge blown film applications where optical haze and seal strength once blocked mineral adoption. European flexible packaging converters serving frozen food and hygiene markets are trialing 25-30% loadings in multilayer structures. The technology is expanding into premium film segments previously reserved for virgin resin, compressing the cost gap between mineral-filled and unfilled alternatives.
EPA industrial emissions standards under the Clean Air Act are reshaping compounding facility siting decisions in the US Gulf Coast and Ohio River Valley corridors. New source review requirements for particulate matter and volatile organic compound thresholds favor greenfield investments with integrated dust collection over legacy plant retrofits. Masterbatch producers targeting automotive OEMs in Michigan and Tennessee are prioritizing permitted sites with rail-served bulk mineral handling to preempt compliance-driven supply interruptions.
Converter procurement consolidation is compressing approved supplier lists from regional fragmentation toward single-source national contracts with technical service guarantees. Mid-tier packaging groups in China's Pearl River Delta are centralizing masterbatch buying through designated platform distributors that bundle credit terms, formulation support, and just-in-time delivery. The shift is most visible in food-grade film extrusion, where SAMR compliance documentation and batch traceability requirements favor integrated suppliers with captive laboratory certification capabilities.
Filler Masterbatch Market Segmentation
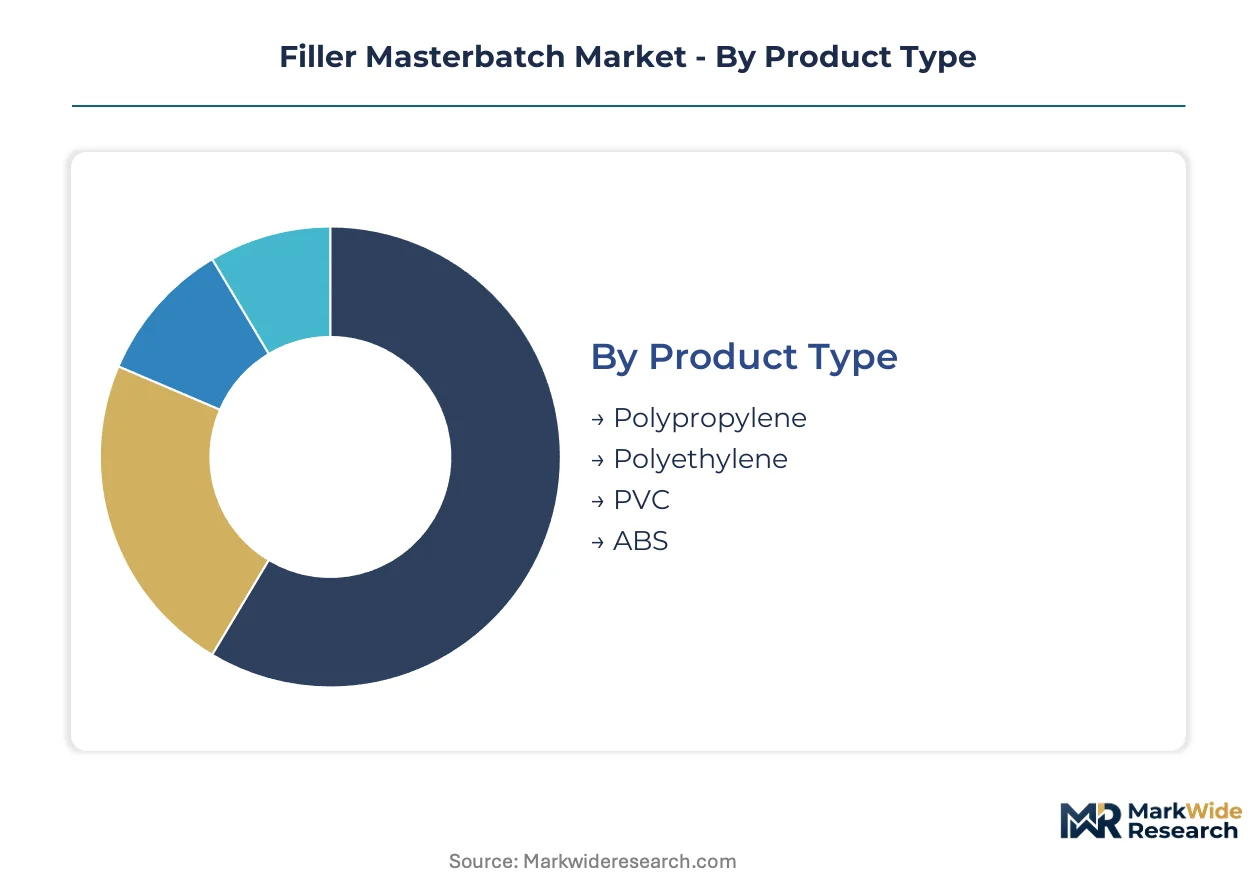
Filler masterbatch segmentation tracks how carrier resin chemistry, downstream application requirements, and physical form factors dictate procurement patterns across converter tiers. Each dimension shapes compounding technology choices and regional capacity allocation decisions differently.
Product Type:
Upgrade cycles in automotive interior panels and flexible packaging films are driving reformulation investments across all carrier resin categories as compounders rebalance mineral loadings against mechanical performance thresholds.
- Polypropylene:High heat-deflection formulations serve automotive bumper substrates and appliance housings requiring dimensional stability above 100°C. Demand clusters in Germany's KBA-mandated lightweighting programs and Tennessee automotive supplier parks where OEMs specify calcium carbonate-filled grades for injection-molded interior panels.
- Polyethylene:Low-density and linear-low variants dominate multilayer blown film for frozen food and hygiene packaging where seal strength and optical clarity govern carrier selection. Jiangsu province converters are trialing 25-30% mineral loadings in export-grade film structures.
- PVC:Rigid and plasticized formulations anchor construction piping and cable sheathing applications across India's BIS-certified pressure-rated compound segment.
- ABS:Specialty grades penetrate appliance housings and consumer electronics enclosures demanding surface aesthetics combined with cost reduction.
Polypropylene sits at the top of the volume ranking, with polyethylene climbing the fastest as packaging circularity targets compress virgin resin consumption.
Application:
Cost tier differentiation separates specification-grade automotive compounds from commodity construction grades, with margin structures varying by certification burden and technical service intensity.
- Automotive:OEM-directed lightweighting mandates in Michigan and Stuttgart push calcium carbonate-filled compounds into structural components previously reserved for unfilled resins. Tier-1 suppliers specify masterbatch with validated impact resistance and emissions compliance documentation.
- Packaging:Food-contact purity requirements under FDA and EFSA extraction thresholds restrict mineral loading levels, capping cost-reduction potential in domestic film markets while export-oriented Chinese converters pursue higher loadings for non-contact layers.
- Construction:Pressure-rated PVC piping and irrigation systems across India's eastern states generate captive demand for barium sulfate-filled masterbatch with BIS certification marks.
- Consumer Goods:Rotational molding and injection-molded houseware applications favor granule forms with custom color-filler combinations for mid-volume converters.
Automotive commands premium pricing tiers, with packaging expanding most quickly as surface-modified nanofillers penetrate thin-gauge film segments.
End User:
Customer type determines whether procurement flows through distributor networks with credit terms and technical support, or direct-to-converter digital platforms capturing margin previously lost to intermediaries.
- OEMs:Automotive and appliance original equipment manufacturers specify masterbatch through approved supplier lists with locked formulations, multi-year volume commitments, and captive laboratory certification capabilities.
- Manufacturers:Tier-2 and tier-3 converters in China's Pearl River Delta centralize buying through platform distributors bundling SAMR compliance documentation and just-in-time delivery.
- Distributors:Regional stocking intermediaries serve mid-volume rotational molders and specialty compounders with configured-to-order pellet platforms and formulation support.
- Retailers:Private-label packaging converters and small-batch houseware producers purchase through wholesale channels with limited technical service attachment.
Manufacturers represent the largest addressable base by transaction count, with OEMs capturing value through specification lock-in and multi-year supply agreements.
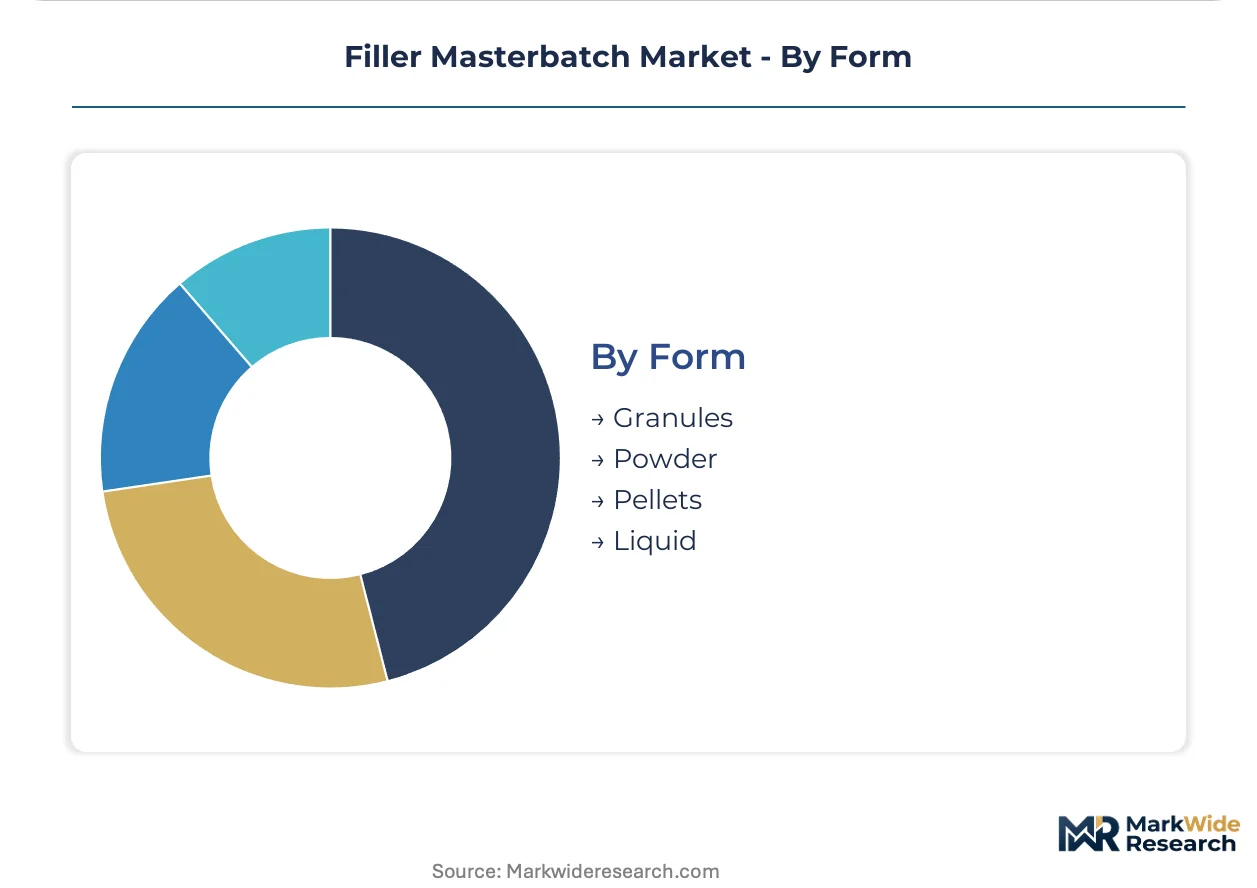
Form:
Supply concentration around high-volume extrusion lines favors granule handling systems, while powder and liquid alternatives penetrate niche operations where dry-blend integration or liquid dosing equipment justifies form-specific capital investment.
- Granules:Standard extruded pellets dominate high-throughput film and injection molding lines across integrated polymer hubs in Zhejiang and Ohio River Valley corridors.
- Powder:Finely ground mineral concentrates serve rotational molding and certain PVC plastisol operations where dry-blend integration eliminates pellet melting steps.
- Pellets:Precision-cut cylindrical forms optimize bulk density for rail-served bulk mineral handling and automated conveying systems.
- Liquid:Pumpable dispersions penetrate continuous extrusion lines with liquid dosing equipment, primarily in European flexible packaging converters seeking rapid color changeover.
Granules maintain volume leadership across all major geographies, with powder gaining share fastest in rotational molding segments previously constrained by pellet feeding limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates the highest volume of filler masterbatch consumption, with Jiangsu and Zhejiang provinces anchoring integrated polymer hubs that serve both export-oriented packaging and domestic construction piping. Automotive lightweighting mandates in Germany and the United States are redrawing regional demand patterns as calcium carbonate-filled compounds penetrate structural components.
China
Packaging converters in Jiangsu province dual-source masterbatch for food-grade film exports and regional construction piping, while Zhejiang's integrated polymer hubs trial 25-30% mineral loadings in multilayer blown film structures. SAMR-administered GB standards for food-contact plastics dictate calcium carbonate purity thresholds and extraction limits. The Pearl River Delta's platform distributors are centralizing procurement for mid-tier converters bundling compliance documentation and just-in-time delivery.
Germany
KBA-mandated fuel-economy targets push calcium carbonate-filled compounds into bumper substrates and injection-molded interior panels for Stuttgart-based automotive OEMs. REACH registration requirements under ECHA govern silane-coated filler surface treatments and additive packages entering EU plastics value chains. The Rhine-Ruhr industrial corridor hosts compounders with validated impact resistance documentation serving tier-1 automotive suppliers.
United States
NHTSA fuel-economy standards drive lightweighting programs embedding mineral-filled compounds into Michigan and Tennessee automotive supplier parks. EPA industrial emissions standards under the Clean Air Act reshape compounding facility siting decisions, favoring greenfield investments with integrated dust collection over legacy retrofits. The Ohio River Valley corridor concentrates rail-served bulk mineral handling for high-throughput extrusion lines.
India
BIS certification requirements for pressure-rated PVC compounds generate captive demand for barium sulfate-filled masterbatch in cable sheathing and irrigation systems across eastern states. Construction piping upgrade cycles in Maharashtra and Gujarat create specification-grade opportunities for certified mineral concentrates. Domestic packaging converters seek single-source procurement for custom color-filler combinations.
Filler Masterbatch Market Key Industry Players
Capacity expansion dominates the current landscape as compounders add twin-screw extrusion lines to capture automotive and packaging volume growth. The vendor base stratifies across integrated mineral processors with quarry-to-pellet operations, polyolefin producers with captive masterbatch compounding, and specialty formulators serving regional converter networks. Two archetypes define competitive positioning: backward-integrated mineral owners controlling raw material costs, and carrier-resin producers leveraging polymer supply chain proximity. Geographic expansion and formulation certification capabilities represent the dominant competitive moves as suppliers pursue multi-jurisdiction approval portfolios.
Among Mediterranean-based integrated operators, Plastika Kritis S.A. exemplifies the quarry-to-pellet archetype with mineral sourcing advantages, while LyondellBasell Industries anchors the carrier-resin-integrated tier through polypropylene supply chain control. Plastiblends India Ltd. occupies a position within the specialty formulation segment serving South Asian packaging converters. These three patterns—mineral backward integration, polymer supply chain leverage, and regional custom formulation—illustrate how competitive positioning fragments across cost structure and service intensity vectors.
| Leading Market Players |
|---|
| Plastika Kritis S.A. |
| Plastiblends India Ltd. |
| LyondellBasell Industries |
| Shivam Polychem |
| Megaplast |
| GCR Group |
| European Plastic Company |
| Alok Masterbatches Pvt. Ltd. |
| Bajaj Superpack India Ltd. |
| Others |
Cost & Logistics Intelligence
OEM specification tightening for calcium carbonate purity and SAMR food-contact documentation compresses formulation flexibility, forcing compounders to absorb certification costs or cede share to integrated mineral processors with captive laboratory capabilities. This demand-side pressure stratifies pricing power along backward-integration lines.
Pricing Analysis
Input-cost pass-through from energy-intensive quarrying operations runs directly into pellet cost structures, with natural gas price volatility squeezing compounder margins during upstream spikes. Three-tier pricing structure across premium, standard, and economy levels separates REACH-validated automotive grades from commodity construction compounds. Pricing pressure stems from recycled-content contamination limits capping mineral loadings in food-contact masterbatch. Tier-1 automotive suppliers exhibit lowest price sensitivity due to specification lock-in, while mid-volume rotational molders drive hardest bargaining through digital procurement platforms.
Supply Chain Analysis
Workforce availability constraints in Germany's Rhine-Ruhr corridor and China's Jiangsu province concentrate twin-screw extrusion expertise among retiring specialists, constraining R&D throughput for custom formulations. Supply concentrates in China, Germany, and the United States, with raw material dependencies on high-purity steatite deposits from Appalachian and Alpine formations and calcium carbonate from Mediterranean quarries. Single-source talc concentration creates geographic supply vulnerability for automotive heat-deflection formulations. Distribution runs through platform distributors in China's Pearl River Delta bundling compliance documentation with just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filler masterbatch functions as a stable compounder, with automotive lightweighting mandates and packaging circularity targets driving steady polymer substitution demand across multiple industrial cycles.
For Market Incumbents: Anchor market position through captive mineral sourcing investments that preempt feedstock volatility transmission. Prioritize multi-certification capabilities spanning SAMR food-contact, BIS construction-grade, and REACH additive-package approvals to freeze working capital in pre-qualified inventory. Defend against specialty compounders bypassing distributor networks via configured-to-order pellet platforms by locking converter relationships through technical service guarantees. For New Entrants and Emerging Players: Platform distributors serving mid-tier packaging groups in China's Pearl River Delta represent the most penetrable channel partner type for market entry. Target biodegradable carrier convergence segments where PLA and PHA matrix compatibility opens compostable packaging applications previously closed to conventional polyolefin masterbatch. Pursue direct-to-converter digital distribution models capturing margin previously lost to intermediaries in rotational molding segments. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated mineral processors possessing quarry-to-pellet operations and validated multi-jurisdiction certification portfolios. Long-term viability centers on compounders with captive laboratory capabilities and rail-served bulk mineral handling infrastructure. Monitor EPA industrial emissions enforcement and ECHA REACH registration timeline compression as inflection indicators for regional capacity reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Captive quarry operations in Mediterranean basin insulate Plastika Kritis from calcium carbonate feedstock volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous SAMR, BIS, and REACH approvals extend product launch cycles but lock in converter switching costs. |
| Direct-to-Converter Digital Platform | Specialty compounders bypass traditional distributors to serve mid-volume rotational molders with configured-to-order pellets. |
| Biodegradable Carrier Development | PLA and PHA matrix compatibility opens compostable packaging segments previously closed to polyolefin masterbatch. |
| Rail-Served Bulk Mineral Handling Infrastructure | Greenfield investments with integrated dust collection preempt EPA Clean Air Act compliance-driven supply interruptions. |
Research Approach
Coverage spans China, Germany, the United States, and India, with primary inputs from each region's manufacturing corridors. Primary interviews with masterbatch plant managers, procurement leads at automotive Tier 1 suppliers, packaging converter technical directors, and distribution channel partners combined with secondary validation from customs/trade data, SEC 10-K filings, ECHA REACH registration databases, and SAMR GB standard disclosures. Bottom-up volume modeling triangulated against top-down polymer consumption forecasts.
Rate-of-change decomposition across carrier resin chemistry, downstream application requirements, and physical form factors shaped the analytical framework. Segmentation dimensions modeled include polypropylene versus polyethylene versus PVC carrier grades, automotive versus packaging versus construction end-uses, and granule versus powder versus liquid form factors. CAGRs derived from mineral loading trend extrapolation, polymer substitution elasticity estimates, and regional regulatory compliance timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA emissions enforcement intensity, ECHA REACH registration backlog clearance rates, and natural gas price volatility transmission into quarrying economics. Forecasts reflect assumptions around specification-grade automotive demand persistence and packaging circularity target stringency. Material deviation in automotive OEM lightweighting program commitment or SAMR food-contact purity threshold revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Superacids Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Tosyl Chloride Market