
 Joint Compound Market | 2026-2036
Joint Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Joint Compound Market Analysis
Lightweight gypsum core technology is rewriting how joint compound achieves coverage and sandability without added weight. Saint-Gobain leverages its integrated gypsum sourcing network to control raw material quality from quarry to finished product. Knauf Gips KG anchors European supply through dense manufacturing footprints in Germany and Austria. USG Corporation dominates the North American contractor channel with specialized formulations for automated taping tools.
Joint compound is a gypsum-based paste or powder, typically containing limestone, perlite, and vinyl or acrylic binders, engineered to fill seams between drywall panels and create smooth, paint-ready surfaces. Ready-mixed formulations lead volume due to labor savings on commercial job sites, while spray applications represent the fastest-growing category as mechanical finishing displaces hand taping in large-scale residential developments. Dry bagged products retain margin strength in renovation and repair segments where small-batch flexibility matters more than speed.
OSHA enforces permissible exposure limits for respirable crystalline silica during joint compound sanding, pushing manufacturers toward dust-control additives and wet-sanding compatibility. EPA guidelines on volatile organic compounds influence binder selection and product labeling requirements across interstate commerce. ECHA REACH restrictions on hazardous additives affect import formulations entering European distribution channels. Stakeholders must weigh formulation compliance costs against the pricing power of certified low-emission product lines as regulatory thresholds tighten without predictable timing.
Market Dynamics
Mechanical finishing systems are compressing labor hours on large-scale drywall projects, forcing formulation chemists to engineer joint compounds for pumpability and automated tape application rather than traditional hand-taping workflows.
Growth Catalysts
- OSHA Silica Rule:The agency's respirable crystalline silica exposure limits are accelerating dust-control additive adoption across ready-mixed product lines.
- Residential renovation cycles:Aging housing stock in the United States sustains repair-driven consumption of small-batch dry bagged formulations.
- Spray application technology:Mechanical finishing equipment is displacing hand taping in multi-unit residential developments, lifting demand for pump-compatible compounds.
Market Restraints
- Gypsum supply concentration:Quarry ownership clusters among integrated building materials conglomerates, constraining independent compound manufacturers' input cost flexibility.
- Limestone price volatility:Energy-intensive calcination processes expose margins to natural gas price swings in key production regions.
- Wet-sanding infrastructure gaps:Commercial job sites lack water recovery systems, limiting adoption of silica-mitigation protocols despite regulatory pressure.
Strategic Opportunities
- Lightweight core chemistry:Perlite and glass microsphere formulations enable coverage expansion without freight cost penalties, opening specification opportunities in high-rise construction.
- EPA VOC guidelines:Low-emission certification pathways create pricing power for compliant product lines in interstate commerce.
- Prefabricated wall panel integration:Offsite construction factories require compounds compatible with factory-controlled curing environments rather than field-variable conditions.
Industry Challenges
- Taper skill attrition:Mechanical finishing adoption is outpacing training pipeline output, creating operator shortages for hybrid hand-machine workflows.
- REACH compliance timelines:ECHA additive restrictions force reformulation cycles that lag certification requirements by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Joint Compound Market |
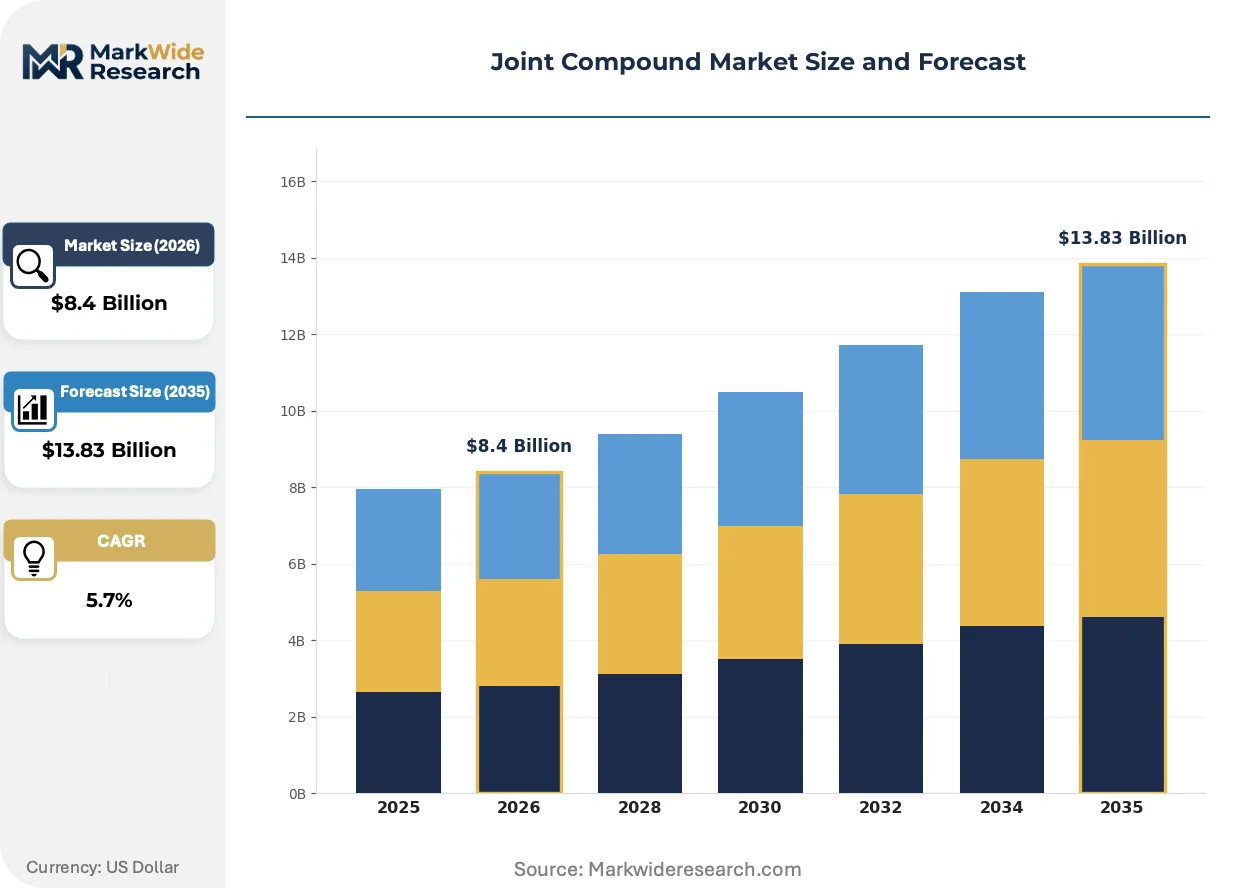
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-Mixed, Dry, Spray, Pre-Mixed Application: Commercial, Residential, Industrial, DIY Distribution Channel: Retail, Wholesale, Online, Direct Sales End Use: Construction, Renovation, Repair, Maintenance |
| Companies Covered | Compagnie de Saint-Gobain S.A, DAP Products Inc, National Gypsum Company, Knauf Gips KG, USG Corporation, Freeman Products Inc, Solid Products Inc, Hamilton Drywall Products, Pladur Gypsum, S.A.U., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Joint Compound Market Emerging Trajectories
Formulation chemistry and application machinery are converging to redefine performance benchmarks for coverage, sandability, and installation speed. Manufacturers now engineer compounds for specific equipment interfaces rather than universal hand-tool compatibility.
Lightweight gypsum core technology incorporating expanded perlite and engineered glass microspheres is rendering obsolete traditional heavyweight compounds in commercial specifications. Large-scale drywall contractors in the United States are specifying these formulations for high-rise projects where freight costs and worker fatigue compound traditional material penalties. The shift is compressing demand for standard-density bagged products in new construction verticals.
REACH restrictions on hazardous additive classifications are forcing European compound importers to reformulate binder systems ahead of sunset dates. ECHA's evolving substance evaluation lists are eliminating certain vinyl acetate copolymer chemistries from approved formulations. German and Austrian manufacturers with captive gypsum supply chains are responding fastest, while distributors of Asian-imported compounds face 12-18 month certification gaps.
Mechanical finishing contractors are consolidating procurement around single-source supply agreements that bundle compound, equipment, and technical service. Traditional distributor relationships based on product availability alone are losing share to integrated vendor partnerships in the United States multi-family residential segment. This concentration is most visible in Sun Belt metro areas where production homebuilders dominate drywall specification.
Joint Compound Market Segmentation
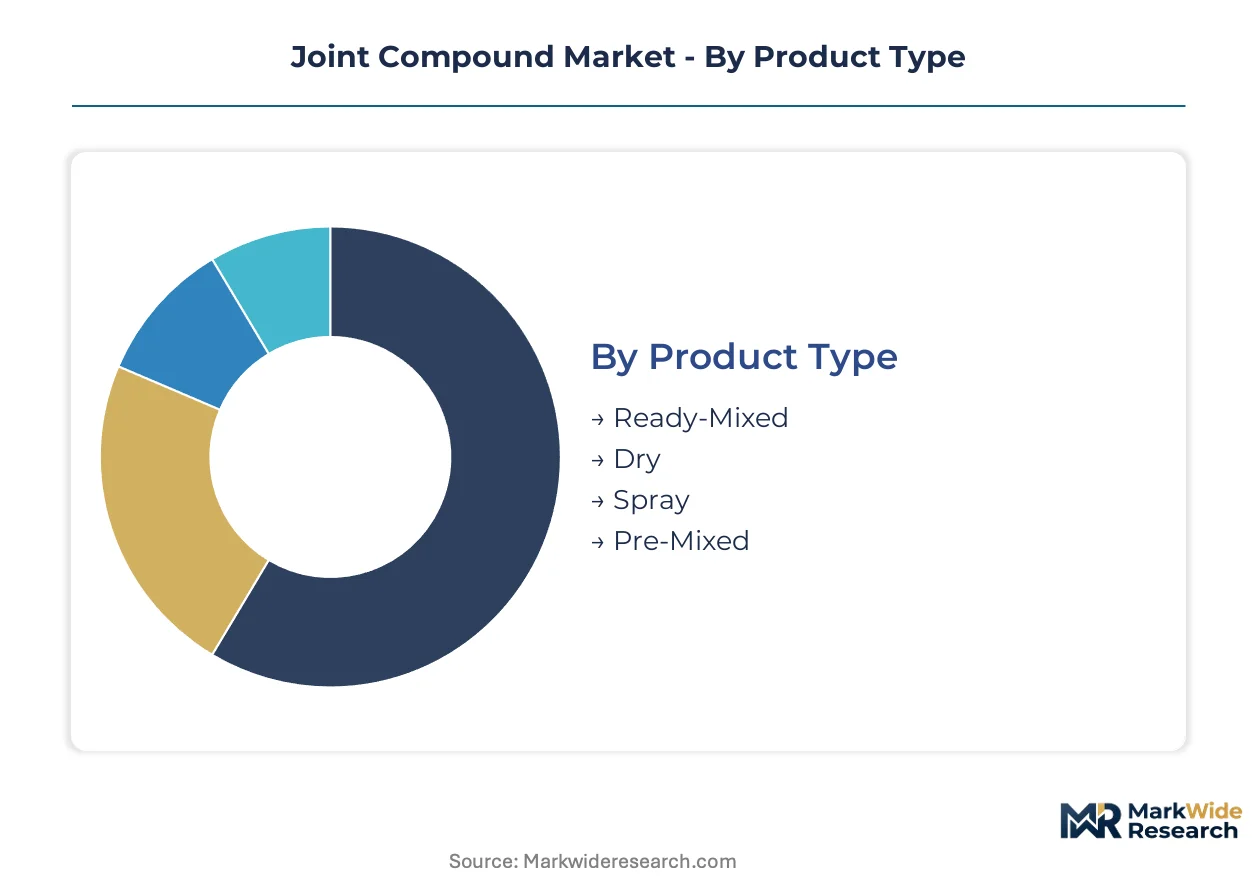
Joint compound manufacturers engineer formulations for distinct application workflows, each demanding tailored technical support and equipment compatibility. Segmentation by product type, application, distribution channel, and end use determines pricing architecture and service intensity across the value chain.
Product Type:
After-sales-service intensity varies sharply across product formats, with spray systems requiring equipment calibration support and ready-mixed formulations demanding shelf-life guidance.
- Ready-Mixed:Pre-hydrated gypsum paste with vinyl or acrylic binders, delivered in buckets or totes for immediate application. Demand concentrates in United States commercial job sites where labor savings outweigh per-unit cost premiums; OSHA silica exposure limits accelerate wet-formulation preference over dry alternatives.
- Spray:Low-viscosity compounds engineered for mechanical pumping through automated taping tools. Multi-unit residential developments in Sun Belt metros specify these formulations; pumpability requirements and equipment compatibility create higher technical service touchpoints than hand-tape products.
- Dry:Powdered gypsum-limestone blends requiring on-site water addition. Small-batch flexibility sustains demand in renovation segments where project scale varies unpredictably.
- Pre-Mixed:Factory-blended formulations with extended working time additives. Specialty contractors favor these for decorative finishing applications requiring extended open times.
Ready-Mixed holds the largest share; momentum sits with Spray as mechanical finishing expands.
Application:
Cost tier differentiation separates specification-grade commercial compounds from economy residential formulations, with industrial applications demanding chemical resistance additives that command premium positioning.
- Commercial:High-coverage, lightweight formulations specified for office towers and institutional buildings. United States high-rise construction drives volume; freight cost sensitivity in urban cores favors perlite-reduced weight compounds.
- Residential:Standard-density products for single-family and multi-family drywall installation. Production homebuilders in Texas and Florida metro areas consolidate procurement around bundled compound-equipment-service agreements.
- Industrial:Mold-resistant and chemical-resistant formulations for manufacturing facilities, food processing plants, and cleanroom environments. EPA VOC guidelines constrain binder selection in interstate commerce.
- DIY:Small-package ready-mixed products sold through retail channels. Repair-cycle demand from aging United States housing stock sustains volume despite lower per-transaction value.
Commercial commands the highest value per pound; residential delivers the steepest expansion trajectory through production housing volume.
Distribution Channel:
Customer type determines channel economics, with mechanical finishing contractors bypassing traditional distribution for direct manufacturer partnerships while independent contractors remain anchored to wholesale availability.
- Retail:Big-box home improvement stores and specialty building material outlets serving DIY and small contractor segments. Shelf-space competition favors national brands with marketing support infrastructure.
- Wholesale:Regional and national distributors maintaining local inventory for professional contractors. Traditional relationships face pressure from integrated vendor partnerships in multi-family residential markets.
- Online:E-commerce platforms capturing specification research and small-order fulfillment. Limited penetration for bulk commercial orders due to freight cost and equipment bundling requirements.
- Direct Sales:Manufacturer-to-contractor agreements for large-scale projects with dedicated technical service. Fastest-growing channel as mechanical finishing consolidates procurement.
Wholesale retains the largest share; direct sales channels are climbing the fastest through equipment bundling.
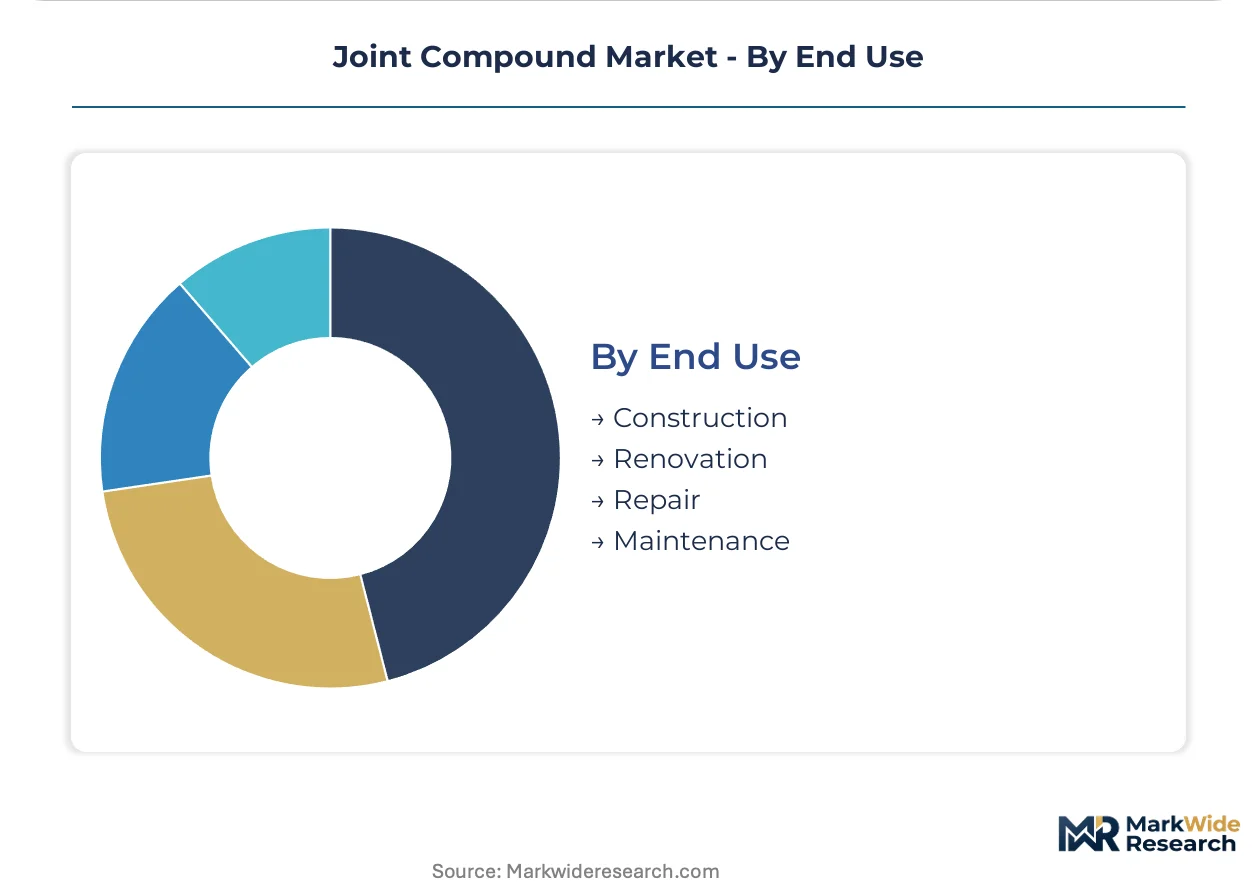
End Use:
Volume concentration in new construction versus repair-driven demand shapes formulation packaging, shelf-life requirements, and inventory turnover economics across the supply chain.
- Construction:New-build drywall installation specifying lightweight, high-coverage compounds for speed. United States multi-family residential towers in Miami, Houston, and Phoenix drive pump-compatible formulation demand.
- Renovation:Whole-unit remodeling requiring flexible batch sizing and color-matching compatibility. Aging housing stock in Northeast and Midwest metros sustains dry bagged product preference.
- Repair:Spot-fixing and damage remediation using small-format ready-mixed containers. Seasonal weather damage cycles in Gulf Coast and Atlantic seaboard states create demand spikes.
- Maintenance:Institutional and commercial facility upkeep with scheduled re-coating protocols. Healthcare and education facilities specify low-VOC, low-odor formulations for occupied-space work.
Construction holds the largest share; renovation is gaining share fastest through housing stock age demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechanical finishing contractors in the United States consolidate procurement around bundled supply agreements, while European compound importers navigate ECHA reformulation deadlines. Asian production clusters serve domestic construction volume with limited export penetration.
United States
Production homebuilders in Texas and Florida metro areas specify pump-compatible formulations for multi-family residential towers. OSHA silica exposure limits accelerate wet-sanding protocol adoption across commercial job sites. Miami, Houston, and Phoenix anchor demand concentration for spray application systems in high-rise drywall installation.
Germany
Captive gypsum supply chains in Bavaria and North Rhine-Westphalia enable rapid REACH compliance turnaround. ECHA restrictions on vinyl acetate copolymer chemistries force binder system substitutions ahead of sunset dates. Stuttgart and Munich manufacturing clusters supply lightweight perlite formulations across Central European commercial specifications.
China
Domestic construction volume in Yangtze River Delta and Pearl River Delta metros absorbs most national compound production. MEE emissions standards tighten calcination plant permitting in Shandong and Hebei provinces. Shanghai and Shenzhen high-rise developers specify locally manufactured lightweight core products for freight cost containment.
Canada
Aging housing stock in Ontario and Quebec sustains renovation-driven demand for small-batch dry bagged products. Health Canada guidelines on construction material emissions influence binder selection for products entering interstate commerce. Toronto and Montreal distribution networks serve independent contractors with flexible batch sizing.
Mexico
Residential development in Nuevo León and Jalisco drives ready-mixed formulation consumption from US-sourced supply chains. Federal environmental standards on industrial emissions shape local manufacturing investment decisions. Mexico City metro area contractors balance imported product availability against domestic production scale-up.
Joint Compound Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a structure where integrated gypsum sourcing separates tier-one suppliers from formulation-only competitors. Saint-Gobain, Knauf, and USG anchor the concentrated tier through quarry ownership and captive raw material pipelines. Mid-scale regional compounders survive on renovation segment flexibility and distributor relationships. Dominant competitive moves include backward integration into gypsum mining and equipment bundling partnerships with mechanical finishing contractors.
Among European-based integrated suppliers, Compagnie de Saint-Gobain S.A. and Knauf Gips KG exemplify the quarry-to-finished-product archetype through captive gypsum networks. USG Corporation occupies a parallel position in North American contractor channels. These three entities represent the scale-driven tier where raw material control determines specification access and pricing power in commercial drywall projects.
| Leading Market Players |
|---|
| Compagnie de Saint-Gobain S.A |
| DAP Products Inc |
| National Gypsum Company |
| Knauf Gips KG |
| USG Corporation |
| Freeman Products Inc |
| Solid Products Inc |
| Hamilton Drywall Products |
| Pladur Gypsum, S.A.U. |
| Others |
Supply Flow & Price Mechanics
Great Lakes freight corridors from Canadian gypsum quarries to United States manufacturing plants transmit natural gas cost volatility directly into landed raw material expenses, amplifying price differentiation between integrated producers with captive quarry access and independent compounders forced into spot-market limestone purchases.
Pricing Analysis
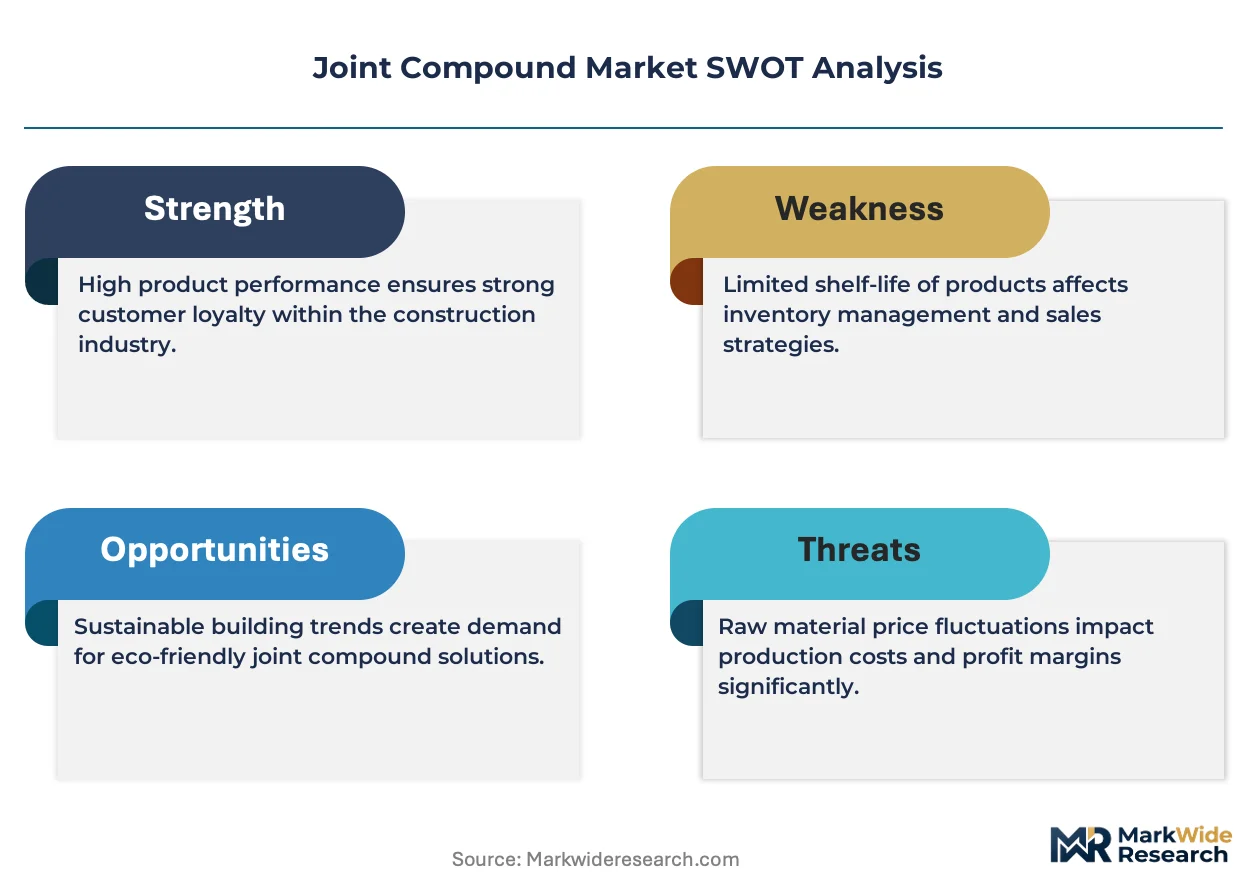
Cost-plus contracts indexed to Henry Hub natural gas benchmarks dominate procurement between independent compound manufacturers and industrial gypsum suppliers. Three-tier pricing structure across premium low-VOC certified, standard commercial-grade, and economy dry-bagged formulations separates specification-grade projects from renovation segments. Pricing pressure stems from energy-intensive calcination processes exposing margins to fuel cost swings. Production homebuilders exhibit highest price sensitivity through consolidated volume tenders, while healthcare facility contractors prioritize certified low-emission products despite premium positioning.
Supply Chain Analysis
Contract manufacturing concentration rests with Saint-Gobain's integrated quarry-to-plant network in Nova Scotia and Michigan, Knauf's captive Bavarian gypsum operations, and USG's North American production clusters. Geographic supply concentration clusters in Canada, Germany, and the United States for high-purity gypsum feedstock; China and Mexico serve regional demand with limited cross-border penetration. Raw material dependencies center on natural gas for calcination energy, perlite ore for lightweight formulations, and vinyl acetate copolymers for binder systems. Single-source vulnerability runs through concentrated quarry ownership among three integrated conglomerates. Distribution runs through wholesale building material distributors facing erosion from direct manufacturer-to-contractor partnerships in mechanical finishing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against advanced panel systems and prefabricated wall assemblies that eliminate field joint finishing entirely.
For Market Incumbents: Harden specification control through captive gypsum quarry investments in Michigan and Nova Scotia to secure input cost stability against limestone price volatility. Deepen equipment bundling partnerships with mechanical finishing contractors in Sun Belt metro areas to lock out independent compound distributors. Prioritize EPA low-VOC certification pathways that command pricing power in interstate commerce and create technical barriers for reformulation-lagged importers. For New Entrants and Emerging Players: Southeast Asian manufacturing cost advantages in Vietnam and Indonesia offer white-space entry points for export-focused dry-bagged production targeting Australian and Pacific Rim renovation markets. Prefabricated construction factory supply agreements represent the most penetrable segment, as offsite builders seek compounds compatible with controlled curing environments rather than field-variable conditions. Lead with technical service intensity around pump calibration and automated taping tool compatibility to differentiate from commodity wholesale distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from building materials conglomerates divesting non-core compound formulation divisions to focus on upstream gypsum mining or downstream distribution assets. Long-term viability across the analysis window hinges on regulatory compliance agility and mechanical finishing equipment integration depth. Watch ECHA additive restriction sunset dates and OSHA silica enforcement patterns as inflection indicators for competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gypsum Quarries | Captive Nova Scotia and Michigan quarry access secures raw material cost stability against natural gas price volatility. |
| Mechanical Finishing Equipment Partnership | Sun Belt metro contractor bundling agreements displace traditional wholesale distribution channels in multi-family residential. |
| EPA Low-VOC Certification Investment | Interstate commerce compliance creates pricing power and technical barriers for reformulation-lagged European importers. |
| Prefabricated Panel Factory Supply Agreement | Offsite construction growth requires compounds engineered for factory-controlled curing rather than field-variable conditions. |
| Lightweight Core Chemistry R&D | Perlite and glass microsphere formulations reduce freight costs for high-rise specifications in Miami and Phoenix towers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC building materials filings, EPA emissions compliance databases, and ECHA REACH substance evaluation lists. Primary interviews covered plant managers at integrated gypsum producers, procurement leads at multi-family residential contractors, distribution channel partners in wholesale building supply, and technical R&D directors at formulation specialists. Bottom-up volume estimates from product-type and application segmentation triangulate against top-down construction spending and housing stock age demographics.
Forecast inputs include natural gas price trajectory assumptions, OSHA silica enforcement intensity projections, and mechanical finishing equipment adoption curves across United States metro areas. Segmentation dimensions modeled encompass product format, application workflow, distribution channel type, and end-use construction phase. CAGRs derive from regression analysis against historical construction permit data and renovation cycle frequency patterns. Industry-specific inputs incorporate ECHA additive restriction sunset timelines and production homebuilder procurement consolidation trends.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-scale regional compounders or accelerated prefabricated construction adoption would shift outcomes beyond modeled ranges. Quarterly review of ECHA substance evaluation updates, OSHA enforcement action filings, and mechanical finishing equipment shipment data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Microcapsules Market