
 HVAC Air Handling Units Market | 2026-2036
HVAC Air Handling Units Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Air Handling Units Market Analysis
Multi-source procurement of heat exchangers and fan assemblies is hardening as OEMs seek supply resilience against component volatility. Daikin Industries leverages captive manufacturing of refrigeration circuits to protect margin pools. Carrier Global Corporation anchors North American distribution through direct contractor relationships. Johnson Controls International plc differentiates via building automation integration that bundles AHUs with controls software.
An HVAC air handling unit is an engineered assembly comprising fans, filters, heating and cooling coils, and dampers housed within a metal casing, designed to condition and circulate air at specified volumetric flow rates measured in cubic feet per minute. These systems serve as the central respiratory mechanism for commercial and institutional buildings, regulating temperature, humidity, and particulate concentration to maintain occupant health and equipment protection. Modular units command premium positioning in healthcare and laboratory verticals where phased capacity expansion and contamination isolation protocols dictate flexible infrastructure. Smart control systems are capturing the fastest expansion trajectory as BACnet and IoT-enabled diagnostics shift maintenance from reactive breakdown response to predictive asset management. Rooftop units remain the mature volume category across retail and light commercial footprints where single-package simplicity minimizes installation labor.
The EPA enforces refrigerant management standards under Section 608 of the Clean Air Act, directly governing coil specifications and leak detection requirements for installed AHUs. The EU F-Gas Regulation and CE marking under the Machinery Directive collectively constrain market access for non-compliant equipment while accelerating replacement demand across Europe's installed base. ASHRAE Standard 62.1 ventilation rate requirements and ISO 16890 filter testing protocols further elevate product performance thresholds that manufacturers must certify. Stakeholders must monitor how refrigerant phase-down schedules intersect with filter efficiency upgrades to anticipate which product configurations will capture retrofit specification wins.
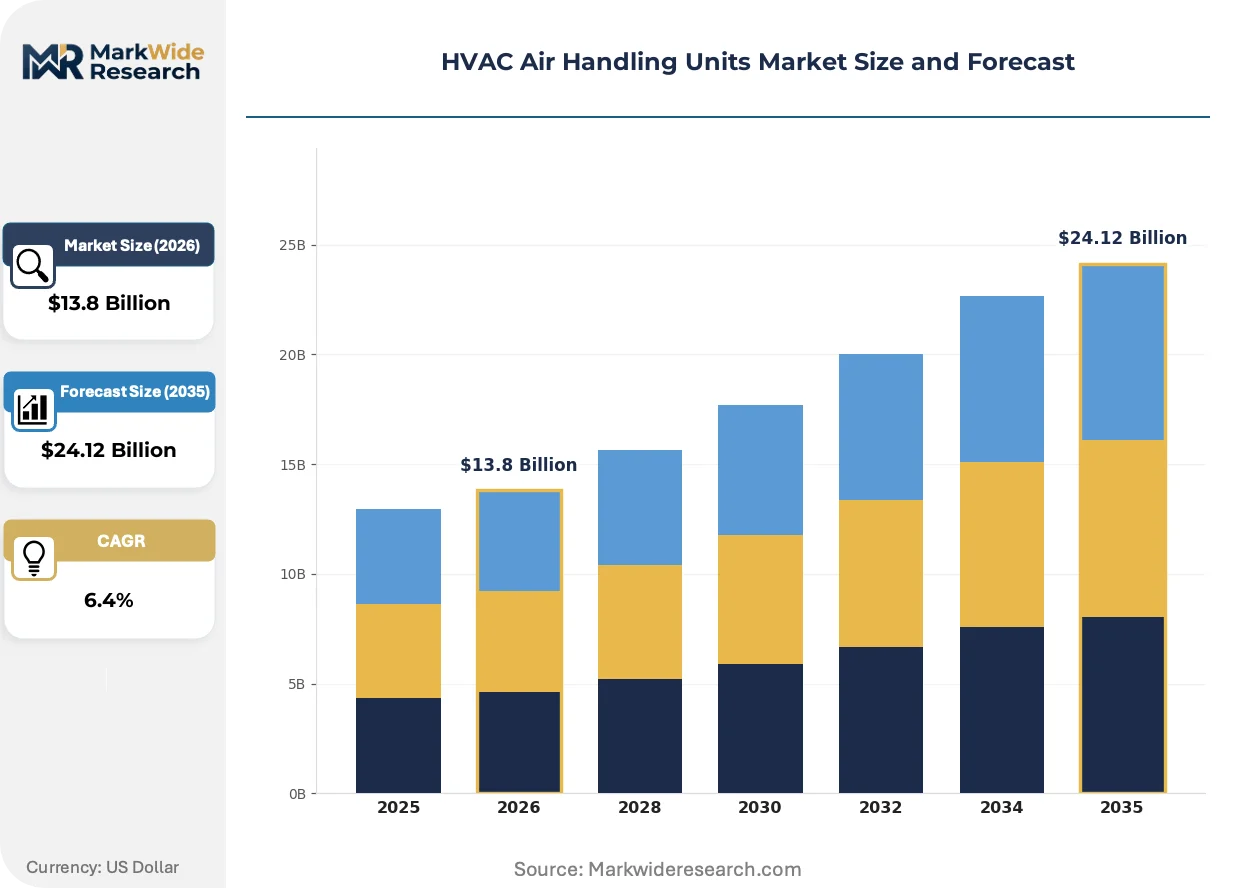
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant phase-down timelines, forcing manufacturers to redesign coil architectures and accelerate R-410A exit strategies ahead of 2030 compliance deadlines.
Growth Catalysts
- Healthcare infrastructure mandates:ASHRAE Standard 170 ventilation requirements for hospital operating rooms are driving specification upgrades across acute care facilities.
- EU Green Deal retrofit programs:Germany's federal building energy efficiency incentives are accelerating replacement cycles in public sector real estate portfolios.
- Heat recovery technology maturation:Enthalpy wheel integration is cutting ventilation energy loads by capturing exhaust stream thermal content.
Market Restraints
- Copper and aluminum price volatility:Coil raw material cost swings are compressing OEM margin pools and complicating project bidding.
- Refrigerant supply concentration:HFO-1234yf and R-32 production capacity clusters in Chinese chemical manufacturing zones.
- Skilled technician scarcity:Leak detection certification under EPA Section 608 is narrowing the qualified installer base.
Strategic Opportunities
- Data center cooling expansion:Hyperscale facility construction is creating demand for high-capacity AHUs with precision humidity control.
- India's hospital infrastructure buildout:Ayushman Bharat health coverage expansion is funding climate system investments in tier-2 and tier-3 cities.
- BACnet/IP protocol convergence:Open building automation standards are enabling third-party controls integration that unbundles hardware from proprietary software stacks.
Industry Challenges
- Legacy BAS integration complexity:Proprietary communication protocols in installed building automation systems are blocking seamless smart AHU retrofits.
- CE marking timeline compression:Machinery Directive conformity assessment delays are extending product launch cycles for modular unit configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Air Handling Units Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Versatile Units, Modular Units, Rooftop Units, Centralized Units Installation: New Construction, Retrofit Projects, Industrial Spaces, Commercial Buildings Control System: Manual Control, Automated Control, Smart Control, Integrated Systems End User: Residential Users, Commercial Properties, Educational Institutions, Healthcare Facilities |
| Companies Covered | Daikin Industries Ltd, Carrier Global Corporation, Johnson Controls International plc, Trane Technologies plc, Lennox International Inc, LG Electronics Inc, Systemair AB, Rheem Manufacturing Company, TROX GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Air Handling Units Market Emerging Trajectories
Digital twin simulation and edge-computing diagnostics are compressing commissioning timelines and shifting maintenance economics toward predictive intervention models.
Variable refrigerant flow hybrid systems are decentralizing thermal distribution architecture by enabling zone-level temperature control without centralized ductwork. Pharmaceutical manufacturing facilities are adopting these configurations to isolate cleanroom environments while reducing fan energy consumption. The technology is decentralizing traditional AHU-centric HVAC design by pushing conditioning capacity to terminal units.
REACH chemical authorization requirements are restricting flame retardant options in insulation materials, compelling casing manufacturers to reformulate thermal barrier specifications. Industrial consequence includes extended material qualification cycles and supplier switching costs. Medical device manufacturing cleanrooms in Ireland and the Netherlands are experiencing the most acute compliance pressure, driving specification shifts toward mineral wool alternatives.
Facility managers are unbundling long-term service contracts from equipment procurement, opting instead for performance-based maintenance agreements with third-party specialists. This pattern disrupts OEM aftermarket revenue streams and elevates independent service provider influence. The shift is most visible in German commercial real estate, where property management platforms are standardizing open-protocol service procurement.
HVAC Air Handling Units Market Segmentation
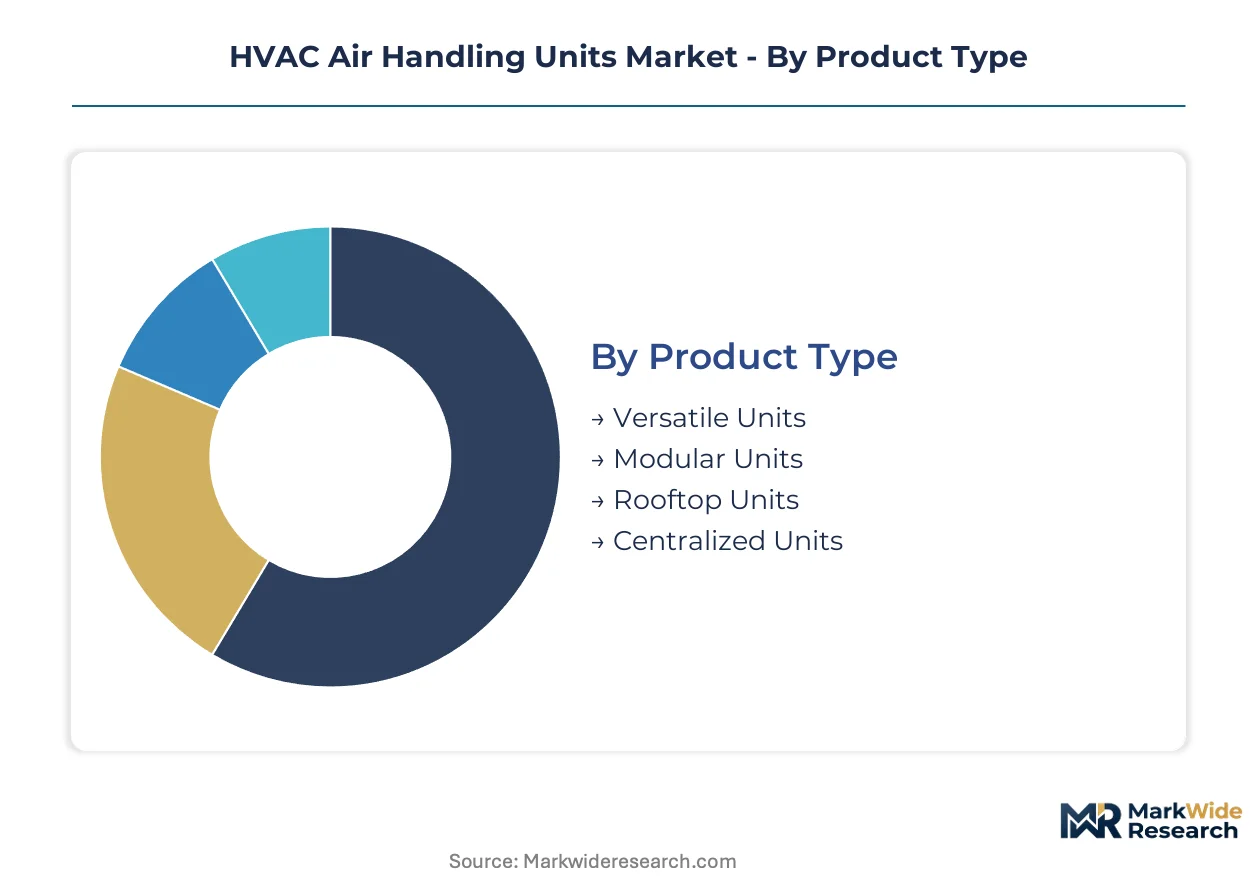
Product configuration in air handling units spans engineered-to-order systems for specialized environments through mass-produced packaged solutions. Specification pathways diverge sharply between healthcare and light commercial verticals, driving distinct procurement behaviors and margin structures across manufacturers.
Product Type:
Customization intensity ranges from standardized packaged units to architecturally integrated engineered systems requiring site-specific fabrication.
- Modular Units:Factory-assembled sections with bolt-together casing joints enable phased capacity expansion and contamination isolation in hospital surgical suites. Demand concentrates in German acute care facilities where ASHRAE Standard 170 compliance mandates redundant air delivery pathways and isolation room flexibility.
- Rooftop Units:Self-contained packaged systems integrate all conditioning components within weatherized casings for single-point installation. Volume leadership in US retail and suburban office construction reflects contractor preference for minimized field labor and rapid commissioning timelines.
- Versatile Units:Configurable platform designs accommodate multiple coil and filter arrangements without full custom engineering.
- Centralized Units:Large-capacity built-up systems serving entire building complexes through extensive duct distribution networks.
Leading the category by volume: Rooftop Units. Growing fastest: Modular Units.
Installation:
Project delivery mode determines equipment specification authority, with design-build contractors favoring packaged solutions and owner-direct procurement enabling premium system selection.
- Retrofit Projects:Existing building infrastructure constraints dictate dimensional compatibility and phased replacement sequencing to maintain occupancy. German federal building energy efficiency programs are accelerating public sector replacement cycles, with Frankfurt and Munich municipal portfolios driving specification volume for compact footprint units designed to fit legacy mechanical rooms.
- New Construction:Greenfield sites enable optimal equipment sizing and placement without spatial compromise. US hospital construction in Texas and Florida is specifying premium AHUs with integrated heat recovery wheels to meet ASHRAE Standard 90.1 energy baselines from commissioning date.
- Commercial Buildings:Office and retail fit-out projects balancing first cost against operating expense predictability.
- Industrial Spaces:Manufacturing environments requiring corrosion-resistant casings and high-dust-load filtration.
Retrofit Projects dominate current quotation activity. New Construction offers the steepest expansion trajectory through healthcare and data center buildouts.
Control System:
Intelligence tiering separates basic pneumatic or electromechanical operation from networked predictive systems with cloud-connected diagnostics.
- Smart Control:IoT-enabled edge computing platforms with BACnet/IP protocol support enable third-party integration and predictive maintenance algorithms. Healthcare facilities in the Netherlands and Ireland are specifying these systems to satisfy Joint Commission environment-of-care monitoring requirements while reducing emergency repair frequency.
- Integrated Systems:Native building automation compatibility with proprietary or open-protocol communication stacks. German commercial real estate platforms are standardizing these configurations to enable centralized portfolio energy management across distributed property holdings.
- Automated Control:Programmable logic-based sequences without full network connectivity or predictive capability.
- Manual Control:Basic electromechanical switches and local adjustment for cost-constrained applications.
Smart Control commands premium positioning and fastest share gain. Integrated Systems lead current specification volume in European commercial construction.
End User:
Regulatory burden and contamination sensitivity create tiered performance requirements from residential comfort through pharmaceutical cleanroom precision.
- Healthcare Facilities:Operating rooms, isolation wards, and pharmacy cleanrooms demand HEPA filtration, pressure cascade control, and redundant fan arrays. India's Ayushman Bharat expansion is funding climate system investments in tier-2 and tier-3 city hospitals, with Nagpur, Indore, and Lucknow emerging as concentrated procurement zones.
- Educational Institutions:K-12 and university buildings balancing occupancy density against capital budget constraints. US EPA Indoor Air Quality Tools for Schools guidance is driving filter efficiency upgrades in legacy buildings without full system replacement.
- Commercial Properties:Office, retail, and hospitality applications prioritizing energy cost management and tenant comfort predictability.
- Residential Users:Multi-family and high-end single-family installations with limited customization requirements.
Healthcare Facilities anchor premium pricing and technology adoption. Educational Institutions represent the volume base with accelerating upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting corridors in Quebec and Siberia feed coil fabrication for North American and European OEMs, while copper cathode from Chilean mines underpins heat exchanger production across multiple manufacturing zones.
Germany
Federal building energy efficiency programs are accelerating public sector AHU replacement cycles in municipal portfolios. The EU F-Gas Regulation compresses refrigerant phase-down timelines for manufacturers operating within member states. Frankfurt and Munich mechanical room retrofits are driving specification volume for compact footprint modular units designed to fit legacy infrastructure constraints.
United States
Hospital construction in Texas and Florida is specifying premium AHUs with integrated heat recovery wheels to meet ASHRAE Standard 90.1 energy baselines from commissioning date. EPA Section 608 refrigerant management standards govern coil specifications and leak detection requirements for installed units. The EPA Indoor Air Quality Tools for Schools guidance is driving filter efficiency upgrades in educational facilities across legacy building stock.
India
Ayushman Bharat health coverage expansion is funding climate system investments in tier-2 and tier-3 city hospitals. BIS certification requirements and energy efficiency standards under CEA regulations are elevating product performance thresholds for market access. Nagpur, Indore, and Lucknow are emerging as concentrated procurement zones for healthcare facility AHUs with HEPA filtration and pressure cascade control.
China
Dual carbon goals under MEE directives are accelerating energy efficiency retrofit programs in commercial building stock across eastern provinces. GB standards for ventilation and air conditioning systems constrain market access for non-compliant equipment while driving replacement demand. Yangtze River Delta manufacturing clusters are experiencing acute copper and aluminum price volatility affecting coil raw material cost structures.
Netherlands
Healthcare facilities are specifying smart control systems with BACnet/IP protocol support to satisfy Joint Commission environment-of-care monitoring requirements. REACH chemical authorization requirements are restricting flame retardant options in insulation materials for medical device manufacturing cleanrooms. Eindhoven and Amsterdam metropolitan areas are driving specification shifts toward mineral wool alternatives in pharmaceutical and laboratory verticals.
HVAC Air Handling Units Market Vendor Landscape
Global majors compete with regional champions across distribution architecture and building automation integration depth. The vendor base separates into three tiers: diversified industrial conglomerates with captive component manufacturing, specialized climate equipment fabricators with modular customization capabilities, and regional contractors with installation-centric service models. Dominant competitive moves include backward integration into refrigeration circuit production and strategic partnerships with building automation software providers.
Within the diversified conglomerate tier, Daikin Industries Ltd and Carrier Global Corporation exemplify scale-driven positioning through captive supply chains and direct contractor channel anchoring. Johnson Controls International plc occupies a distinct position bundling hardware with controls software integration. Among European specialists, TROX GmbH represents the engineered-to-order archetype serving healthcare and laboratory verticals with site-specific fabrication capabilities. Systemair AB anchors the Nordic regional champion model with standardized packaged solutions for commercial construction.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Carrier Global Corporation |
| Johnson Controls International plc |
| Trane Technologies plc |
| Lennox International Inc |
| LG Electronics Inc |
| Systemair AB |
| Rheem Manufacturing Company |
| TROX GmbH |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation refrigerant phase-down mandates gate qualified coil supply and premium-tier pricing access for manufacturers serving healthcare and data center verticals. OEMs with captive HFO-1234yf and R-32 sourcing capabilities command pricing power as independent fabricators face extended qualification cycles and supplier switching costs.
Pricing Analysis
Warranty and service contract bundling separates incumbent OEM pricing from unbundled equipment-only procurement favored by German commercial real estate platforms. Three-tier pricing structure across premium smart-control systems, standard integrated BAS-compatible units, and economy manual configurations reflects certification grade and aftermarket coverage depth. Price differentiation hinges on ASHRAE Standard 170 compliance certification and predictive maintenance software inclusion. Cost compression in standard-tier coil assemblies is intensifying because copper and aluminum price volatility complicates project bidding accuracy. Educational institutions exhibit highest price sensitivity due to capital budget constraints, while healthcare facilities prioritize total cost of ownership over first cost.
Supply Chain Analysis
Skilled HVAC technician scarcity in Yangtze River Delta manufacturing clusters and German industrial corridors constrains coil fabrication and leak detection certification throughput. Supply concentration centers on China for HFO-1234yf and R-32 production capacity, Germany for precision fan assembly and controls integration, and the United States for aluminum heat exchanger fabrication. Raw material dependencies draw from Chilean copper cathode, Quebec aluminum smelting output, and specialized filter media from Netherlands-based suppliers. Single-source vulnerability in Chinese refrigerant chemical manufacturing zones exposes OEMs to export restriction risk. Distribution runs through direct contractor relationships in North American markets and specialized HVAC distributors serving European commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC air handling unit market is executing a technology-transition phase as IoT-enabled edge computing diagnostics displace electromechanical control architectures. Smart control system adoption is reshaping competitive positioning and aftermarket revenue models.
For Market Incumbents: Hedge refrigerant transition risk by accelerating backward integration into refrigeration circuit production and securing dual-source HFO-1234yf supply agreements ahead of 2030 compliance deadlines. Defend margin pools against independent service provider encroachment by unbundling predictive maintenance software as standalone subscription offerings. Prioritize BACnet/IP protocol certification investment to maintain specification authority in German commercial real estate portfolios.
For New Entrants and Emerging Players: Tier-2 and tier-3 city hospital procurement managers in India represent an underserved buyer archetype with limited incumbent service coverage and Ayushman Bharat funding availability. White-space targets include modular AHU configurations for pharmaceutical cleanroom verticals in Ireland and Netherlands medical device manufacturing clusters. Pursue performance-based maintenance agreement positioning to bypass capital equipment procurement gatekeepers and capture recurring revenue streams.
For Investors and Strategic Acquirers: REACH chemical authorization enforcement actions against legacy flame retardant formulations is the leading indicator that mineral wool insulation specialists will command acquisition premiums. Long-term viability favors controls software assets with open-protocol integration capabilities over pure hardware fabricators. Watch for CE marking timeline compression under Machinery Directive revisions as signal for modular unit configuration consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Circuit Backward Integration | Captive HFO-1234yf sourcing protects margins against Chinese supply concentration. |
| BACnet/IP Protocol Certification | Open building automation standards enable third-party controls unbundling from proprietary stacks. |
| Heat Recovery Wheel Integration | Enthalpy technology captures exhaust stream thermal content for ASHRAE 90.1 compliance. |
| Predictive Maintenance Software Launch | Edge-computing diagnostics shift service revenue from reactive repair to subscription models. |
| India Distribution Channel Expansion | Ayushman Bharat hospital buildout in Nagpur and Lucknow creates specification volume opportunity. |
Methodological Framework
Independent corroboration across primary interviews with HVAC OEM product managers, hospital facilities directors, and building automation integration specialists, combined with secondary validation through EPA Section 608 enforcement data, EU F-Gas Regulation implementation timelines, and ASHRAE standard revision documentation, underwrites the qualitative findings. Bottom-up equipment shipment analysis and top-down construction spending attribution triangulate market sizing across product configuration, control system intelligence tier, and end-use vertical segmentation dimensions.
Comparable-period anchoring to historical replacement cycle patterns and retrofit program enrollment rates calibrated the projection horizon across the analysis window. The analytical framework models volume and value trajectories by product type, installation mode, control system protocol, and end-user regulatory burden tier. CAGRs derive from regression against construction spending indices, energy efficiency incentive program budgets, and refrigerant phase-down schedule compliance cost curves. Coil raw material cost structures and skilled technician certification pipeline constraints inform industry-specific forecast inputs.
Revisions become necessary when EU F-Gas Regulation enforcement intensity, copper and aluminum commodity price volatility, or REACH chemical authorization scope expansion materialize beyond modeled assumptions. Forecasts reflect documented expectations regarding healthcare infrastructure mandate expansion and data center cooling capacity buildout trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Duct Fans Market