
 Steam Operated Condensate Pump Market | 2026-2036
Steam Operated Condensate Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Operated Condensate Pump Market Analysis
The gap between premium engineered systems and commodity condensate units is realigning procurement patterns across industrial buyers. Roth Pump Company leverages its vertical integration in precision casting to command premium positioning in power generation applications. Armstrong International anchors its presence through extensive steam trap and pump bundling across North American refineries. Skidmore Pump competes on specialized horizontal configurations for high-pressure process environments.
Steam operated condensate pumps recover and return hot condensate to boiler feed systems using steam pressure as the motive force, typically handling temperatures exceeding 200°F with cast iron or stainless steel construction. These units reduce fuel consumption, chemical treatment costs, and water discharge in continuous steam operations. Horizontal configurations dominate heavy industrial installations where floor-mounted accessibility matters, while vertical designs capture commercial HVAC retrofits with space constraints. Submersible variants represent the fastest-growing category as facilities prioritize flood-proof basement installations. Electric drive technology holds mature status while pneumatic control systems retain share in explosion-classified process zones.
EPA regulations on boiler MACT standards and DOE efficiency mandates shape product certification requirements and retrofit timelines across American manufacturing. OSHA pressure vessel standards and ASME BPVC codes govern material specifications and safety margins for domestic installations. Stakeholders must monitor how state-level decarbonization targets redirect capital from steam infrastructure toward electrification alternatives.
Market Dynamics
The retrofit imperative across aging American power infrastructure is compressing replacement cycles for steam condensate recovery equipment, as facilities balance EPA emissions mandates against electrification capital reallocation.
Growth Catalysts
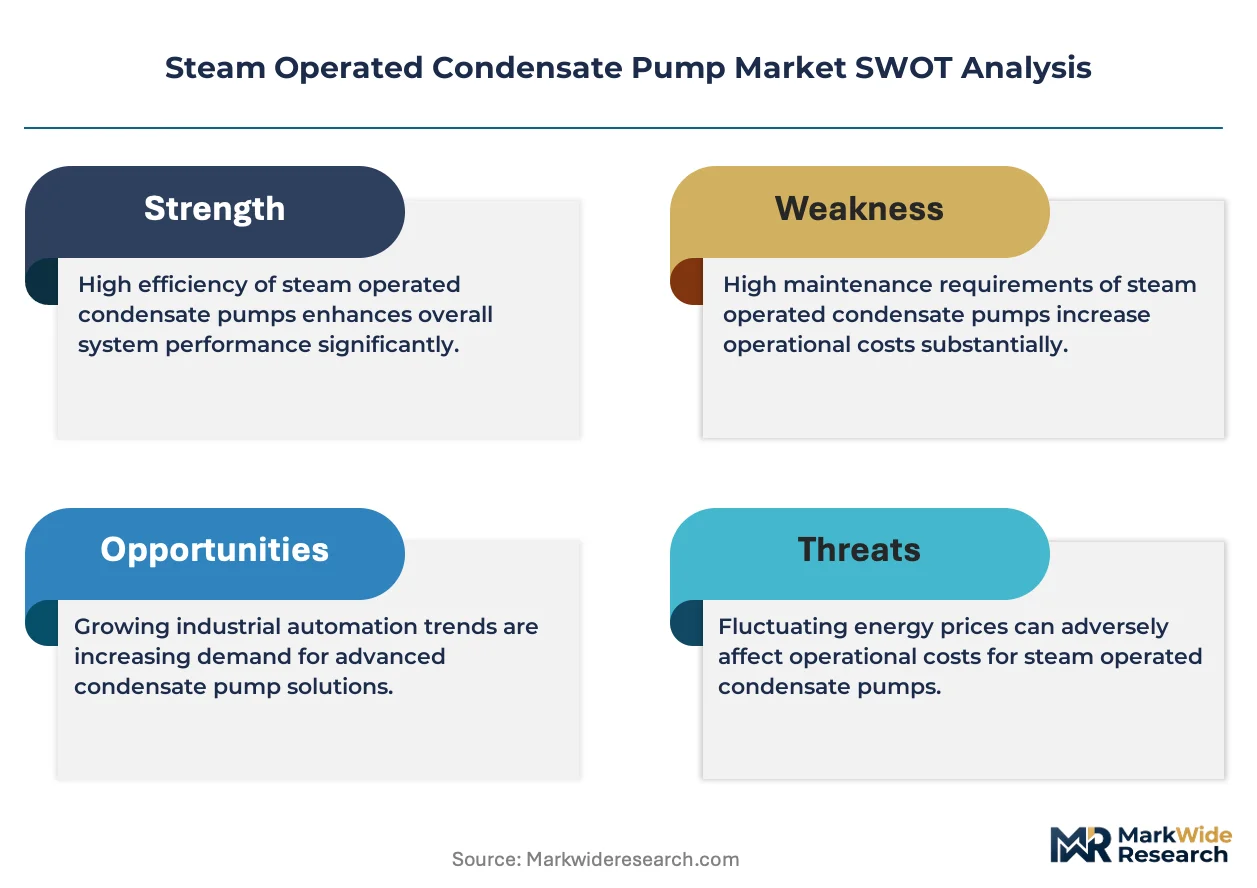
- Boiler MACT Enforcement:EPA compliance deadlines force industrial facilities to upgrade condensate recovery efficiency, accelerating system replacement across Midwest manufacturing clusters.
- Steam Infrastructure Aging:Decades-old boiler installations in Great Lakes petrochemical corridors require motive-force pump upgrades to maintain operational continuity.
- Water Scarcity Pressures:Western states facing drought conditions prioritize closed-loop condensate systems to reduce freshwater withdrawal and discharge volumes.
Market Restraints
- Cast Iron Input Volatility:Foundry-grade pig iron pricing swings compress margin predictability for domestic pump manufacturers dependent on bulk metallurgical supply.
- Electrification Substitution:Variable-frequency electric drive pumps displace steam-motive units in new-build facilities, eroding addressable market expansion in greenfield projects.
- Specialized Foundry Concentration:Precision casting capacity for high-temperature alloy components concentrates in a narrow supplier base, creating bottleneck risk for premium system production.
Strategic Opportunities
- Subterranean Flood-Proofing:Submersible condensate pump configurations capture basement mechanical room retrofits in coastal cities facing storm surge exposure.
- State Decarbonization Incentives:California and New York efficiency rebate programs create partial offset for hybrid steam-electric recovery system upgrades.
- IIoT Sensor Convergence:Wireless vibration monitoring integrated with pneumatic pump controls enables predictive maintenance contracts in refinery maintenance budgets.
Industry Challenges
- ASME BPVC Certification Timelines:Pressure vessel code compliance documentation extends product launch cycles by 8-14 months for new casting designs.
- Legacy Steam System Integration:Pneumatic control retrofitting into 1970s-era boiler rooms requires custom manifold fabrication, inflating field engineering costs.
- Skilled Welder Scarcity:Certified pressure-boundary welders for stainless steel pump fabrication command premium wages, constraining production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Operated Condensate Pump Market |
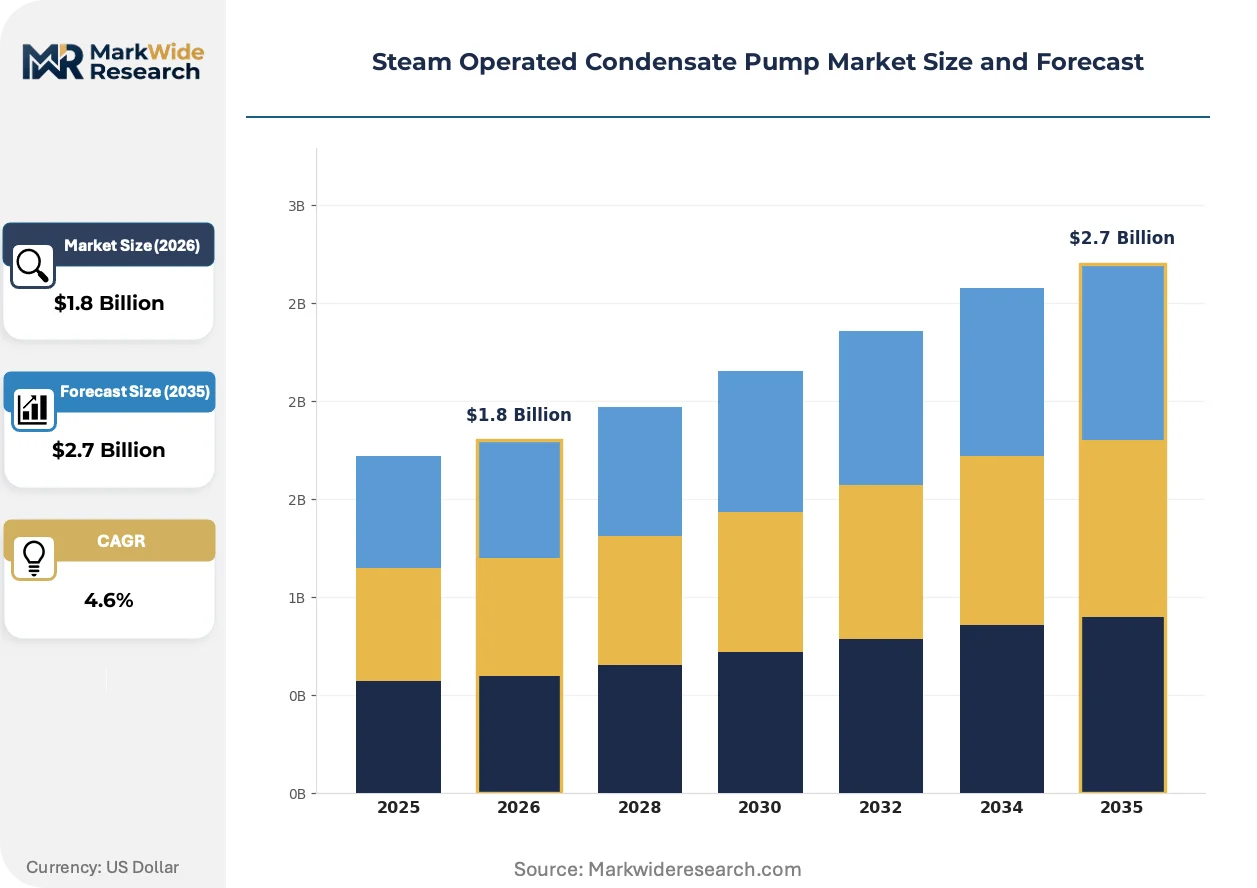
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
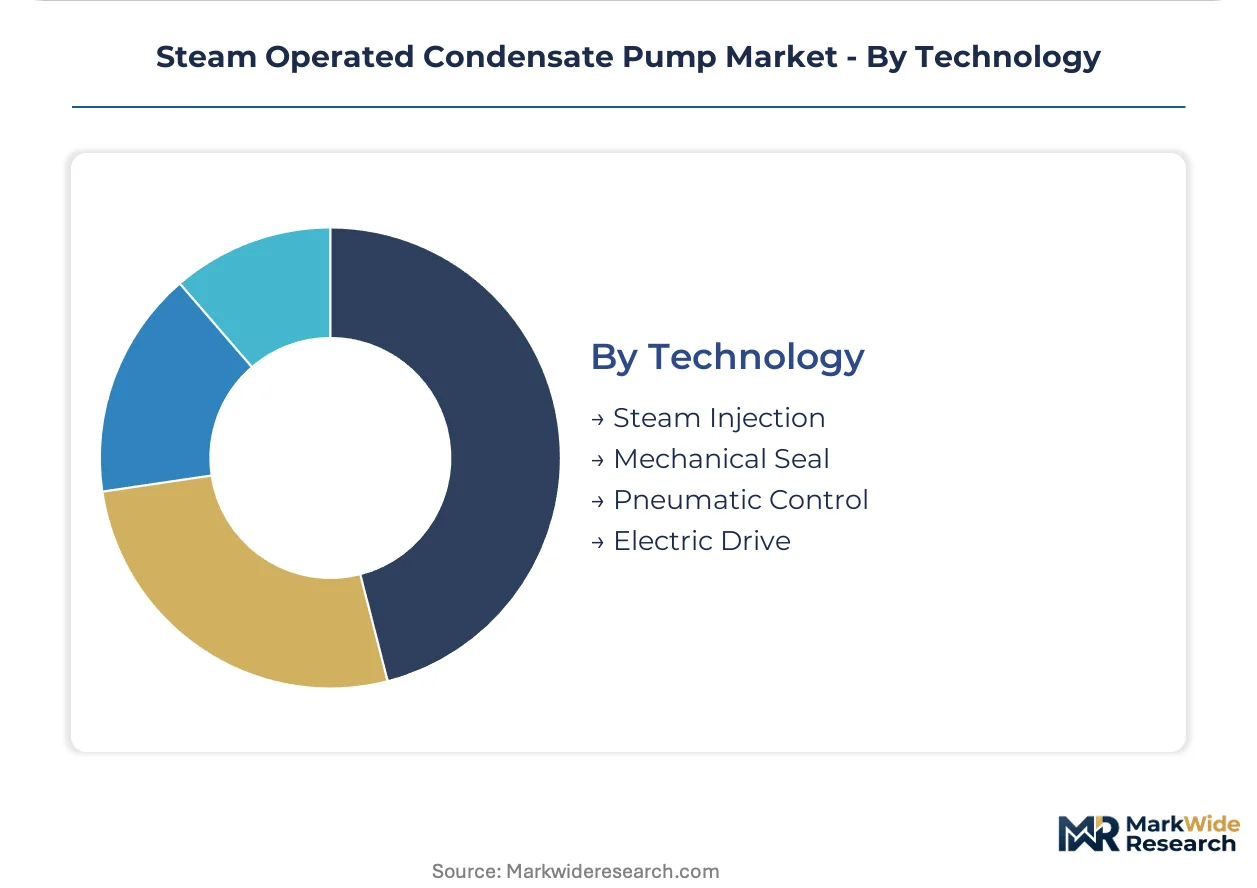
| Segmentation | Product Type: Vertical, Horizontal, Submersible, Electric End User: Industrial, Commercial, Residential, Hospitality Application: Heating Systems, Power Generation, HVAC, Process Applications Technology: Steam Injection, Mechanical Seal, Pneumatic Control, Electric Drive |
| Companies Covered | Aspen Pumps Limited, Skidmore Pump, Roth Pump Company, Diversitech, Little Giant, Hoffman Pump, Shipco Pumps, Armstrong International, Hartell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Operated Condensate Pump Market Emerging Trajectories
Steam condensate recovery technology is bifurcating between premium integrated systems and modular retrofit kits, as facilities prioritize uptime assurance over capital minimization in maintenance budgets.
Magnetic drive sealing technology is consolidating market preference for leak-free condensate handling in high-temperature process environments. Pharmaceutical and food processing facilities in the Mid-Atlantic region are specifying mag-drive configurations for 220°F-plus condensate return lines. This shift is consolidating supplier margins around proprietary magnet alloy formulations and specialized containment can designs.
OSHA's updated Process Safety Management enforcement is tightening mechanical integrity documentation requirements for steam systems handling hazardous area classifications. Refinery operators in the Gulf Coast corridor now face expanded audit scopes covering condensate pump maintenance records and spare parts traceability. Pneumatically actuated units in Class I Division 2 zones are seeing accelerated replacement cycles as facilities preempt citation exposure.
Maintenance contracting is unbundling from equipment supply, with third-party service providers capturing valve rebuild and pump overhaul work previously bundled in OEM sales. Independent mechanical contractors in Texas and Louisiana are building dedicated steam system service divisions. This fragmentation is most visible in petrochemical maintenance turnarounds, where owner-operators now separate capital procurement from operating expenditure service agreements.
Steam Operated Condensate Pump Market Segmentation
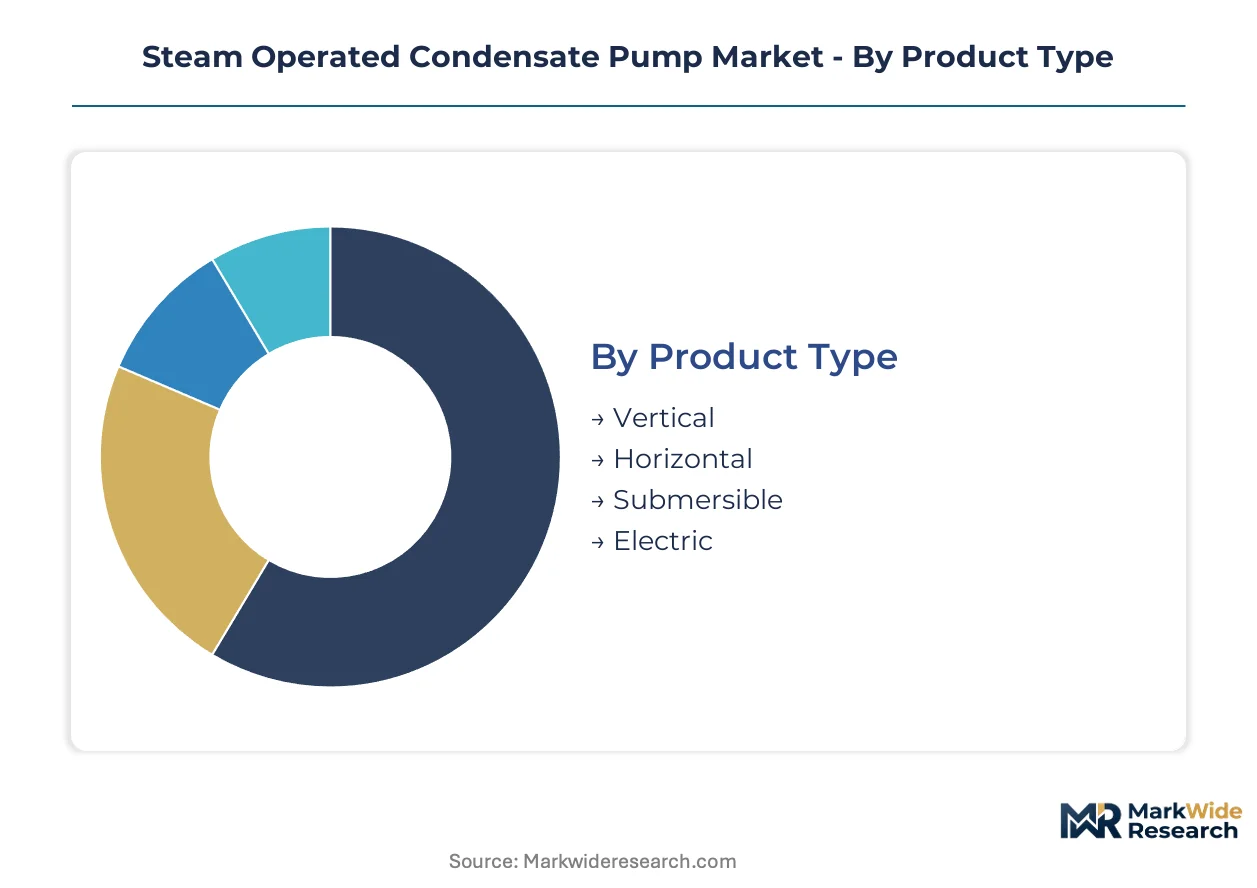
Steam operated condensate pump procurement divides sharply between heavy industrial specifications requiring ASME certification and lighter-duty commercial installations. Facility engineers select configurations based on floor space constraints, temperature handling requirements, and integration complexity with legacy boiler infrastructure.
Product Type:
Volume deployment concentrates in standardized horizontal units, while premium positioning attaches to specialized vertical and submersible configurations for constrained mechanical spaces.
- Vertical:Upright pump assemblies mount directly on condensate receiver tanks, eliminating floor footprint in crowded boiler rooms. Demand clusters in commercial HVAC retrofits across northeastern US cities where basement headroom limits horizontal alternatives. Premium pricing reflects custom tank integration and extended discharge head specifications.
- Horizontal:Floor-mounted split-case designs dominate heavy industrial installations with maintenance aisle requirements. Great Lakes petrochemical facilities specify these for 200°F-plus continuous duty with cast iron housings and bronze impellers. Standardized API dimensional compliance enables rapid spare parts interchangeability.
- Submersible:Hermetically sealed motor-pump units withstand flood immersion in below-grade mechanical rooms. Coastal municipalities in Florida and Louisiana prioritize these for hurricane-resistant infrastructure.
- Electric:Motor-driven alternatives displace steam-motive units in electrification retrofits where facility steam headers are being decommissioned.
Mature deployment sits with Horizontal configurations. Newer deployment is concentrated in Submersible variants.
End User:
Application intensity separates continuous-process industrial buyers from intermittent-use commercial operators with diverging reliability specifications.
- Industrial:Power generation, refining, and chemical processing facilities operate condensate recovery as critical path infrastructure. Midwest manufacturing clusters drive replacement demand as EPA Boiler MACT deadlines enforce efficiency upgrades. These buyers specify redundant pump arrangements with automatic alternation controls.
- Commercial:Office buildings, schools, and institutional facilities prioritize first-cost minimization over energy recovery optimization. Western states facing drought mandates increasingly specify closed-loop condensate systems for LEED compliance and water use permits.
- Residential:Multi-unit steam heating systems in legacy urban housing stock require compact condensate handling. High-rise buildings in Chicago and New York specify vertical receiver-mounted units.
- Hospitality:Hotels and resorts with central laundry and kitchen steam loads balance uptime assurance against acoustic isolation requirements. Casino properties in Nevada prioritize vibration-dampened installations for guest floor proximity.
Procurement sophistication peaks with Industrial buyers. Volume expansion is accelerating fastest in Commercial retrofits.
Application:
Process criticality determines specification grade, with power generation and process applications demanding certified pressure-boundary construction absent in heating-only service.
- Heating Systems:District heating networks and building steam loops recover condensate for boiler feedwater temperature elevation. Cold-climate municipalities in Minnesota and Wisconsin prioritize these for winter reliability.
- Power Generation:Utility and cogeneration facilities handle highest condensate volumes with continuous-duty requirements. These installations specify stainless steel construction for oxygen corrosion resistance in high-purity water systems.
- HVAC:Commercial building climate control systems operate intermittent-duty cycles with seasonal load variation. California Title 24 efficiency standards accelerate condensate recovery specification in new construction.
- Process Applications:Food processing, pharmaceutical, and chemical manufacturing integrate condensate recovery with product contact steam systems. FDA sanitary requirements in these sectors mandate specific surface finishes and drainability features.
Technical specification intensity concentrates in Power Generation. Regulatory-driven replacement cycles are strongest in HVAC applications.
Technology:
Motive force selection reflects facility infrastructure availability, with steam injection retaining preference where compressed air or reliable electric supply is absent.
- Steam Injection:Direct steam motive force eliminates electric motor and seal complexity in high-temperature service. Gulf Coast refineries specify these for explosion-classified zones where electrical classification is costly.
- Mechanical Seal:Conventional packed or cartridge seal designs remain standard for non-hazardous condensate service. These dominate budget-conscious commercial replacements.
- Pneumatic Control:Instrument air-actuated pump controls integrate with distributed control systems in process plants. OSHA Process Safety Management documentation requirements are tightening maintenance record standards for these installations.
- Electric Drive:Variable frequency drive compatibility enables flow matching and energy optimization. New-build facilities in states with aggressive decarbonization targets specify these over steam-motive alternatives.
Steam Injection technology anchors legacy industrial infrastructure. Electric Drive configurations are climbing the fastest in greenfield specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American steam condensate pump procurement through its Gulf Coast petrochemical corridor, where refinery maintenance cycles and hurricane-resistant infrastructure mandates concentrate demand for submersible and pneumatic-controlled configurations.
United States
EPA Boiler MACT enforcement and DOE efficiency mandates compress replacement timelines across Midwest manufacturing clusters and Great Lakes petrochemical facilities. OSHA Process Safety Management audits tighten documentation requirements for steam system maintenance records. Texas and Louisiana refineries prioritize pneumatic pump retrofits in explosion-classified zones to preempt citation exposure during federal inspections.
Germany
Industrial boiler efficiency standards under the EU Green Deal accelerate condensate recovery system upgrades across Rhine-Ruhr manufacturing basins. REACH compliance governs material specifications for high-temperature alloy components in precision casting supply chains. Bavarian chemical processors specify stainless steel pump configurations for oxygen corrosion resistance in continuous-process environments.
China
Dual carbon goals and provincial emissions targets drive retrofit demand in Yangtze River Delta textile and chemical processing zones. GB standards and MIIT energy efficiency mandates shape product certification requirements for domestic boiler installations. Shandong Peninsula power plants specify cast iron horizontal configurations for 200°F-plus continuous duty in aging steam infrastructure.
Japan
METI industrial efficiency programs promote closed-loop condensate systems to reduce freshwater withdrawal in drought-vulnerable manufacturing regions. JIS standards govern pressure vessel construction and material specifications for domestic pump fabrication. Kansai region pharmaceutical facilities specify magnetic drive sealing technology for leak-free handling in FDA-regulated process environments.
India
Bureau of Energy Efficiency mandates and state-level industrial efficiency programs accelerate boiler replacement cycles across Gujarat and Maharashtra chemical processing corridors. CEA grid reliability concerns reinforce steam-motive pump preference where electrical supply interruptions threaten continuous operations. Tamil Nadu textile clusters prioritize vertical receiver-mounted units for space-constrained mechanical rooms in legacy industrial estates.
Steam Operated Condensate Pump Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and material-specification dimensions, with ASME BPVC-certified fabricators commanding pricing power over standard commercial configurations. The vendor base stratifies into three tiers: vertically integrated foundry operators controlling precision casting supply, specialized pump assemblers sourcing components from distributed metallurgical suppliers, and commodity distributors private-labeling generic configurations. Dominant competitive moves include backward integration into foundry capacity and technology licensing agreements for magnetic drive sealing systems.
Among North American specialists, Roth Pump Company exemplifies the vertically integrated archetype through captive precision casting operations, while Armstrong International anchors the bundling strategy across steam trap and pump combinations. Skidmore Pump occupies a position within the specialized horizontal configuration tier for high-pressure process environments. These three named entities represent distinct competitive postures without implying specific market share or strategic action claims beyond their visible positioning in industry supply structures.
| Leading Market Players |
|---|
| Aspen Pumps Limited |
| Skidmore Pump |
| Roth Pump Company |
| Diversitech |
| Little Giant |
| Hoffman Pump |
| Shipco Pumps |
| Armstrong International |
| Hartell |
| Others |
Supply Flow & Price Mechanics
Captive precision casting operations anchor margin protection for ASME-certified fabricators, insulating premium-tier producers from commodity price swings while concentrating pricing power among vertically integrated specialists serving EPA-regulated power generation retrofits.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for critical-path industrial installations, with premium tiers commanding multiples over standard commercial configurations due to ASME BPVC certification requirements and redundant pump arrangements. Price differentiation separates certified pressure-boundary construction from standard cast iron commercial units, with foundry-grade pig iron volatility compressing margins in commodity tiers. Cost compression in economy segments intensifies as electric drive alternatives displace steam-motive units in greenfield specifications. Commercial HVAC buyers exhibit highest price sensitivity, while power generation facilities prioritize reliability specifications over capital minimization.
Supply Chain Analysis
Domestic-content mandates under the Buy American Act reshape sourcing patterns for federally funded infrastructure projects, pressuring OEMs toward domestic foundry partnerships. Precision casting capacity concentrates in the United States, Germany, and Japan, with high-temperature alloy components drawing from specialized metallurgical suppliers in each jurisdiction. Supply chain risk centers on single-source vulnerability for certified pressure-boundary welders capable of stainless steel fabrication. Distribution runs through authorized industrial distributors serving MRO procurement channels, with direct OEM relationships dominating large capital projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race defines competitive positioning, with foundry capacity acquisition emerging as the decisive upstream lever separating premium-margin specialists from component assemblers exposed to metallurgical supply bottlenecks.
For Market Incumbents: Deepen captive foundry investments to secure ASME-certified casting capacity, insulating against skilled welder scarcity while preempting margin erosion from commodity-tier competitors. Defensive patent positioning around magnetic drive sealing technology blocks emerging entrants from pharmaceutical and food processing specifications. Prioritize predictive maintenance service contracts to capture recurring revenue streams unbundled from equipment sales. For New Entrants and Emerging Players: EPA Boiler MACT enforcement in the United States opens a window for specialized retrofit kit providers targeting Midwest manufacturing clusters facing compressed compliance deadlines. White-space opportunity concentrates in submersible configurations for coastal flood-proofing applications, where hurricane-resistant infrastructure mandates outpace incumbent capacity expansion. A go-to-market angle through independent mechanical contractors building dedicated steam system service divisions bypasses entrenched OEM distribution relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified industrial conglomerates seeking steam infrastructure exposure. Long-term viability favors vertically integrated specialists with captive precision casting and established ASME certification track records. The signal to watch is state-level decarbonization target acceleration, which would redirect capital from steam infrastructure toward electrification alternatives and compress addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive precision casting secures ASME BPVC certification timelines against metallurgical supply bottlenecks. |
| Magnetic Drive Sealing Technology Licensing | Proprietary magnet alloy formulations capture pharmaceutical and FDA-regulated process environment specifications. |
| Predictive Maintenance Service Contracts | Wireless vibration monitoring integrated with pneumatic controls penetrates refinery MRO budgets. |
| Submersible Configuration Capacity Expansion | Hermetically sealed motor-pump units address hurricane-resistant infrastructure mandates in Gulf Coast municipalities. |
| Hybrid Steam-Electric System Development | Dual-motive configurations qualify for California and New York state efficiency rebate programs. |
Methodological Framework
Multi-period observation of EPA compliance deadlines, foundry capacity utilization rates, and refinery maintenance turnaround schedules anchored the trend analysis, supplemented by interviews with plant engineers, maintenance directors at power generation facilities, OEM procurement teams, and aftermarket service heads. Secondary validation drew from EPA Boiler MACT enforcement records, DOE efficiency mandate documentation, ASME BPVC code revision filings, and customs data on foundry-grade pig iron imports. Bottom-up equipment shipment tracking triangulated against top-down industrial boiler replacement cycle analysis.
Input-output matrices modeled deployment across product type, end-user industry, application criticality, and motive force technology dimensions throughout the forecast period. CAGRs were derived from segment-level replacement cycle compression and regulatory enforcement timelines. Industry-specific forecast inputs included state-level decarbonization incentive program adoption rates and OSHA Process Safety Management audit frequency projections.
The model assumes a particular technology adoption path for steam-motive retention in explosion-classified zones; alternative pathways for electric drive displacement would alter the outlook for pneumatic control system demand. Forecasts reflect assumptions regarding EPA enforcement continuity and foundry capacity expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Scrubber Dryer Market