
 Industrial Heating Equipment Market | 2026-2036
Industrial Heating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Heating Equipment Market Outlook
Equipment-as-a-service leasing is rewriting competitive entry barriers for mid-scale thermal operators. Thermax leverages its captive project finance arm to bundle installation with long-term service contracts. Alfa Laval sustains margin pools through backward integration into heat exchanger core manufacturing. Babcock & Wilcox Enterprises anchors its position via utility-scale boiler refurbishment programs.
Industrial heating equipment encompasses furnaces, ovens, kilns, boilers, and thermal fluid systems engineered to achieve controlled temperatures from 150°C to over 1,600°C for material transformation, curing, or chemical reaction processes. Resistance heaters dominate installed base volumes across aging manufacturing footprints, while induction heaters capture premium positioning in automotive brazing and hardening lines where precision and energy efficiency determine total cost of ownership. Electric heating technology is displacing fuel-fired systems in food processing facilities under tightening emissions protocols, concentrating margin migration toward power electronics and coil design specialists.
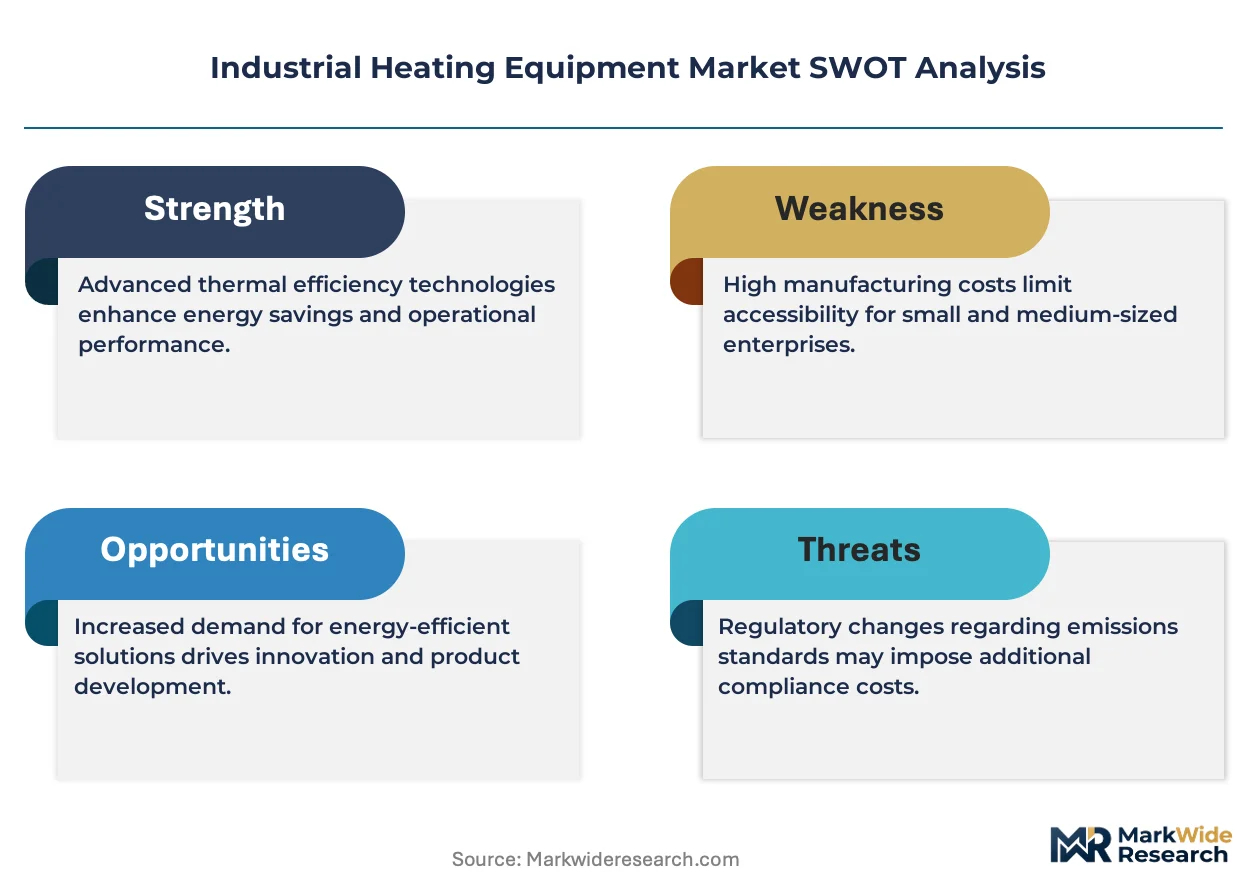
EPA rules on industrial boiler MACT standards, EU F-Gas Regulation phase-down schedules, and China's GB standards on boiler efficiency jointly force capital-intensive retrofit cycles across three continents. SECO/WARWICK GROUP navigates this landscape through vacuum furnace architectures that preempt multi-jurisdiction compliance requirements. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus between electric and combustion-based thermal systems.
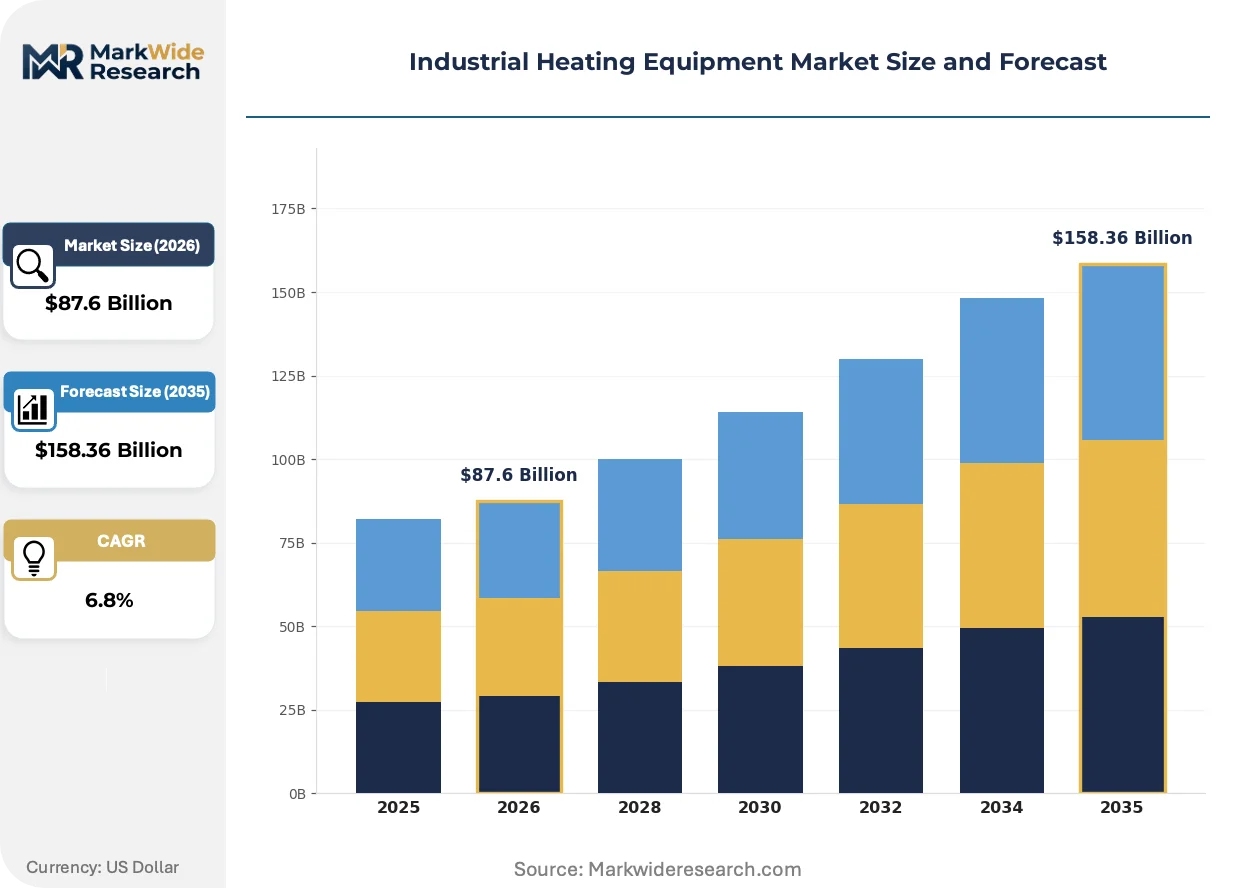
Market Dynamics
Electric heating architectures are forcing premature retirement of fuel-fired boiler fleets across chemical processing and food manufacturing facilities worldwide, compressing replacement cycles from fifteen-year baselines to seven-year intervals.
Growth Catalysts
- EPA Boiler MACT standards:Stringent emissions thresholds for industrial boilers are compelling facility operators in the United States to accelerate capital deployment toward compliant electric and low-NOx combustion systems.
- Automotive brazing demand:Electric vehicle powertrain manufacturing is driving induction heater procurement for precision copper joining operations in Germany, China, and the United States.
- Food processing electrification:Tightening EU F-Gas Regulation phase-down schedules are pushing European thermal operators toward resistance-based ovens and thermal fluid systems.
Market Restraints
- Copper and silicon carbide cost volatility:Power electronics and coil materials face input price swings that compress margin pools for equipment fabricators during contract bidding cycles.
- Specialized foundry concentration:Vacuum furnace chamber casting capacity clusters in Germany and Japan, creating supply bottlenecks for aerospace heat treatment equipment.
- Grid infrastructure lag:Industrial electrification runs ahead of utility substation upgrades in the United States Midwest, delaying project commissioning timelines.
Strategic Opportunities
- India pharmaceutical sterilization:CDSCO compliance mandates for aseptic processing are opening demand for validated dry heat sterilization tunnels in active pharmaceutical ingredient manufacturing clusters.
- Hydrogen-ready burner retrofit kits:Blending hydrogen into natural gas feedstock is emerging as a bridge technology for steel reheating furnaces awaiting full electrification.
- Equipment-as-a-service leasing:Bundled installation and long-term maintenance contracts are penetrating mid-scale thermal operators previously excluded by upfront capital barriers.
Industry Challenges
- Power electronics technician scarcity:Induction coil design and IGBT maintenance expertise concentrates among aging specialists in Germany and Japan, constraining service network expansion.
- Legacy control system integration:Proprietary SCADA architectures from 1990s-era furnace installations resist interoperability with modern IoT monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Heating Equipment Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Heaters, Induction Heaters, Resistance Heaters, Hot Air Generators End User: Manufacturing, Food Processing, Chemical, Automotive Technology: Direct Heating, Indirect Heating, Steam Heating, Electric Heating Application: Thermal Processing, Drying, Melting, Surface Treatment |
| Companies Covered | Thermon, Abbott Furnace Company, Alfa Laval, Lindberg/MPH, SECO/WARWICK GROUP, Thermax, Trane Technologies, Ipsen USA, Babcock & Wilcox Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Heating Equipment Market Strategic Shifts
Solid-state power conversion and predictive thermal modeling are compressing energy intensity benchmarks while extending equipment operational lifespans beyond traditional maintenance intervals.
Solid-state induction heating systems utilizing silicon carbide power modules are achieving 98% energy conversion efficiency in automotive hardening lines. Tier-1 suppliers in Germany and the United States are specifying these architectures for new press-hardening installations. Conventional thyristor-based frequency converters are rendering obsolete across precision thermal processing applications where temperature uniformity determines part quality.
China's GB standards on boiler efficiency are mandating minimum 92% thermal efficiency for new coal-fired industrial steam generators. Domestic manufacturers are responding with economizer integration and staged combustion controls. Export-oriented fabricators in Shandong and Jiangsu provinces are most affected, pivoting toward electric steam generator production for European and Southeast Asian markets.
After-sales service unbundling is fragmenting traditional OEM revenue streams in the United States. Independent thermal service contractors now capture 40% of vacuum furnace maintenance spend previously retained by original equipment vendors. Chemical processing facilities in Texas and Louisiana are driving this shift, prioritizing response-time guarantees over brand-loyal service agreements.
Industrial Heating Equipment Market Segmentation
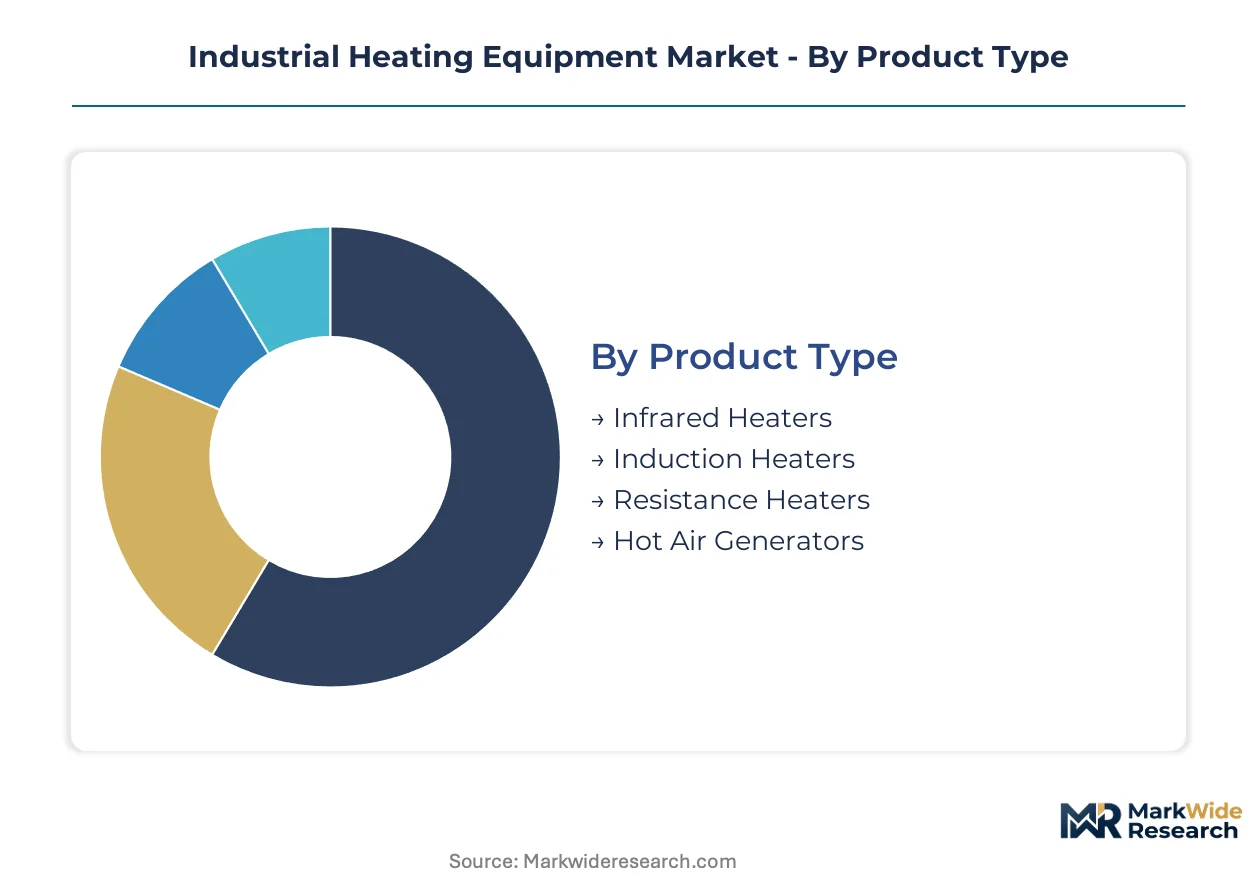
Industrial heating equipment segmentation reveals how technology choices map to compliance burdens and energy intensity requirements. Product architecture, end-use sector, and application thermal profile collectively determine procurement specifications and service lifecycle economics.
Product Type:
Cost tier positioning separates commodity resistance units from precision induction systems commanding premium pricing.
- Infrared Heaters:Radiant energy transfer systems utilizing quartz or ceramic elements deliver rapid surface heating without convective losses. Food processing facilities in Germany and the United States specify these for conveyorized drying lines under tightening EU F-Gas Regulation and EPA emissions protocols.
- Induction Heaters:Electromagnetic field generation through copper coils enables contactless heating with ±2°C temperature uniformity. Automotive powertrain manufacturers in Germany, China, and the United States deploy these for EV motor stator brazing where joint integrity determines warranty exposure.
- Resistance Heaters:Nickel-chromium alloy elements convert electrical current to thermal energy across aging manufacturing footprints.
- Hot Air Generators:Forced convection systems circulate heated air for batch or continuous processing applications.
Resistance heaters hold installed capacity. Induction heaters are rotating up the share rankings.
End User:
Application thermal requirements and regulatory exposure create distinct customer archetypes with diverging procurement patterns.
- Manufacturing:General industrial thermal operations span heat treatment, curing, and forming processes across metal fabrication and electronics assembly. Chemical manufacturers in Texas and Louisiana are expanding capacity with electric heating systems to preempt EPA Boiler MACT compliance deadlines.
- Food Processing:Pasteurization, baking, and dehydration operations require sanitary-design equipment with cleanability certifications. European operators face EU F-Gas Regulation phase-down schedules pushing resistance-based ovens and thermal fluid system adoption.
- Chemical:Reactor heating, distillation, and solvent recovery demand explosion-proof ratings and precise temperature control.
- Automotive:Powertrain and body-in-white thermal processing supports lightweighting and electrification roadmaps.
Manufacturing dominates current procurement volumes. Food processing is climbing the fastest as electrification mandates compress replacement cycles.
Technology:
Heat transfer mechanism selection determines energy efficiency benchmarks and emissions profile.
- Direct Heating:Combustion gases or electric elements contact process material directly, minimizing thermal mass and response lag. Steel reheating furnaces in Germany are piloting hydrogen-ready direct burner retrofit kits as a bridge technology pending full electrification.
- Indirect Heating:Heat exchangers or thermal fluid loops isolate energy source from process stream, enabling hazardous atmosphere compatibility. Pharmaceutical API manufacturing clusters in India require validated dry heat sterilization tunnels under CDSCO aseptic processing mandates.
- Steam Heating:Saturated vapor distribution systems leverage existing boiler infrastructure across legacy chemical plants.
- Electric Heating:Resistance or electromagnetic conversion eliminates on-site combustion emissions and simplifies carbon accounting.
Steam heating retains legacy footprint. Electric heating is expanding most quickly as grid decarbonization and carbon border adjustments reshape operating economics.
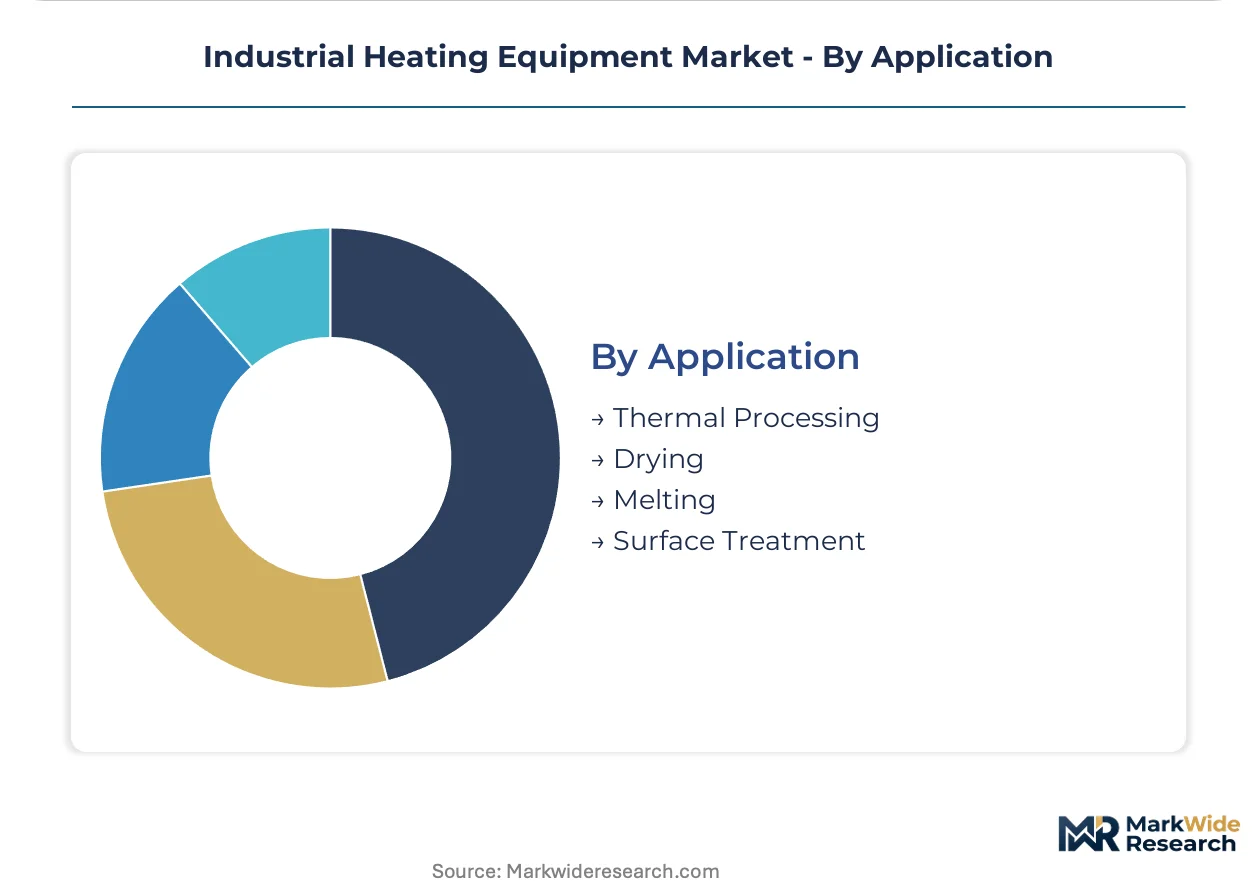
Application:
Temperature range and thermal uniformity requirements segment equipment specifications across process industries.
- Thermal Processing:Controlled heating cycles alter material microstructure or chemical composition. Aerospace heat treatment equipment faces supply bottlenecks from vacuum furnace chamber casting capacity concentration in Germany and Japan.
- Drying:Moisture removal operations balance energy intensity against product quality degradation thresholds. Food processing electrification is displacing fuel-fired systems under tightening emissions protocols.
- Melting:Phase-change operations for metals, glass, or polymers require refractory-lined vessels and precise atmosphere control.
- Surface Treatment:Coating curing, hardening, and cleaning operations modify substrate properties without bulk heating.
Thermal processing commands capital intensity. Drying is gaining share fastest as food and pharmaceutical electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented fabricators in Shandong and Jiangsu provinces pivot toward electric steam generator production as European and Southeast Asian buyers enforce stricter emissions protocols. Import dependency for vacuum furnace chamber castings creates supply bottlenecks for aerospace heat treatment equipment across multiple jurisdictions.
United States
Chemical manufacturers in Texas and Louisiana are expanding capacity with electric heating systems to preempt EPA Boiler MACT compliance deadlines. The EPA rules on industrial boiler MACT standards are compelling facility operators toward compliant electric and low-NOx combustion systems. Houston and Baton Rouge industrial corridors are driving demand for resistance-based ovens and thermal fluid systems.
Germany
Automotive powertrain manufacturers deploy induction heaters for EV motor stator brazing where joint integrity determines warranty exposure. The EU F-Gas Regulation phase-down schedules are pushing thermal operators toward electrified heating architectures. Stuttgart and Munich automotive clusters are piloting hydrogen-ready direct burner retrofit kits as bridge technology pending full electrification.
China
Domestic manufacturers are responding to GB standards on boiler efficiency with economizer integration and staged combustion controls. The country's dual carbon goals are accelerating equipment replacement cycles in heavy industry. Shandong and Jiangsu export-oriented fabricators are pivoting toward electric steam generator production for European and Southeast Asian markets.
India
Pharmaceutical API manufacturing clusters require validated dry heat sterilization tunnels under CDSCO aseptic processing mandates. The CDSCO compliance requirements for aseptic processing are opening demand for sterilization equipment. Hyderabad and Mumbai pharmaceutical corridors are procuring resistance-based thermal systems for active pharmaceutical ingredient manufacturing.
Japan
Vacuum furnace chamber casting capacity concentrates among specialized foundries serving aerospace heat treatment equipment demand. The METI efficiency standards are driving retrofit cycles across aging manufacturing footprints. Nagoya and Osaka industrial zones are maintaining precision induction heater production for automotive hardening lines.
Industrial Heating Equipment Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers. Large-scale diversified industrial groups compete against specialized thermal equipment fabricators and regional boiler refurbishment specialists. Equipment-as-a-service leasing is rewriting competitive entry barriers for mid-scale thermal operators. M&A activity concentrates on power electronics capabilities and captive project finance arms.
Among diversified industrial conglomerates, Thermax and Alfa Laval exemplify archetypes bundling installation with long-term service contracts or sustaining margin pools through backward integration into core component manufacturing. SECO/WARWICK GROUP occupies a position within the specialized fabricator tier, navigating multi-jurisdiction compliance through vacuum furnace architectures. These three entities represent distinct strategic postures: captive finance integration, upstream component control, and preemptive regulatory compliance engineering.
| Leading Market Players |
|---|
| Thermon |
| Abbott Furnace Company |
| Alfa Laval |
| Lindberg/MPH |
| SECO/WARWICK GROUP |
| Thermax |
| Trane Technologies |
| Ipsen USA |
| Babcock & Wilcox Enterprises |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu provinces anchor export-oriented electric steam generator capacity, concentrating pricing power among domestic fabricators serving European emissions-mandated buyers while compressing margins for second-tier assemblers dependent on spot component markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium induction systems command positioning through CE-certified silicon carbide power modules and bundled predictive maintenance contracts. Standard resistance heaters compete on nickel-chromium alloy sourcing scale and regional logistics reach. Cost compression in economy tiers intensifies as Chinese fabricators absorb copper price volatility to defend European export share. Chemical processing facilities in Texas and Louisiana exhibit highest price sensitivity, prioritizing response-time guarantees over brand premiums.
Supply Chain Analysis
Export control regimes on advanced power electronics constrain silicon carbide MOSFET flows from Japan and Germany to third-party fabricators, fragmenting procurement strategies. Vacuum furnace chamber casting capacity concentrates in Germany and Japan, creating aerospace equipment bottlenecks. Copper coil winding and IGBT module assembly draw from South Korean and Chinese component ecosystems. Single-source vulnerability runs through specialized foundry capacity for high-temperature alloy chambers. Distribution runs through OEM-direct channels for large installations, with independent service contractors capturing mid-scale aftermarket spend.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric heating architectures are forcing seven-year replacement cycles against historical fifteen-year baselines, creating a high-growth disruption window as EPA Boiler MACT and EU F-Gas Regulation deadlines compress procurement timelines.
For Market Incumbents: Harden service network density in automotive powertrain corridors to preempt independent contractor capture of induction heater maintenance spend. Deepen backward integration into silicon carbide power module supply through captive semiconductor partnerships, insulating margin pools from raw material volatility that threatens contract bidding competitiveness.
For New Entrants and Emerging Players: Pursue equipment-as-a-service leasing penetration among mid-scale thermal operators excluded by upfront capital barriers in India pharmaceutical sterilization and Southeast Asian food processing clusters. Target validated dry heat sterilization tunnel demand under CDSCO mandates with bundled compliance documentation and local service presence.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power electronics specialists with silicon carbide design capabilities and captive project finance arms capable of bundling long-term service contracts. Long-term viability hinges on carbon border adjustment mechanism preparedness. Monitor hydrogen-ready burner retrofit kit pilot adoption in German steel reheating furnaces as electrification bridge technology inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive silicon carbide module production insulates margin pools from copper and semiconductor cost volatility. |
| Equipment-as-a-Service Leasing | Bundled installation and maintenance contracts penetrate mid-scale operators previously excluded by capital barriers. |
| Hydrogen-Ready Burner Retrofit Kits | Bridge technology for steel reheating furnaces awaiting full electrification under carbon border adjustments. |
| Validated Sterilization Equipment Certification | CDSCO compliance documentation opens pharmaceutical API manufacturing clusters in Hyderabad and Mumbai corridors. |
| Predictive Thermal Modeling Platforms | Solid-state induction systems with IoT monitoring extend operational lifespans beyond traditional maintenance intervals. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, EU ECHA substance databases, and Chinese customs trade data. Plant engineers, maintenance directors at chemical processing facilities, OEM procurement teams, and aftermarket service heads provided operational perspective on replacement cycle compression. SEC 10-K disclosures from listed equipment fabricators and GB standards documentation supplied financial and technical validation. Bottom-up equipment shipment analysis triangulates against top-down industrial capacity expansion tracking.
Forecast inputs span product type, end-use sector, technology architecture, and application thermal profile across the projection horizon. CAGRs derive from segment-level replacement cycle modeling and regulatory deadline clustering. Electric heating adoption curves incorporate grid decarbonization timelines and carbon border adjustment implementation schedules. Automotive powertrain electrification roadmaps inform induction heater demand specifications.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, copper commodity trajectories, or semiconductor foundry capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and grid infrastructure upgrade pacing. Cross-checking against IEA industrial energy efficiency benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Hydronic Radiators Market