
 Duct Fans Market | 2026-2036
Duct Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Duct Fans Market Foresight
Consolidation among commercial real estate portfolio owners is recalibrating procurement volumes toward long-term service contracts. Systemair AB leverages its pan-European distribution network to sustain aftermarket revenue streams. Greenheck Fan Corporation anchors North American specification channels through deep HVAC contractor relationships. Twin City Fan Companies competes on custom industrial configurations for power generation clients.
Duct fans are electromechanical air-moving devices installed within HVAC distribution networks, typically rated from 100 to 50,000 CFM with static pressure capabilities exceeding 10 inches water gauge, designed to overcome system resistance while maintaining target airflow volumes in conditioned spaces. Inline fans lead specification sheets for space-constrained retrofits where plenum access is restricted, while mixed flow fans represent the fastest-growing product category by blending axial efficiency with centrifugal pressure characteristics. Ceiling mounted installations dominate residential replacement cycles, whereas ducted configurations capture margin pools in cleanroom and laboratory applications requiring positive pressure maintenance.
The US Department of Energy enforces fan efficiency rating standards that disqualify sub-peak products from federal procurement, while the EPA's Energy Star certification shapes consumer preference in residential segments. Europe's Ecodesign Directive and F-Gas Regulation jointly pressure manufacturers toward lower wattage motors and sealed bearing assemblies that reduce refrigerant leakage pathways. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to regionalize motor production or absorb incremental compliance costs through specification upgrades.
Market Dynamics
Commercial real estate portfolio consolidation is compressing procurement cycles toward multi-year service agreements, forcing manufacturers to restructure revenue models around predictive maintenance rather than episodic equipment sales.
Growth Catalysts
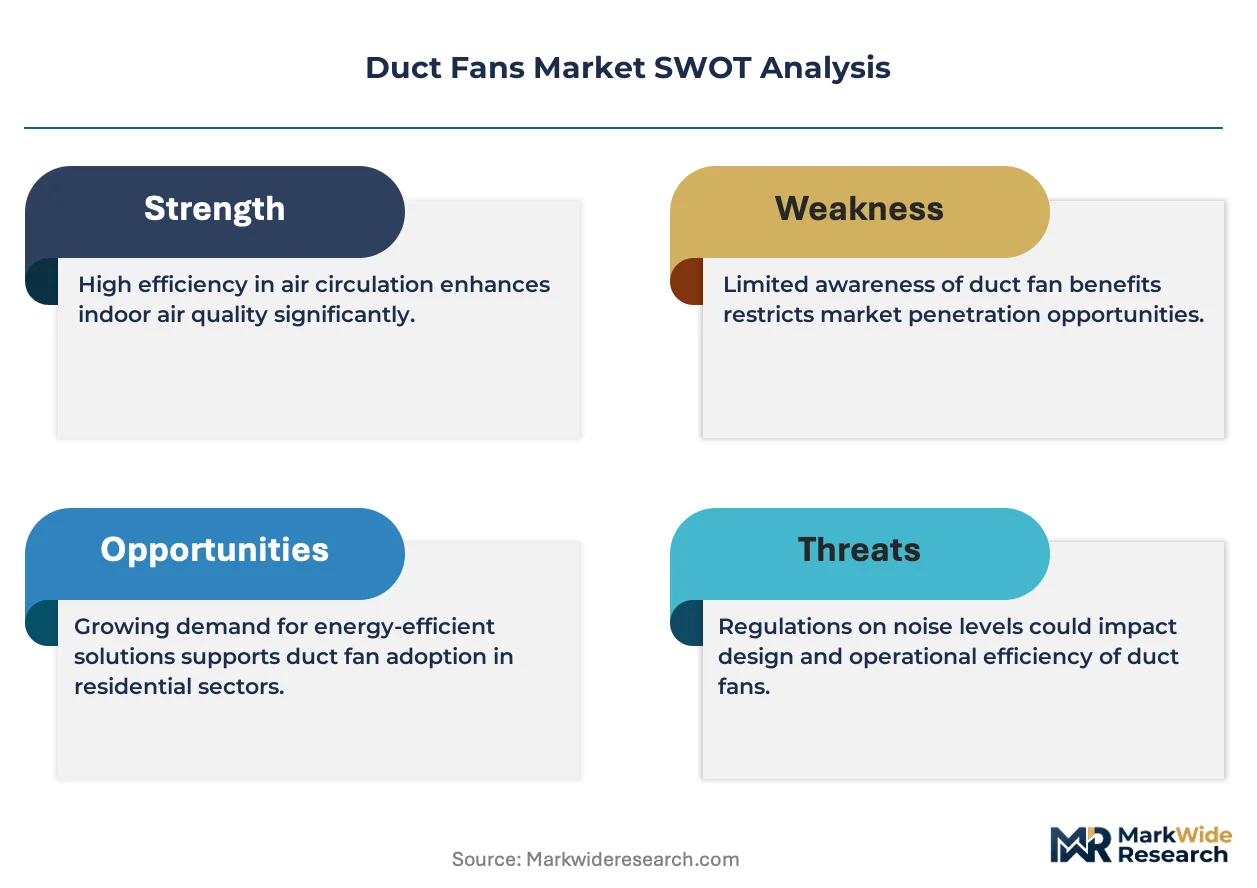
- Energy recovery ventilation mandates:Germany's industrial corridor enforces heat recovery thresholds in manufacturing facilities, driving specification of high-efficiency mixed flow configurations for process cooling applications.
- Fan efficiency rating standards:The US Department of Energy disqualifies sub-peak products from federal procurement, accelerating replacement of aging constant-speed units with electronically commutated motor systems.
- Cleanroom positive pressure requirements:Pharmaceutical and semiconductor fabrication facilities in Singapore and Ireland demand ducted configurations with sealed bearing assemblies to maintain ISO 14644 contamination control.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing facilities exposes permanent magnet motor production to export quota volatility and tariff escalation.
- Copper and aluminum price volatility:Winding wire and housing material costs fluctuate with London Metal Exchange pricing, compressing margins on fixed-price municipal HVAC contracts.
- Refrigerant leakage pathway regulations:Europe's F-Gas Regulation mandates sealed bearing designs that increase unit cost by 15-25 percent versus conventional open-bearing alternatives.
Strategic Opportunities
- Data center thermal management:Hyperscale facilities in Northern Virginia and Frankfurt require inline fan arrays with variable frequency drives for aisle containment and hot aisle containment architectures.
- Carbon border adjustment mechanism positioning:Manufacturers with EU-based motor production gain preference in public procurement scoring against Asian imports subject to embedded carbon tariffs.
- Smart building integration:BACnet and Modbus protocol convergence with fan controllers enables predictive maintenance subscriptions in commercial office retrofits.
Industry Challenges
- Electronics-embedded mechanical engineering talent scarcity:Variable frequency drive programming and IoT sensor integration require hybrid skill sets that outpace vocational training pipeline output.
- Legacy pneumatic control system integration:Industrial facilities with 1980s-era building automation infrastructure face protocol translation complexity when upgrading to digital fan speed modulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duct Fans Market |
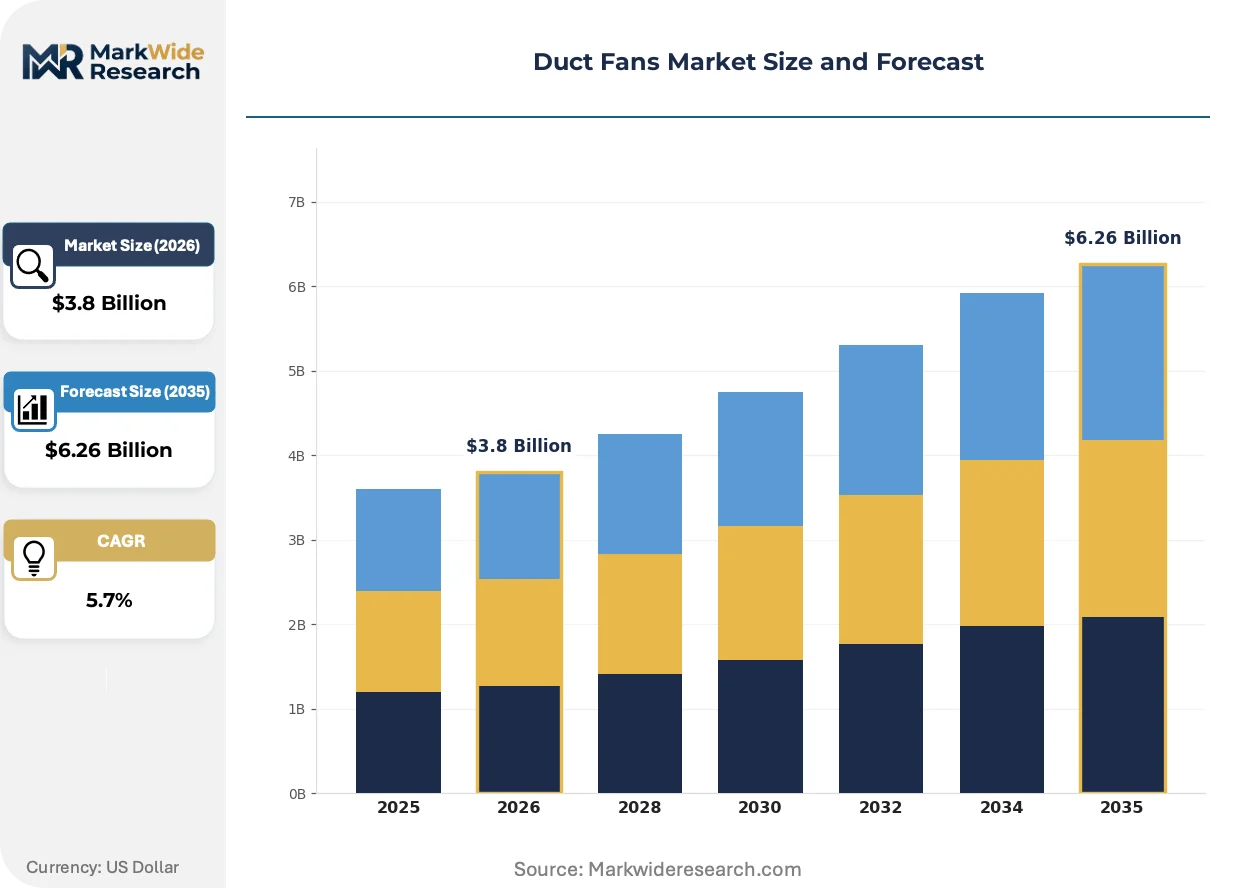
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Fans, Exhaust Fans, Centrifugal Fans, Mixed Flow Fans Installation Type: Ceiling Mounted, Wall Mounted, Ducted, Portable End User: Residential, Commercial, Industrial, Agricultural Power Rating: Low Power, Medium Power, High Power, Variable Speed |
| Companies Covered | Systemair AB, Greenheck Fan Corporation, Twin City Fan Companies, Soler & Palau S.A., Continental Fan Manufacturing Inc., Ziehl-Abegg SE, Loren Cook Company, Fantech Pty Ltd, Broan-NuTone LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duct Fans Market Shifts & Advancements
Permanent magnet synchronous motor technology is absorbing specification share from induction motor architectures, while regulatory pressure on embodied carbon reshapes supply chain geography and procurement scoring methodologies.
Electronically commutated motor systems with integrated variable frequency drives are absorbing market share in commercial HVAC retrofits where plenum access restrictions favor compact inline configurations. Facility managers in US healthcare and education sectors specify these units for demand-controlled ventilation compliance. The technology is absorbing specification volume previously captured by belt-driven centrifugal alternatives.
The US Department of Energy's amended fan efficiency rating standards tighten minimum peak efficiency thresholds and mandate multi-point testing protocols. Equipment manufacturers must redesign impeller geometries and motor windings to maintain federal procurement eligibility. Commercial specification channels in California and New York respond fastest due to state-level stretch codes that anticipate federal ratcheting.
Building automation system integration now dictates procurement preference beyond standalone unit cost. Mechanical contractors in Germany's Ruhr industrial cluster bundle fan specification with predictive maintenance software subscriptions. This pattern concentrates in facilities with ISO 50001 energy management certification where continuous commissioning requirements favor connected equipment.
Duct Fans Market Segmentation
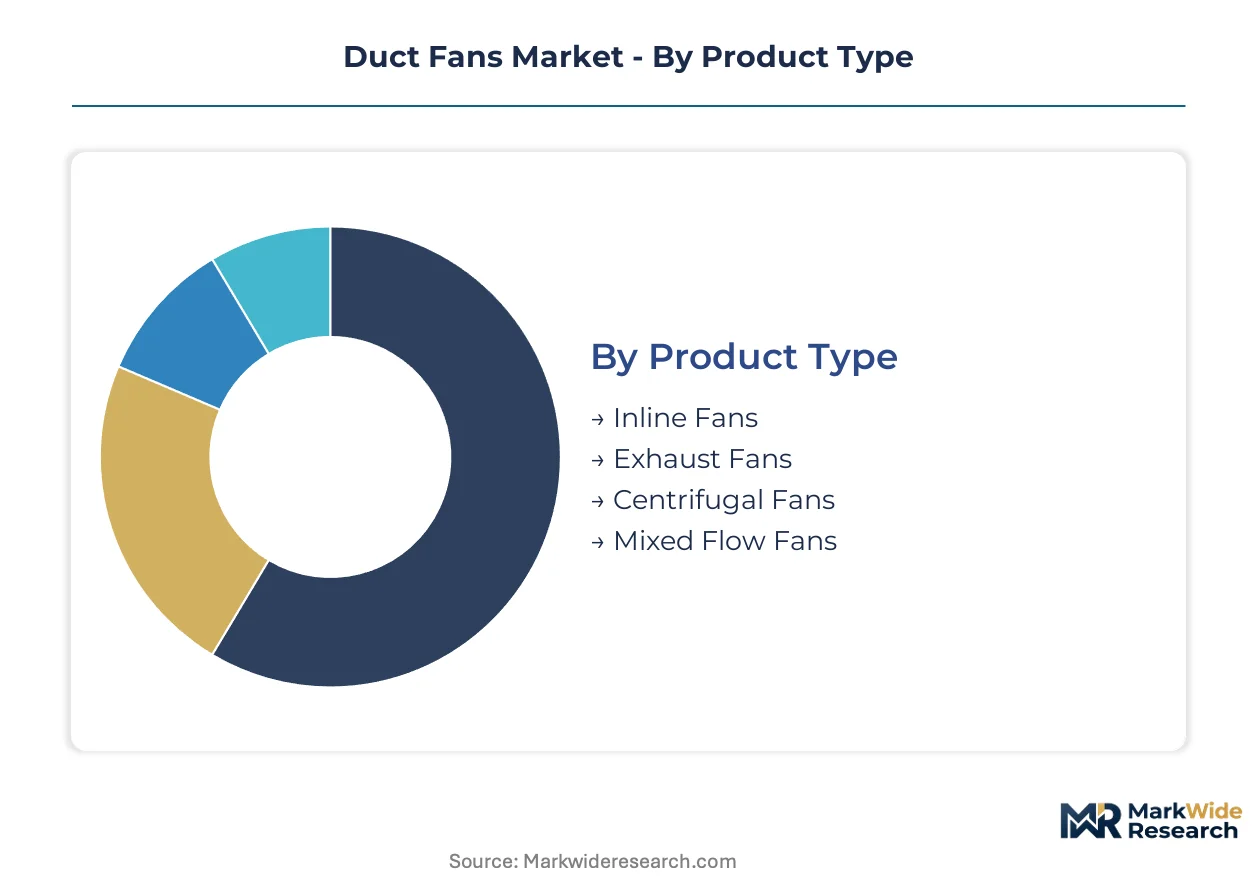
Duct fan specifications diverge sharply across building typologies and airflow requirements. Product architecture, mounting constraints, and end-use intensity each create distinct procurement channels with separate margin structures and replacement cycles.
Product Type:
Inline fans command volume leadership in retrofit-heavy corridors, while mixed flow configurations capture specification premiums in process-intensive environments.
- Inline Fans:Compact electromechanical units install directly within ductwork runs, typically rated 100-2,000 CFM for space-constrained commercial retrofits. Demand concentrates in US healthcare and education sectors where plenum access restrictions favor minimal footprint designs and demand-controlled ventilation compliance drives specification. These units are displacing belt-driven centrifugal alternatives in mid-pressure applications.
- Mixed Flow Fans:Hybrid impeller geometries blend axial flow efficiency with centrifugal pressure generation, achieving static pressure capabilities exceeding 6 inches water gauge. Germany's industrial corridor specifies these for energy recovery ventilation systems where heat recovery thresholds mandate high-efficiency process cooling. The technology is gaining share fastest in pharmaceutical cleanrooms requiring precise pressure maintenance.
- Exhaust Fans:Single-point discharge units rated for moisture and contaminant removal in residential kitchens and bathrooms.
- Centrifugal Fans:Belt-driven or direct-drive architectures with forward-curved or backward-inclined impellers for high-static industrial applications.
Mature deployment sits with centrifugal fans in heavy industrial ventilation. Newer deployment is concentrated in mixed flow configurations for energy recovery mandates.
Installation Type:
Mounting geometry determines labor intensity, accessibility for maintenance, and compatibility with existing building infrastructure.
- Ducted:Fully enclosed configurations integrate within HVAC distribution networks, requiring sealed bearing assemblies for positive pressure maintenance in ISO 14644 cleanrooms. Demand concentrates in Singapore and Ireland semiconductor fabrication facilities where contamination control protocols specify sealed pathways. Europe's F-Gas Regulation compliance adds 15-25 percent cost premium versus open-bearing alternatives.
- Ceiling Mounted:Surface or recessed units attach directly to structural elements for residential replacement cycles and light commercial applications. US residential markets specify these for bathroom and kitchen exhaust where Energy Star certification shapes consumer preference. Replacement demand accelerates in aging housing stock across the Northeast and Midwest.
- Wall Mounted:Through-wall configurations for localized exhaust without ductwork distribution.
- Portable:Temporary units for construction drying, event ventilation, and emergency remediation.
Volume procurement favors ceiling mounted units in residential channels. Specification premiums concentrate in ducted configurations for controlled environments.
End User:
Intensity of operation and regulatory exposure create four distinct customer archetypes with separate procurement behaviors.
- Commercial:Office, retail, and institutional facilities with 8-16 hour daily operation cycles and ASHRAE ventilation compliance requirements. Portfolio consolidation among US real estate investment trusts compresses procurement toward multi-year service agreements with predictive maintenance subscriptions. California and New York stretch codes anticipate federal fan efficiency rating ratcheting.
- Industrial:Manufacturing and process facilities with continuous operation, high particulate loading, and aggressive chemical exposure. Germany's Ruhr industrial cluster bundles fan specification with building automation integration and ISO 50001 continuous commissioning requirements. These specifications prioritize mean time between failure over first cost.
- Residential:Single-family and multifamily dwellings with intermittent operation and price-sensitive replacement cycles.
- Agricultural:Livestock ventilation and crop storage applications with high humidity and ammonia exposure.
Service contract penetration is deepest in commercial portfolios. Direct equipment sales dominate residential replacement cycles.
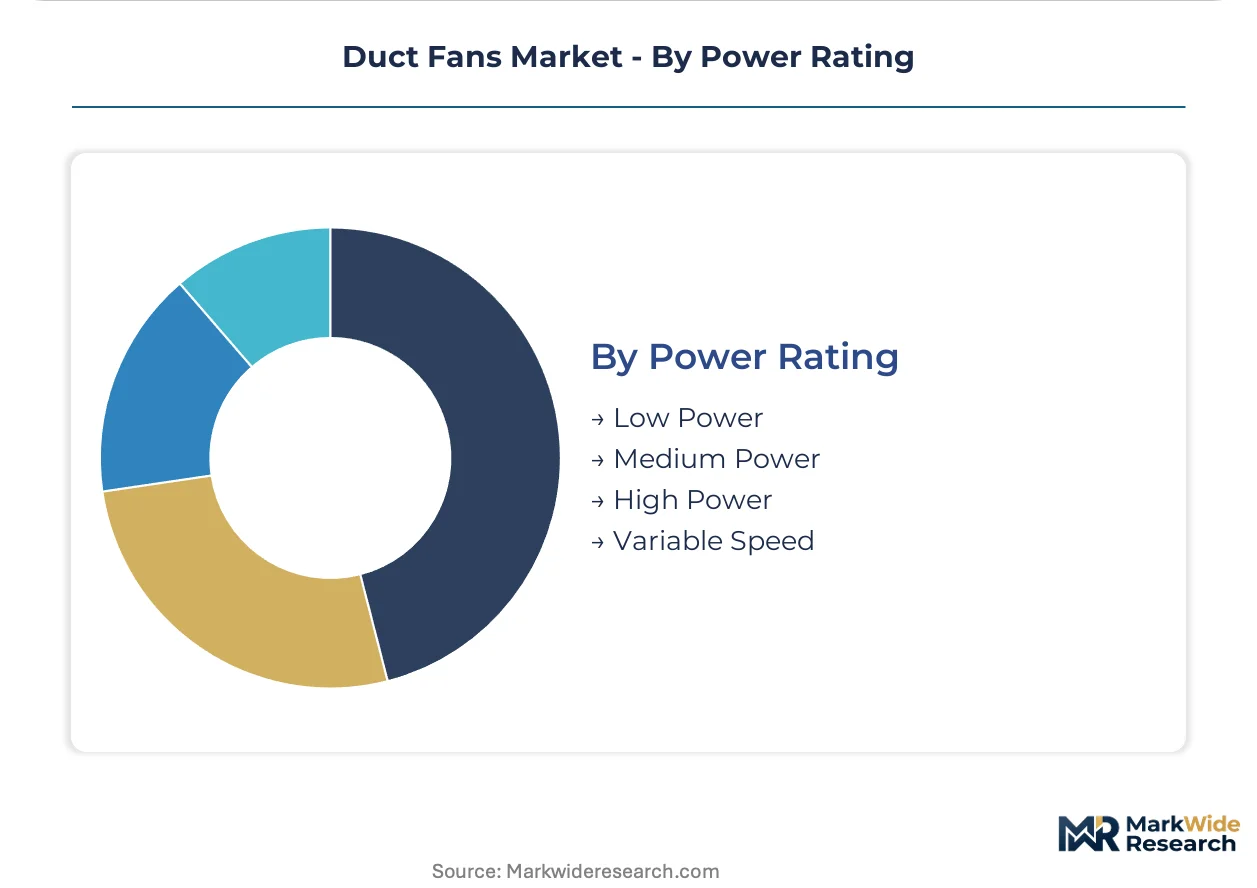
Power Rating:
Motor architecture and speed control capability segment procurement into efficiency tiers with distinct regulatory treatment.
- Variable Speed:Electronically commutated motor systems with integrated variable frequency drives modulate airflow against demand signals. US Department of Energy fan efficiency rating standards mandate multi-point testing protocols that disqualify constant-speed alternatives from federal procurement. Northern Virginia and Frankfurt hyperscale data centers specify these for aisle containment thermal management.
- High Power:Permanent magnet synchronous or premium induction motors rated above 15 kW for industrial process ventilation. Rare earth magnet supply concentration in Chinese processing facilities exposes production to export quota volatility.
- Medium Power:Standard efficiency induction motors for commercial HVAC baseline specifications.
- Low Power:Fractional horsepower units for residential and light commercial exhaust applications.
Regulatory preference is shifting toward variable speed architectures. Fixed-speed medium power units retain share in budget-constrained municipal contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's industrial corridor, where manufacturing facilities prioritize energy recovery ventilation systems. The US commercial retrofit channel accelerates replacement cycles through federal efficiency mandates. Singapore and Ireland anchor cleanroom specification demand for semiconductor fabrication.
Germany
Heat recovery thresholds in manufacturing facilities drive specification of high-efficiency mixed flow configurations. The F-Gas Regulation mandates sealed bearing designs that increase unit cost versus conventional alternatives. The Ruhr industrial cluster bundles fan specification with building automation integration and ISO 50001 continuous commissioning requirements.
United States
Healthcare and education sectors specify compact inline fans for demand-controlled ventilation compliance. The Department of Energy's fan efficiency rating standards disqualify sub-peak products from federal procurement. Northern Virginia hyperscale data centers require inline fan arrays with variable frequency drives for aisle containment architectures.
Singapore
Pharmaceutical and semiconductor fabrication facilities demand ducted configurations with sealed bearing assemblies. The national environmental regulator enforces contamination control protocols aligned with ISO 14644 standards. The Jurong Island chemical cluster maintains positive pressure maintenance requirements for process-critical ventilation systems.
Ireland
Semiconductor cleanrooms specify ducted configurations with sealed bearing assemblies for contamination control. The EPA enforces industrial emissions standards that shape ventilation system design. The Cork and Dublin metro areas concentrate pharmaceutical fabrication facilities with ISO 14644 compliance requirements.
France
Commercial office retrofits in Paris and Lyon accelerate service contract penetration for predictive maintenance subscriptions. The Ecodesign Directive pressures manufacturers toward lower wattage motors and reduced refrigerant leakage pathways. The Île-de-France region concentrates portfolio owners consolidating procurement toward multi-year agreements.
Duct Fans Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart building integration and predictive maintenance software. The vendor base stratifies across three tiers: pan-European distribution networks, North American specification channels, and custom industrial specialists. Strategic archetypes include efficiency-focused motor innovators, service-contract bundlers, and cleanroom contamination control specialists. Dominant competitive moves encompass geographic expansion through distribution partnerships and backward integration into motor production to mitigate rare earth supply exposure.
Among European-based ventilation specialists, Systemair AB exemplifies the pan-European distribution archetype, while Ziehl-Abegg SE occupies a position within precision motor technology. Greenheck Fan Corporation anchors North American specification channels. Twin City Fan Companies represents the custom industrial configuration specialist serving power generation and process-intensive environments.
| Leading Market Players |
|---|
| Systemair AB |
| Greenheck Fan Corporation |
| Twin City Fan Companies |
| Soler & Palau S.A. |
| Continental Fan Manufacturing Inc. |
| Ziehl-Abegg SE |
| Loren Cook Company |
| Fantech Pty Ltd |
| Broan-NuTone LLC |
| Others |
Supply & Pricing Matrix
Electronically commutated motor adoption simultaneously compresses manufacturing cost curves and concentrates supplier power among Asian motor specialists with permanent magnet winding expertise. The technology transition reshapes procurement economics as sealed bearing assemblies mandated by Europe's F-Gas Regulation add 15-25 percent unit cost premiums versus conventional alternatives.
Pricing Analysis
Volume procurement concentrates in ceiling-mounted residential exhaust units with Energy Star certification, while margin pools accrue to ducted configurations for ISO 14644 cleanrooms. Price differentiation separates sealed-bearing premium tiers from open-bearing economy alternatives, with certification grade and after-sales service bundling as secondary drivers. Cost compression in medium-power induction motor segments is intensifying because of copper and aluminum price volatility on London Metal Exchange markets. Municipal HVAC contractors exhibit highest price sensitivity due to fixed-price contract structures, whereas pharmaceutical cleanroom operators prioritize mean time between failure over first cost.
Supply Chain Analysis
Certification gating through DOE fan efficiency rating standards and EPA Energy Star programs restricts federal procurement eligibility to redesigned impeller geometries and multi-point tested motor systems. Permanent magnet synchronous motor production draws from Chinese rare earth processing facilities for neodymium and dysprosium, with secondary winding wire sourcing from Germany and Japan. Single-source vulnerability in rare earth magnet supply exposes manufacturers to export quota volatility and tariff escalation. Distribution runs through pan-European HVAC wholesalers in Germany, specification-grade mechanical contractors in the United States, and cleanroom engineering specialists in Singapore and Ireland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The duct fans market sits in a technology-transition phase as electronically commutated motor systems with integrated variable frequency drives displace belt-driven centrifugal architectures in commercial retrofit specifications.
For Market Incumbents: Cement specification channel control through deep HVAC contractor relationships in North American healthcare and education sectors. Deepen backward integration into permanent magnet motor production to mitigate rare earth supply exposure from Chinese processing concentration. Prioritize predictive maintenance software subscriptions to capture recurring revenue from commercial real estate portfolio consolidation.
For New Entrants and Emerging Players: Begin with data center thermal management segments in Northern Virginia and Frankfurt where hyperscale facilities require inline fan arrays with BACnet protocol integration. Target white-space opportunities in smart building integration for ISO 50001-certified industrial facilities in Germany's Ruhr cluster. Pursue a go-to-market angle bundling fan specification with continuous commissioning software subscriptions.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pan-European ventilation specialists seeking North American specification channel access. Long-term viability favors manufacturers with EU-based motor production positioned against carbon border adjustment mechanism scoring. Acquisition target archetypes include cleanroom contamination control specialists with sealed bearing assembly expertise. Watch for inflection signals in rare earth export quota announcements from Chinese regulatory authorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive rare earth magnet supply reduces exposure to Chinese export quota volatility and tariff escalation. |
| Predictive Maintenance Software Launch | BACnet protocol convergence enables subscription revenue from commercial real estate portfolio owners consolidating procurement. |
| Cleanroom Certification Investment | ISO 14644 compliance opens specification channels in Singapore semiconductor fabrication and Ireland pharmaceutical facilities. |
| Geographic Expansion through Distribution Partnerships | Pan-European HVAC wholesaler relationships accelerate aftermarket parts revenue and service contract penetration. |
| Sealed Bearing Assembly Product Line | F-Gas Regulation compliance captures margin premiums in Europe's industrial corridor despite 15-25 percent unit cost increase. |
Research Methodology
Multi-period observation of DOE fan efficiency rating compliance rates, rare earth export quota announcements, and commercial real estate portfolio transaction volumes anchored the trend analysis, supplemented by interviews with HVAC contractor specification managers, plant engineers at Germany's Ruhr industrial facilities, cleanroom engineering consultants in Singapore, and aftermarket service directors at pan-European distribution networks. Secondary validation drew from DOE appliance standards filings, EPA Energy Star certified product listings, Ecodesign Directive implementation reports, London Metal Exchange copper and aluminum price data, and SEC 10-K disclosures from publicly traded ventilation equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down construction spending and HVAC retrofit investment flows.
Segment-weighting across product architecture, installation geometry, end-use intensity, and power rating tiers informed volume and value allocation through the projection horizon. The analytical framework modeled inline, mixed flow, exhaust, and centrifugal configurations against commercial, industrial, residential, and agricultural demand archetypes. CAGRs were derived from regression analysis of replacement cycle acceleration, regulatory compliance deadlines, and technology substitution rates. Forecast inputs incorporated permanent magnet motor cost curves, sealed bearing assembly penetration assumptions, and smart building automation integration adoption patterns.
Underlying measurement precision varies by segment; cleanroom and data center specifications carry tighter precision than residential replacement cycles due to documented procurement volumes and regulatory filing requirements. Forecasts reflect assumptions around rare earth supply stability, copper price volatility bands, and stretch code adoption timing in California and New York. A model refresh is warranted upon material change in Chinese rare earth export policy or federal fan efficiency rating standard amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Underfloor Heating Market