
 Steam Humidifiers Market | 2026-2036
Steam Humidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Humidifiers Market Analytics
Aftermarket service revenue is fragmenting across the installed base as end users extend equipment life cycles rather than replace aging units. Condair Group AG leverages its global service network to capture recurring maintenance contracts. Armstrong International Inc. anchors its position through spare parts availability and technical field support. CAREL INDUSTRIES S.p.A. differentiates via cloud-connected diagnostics that reduce unplanned downtime for commercial clients.
A steam humidifier is a device that generates water vapor through thermal energy input to raise ambient relative humidity, typically operating at pressures from atmospheric to 15 psig and delivering outputs measured in pounds per hour of steam. Its primary purpose is to protect sensitive processes, preserve material integrity, and maintain occupant health in controlled environments. Industrial electrode and immersion technologies dominate current procurement volumes due to lower capital outlay and simpler maintenance protocols. Hybrid systems represent the fastest-expanding technology segment as facilities seek redundancy against single-point failures. The commercial HVAC application category sustains the largest margin pool because specification-grade projects command premium pricing for compliance documentation and commissioning support.
The U.S. FDA, EPA, and ASHRAE standards collectively govern humidity parameters in healthcare and pharmaceutical manufacturing, with Joint Commission audits enforcing documented control evidence that drives replacement demand. The EU MDR and F-Gas Regulation impose additional material and refrigerant constraints on systems sold into European medical and climate-control applications. Stakeholders must monitor evolving indoor air quality mandates and assess whether regional certification requirements warrant dedicated product variants or modular platform architectures.
Market Dynamics
Healthcare facilities are extending equipment replacement cycles while tightening precision requirements, forcing suppliers to pivot from unit sales toward lifecycle service contracts and predictive maintenance platforms.
Growth Catalysts
- EU MDR compliance deadlines:Medical device manufacturing facilities across Germany and France are retrofitting cleanrooms with specification-grade humidification systems to meet documentation and environmental control mandates.
- Pharmaceutical cluster expansion:Bio-pharma manufacturing corridors in Switzerland and Belgium are driving procurement of redundant steam humidification architectures to protect batch integrity.
- Electrode technology maturation:Simplified maintenance protocols and lower capital thresholds are accelerating replacement of aging boiler-based systems in mid-scale commercial facilities.
Market Restraints
- Copper and stainless steel input volatility:Raw material price swings for vapor chamber components compress margin visibility for equipment fabricators.
- Regional supply concentration:Critical sensor and control module production clusters in Taiwan and South Korea create single-point vulnerability for European OEM assembly lines.
- Refrigerant-based dehumidifier substitution:Desiccant and cooling-based alternatives capture share in applications where ±5% RH tolerance is acceptable.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO certification requirements and export-oriented production growth create specification-grade demand in Hyderabad and Mumbai clusters.
- Cloud-native diagnostics convergence:Integration of IoT sensors with predictive analytics platforms enables remote commissioning and reduces field service density requirements.
- ASHRAE 170 revision cycles:Updated ventilation standards for healthcare environments mandate documented humidity control evidence, accelerating replacement of non-compliant legacy installations.
Industry Challenges
- Controls engineering specialization:Shortage of technicians proficient in Building Management System integration and BACnet protocol configuration delays commissioning timelines.
- Legacy pneumatic system interoperability:Facilities with 1980s-era HVAC infrastructure face complex retrofit coordination to achieve digital control compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Humidifiers Market |
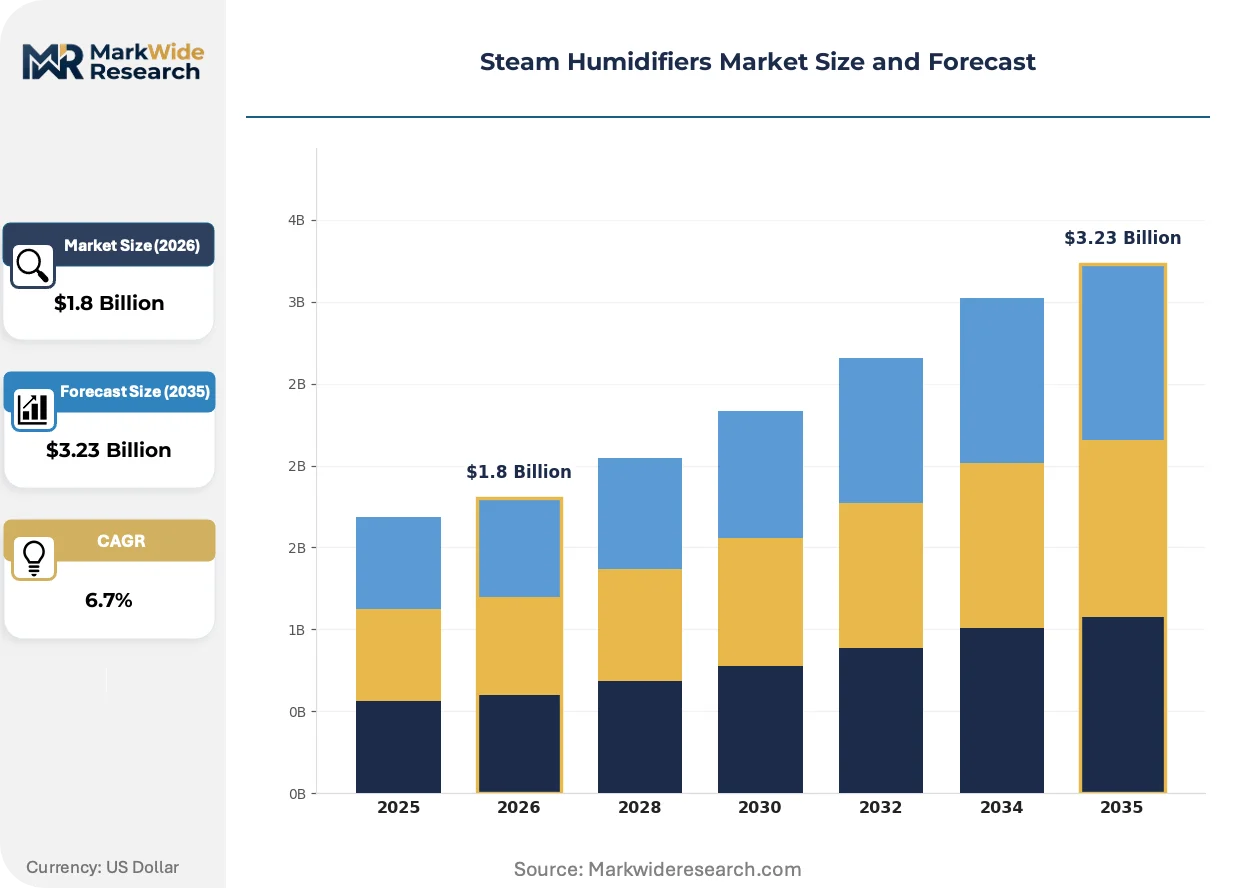
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Portable Application: Healthcare, Agriculture, Industrial Processes, HVAC End User: Hospitals, Laboratories, Greenhouses, Manufacturing Plants Technology: Electrode, Immersion, Steam-to-Steam, Hybrid |
| Companies Covered | Condair Group AG, Armstrong International Inc., CAREL INDUSTRIES S.p.A., DriSteem, Neptronic, Pure Humidifier Company, Spirax Sarco, HygroMatik, Mee Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Humidifiers Market Evolving Landscape
Digital twin architectures and remote service platforms are compressing traditional equipment ownership models, while regulatory documentation requirements harden specification barriers for new market entrants.
Steam humidifier control systems are virtualizing physical commissioning and diagnostic workflows through cloud-connected digital twin platforms. Pharmaceutical manufacturers in Denmark and the Netherlands are adopting these architectures to reduce validation documentation burden. This virtualization is compressing the traditional field service revenue model toward software-subscription economics.
REACH substance restrictions and F-Gas Regulation phase-down schedules are constraining refrigerant choices in climate-control adjacent applications. Equipment suppliers serving European medical markets must now certify material compliance across humidifier wetted surfaces and thermal transfer components. German pharmaceutical OEMs are responding by demanding full material disclosure documentation upstream from component vendors.
Service contract unbundling is fragmenting the traditional bundled procurement model for commercial HVAC projects. Facility managers in US hospital systems are separating humidifier acquisition from commissioning and multi-year maintenance obligations. This behavioral shift is most visible in California and Texas, where energy performance contracting structures favor discrete vendor accountability for humidity control outcomes.
Steam Humidifiers Market Segmentation
Steam humidifier procurement patterns diverge sharply across facility types, with specification-grade requirements in pharmaceutical manufacturing commanding fundamentally different engineering and compliance investments than standard commercial HVAC installations. Technology selection, end-use criticality, and regional regulatory density collectively determine margin structures and vendor qualification barriers within each segment cluster.
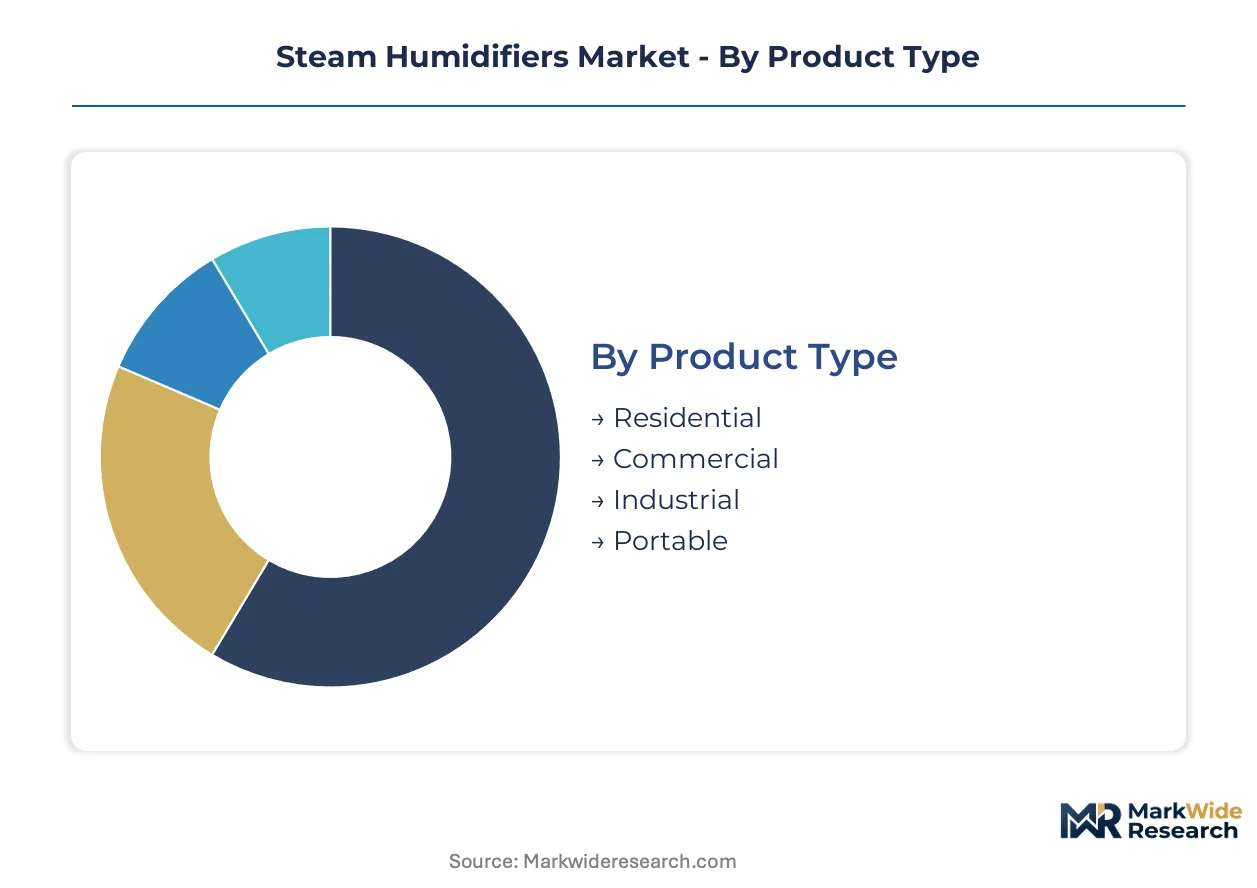
Product Type:
Cost tier differentiation separates specification-grade systems from commodity humidification equipment, with capital outlay thresholds and maintenance protocols varying by an order of magnitude across the spectrum.
- Industrial:High-capacity electrode and immersion systems operate at pressures up to 15 psig, delivering outputs measured in hundreds of pounds per hour. Pharmaceutical manufacturing corridors in Germany and Switzerland specify these units for cleanroom redundancy, driven by batch integrity protection mandates under EU MDR documentation requirements.
- Commercial:Mid-scale distributed steam generators serve office complexes, data centers, and retail environments where ±5% RH tolerance satisfies operational needs. Procurement concentrates in US hospital systems facing Joint Commission audit pressure for documented humidity control evidence.
- Residential:Compact portable and whole-home units address consumer comfort and health concerns in arid climate zones.
- Portable:Mobile electrode-based systems provide temporary humidity control for construction, events, and emergency remediation.
Industrial holds installed capacity. Commercial is rotating up the share rankings.
Application:
End-use criticality determines engineering specification depth, with life-science applications demanding redundant architectures that manufacturing processes and comfort conditioning cannot justify.
- Healthcare:Operating suites, sterile processing departments, and patient care zones require continuous humidity maintenance within narrow bands to prevent electrostatic discharge and pathogen transmission. US FDA indoor air quality guidelines and ASHRAE 170 ventilation standards enforce documented control evidence, accelerating replacement of non-compliant legacy installations.
- Industrial Processes:Textile manufacturing, printing operations, and electronics assembly depend on precise moisture content to prevent material degradation and static damage. Pharmaceutical manufacturing clusters in Belgium and the Netherlands drive specification-grade procurement for API production environments.
- HVAC:General building conditioning represents the largest volume segment, though specification-grade projects command premium pricing for compliance documentation and commissioning support.
- Agriculture:Greenhouse and controlled-environment agriculture operations utilize humidification for crop stress reduction and yield optimization.
HVAC maintains volume leadership. Healthcare is climbing the fastest on specification-grade premium capture.
End User:
Customer type segmentation reveals procurement authority concentration, with facility engineering teams in regulated industries wielding specification power that general contractors in commercial construction cannot match.
- Manufacturing Plants:Pharmaceutical, semiconductor, and precision manufacturing facilities deploy redundant steam humidification architectures to protect process yield. German pharmaceutical OEMs demand full material disclosure documentation upstream from component vendors to satisfy REACH substance restrictions.
- Hospitals:Acute care facilities and integrated delivery networks face tightening compliance requirements from the Joint Commission and state health departments. California and Texas hospital systems are unbundling service contracts from equipment acquisition to enforce discrete vendor accountability.
- Laboratories:Research and quality control environments require stable humidity for analytical instrument calibration and sample integrity.
- Greenhouses:Controlled-environment agriculture operations prioritize capital efficiency over precision, accepting wider control tolerances.
Manufacturing Plants dominate specification-grade revenue. Hospitals are gaining share fastest on regulatory replacement cycles.
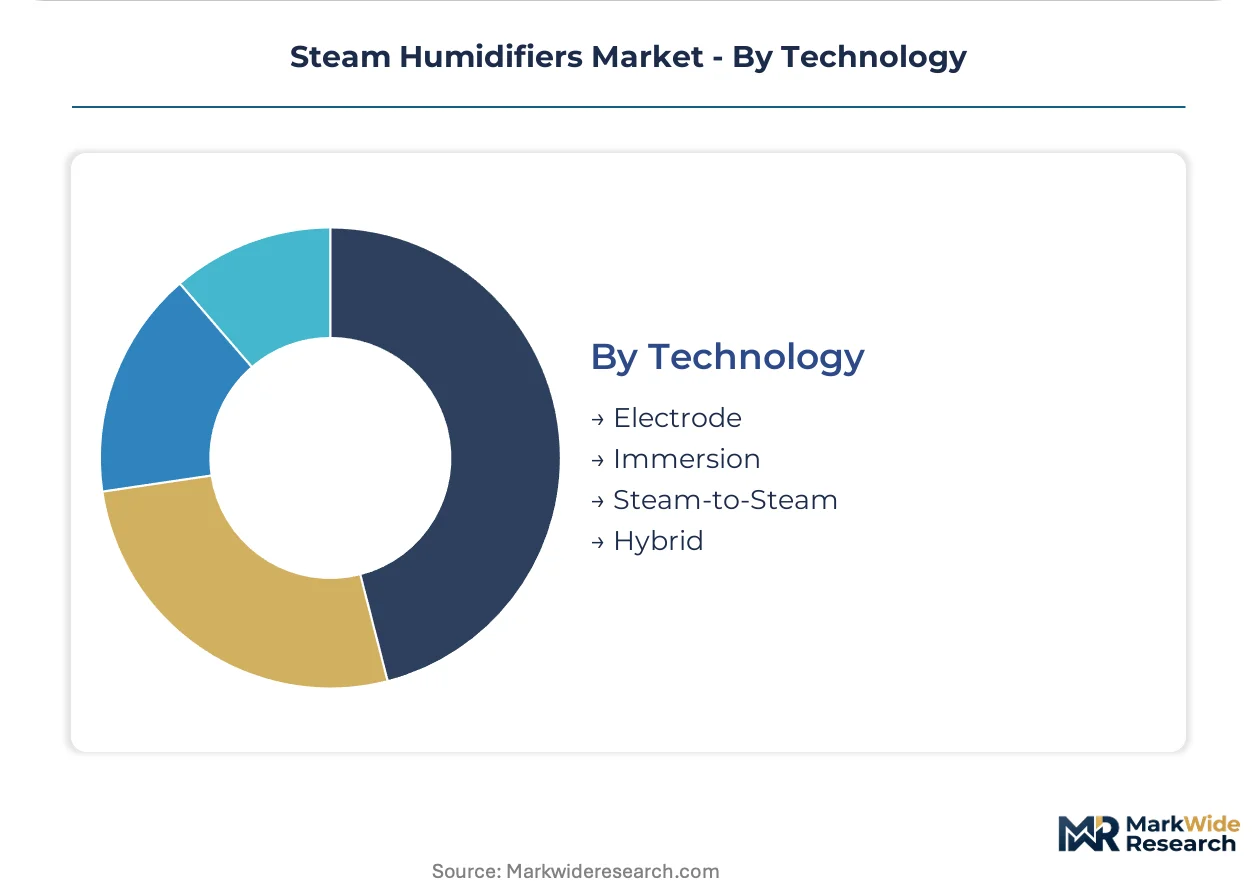
Technology:
Technology maturity curves separate established electrode and immersion systems from emerging hybrid architectures, with maintenance protocol simplicity and capital threshold accessibility driving adoption velocity.
- Electrode:Simplified maintenance protocols and lower capital thresholds accelerate replacement of aging boiler-based systems in mid-scale commercial facilities. The technology dominates current procurement volumes due to field service familiarity and spare parts availability.
- Hybrid:Redundant configurations combining multiple generation methods protect against single-point failures in critical applications. Pharmaceutical manufacturers in Denmark and the Netherlands are adopting these architectures to reduce validation documentation burden through digital twin commissioning platforms.
- Immersion:Direct heating element systems serve high-purity steam requirements where electrode contamination risks are unacceptable.
- Steam-to-Steam:Heat exchanger-based systems isolate process steam from humidification distribution, serving nuclear and chemical processing environments.
Electrode holds installed capacity. Hybrid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German pharmaceutical corridors demonstrate the lowest price elasticity, accepting specification-grade premiums for compliance documentation, while US hospital systems unbundle contracts to enforce discrete vendor accountability and compress acquisition costs.
Germany
Pharmaceutical manufacturing clusters in Baden-Württemberg and Bavaria drive specification-grade electrode system procurement for cleanroom redundancy. EU MDR documentation mandates and REACH substance restrictions on wetted surfaces tighten vendor qualification barriers. Stuttgart and Munich anchor redundant humidification architecture demand as batch integrity protection becomes non-negotiable.
United States
Acute care facilities in California and Texas face Joint Commission audit pressure for documented humidity control evidence. FDA indoor air quality guidelines and ASHRAE 170 ventilation standards accelerate replacement of non-compliant legacy installations. The Southeast hospital construction corridor concentrates procurement of mid-scale commercial systems.
Switzerland
Bio-pharma manufacturing corridors in Basel and Zurich specify hybrid steam architectures to protect API production yield. Swissmedic certification requirements and F-Gas Regulation phase-down schedules constrain refrigerant choices in adjacent climate-control applications. The Basel-Land cluster leads adoption of digital twin commissioning platforms.
India
CDSCO certification requirements and export-oriented pharmaceutical production growth create specification-grade demand in Hyderabad and Mumbai. The country's national pharmaceutical regulator tightens environmental control documentation for active pharmaceutical ingredient facilities. Telangana and Maharashtra manufacturing zones retrofit cleanrooms to capture contract manufacturing organization revenue.
Belgium
Pharmaceutical manufacturing facilities in Flanders and Wallonia deploy redundant humidification to protect sterile processing environments. EU MDR compliance deadlines and ECHA material disclosure mandates drive full supply chain transparency upstream from component vendors. The Antwerp pharmaceutical corridor concentrates high-purity steam-to-steam system specification.
Steam Humidifiers Market Competitive Landscape
Specification-grade system fabricators and commercial HVAC equipment suppliers split the market along compliance-depth fault lines, with tiered procurement authority concentrating in regulated industries. The vendor base organizes around three archetypes: full-stack platform providers with global service networks, regional specialists with deep regulatory navigation expertise, and component-agnostic system integrators. Consolidation pressure concentrates among mid-scale commercial suppliers as hospital procurement unbundling fragments traditional bundled contracts. Geographic expansion and predictive maintenance platform licensing represent the dominant competitive vectors.
Within the full-stack platform tier, Condair Group AG and Armstrong International Inc. exemplify archetypes leveraging global service infrastructure to capture recurring maintenance revenue. CAREL INDUSTRIES S.p.A. occupies a position at the convergence of cloud-native diagnostics and commercial building automation integration. These three anchors demonstrate how vendor qualification in pharmaceutical and healthcare verticals depends less on unit economics than on lifecycle service contract penetration and regulatory documentation depth.
| Leading Market Players |
|---|
| Condair Group AG |
| Armstrong International Inc. |
| CAREL INDUSTRIES S.p.A. |
| DriSteem |
| Neptronic |
| Pure Humidifier Company |
| Spirax Sarco |
| HygroMatik |
| Mee Industries Inc. |
| Others |
Value Network & Pricing Analysis
Copper and stainless steel price volatility for vapor chamber components compresses margin visibility for equipment fabricators, forcing tiered pricing spreads between specification-grade systems and commodity alternatives while simultaneously reshaping supplier geography preferences toward regional metalworking clusters.
Pricing Analysis
Aftermarket service revenue streams anchor lifetime value capture across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade systems with full EU MDR documentation from mid-scale commercial units and basic HVAC commodities. Cost compression in the commercial tier intensifies because hospital procurement unbundling fragments traditional bundled contracts. Manufacturing plants demonstrate the lowest price elasticity, accepting specification-grade premiums for REACH-compliant material disclosure, while residential and portable segments exhibit highest sensitivity to upfront capital thresholds.
Supply Chain Analysis
Export-control restrictions on semiconductor-grade sensors and precision control modules limit flows from Taiwan and South Korea to European OEM assembly lines. Component fabrication draws from Germany, Switzerland, and the United States for specification-grade electrode and immersion systems. Copper sheet and stainless steel tubing feed from regional metalworking centers. Single-source vulnerability concentrates in Taiwanese sensor foundries serving humidity control module production. Distribution runs through authorized service networks and direct specification sales to pharmaceutical OEMs and hospital engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling fragments procurement authority, creating white-space opportunities for specialists who can isolate commissioning expertise from equipment supply.
For Market Incumbents: Harden regulatory documentation depth to defend against cloud-native diagnostics entrants. Invest in REACH-compliant material disclosure upstream from component vendors to satisfy German pharmaceutical OEM demands. Expand predictive maintenance platform licensing to capture recurring revenue as hardware margins compress. For New Entrants and Emerging Players: Mid-market commercial buildings in India represent the most penetrable entry point, where CDSCO certification requirements and export-oriented pharmaceutical growth create specification-grade demand without entrenched incumbent relationships. Target electrode technology retrofits in aging European boiler-replacement cycles. Lead with remote commissioning capabilities to reduce field service density requirements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform providers with captive service networks. Long-term viability hinges on lifecycle contract penetration rather than unit shipment volumes. Watch for ASHRAE 170 revision announcements as inflection indicators accelerating replacement demand in non-compliant legacy installations.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Diagnostics Platform | Condair and CAREL leverage IoT sensor convergence to reduce unplanned downtime for pharmaceutical clients. |
| EU MDR Documentation Investment | Full material disclosure upstream from component vendors satisfies REACH substance restrictions for German cleanroom specifications. |
| Service Network Geographic Expansion | Armstrong International anchors position through spare parts availability and technical field support in hospital systems. |
| Hybrid System Architecture Development | Redundant configurations protect batch integrity for Belgian and Dutch pharmaceutical manufacturers under tightening compliance mandates. |
| Predictive Maintenance Licensing | Remote commissioning platforms compress traditional field service economics toward software-subscription revenue models. |
Research Methodology
The analysis maps electrode, immersion, hybrid, and steam-to-steam technology segments, each validated through facility engineering directors, pharmaceutical plant managers, hospital procurement committees, and HVAC contractor technical leads. Primary interview data triangulates against FDA guidance documents, ASHRAE standards filings, EU MDR compliance databases, and ECHA REACH substance registrations. Secondary sources include customs trade records for copper and stainless steel inputs, SEC filings from publicly traded building automation suppliers, and pharmaceutical manufacturing facility construction permits. Bottom-up unit demand estimates cross-validate against top-down addressable market sizing across healthcare, industrial process, and commercial HVAC end uses.
Forecasts assume steady-state regulatory enforcement intensity across the analysis window, with EU MDR documentation requirements and ASHRAE 170 ventilation standards held fixed at current interpretation levels. Segmentation dimensions include product type, application criticality, technology maturity, and end-user procurement authority concentration. CAGRs derive from installed base turnover rates and specification-grade premium capture trajectories. Modeled inputs incorporate electrode replacement cycle acceleration, hybrid system adoption velocity in pharmaceutical corridors, and service contract unbundling penetration in US hospital systems.
Practitioners should monitor copper price volatility, Taiwan semiconductor export policy shifts, and ASHRAE revision timelines for early signals requiring forecast reassessment. Material shifts in FDA indoor air quality guideline enforcement or EU F-Gas Regulation phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Europe Heat Pump Market