
 Vietnam Architectural Coatings Market | 2026-2036
Vietnam Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Architectural Coatings Market Analytics
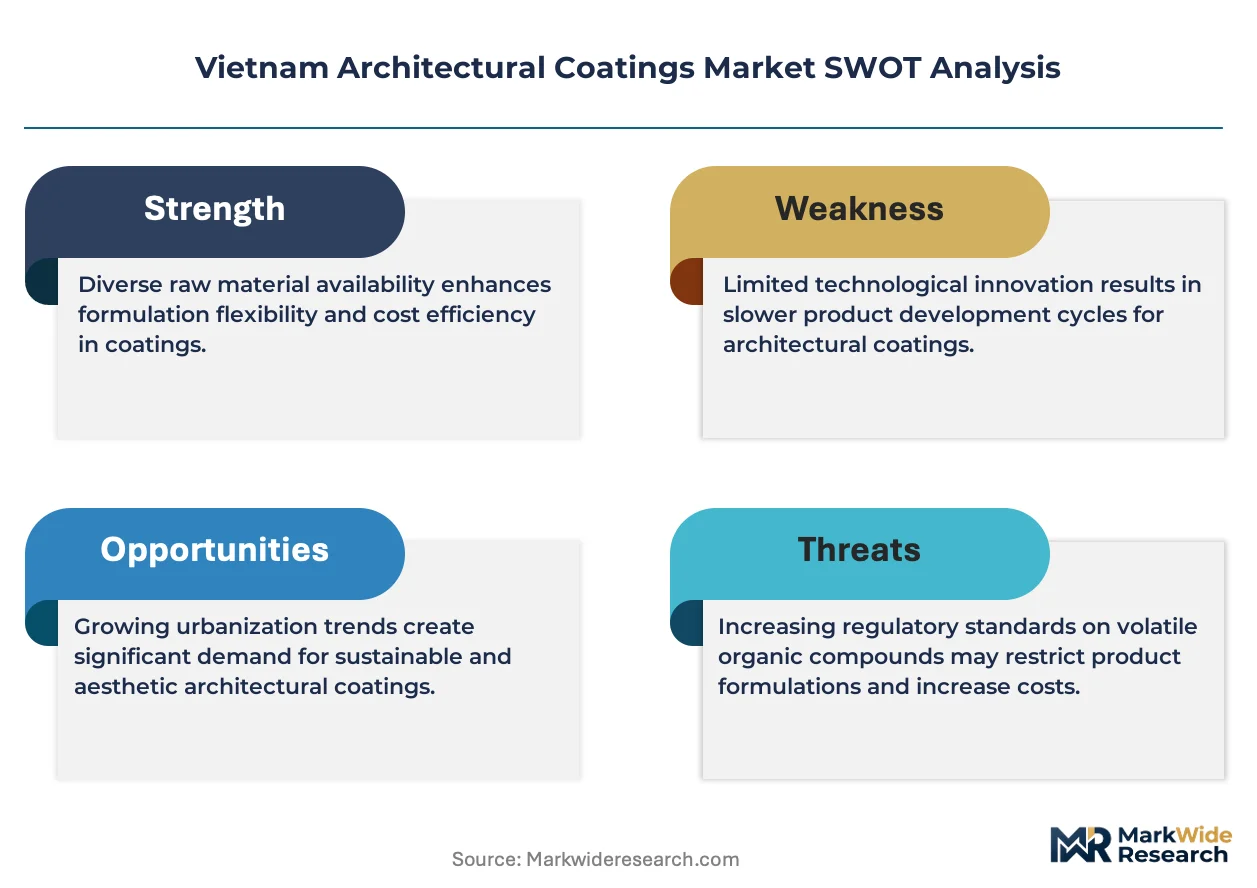
High-rise residential developers is bifurcating from small-scale retail buyers as the dominant specification channel. KOVA Group leverages its domestic manufacturing footprint to anchor supply across northern provinces. PPG Industries, Inc. competes through technology leadership in low-VOC water-based formulations. Jotun sustains premium positioning via specialized marine-grade exterior systems adapted for tropical humidity.
Vietnam architectural coatings encompass liquid and film-forming protective materials applied to building substrates, typically comprising binders, pigments, solvents, and additives engineered for adhesion, weather resistance, and aesthetic finish. These formulations serve primarily to shield concrete, plaster, and masonry from monsoon moisture, UV degradation, and salt-laden coastal air while delivering decorative surfaces. Water-based emulsion systems dominate volume due to regulatory pressure on solvent-borne VOC emissions, though solvent-based enamel retains margin concentration in industrial and high-durability exterior specifications. Interior wall applications absorb the fastest-growing demand share as urban condominium stock expands across tier-one cities, while powder coating technology occupies a niche but expanding position in commercial facade metalwork.
Vietnam's Ministry of Construction enforces QCVN building material standards that limit VOC content and mandate lead-free formulations, compelling reformulation investments across domestic and imported product lines. BIS-equivalent conformity assessment procedures and local fire safety codes under the Department of Fire Prevention and Fighting further shape product registration and market access timelines. Stakeholders must monitor pending amendments to green building certification criteria and provincial urban planning approvals that will determine specification-grade demand concentration across the next development cycle.
Market Dynamics
Vietnam's architectural coatings sector is bifurcating around QCVN emission enforcement, which splits domestic formulators from import-dependent suppliers on compliance investment timelines and product registration cycles.
Growth Catalysts
- QCVN VOC Standards:Vietnam's Ministry of Construction tightened emission limits for interior wall coatings, forcing reformulation investments that favor established domestic producers with captive R&D facilities.
- Red River Delta Urbanization:Hanoi and surrounding provinces are absorbing the majority of new high-rise residential stock, concentrating specification-grade demand in a corridor with established distribution infrastructure.
- Water-Based Emulsion Technology:Low-VOC waterborne systems are capturing volume from solvent-borne enamel in premium interior segments as developer specifications harden on indoor air quality metrics.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Pigment costs swing with global sulfate-process supply disruptions, compressing margin visibility for mid-tier Vietnamese formulators lacking long-term offtake contracts.
- Import Dependency on Epoxy Resins:Specialty-grade binders for marine-adapted exterior systems concentrate through Singapore and South Korea transshipment hubs, exposing lead time risk during regional port congestion.
- Monsoon Durability Ceiling:Conventional acrylic emulsions face performance limits in Mekong Delta humidity cycles, restricting warranty extension and premium pricing power in coastal provinces.
Strategic Opportunities
- Central Highlands Commercial Construction:Da Nang and surrounding secondary cities are absorbing logistics and light manufacturing facilities, creating specification entry points outside Ho Chi Minh City-Hanoi duopoly.
- Green Building Certification Alignment:Pending amendments to Vietnam Green Building Council criteria will mandate low-emitting interior finishes, positioning early QCVN-compliant registrants for preferred vendor status.
- Powder Coating Metalwork Integration:Curtain wall and aluminum facade fabricators are adopting electrostatic application systems, opening adjacent coating technology partnerships for architectural suppliers with formulation flexibility.
Industry Challenges
- Fire Safety Certification Bottlenecks:Department of Fire Prevention and Fighting approval timelines for intumescent and fire-retardant coating variants extend market access by 8-14 months versus standard interior emulsions.
- Technical Service Workforce Scarcity:Application specification expertise for humidity-engineered exterior systems concentrates among aging contractor networks in Ho Chi Minh City, constraining quality deployment in emerging provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Architectural Coatings Market |
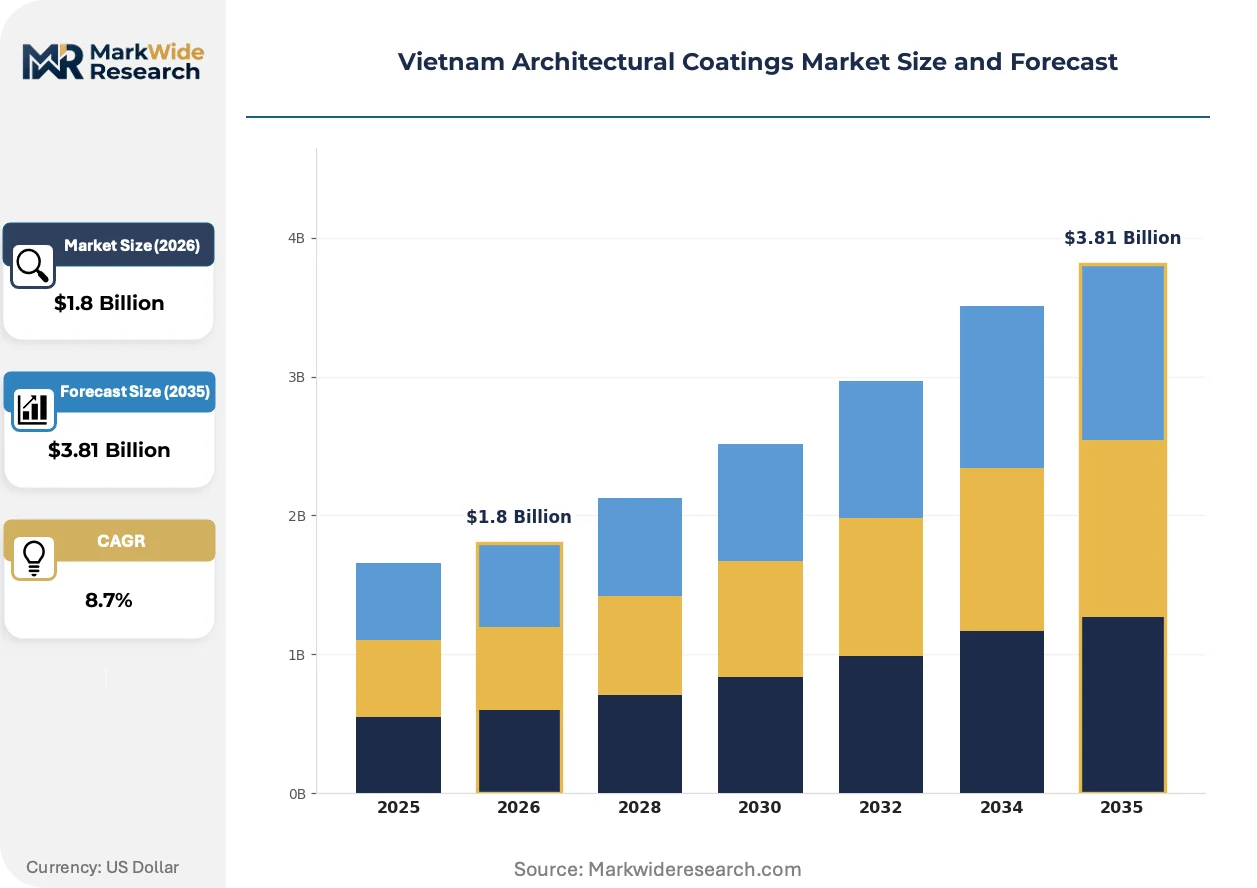
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Enamel, Primer, Sealant Application: Interior Walls, Exterior Walls, Ceilings, Floors Technology: Water-Based, Solvent-Based, Powder Coating, UV-Curable Delivery Mode: Roller, Brush, Spray, Others |
| Companies Covered | KOVA Group, PPG Industries, Inc., Jotun, Dong Tam, Hoa Binh Paint, AkzoNobel N.V., 4Oranges Co., Ltd., Toa Vietnam, Nippon Paint Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Architectural Coatings Market Evolving Landscape
Formulation chemistry and procurement protocols are simultaneously evolving, with regulatory pressure and buyer consolidation forcing technology investment ahead of traditional replacement cycles.
Self-cleaning nanocoating technology is decomposing the traditional maintenance-contracting model for high-rise exterior facades. Premium residential developers in Ho Chi Minh City are specifying photocatalytic titanium dioxide topcoats on pilot towers, compressing the repainting cycle from five-year intervals to eight-to-ten year horizons and threatening aftermarket service revenue pools.
REACH-equivalent substance notification requirements are reshaping import registration pathways for European and Northeast Asian suppliers. Vietnam's Ministry of Construction is harmonizing QCVN standards with ASEAN mutual recognition frameworks, forcing reformulation disclosure that disadvantages smaller regional traders lacking toxicological dossier capabilities.
Developer-direct procurement is consolidating purchasing authority away from traditional distributor networks. Tier-one residential contractors in Hanoi are establishing captive specification desks that negotiate master service agreements with formulators, disintermediating the provincial distributor tier that historically controlled technical recommendation influence in northern provinces.
Vietnam Architectural Coatings Market Segmentation
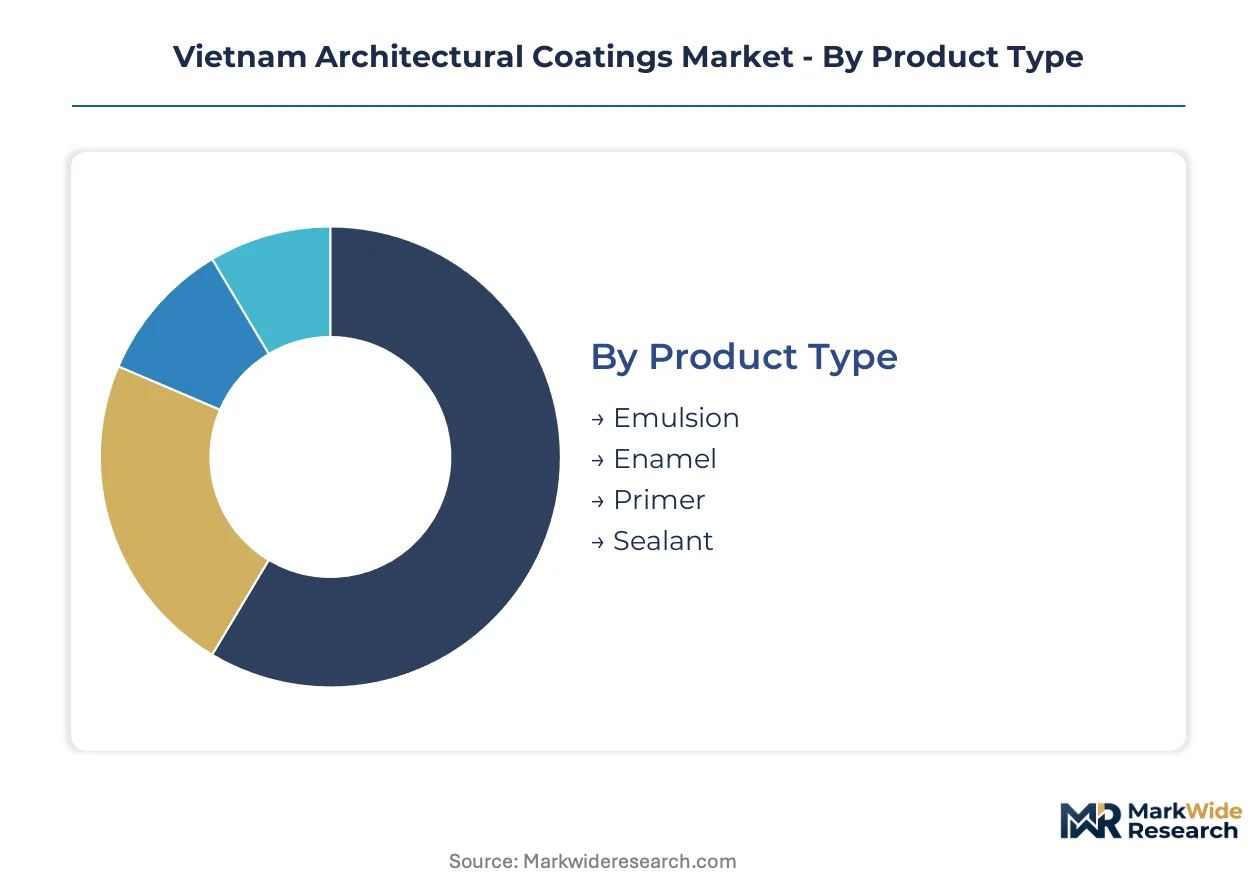
Architectural coatings in Vietnam fragment across formulation chemistry, substrate application, and contractor delivery methods. Each segmentation axis carries distinct margin profiles and regulatory exposure under QCVN standards. Understanding these divisions reveals where specification-grade value concentrates versus commodity volume.
Product Type:
Margin pools concentrate in specialized binders and performance-grade formulations that command specification premiums from tier-one developers.
- Emulsion:Water-based acrylic and vinyl acetate copolymer systems dominate interior volume with low-VOC compliance under QCVN 16:2019/BXD. Demand clusters in Hanoi high-rise residential where developer specifications mandate indoor air quality certification.
- Enamel:Solvent-based alkyd and polyurethane formulations retain margin concentration in exterior durability segments despite regulatory pressure. Alkyd enamel captures industrial maintenance specifications across Haiphong port infrastructure where salt-spray resistance overrides emission concerns.
- Primer:Penetrating sealer and blocking formulations serve substrate preparation across concrete and plaster applications.
- Sealant:Elastomeric and silicone-modified acrylic systems address expansion joint and crack-bridging requirements in tropical humidity cycles.
The dominant share belongs to Emulsion, while Sealant is closing the gap fastest through waterproofing specification upgrades in coastal provinces.
Application:
Volume distribution tracks urban construction intensity, with interior finishes absorbing the majority of new stock deployment across Red River Delta condominium towers.
- Interior Walls:Matte and low-sheen decorative finishes cover gypsum board, plaster, and concrete substrates in residential and commercial fit-outs. Ho Chi Minh City luxury developers are specifying anti-microbial and stain-resistant variants in master service agreements.
- Exterior Walls:Elastomeric, textured, and ceramic-reinforced systems protect against monsoon-driven hydrostatic pressure and UV degradation. Tropical humidity in Da Nang and Nha Trang is forcing silicone-modified acrylic upgrades beyond standard styrene-acrylic performance limits.
- Ceilings:Flat and acoustic-absorptive coatings address condensation resistance in climate-controlled commercial spaces.
- Floors:Epoxy and polyurethane screed systems serve industrial and commercial traffic-bearing applications.
Interior Walls commands the largest volume position, though Exterior Walls is expanding most quickly through facade upgrade cycles in aging urban stock.
Technology:
Regulatory trajectory favors waterborne chemistry, though solvent systems retain niche durability premiums in industrial exterior specifications.
- Water-Based:Acrylic, styrene-acrylic, and vinyl acetate emulsions capture regulatory tailwinds from QCVN VOC limits. Vietnam's Ministry of Construction enforcement timeline is accelerating formulator conversion investments ahead of ASEAN harmonization deadlines.
- Solvent-Based:Alkyd, polyurethane, and epoxy systems concentrate in marine-grade and high-durability industrial applications. Solventborne enamel retains specification lock-in for steel structure corrosion protection where waterborne technology has not matched performance.
- Powder Coating:Thermoset epoxy and polyester systems serve metal facade and architectural metalwork through electrostatic application.
- UV-Curable:Acrylate oligomer formulations occupy emerging position in wood coating and specialty substrate segments.
Water-Based holds the established volume lead, while Powder Coating is gaining share fastest through curtain wall fabricator integration in secondary cities.
Delivery Mode:
Application method selection tracks project scale and labor cost structure, with spray systems capturing efficiency premiums in large-format developments.
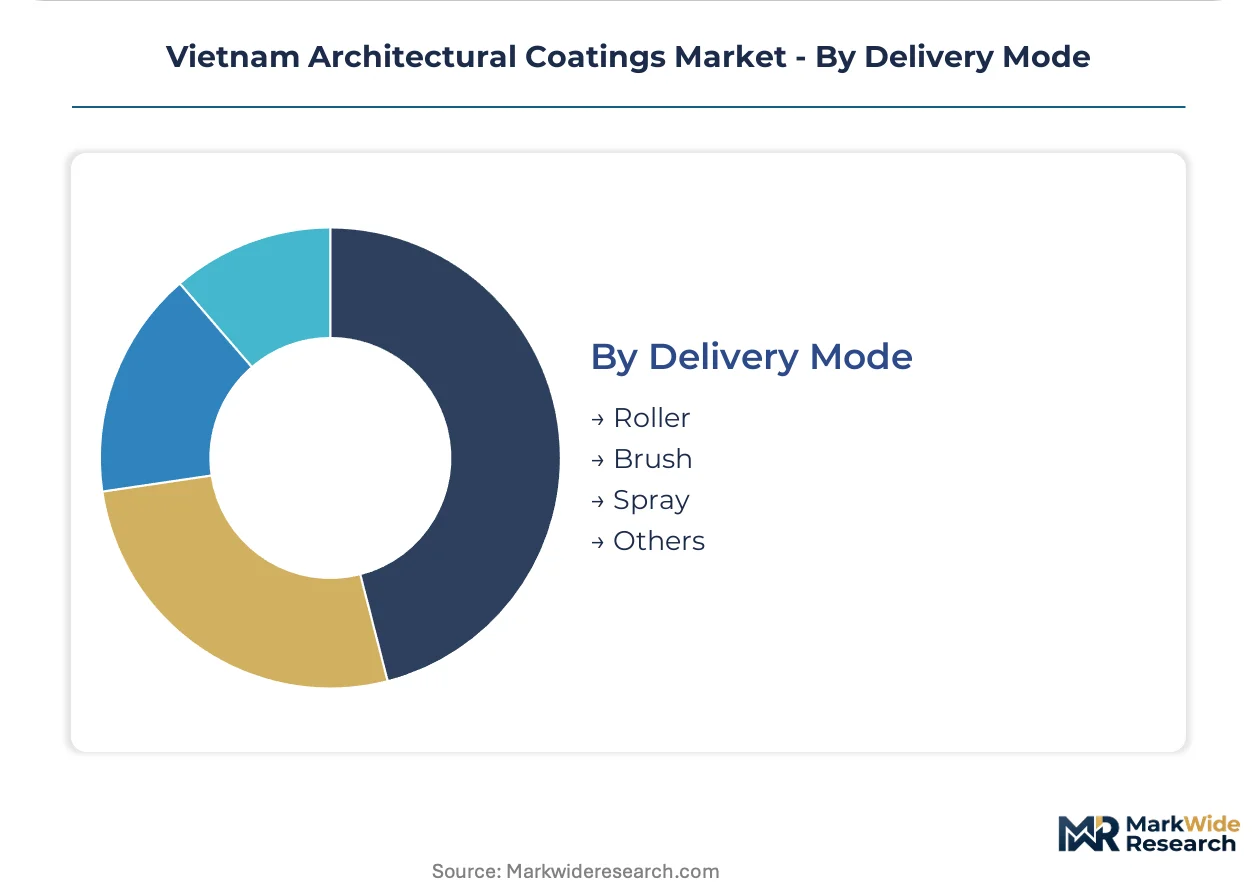
- Roller:Woven fabric and foam applicators dominate residential interior deployment for cost efficiency and finish control. Roller application retains contractor preference in Hanoi and Ho Chi Minh City renovation markets where masking complexity limits spray feasibility.
- Brush:Natural and synthetic bristle tools serve detail work, touch-up, and small-scale residential maintenance.
- Spray:Airless and HVLP systems deliver production speed across high-rise exterior and large commercial interiors. Spray equipment adoption is climbing fastest in Da Nang and Can Tho where developer-direct procurement is consolidating contractor scale.
- Others:Trowel, dip, and electrostatic methods serve specialty substrate and industrial coating applications.
Roller maintains the dominant application share, while Spray is expanding most quickly through mechanization investment in tier-one developer specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cai Mep-Thi Vai deepwater port complex underwrites southern Vietnam's coatings distribution capacity, connecting Ho Chi Minh City formulators to ASEAN transshipment networks and bulk resin import channels.
Ho Chi Minh City Metropolitan Area
Luxury condominium developers in District 2 and Thu Duc City are specifying photocatalytic self-cleaning exterior systems. Vietnam's Ministry of Construction enforces QCVN 16:2019/BXD emission limits that accelerate water-based formulation adoption. The Saigon Hi-Tech Park cluster is absorbing R&D investment from multinational suppliers establishing local technical service centers.
Hanoi and Red River Delta Corridor
High-rise residential towers in Cau Giay and Nam Tu Liem districts are driving specification-grade interior emulsion demand. Provincial People's Committees coordinate with the Ministry of Construction on green building pilot zones. Bac Ninh and Hai Duong industrial zones are hosting captive powder coating operations for electronics manufacturing facility construction.
Da Nang and Central Coast
Logistics warehouse developers in the Dien Nam-Dien Ngoc Industrial Zone are specifying epoxy floor screed systems. The city's Department of Construction aligns local building codes with national fire safety standards under Department of Fire Prevention and Fighting protocols. The Hoa Khanh Industrial Zone is emerging as a curtain wall fabrication hub driving adjacent powder coating demand.
Can Tho and Mekong Delta
Commercial retail construction in Ninh Kieu District is testing humidity-engineered acrylic systems beyond standard warranty periods. Provincial environmental departments enforce QCVN standards with delayed compliance timelines versus northern metros. The Tra Noc Industrial Zone is consolidating contractor scale through developer-direct procurement arrangements.
Hai Phong and Northern Port Corridor
Industrial maintenance specifications across Dinh Vu-Cat Hai Economic Zone are preserving solvent-based enamel demand for steel structure protection. The municipal People's Committee coordinates port infrastructure upgrades with national construction material standards. Cat Bi International Airport expansion is driving fire-retardant coating certification through extended Department of Fire Prevention and Fighting approval cycles.
Vietnam Architectural Coatings Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and distribution reach, producing a tiered structure where scale-driven multinationals anchor premium specifications while domestic family-owned groups control provincial retail networks. Three archetypes dominate: integrated domestic manufacturers with captive resin supply, technology-licensed regional subsidiaries of global majors, and specialty importers serving niche industrial maintenance segments. Competitive moves concentrate on backward integration into titanium dioxide procurement and master service agreement consolidation with tier-one developers.
Within the domestic integrated tier, KOVA Group and Dong Tam exemplify scale positions built on northern manufacturing footprints and provincial distribution density. Among technology-licensed multinationals, PPG Industries, Inc. and Jotun occupy specification leadership in low-VOC and marine-adapted exterior segments respectively. These named entities represent archetype anchors rather than exhaustive market coverage, with additional volume concentrating among Japanese and European majors with regional headquarters in Singapore.
| Leading Market Players |
|---|
| KOVA Group |
| PPG Industries, Inc. |
| Jotun |
| Dong Tam |
| Hoa Binh Paint |
| AkzoNobel N.V. |
| 4Oranges Co., Ltd. |
| Toa Vietnam |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Value Network & Pricing Analysis
QCVN 16:2019/BXD certification gates both supply qualification and price differentiation simultaneously, as formulators without compliant registrations face exclusion from specification-grade procurement while certified domestic producers command premiums in Hanoi high-rise residential tenders. This regulatory filter compresses margin visibility for import-dependent suppliers facing extended conformity assessment timelines, tilting procurement authority toward integrated manufacturers with captive testing facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with specification-grade emulsions commanding spreads based on VOC certification tier and master service agreement volume commitments. Price differentiation hinges on QCVN compliance status and developer-direct procurement scale, with tier-one residential contractors extracting volume discounts that compress distributor margins. Cost compression in mid-tier enamel segments is intensifying because titanium dioxide feedstock volatility erodes formulator pricing power. Small-scale retail buyers in provincial renovation markets exhibit highest price sensitivity, while luxury condominium developers in Ho Chi Minh City demonstrate lowest sensitivity due to specification-locked procurement protocols.
Supply Chain Analysis
Container availability constraints on Singapore and South Korea transshipment lanes elevate inbound logistics costs for specialty epoxy resin shipments serving marine-grade exterior formulations. Geographic supply concentration centers on China for titanium dioxide pigment, South Korea for epoxy resin intermediates, and Thailand for acrylic emulsion monomers. Raw material dependencies span sulfate-process TiO2, bisphenol-A epoxy precursors, and styrene-acrylic copolymers. Single-source vulnerability concentrates in specialty binder imports through regional port hubs. Distribution runs through provincial distributor networks in northern provinces and developer-direct master service agreements in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through developer-direct procurement consolidation, as tier-one residential contractors in Hanoi and Ho Chi Minh City disintermediate traditional distributor networks via captive specification desks.
For Market Incumbents: Shield specification-grade positioning by accelerating QCVN compliance registration for pending ASEAN harmonization deadlines, while securing backward integration into titanium dioxide procurement through long-term offtake contracts with Chinese sulfate-process suppliers. Threat exposure concentrates in water-based emulsion technology displacement of solvent-borne enamel volume and emerging domestic formulators with provincial manufacturing footprints. For New Entrants and Emerging Players: QCVN fast-track registration for low-VOC interior emulsions opens specification entry points in Da Nang and Can Tho secondary cities where developer-direct procurement is consolidating contractor scale. White-space targets include humidity-engineered exterior systems for Mekong Delta coastal provinces and powder coating partnerships with curtain wall fabricators in Central Highlands logistics facilities. Go-to-market execution should anchor on technical service partnerships with aging contractor networks lacking application specification expertise. For Investors and Strategic Acquirers: Pending amendments to Vietnam Green Building Council certification criteria reshape the acquisition landscape by positioning early QCVN-compliant registrants for preferred vendor status in green building pilot zones. Long-term viability favors domestic integrated manufacturers with northern manufacturing footprints and captive R&D facilities over import-dependent regional traders lacking toxicological dossier capabilities. Monitor Department of Fire Prevention and Fighting approval timeline compression for intumescent coating variants as inflection indicator for regulatory compliance capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Procurement | Captive supply of sulfate-process pigment insulates margin visibility from global feedstock volatility. |
| QCVN Certification Fast-Track Investment | Early registration under ASEAN harmonization deadlines secures preferred vendor status in green building zones. |
| Master Service Agreement Consolidation | Direct procurement relationships with tier-one developers disintermediate provincial distributor networks. |
| Humidity-Engineered Exterior Formulation Development | Silicone-modified acrylic systems address Mekong Delta performance limits beyond standard warranties. |
| Powder Coating Technology Partnership | Electrostatic application integration with curtain wall fabricators captures adjacent metalwork demand. |
Research Methodology
Cross-validation between Ministry of Construction regulatory filings and provincial construction permit databases anchors the qualitative findings on specification-grade demand concentration. Primary interviews with plant managers at domestic formulators, procurement leads at tier-one residential developers, distribution channel partners in northern provinces, and technical R&D directors at multinational subsidiaries combined with secondary validation from customs/trade data, QCVN standard documentation, and Department of Fire Prevention and Fighting certification records. Bottom-up project pipeline analysis and top-down construction expenditure triangulation frame volume estimates.
Sensitivity analysis around titanium dioxide price volatility scenarios and ASEAN harmonization timeline assumptions tests forecast robustness across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, substrate application category, technology type, delivery mode, and regional construction cluster. CAGRs derive from construction completion forecasts and coating intensity coefficients applied to residential and commercial floor space additions. Industry-specific inputs incorporate monsoon durability performance degradation curves and green building certification adoption rates.
Underlying assumptions cover QCVN enforcement consistency, construction permit issuance continuity, and resin import channel stability, with deviation risk concentrated in regulatory amendment timing and regional port congestion recurrence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Fire Retardant Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Hydrophilic Coatings Market
Coatings
Rail Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Zero Friction Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Mold Release Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Canada Industrial Wood Coatings Market