
 Global Fluorinated Ethylene Propylene (FEP) Coatings Market | 2026-2036
Global Fluorinated Ethylene Propylene (FEP) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluorinated Ethylene Propylene (FEP) Coatings Market Foresight
Chemical processing plants is restructuring the largest demand channel for FEP coatings as petrochemical operators replace traditional linings with fluoropolymer alternatives. Daikin Industries leverages captive resin production to control raw material quality across Asian supply chains. The Chemours Company sustains technology leadership in high-purity grades for semiconductor fabrication equipment. Saint-Gobain Performance Plastics dominates European architectural panel applications through specialized powder formulations.
Fluorinated ethylene propylene coatings consist of a fully fluorinated copolymer of tetrafluoroethylene and hexafluoropropylene, typically applied at film thicknesses of 25-100 microns to deliver continuous service temperatures up to 200°C with exceptional dielectric strength exceeding 2,000 V/mil. Their primary purpose is to provide non-stick, chemically inert, and electrically insulating barriers for industrial substrates exposed to aggressive media. Powder coating deployment forms command premium positioning due to zero-VOC compliance and superior edge coverage in complex geometries. Wire insulation applications anchor volume consumption as electric vehicle motor windings require thinner, thermally stable dielectric layers. Electronics manufacturing end users represent the fastest-expanding margin pool as miniaturization trends demand precision-applied FEP films.
REACH in Europe and EPA regulations in the United States restrict perfluorinated substance emissions, compelling reformulation investments and third-party certification costs that filter into pricing structures. China's MEE enforces dual carbon goals that elevate energy-efficiency standards for coating cure processes, favoring electrostatic application methods with reduced thermal input. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent compliance timelines.
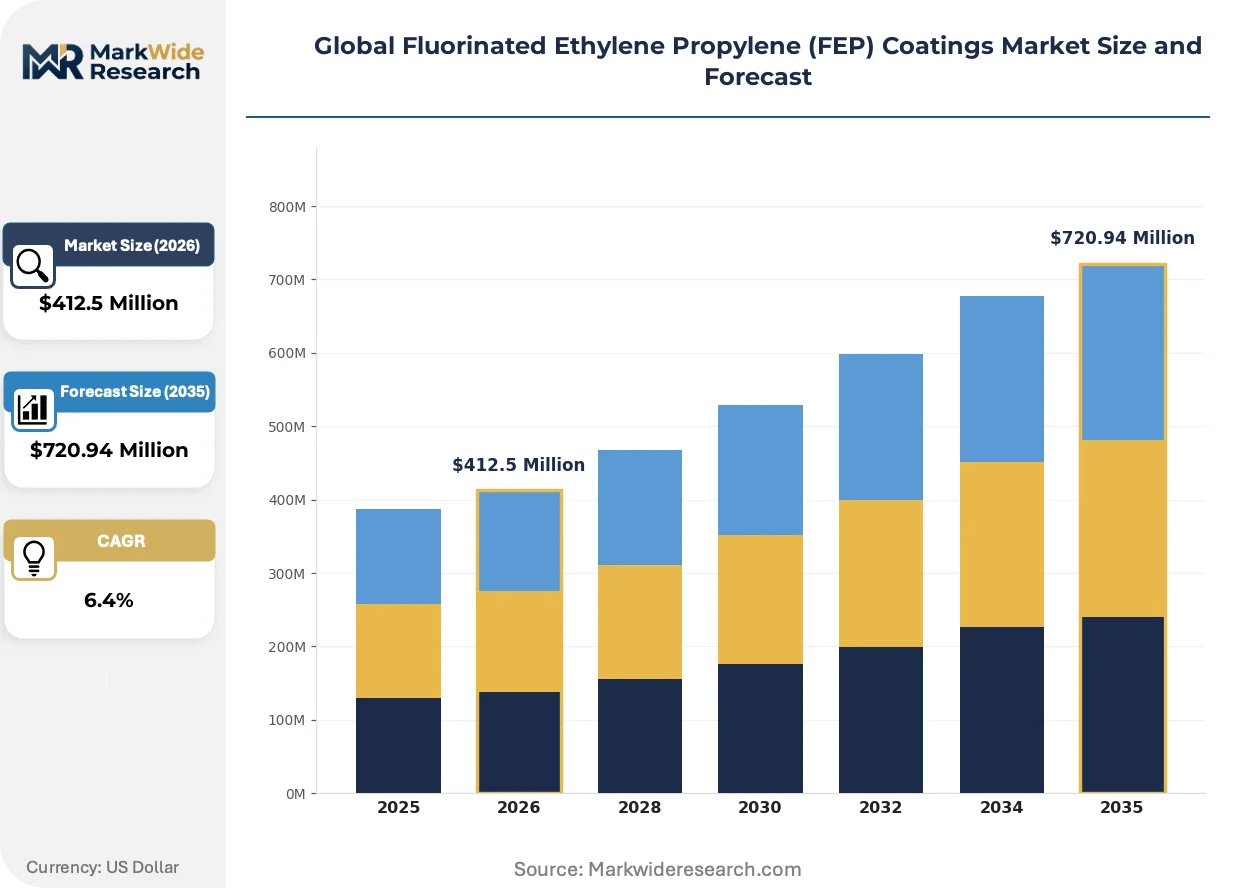
Market Dynamics
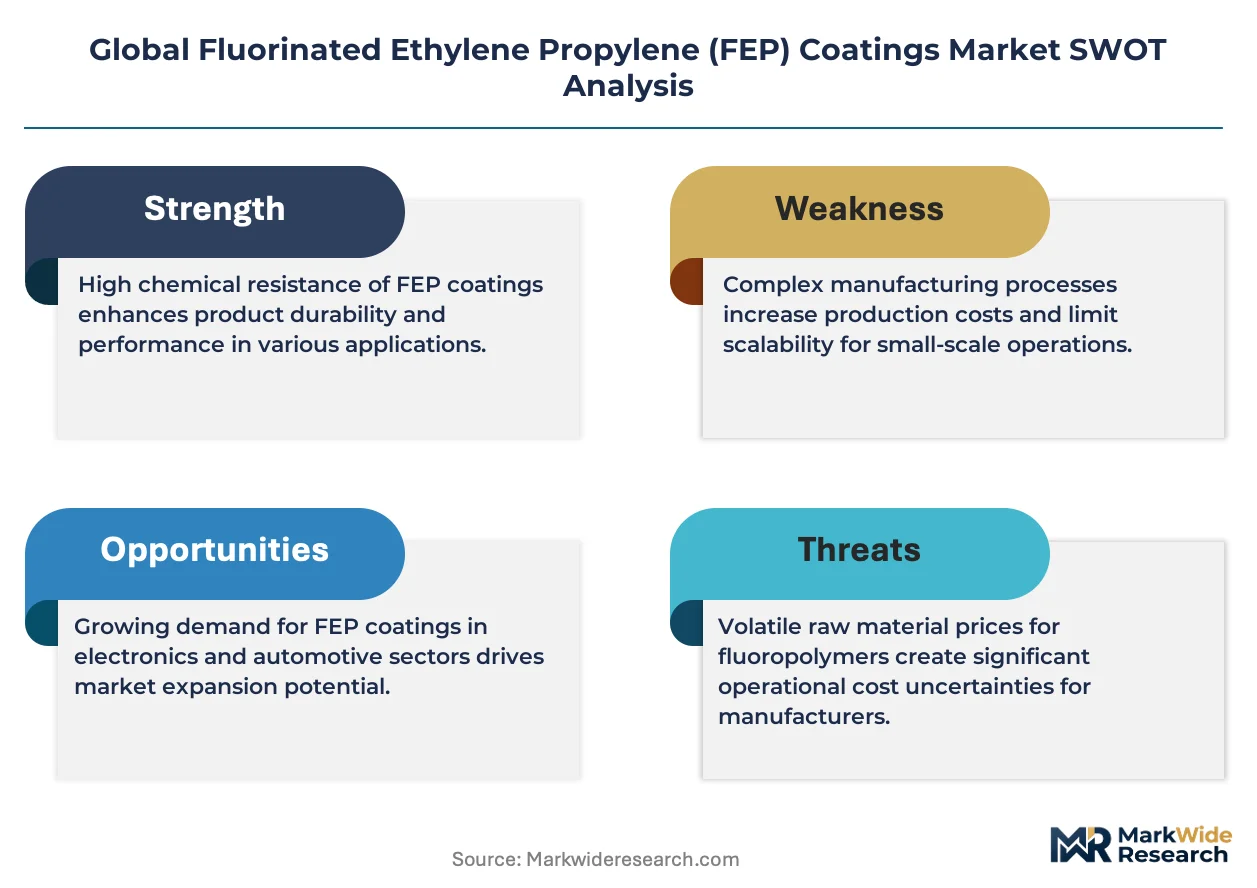
Semiconductor fabrication capacity expansion in East Asia is concentrating demand for high-purity FEP coatings, while REACH and RoHS compliance in Europe forces simultaneous reformulation across legacy product lines.
Growth Catalysts
- Semiconductor equipment demand:Domestic wafer fabrication expansion in China drives consumption of ultra-high-purity FEP films for chamber linings and gas delivery systems.
- REACH substance restrictions:European legacy coating substitution accelerates as ECHA evaluations phase out chromate-based alternatives in chemical processing environments.
- Electric vehicle motor windings:Thinner dielectric layer requirements for high-frequency inverter-fed motors elevate FEP wire insulation specifications across automotive supplier networks.
Market Restraints
- Fluoropolymer resin concentration:Captive production by integrated resin-coating manufacturers limits third-party coating compounders' supply security and pricing leverage.
- Perfluorinated substance scrutiny:EPA emission controls and state-level PFAS restrictions in the US impose capital-intensive abatement equipment on coating cure operations.
- ETFE substitution in architectural panels:Ethylene tetrafluoroethylene films displace FEP powder coatings in certain building cladding applications due to superior mechanical durability.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO-compliant coating demand for reactor vessels and piping remains underpenetrated as domestic API production scales under PLI incentives.
- Solar panel backsheet integration:FEP film lamination for photovoltaic module edge sealing represents an emerging application with distinct thermal cycling requirements.
- Electrostatic powder convergence:Combination with UV-cure primers enables lower-temperature application onto temperature-sensitive polymer substrates.
Industry Challenges
- Fluoropolymer application technician scarcity:Specialized spray and powder coating expertise for thin-film FEP deposition remains concentrated among aging workforce cohorts in mature markets.
- Dual certification timelines:Simultaneous REACH registration and FDA food-contact approval for food processing equipment coatings extends commercialization cycles by 18-24 months.
- Legacy PTFE system integration:Retrofitting FEP coatings onto existing polytetrafluoroethylene-lined vessels requires surface preparation protocols that compromise substrate adhesion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluorinated Ethylene Propylene (FEP) Coatings Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoropolymer, Perfluorinated, Copolymer, Homopolymer, Thermoplastic Application: Wire Insulation, Chemical Processing, Automotive Components, Electronics, Architectural Panels End User Industry: Electronics Manufacturing, Chemical Processing Plants, Transportation Equipment, Construction Firms, Aerospace Suppliers Deployment Form: Powder Coating, Liquid Coating, Spray Coating, Dip Coating, Electrostatic Application |
| Companies Covered | DAIKIN INDUSTRIES, Ltd, The Chemours Company, 3M, AGC Inc, AFT Fluorotec Limited, Saint-Gobain Performance Plastics, DuPont, HaloPolymer Trading Inc, INOFLON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluorinated Ethylene Propylene (FEP) Coatings Market Shifts & Advancements
Coating application technology and regulatory chemistry are converging to redefine performance benchmarks and compliance pathways across industrial end-uses.
Hybrid electrostatic-thermal spray deposition is unifying powder and liquid FEP application into single-pass systems. Semiconductor OEMs in Taiwan and South Korea are piloting these integrated lines for chamber component refurbishment. The technology is compressing capital requirements for high-purity coating operations while narrowing the performance gap between application methods.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon propellants in solvent-based FEP dispersion coatings. Coating formulators in Germany and France are accelerating water-based carrier development for architectural and industrial applications. Wire insulation manufacturers face the steepest reformulation costs due to film thickness uniformity requirements.
Specification-driven procurement now dominates chemical processing and pharmaceutical equipment purchasing. Engineering contractors in the US Gulf Coast and Rotterdam-Antwerp cluster bundle coating selection with vessel fabrication contracts, displacing aftermarket application decisions. This consolidation concentrates volume with coating applicators holding OEM-approved status and third-party inspection credentials.
Global Fluorinated Ethylene Propylene (FEP) Coatings Market Segmentation
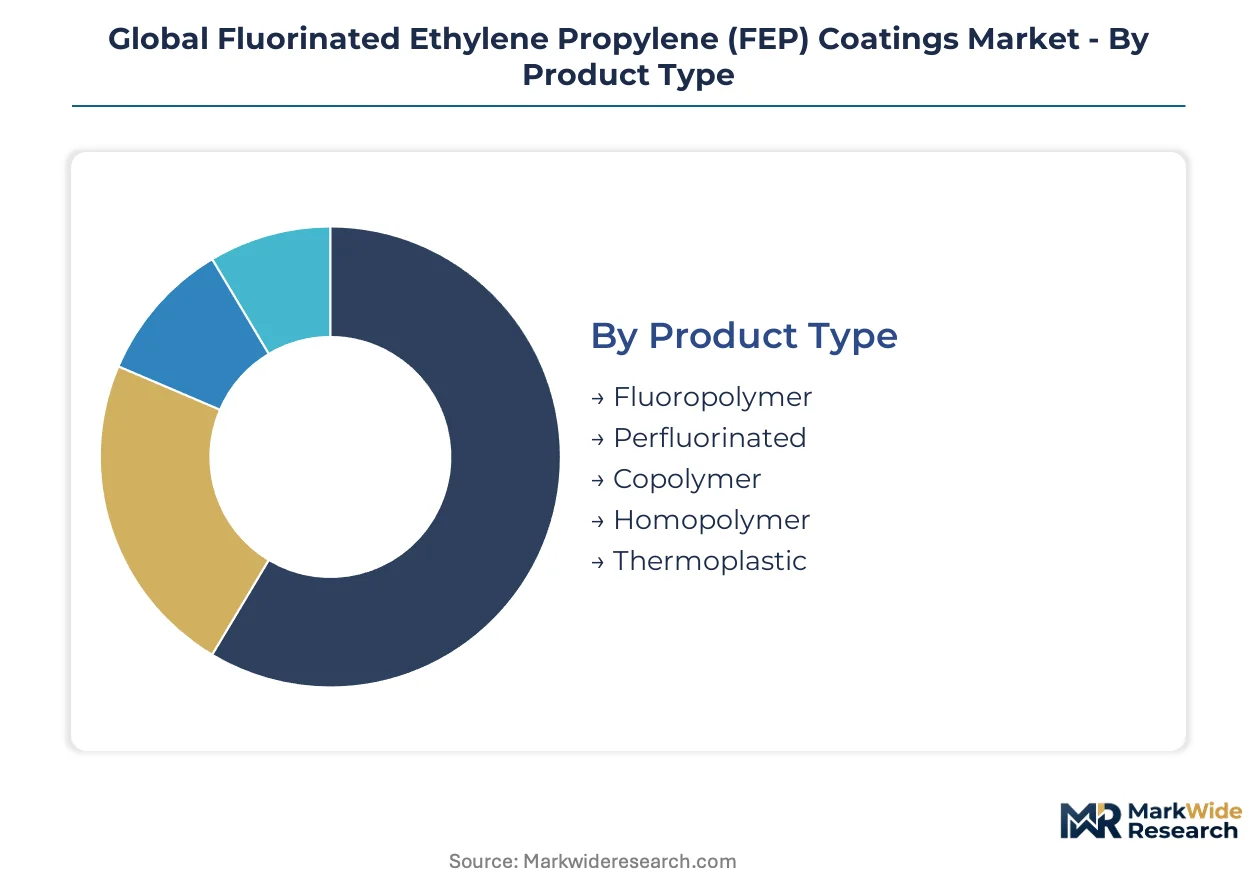
FEP coatings segment across multiple technical and commercial dimensions. Each axis reveals distinct upgrade cycles, from resin chemistry reformulation to application method modernization.
Product Type:
Equipment replacement cycles favor fluoropolymer grades with superior thermal stability and chemical resistance.
- Fluoropolymer:The foundational resin class delivers continuous service temperatures to 200°C and dielectric strength exceeding 2,000 V/mil. Semiconductor fabrication equipment in Taiwan and South Korea drives specification tightening for chamber lining applications.
- Perfluorinated:Fully fluorinated backbone structures provide maximum chemical inertness against aggressive acids and oxidizers. Chemical processing operators on the US Gulf Coast specify these grades for reactor vessel refurbishment cycles.
- Copolymer:Tetrafluoroethylene-hexafluoropropylene compositions balance processability with performance.
- Homopolymer:Single-monomer structures offer distinct rheological properties for specific coating methods.
- Thermoplastic:Melt-processable variants enable injection molding integration with coating operations.
Volume placements concentrate in Fluoropolymer; the faster expansion belongs to Perfluorinated.
Application:
End-use diversification spreads across electrical, chemical, and structural domains with varying specification intensity.
- Wire Insulation:Thin-film dielectric layers for high-frequency motor windings. Electric vehicle powertrain manufacturers in Germany and Japan specify 25-50 micron coatings for inverter-fed traction motors.
- Chemical Processing:Vessel linings and piping protection against corrosive process streams. Petrochemical complexes in Rotterdam-Antwerp and Singapore prioritize FEP over legacy PTFE for reduced permeation.
- Automotive Components:Fuel system and sensor protection applications.
- Electronics:Precision coating of connectors and semiconductor handling equipment.
- Architectural Panels:Weather-resistant cladding and facade systems.
Wire Insulation commands the largest volume position; Electronics climbs the fastest on miniaturization requirements.
End User Industry:
Customer concentration patterns reflect capital investment cycles and regulatory compliance burdens.
- Electronics Manufacturing:Wafer fabrication and assembly operations demand ultra-high-purity coating protocols. Domestic capacity expansion in China concentrates procurement with qualified applicators holding SMIC and Hua Hong certifications.
- Chemical Processing Plants:Petrochemical and specialty chemical operators replace linings on 7-10 year cycles. REACH substance restrictions in Europe accelerate chromate-based system phase-outs.
- Transportation Equipment:Automotive and rail applications emphasize thermal cycling durability.
- Construction Firms:Building envelope and infrastructure projects specify weathering resistance.
- Aerospace Suppliers:Commercial aviation and defense contractors impose stringent outgassing and flammability standards.
Chemical Processing Plants anchor current volume; Electronics Manufacturing gains share fastest on capacity buildouts.
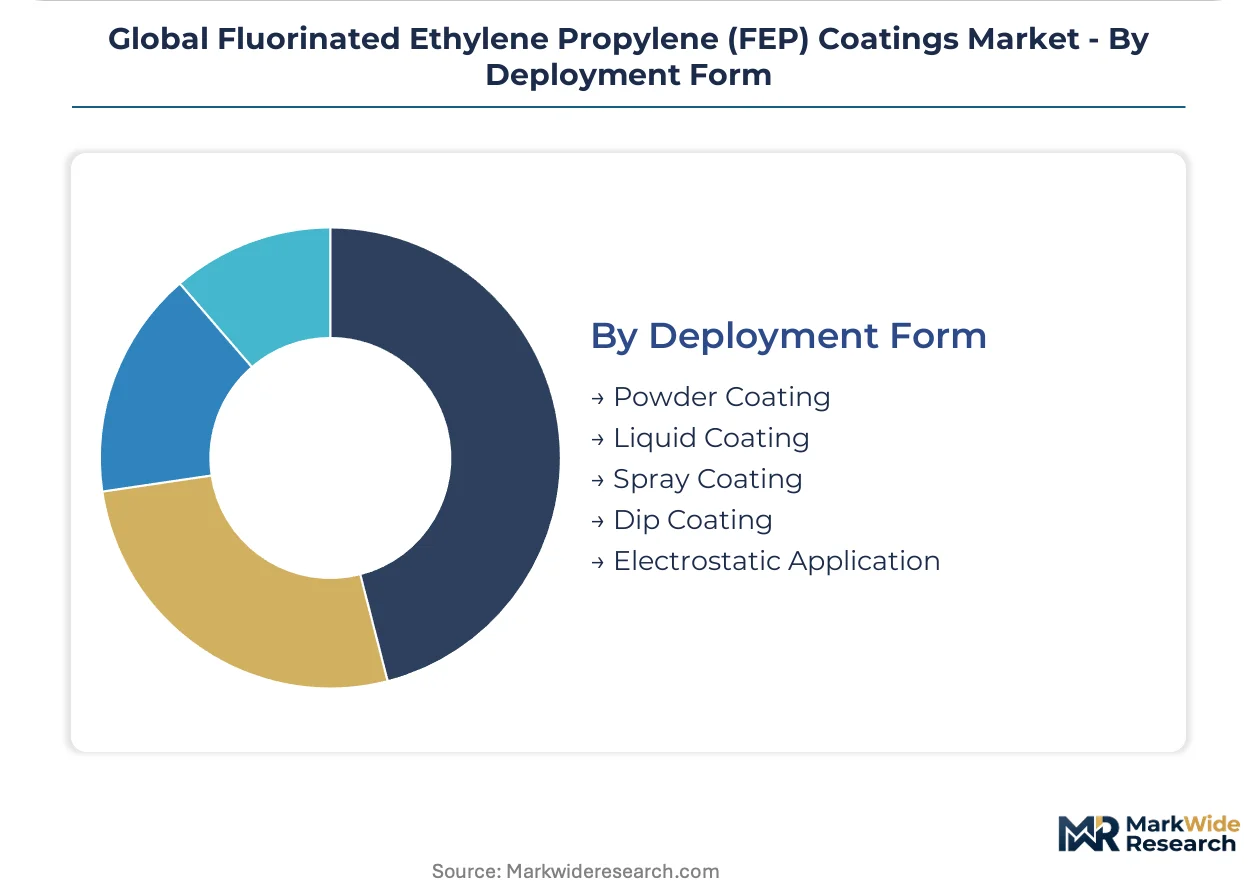
Deployment Form:
Application technology selection governs capital requirements, environmental compliance, and substrate compatibility.
- Powder Coating:Zero-VOC compliance and superior edge coverage for complex geometries. European architectural panel fabricators favor electrostatic powder methods under EU F-Gas Regulation constraints on solvent carriers.
- Liquid Coating:Dispersion-based systems enable thin-film precision for electronics. Water-based carrier development in Germany and France responds to propellant phase-down schedules.
- Spray Coating:Conventional air and airless methods for field application.
- Dip Coating:Immersion methods for uniform coverage of intricate shapes.
- Electrostatic Application:Charged particle deposition improves transfer efficiency and film uniformity.
Powder Coating dominates volume placements; Electrostatic Application expands most quickly on efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated industrial zones and chemical processing corridors concentrate FEP coatings procurement. Wafer fabrication clusters, petrochemical complexes, and automotive supplier networks anchor demand geography.
United States
Gulf Coast petrochemical complexes and semiconductor fabrication facilities in Arizona and Texas drive specification intensity. EPA emission controls on perfluorinated substances impose capital-intensive abatement requirements on coating cure operations. Houston and Corpus Christi anchor chemical processing vessel refurbishment cycles with OEM-approved applicator networks.
China
Domestic wafer fabrication expansion by SMIC and Hua Hong concentrates ultra-high-purity FEP film procurement. MEE dual carbon goals elevate energy-efficiency standards for coating cure processes, favoring electrostatic application methods. Yangtze River Delta fabrication clusters in Shanghai and Wuxi qualify specialized applicators for chamber lining contracts.
Germany
Electric vehicle powertrain manufacturers specify thin-film FEP wire insulation for inverter-fed traction motors. EU F-Gas Regulation phase-down schedules restrict hydrofluorocarbon propellants in solvent-based dispersion coatings. Industrial corridors in Bavaria and Baden-Württemberg host automotive supplier networks accelerating coating specification upgrades.
Japan
Precision electronics and semiconductor equipment manufacturers demand miniaturization-compatible coating protocols. METI industrial standards govern fluoropolymer emissions and workplace exposure limits. Kyushu fabrication clusters and Nagoya automotive supplier networks concentrate qualified applicator expertise for thin-film deposition.
South Korea
Memory and logic chip fabrication expansion by Samsung and SK Hynix concentrates chamber lining refurbishment demand. MFDS pharmaceutical equipment standards intersect with semiconductor purity requirements for dual-use coating applicators. Pyeongtaek and Yongin fabrication complexes qualify domestic applicators for high-purity FEP film contracts.
Global Fluorinated Ethylene Propylene (FEP) Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Integrated resin-coating manufacturers with captive fluoropolymer production command supply security advantages over third-party compounders. Three archetypes dominate: upstream-integrated resin producers, specialized coating applicators with OEM approvals, and diversified materials conglomerates with architectural panel focus. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure qualified applicator networks.
Among integrated manufacturers, Daikin Industries leverages captive resin production to control raw material quality across Asian supply chains. The Chemours Company occupies a position in high-purity grades for semiconductor fabrication equipment. Saint-Gobain Performance Plastics anchors European architectural panel applications through specialized powder formulations.
| Leading Market Players |
|---|
| DAIKIN INDUSTRIES, Ltd |
| The Chemours Company |
| 3M |
| AGC Inc |
| AFT Fluorotec Limited |
| Saint-Gobain Performance Plastics |
| DuPont |
| HaloPolymer Trading Inc |
| INOFLON |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap coating compounders in Japan and Germany anchor supply discipline through conservative balance sheet management and selective capacity commitments. Their financing patterns limit aggressive price competition while reinforcing long-term contract preferences with semiconductor OEMs and chemical processors.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as wafer fabrication chamber refurbishment cycles compress turnaround windows. Three-tier pricing structure across semiconductor-grade, industrial-grade, and architectural-grade tiers reflects certification intensity and purity testing overhead. Pricing pressure stems from ETFE substitution in building cladding applications where mechanical durability requirements exceed FEP performance envelopes. Chemical processing operators exhibit highest price sensitivity due to cyclical capital expenditure constraints, while semiconductor OEMs accept premium positioning for qualified applicator networks.
Supply Chain Analysis
Freight cost volatility from fluoropolymer resin production centers in Japan, China, and the United States elevates landed cost uncertainty for European compounders. Raw material sourcing draws from tetrafluoroethylene monomer supply anchored in Gulf Coast petrochemical complexes and Asian fluorochemical manufacturing zones. Single-source vulnerability concentrates in high-purity resin grades where Daikin Industries and Chemours maintain captive production. Distribution runs through OEM-approved applicator networks rather than commodity chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FEP coatings market sits in a technology-transition phase as hybrid electrostatic-thermal spray deposition displaces conventional single-method application lines. Semiconductor OEMs in Taiwan and South Korea pilot integrated systems that compress capital requirements while narrowing performance gaps between powder and liquid coating methods.
For Market Incumbents: Deepen captive resin production control to secure supply continuity as REACH substance restrictions accelerate legacy coating substitution. Expand qualified applicator certification programs in Yangtze River Delta fabrication clusters to defend positioning against emerging Chinese compounders. Prioritize FDA food-contact approval investments alongside semiconductor-grade qualifications to capture dual-use equipment demand. For New Entrants and Emerging Players: Begin with CDSCO-compliant pharmaceutical vessel coating applications in India where domestic API production scaling under PLI incentives concentrates underpenetrated demand. Target solar panel backsheet edge sealing as a specification-light entry point with distinct thermal cycling requirements. Pursue electrostatic-UV hybrid application partnerships to differentiate on temperature-sensitive substrate compatibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized coating applicators with OEM-approved status in South Korea and Japan where memory chip fabrication expansion concentrates chamber lining refurbishment demand. Long-term viability rests on qualification moats rather than commodity resin access. Monitor EU F-Gas Regulation phase-down enforcement as inflection indicator for water-based formulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive tetrafluoroethylene supply secures quality control across Asian fabrication clusters. |
| Hybrid Application Technology Deployment | Electrostatic-thermal spray convergence compresses capital requirements for high-purity coating operations. |
| Water-Based Formulation Development | German and French compounders respond to EU F-Gas Regulation propellant phase-down schedules. |
| OEM-Approved Applicator Network Expansion | Qualification credentials concentrate procurement with certified coating operations in Rotterdam-Antwerp corridor. |
| Dual Certification Investment | Simultaneous REACH registration and FDA approval extends commercialization cycles but captures food processing equipment demand. |
Research Methodology
Document review covered fluoropolymer producer technical literature, ECHA substance evaluation reports, and semiconductor equipment OEM procurement specifications, complemented by interviews with coating applicator technical directors, chemical processing plant maintenance managers, and pharmaceutical manufacturing engineering leads. Secondary validation drew from SEC 10-K filings of integrated resin-coating manufacturers, customs trade data on fluoropolymer resin shipments, and MEE dual carbon policy implementation guidance. Bottom-up demand modeling triangulated against top-down market sizing from industrial coatings trade associations.
Cross-referencing historical application technology adoption curves with expert panel input on electrostatic powder convergence timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product purity grade, deployment form, end-use industry vertical, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and capacity expansion announcements rather than extrapolated trend lines. Forecast inputs incorporated wafer fabrication equipment spend patterns and electric vehicle motor winding specification shifts.
Underlying measurement precision varies by segment; semiconductor-grade and pharmaceutical-grade coatings carry tighter precision than architectural applications due to qualification documentation density. Forecasts reflect documented assumptions on regulatory compliance timelines and substitution elasticity parameters. Stakeholders should weight assumptions against their own operating context and regional enforcement variation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Consumer Appliance Coatings Market
Coatings
US Protective Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Graphene Coatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Canada Floor Coatings Market
Coatings
UV Coatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Insulation Coating Market