
 Wood Preservative Coatings Market | 2026-2036
Wood Preservative Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Preservative Coatings Market Outlook
North American capacity expansion is rewriting supply dynamics for wood preservative coatings. Lonza leverages its integrated biocide manufacturing to sustain cost advantages across copper-based treatments. BASF SE anchors European supply through specialized acrylate resin production for exterior wood applications.
Wood preservative coatings are protective formulations containing biocides, resins, and solvents designed to inhibit fungal decay, insect infestation, and moisture-induced degradation in timber substrates, typically applied at dry-film thicknesses of 75–150 microns for exterior exposures. Their primary purpose is extending service life of structural lumber, decking, and joinery in high-decay hazard environments. Waterborne formulations now lead volume growth as contractors face tightened VOC limits, while solvent-based alkyd systems retain margin concentration in industrial pole and piling treatments. Epoxy-based preservatives represent the fastest-expanding chemistry segment for below-ground and marine applications where dimensional stability demands are most severe.
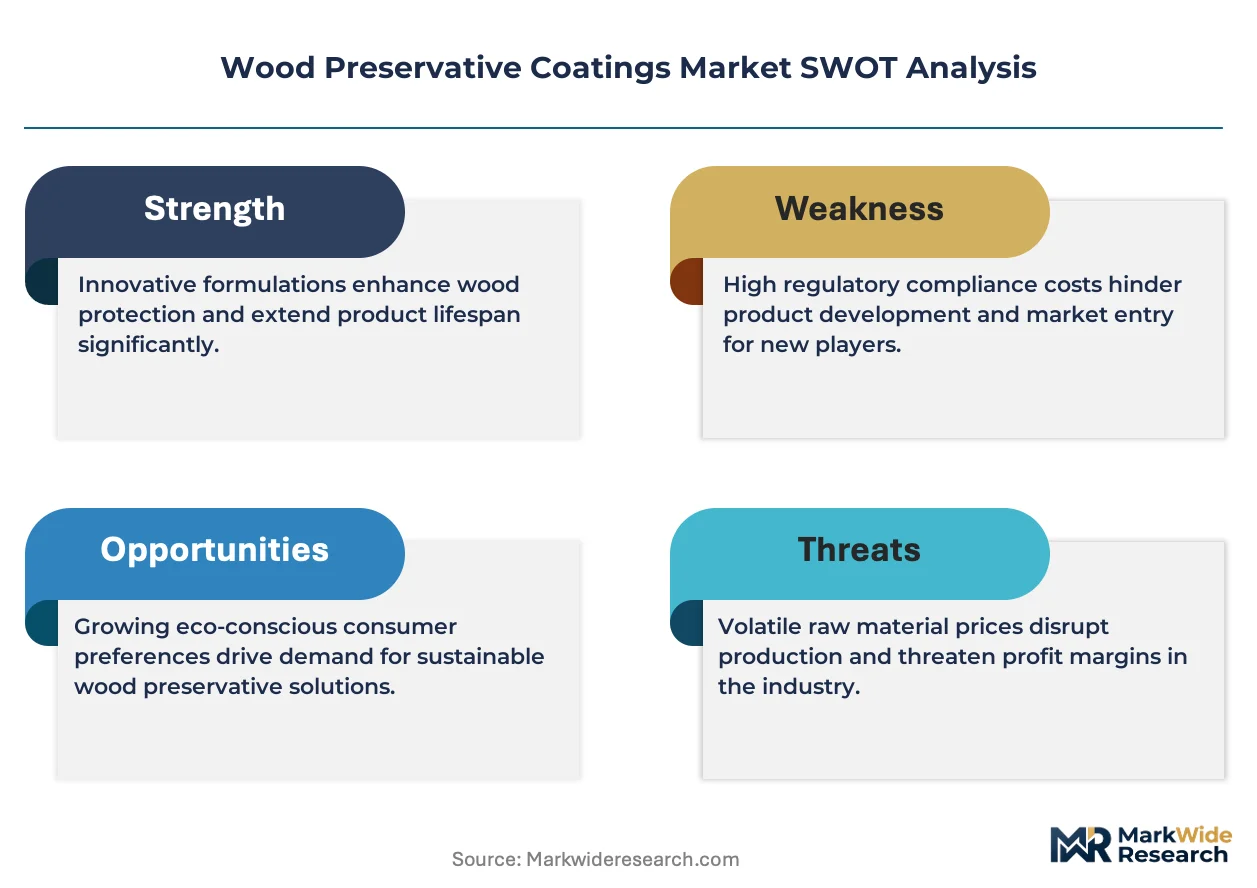
EPA registration requirements under FIFRA govern biocide efficacy claims and label restrictions for all products entering US commerce, while REACH compliance in Europe mandates full substance toxicity dossiers that filter out legacy chemistries. The EU Green Deal's chemical sustainability targets are accelerating substitution of chromated copper arsenate in remaining industrial applications. Stakeholders must monitor regulatory divergence between jurisdictions when configuring product portfolios and manufacturing footprints.
Market Dynamics
Waterborne formulation conversion is compressing solvent-based capacity while REACH and EPA VOC limits force simultaneous R&D and manufacturing retooling across the value chain.
Growth Catalysts
- Residential exterior renovation intensity:Deck and fencing replacement cycles in the United States Southeast and Pacific Northwest are pulling preservative volumes as homeowners extend outdoor living infrastructure lifespans.
- REACH Annex XVII restrictions:European chromated copper arsenate phase-outs are redirecting industrial pole and piling specifications toward copper azole and micronized copper alternatives.
- Marine infrastructure rehabilitation:Below-ground timber in coastal zones requires epoxy-based dimensional stabilization, opening specification opportunities for high-performance chemistries.
Market Restraints
- Copper and biocide feedstock volatility:Lonza's integrated position notwithstanding, merchant buyers face cost pressure from concentrated South American copper sourcing and specialty biocide intermediate tightness.
- Solvent-based alkyd stranded asset risk:Industrial pole treatment facilities in the US Midwest carry legacy equipment depreciation exposure as waterborne conversion accelerates.
- Cross-jurisdictional registration burden:FIFRA efficacy dossier requirements and REACH toxicity data demands create parallel compliance costs without mutual recognition.
Strategic Opportunities
- EU Green Deal chemical sustainability targets:Accelerating CCA substitution timelines create first-mover positioning for copper-free preservative platforms in remaining industrial applications.
- Direct-to-contractor digital channels:Professional applicator procurement is fragmenting away from traditional distributor networks toward specialized e-procurement platforms.
- Hybrid waterborne-epoxy convergence:Combining ambient cure convenience with below-ground performance opens specification in utility pole and marine piling segments previously reserved for solvent systems.
Industry Challenges
- Formulation chemist scarcity:Biocide-resin compatibility expertise sits concentrated with retiring specialists, constraining new product development velocity.
- EPA registration timeline compression:FIFRA label amendment cycles extend 18-24 months, delaying reformulation responses to regulatory changes.
- Legacy equipment integration friction:Waterborne conversion requires spray system corrosion resistance upgrades and drying capacity expansion at contractor applicator level.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Preservative Coatings Market |
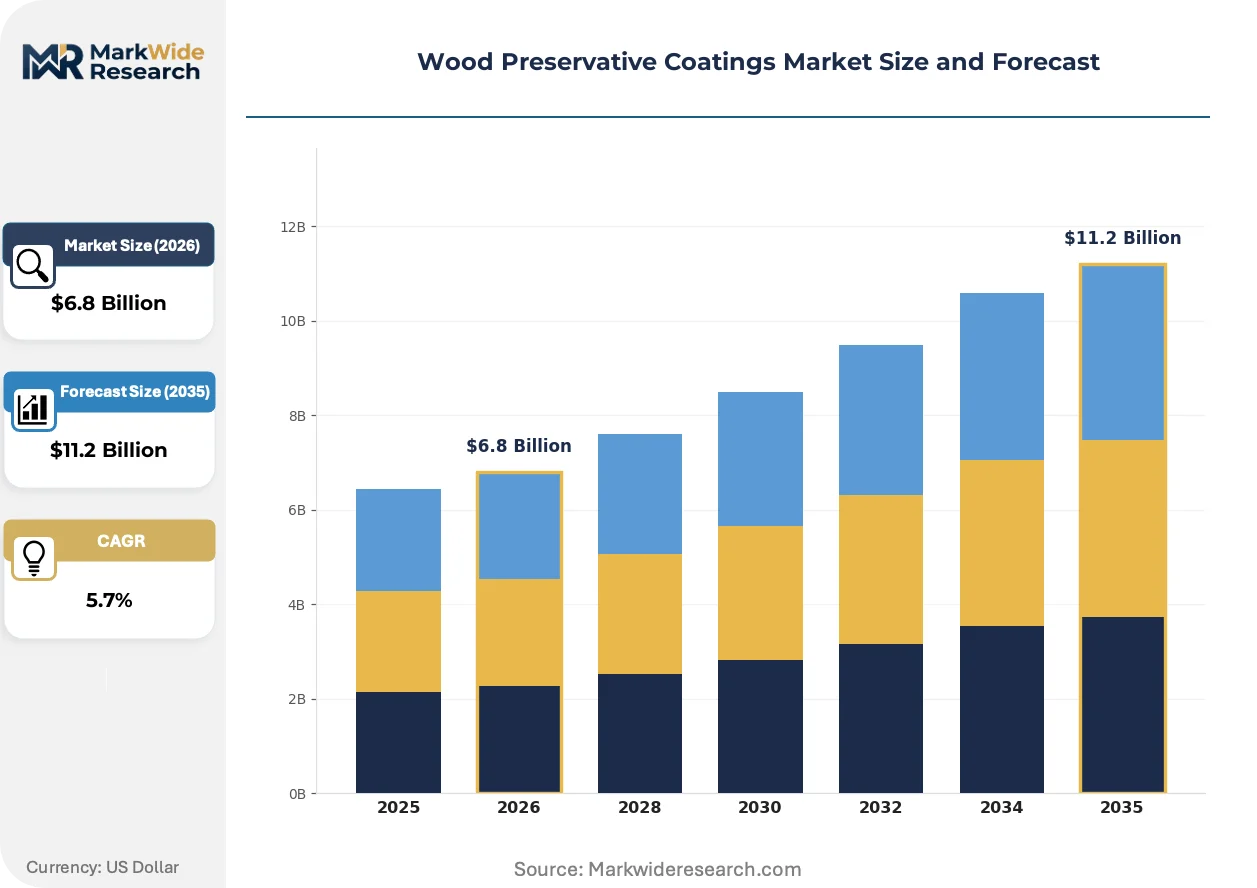
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solvent-Based, Oil-Based, Powder Coatings Application: Residential, Commercial, Industrial, Agricultural Chemical Composition: Alkyds, Acrylates, Epoxies, Phenolics End User: Contractors, DIY Enthusiasts, Furniture Manufacturers, Builders |
| Companies Covered | Lonza, BASF SE, Koppers Performance Chemicals, PPG Industries Inc., The Sherwin-Williams Company, LANXESS, Viance, Akzo Nobel N.V., Arxada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Preservative Coatings Market Strategic Shifts
Formulation chemistry is bifurcating between commodity waterborne conversion and premium epoxy hybridization, while regulatory divergence between EPA and ECHA frameworks forces parallel product line maintenance.
Hybrid waterborne-epoxy preservative systems are hybridizing performance characteristics previously split between ambient-cure convenience and below-ground dimensional stability. Marine piling contractors and utility pole specifiers are piloting these platforms for severe decay hazard zones. The technology is hybridizing what were separate product categories into unified specification options, compressing SKU proliferation while raising performance baselines.
ECHA REACH authorization procedures are tightening biocide substance sunset dates, forcing active ingredient substitution cycles faster than historical reformulation patterns. European manufacturers must maintain dual inventory positions during transition windows. Industrial pole treatment facilities in Germany and Scandinavia face the most compressed compliance timelines as copper-based alternatives require new application equipment.
Professional contractor purchasing is consolidating toward integrated coating-system suppliers who bundle preservatives with application equipment and technical service. Independent distributors are losing specification influence to manufacturer-direct field technical support. This pattern is most visible in the United States Pacific Northwest, where large deck contractors negotiate annual volume agreements bypassing traditional two-step distribution.
Wood Preservative Coatings Market Segmentation
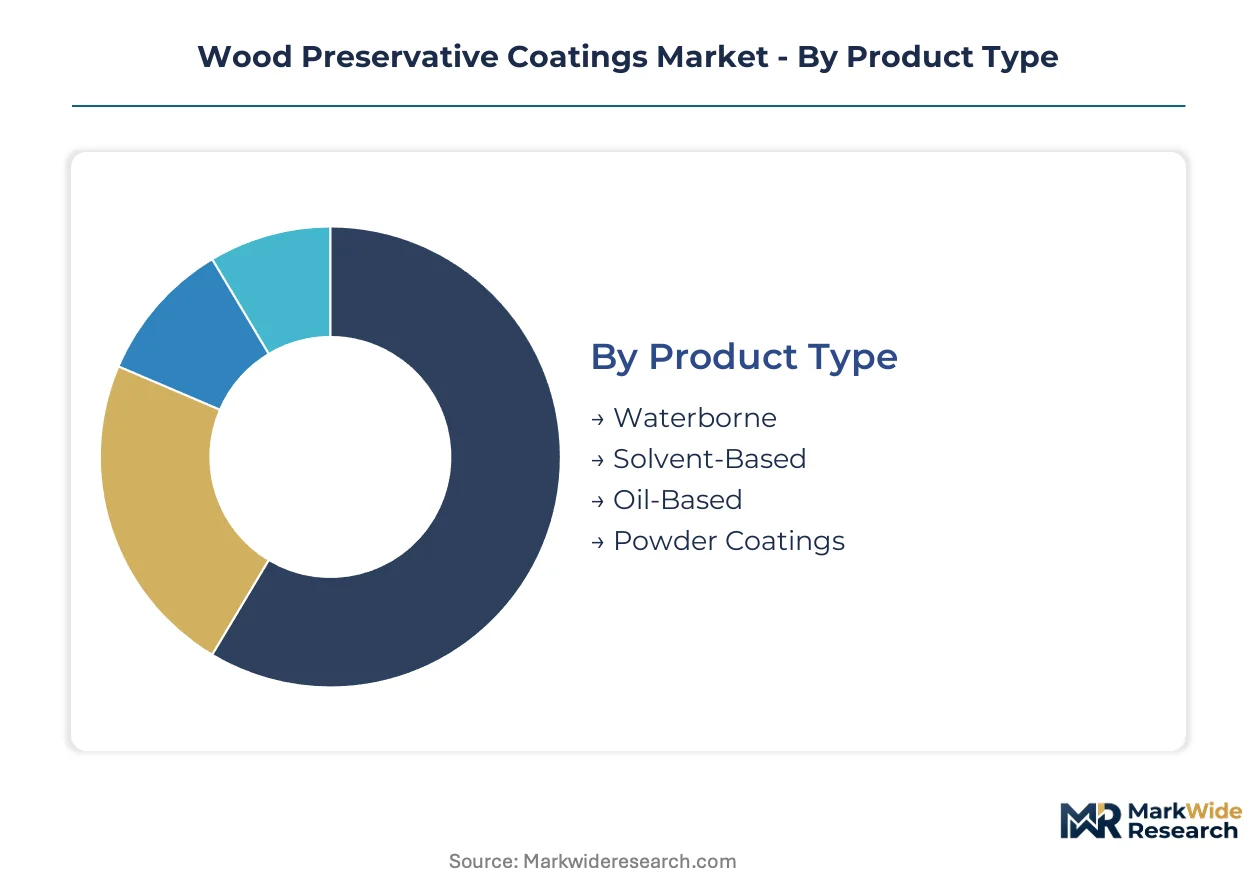
Wood preservative coatings demand fragments across formulation chemistries, application settings, and procurement channels. Each segment carries distinct technical service requirements, regulatory exposure, and margin structures that reshape competitive positioning.
Product Type:
After-sales technical support intensity varies sharply across formulation platforms, with waterborne systems demanding the most intensive contractor training and equipment upgrade assistance.
- Waterborne:Acrylic and polyurethane dispersions suspended in water carriers, applied at 40-60% solids content with flash-off periods of 30-45 minutes. EPA VOC limits in California and the US Northeast are concentrating specification here for residential decking, though contractors face spray gun corrosion and drying capacity constraints.
- Solvent-Based:Alkyd and urethane resins dissolved in mineral spirits or naphtha, delivering deeper substrate penetration and faster recoat windows. Industrial pole treatment facilities in the US Midwest retain legacy specifications where ambient moisture complicates waterborne curing.
- Oil-Based:Penetrating linseed and tung oil formulations that nourish cellular structure while repelling moisture. DIY enthusiasts in Pacific Northwest outdoor living markets favor these for cedar and redwood restoration projects.
- Powder Coatings:Thermoset epoxy and polyester resins applied electrostatically to engineered wood components. Furniture manufacturers specify these for interior joinery where zero-VOC claims support sustainability certifications.
Waterborne formulations hold the largest share; momentum sits with hybrid waterborne-epoxy platforms gaining specification in below-ground applications.
Application:
Volume concentration tracks construction cycle intensity and timber exposure severity, with industrial infrastructure commanding premium pricing for performance guarantees.
- Residential:Deck, fence, and siding treatments driven by homeowner renovation cycles and outdoor living infrastructure expansion. The US Southeast pulls disproportionate volume as humidity accelerates fungal decay pressure on pressure-treated lumber.
- Commercial:Boardwalk, marina, and hospitality exterior wood specifications requiring 10-15 year service life warranties. Coastal zone contractors in Florida and California face the most stringent below-ground performance demands.
- Industrial:Utility pole, railway tie, and marine piling treatments governed by structural engineering specifications. REACH Annex XVII restrictions are redirecting European pole specifications away from legacy chemistries.
- Agricultural:Barn, silo, and fencing treatments exposed to livestock waste and high-moisture manure environments. Farmers in Iowa and Wisconsin prioritize copper-based formulations for fungal resistance in humid confinement buildings.
Residential applications anchor volume; industrial infrastructure is expanding most quickly as marine rehabilitation and utility grid hardening accelerate.
Chemical Composition:
Resin selection determines compatibility with biocide actives, cure speed, and long-term dimensional stability under cyclic moisture loading.
- Alkyds:Oil-modified polyester resins offering excellent penetration into porous softwoods and straightforward ambient cure. Solvent-based alkyd systems retain pole and piling specifications where deep substrate saturation remains critical.
- Acrylates:Water-dispersible polymers enabling low-VOC formulations with UV resistance and color retention. BASF SE anchors European supply through specialized production for exterior joinery exposed to maritime climates.
- Epoxies:Two-part thermoset systems delivering dimensional stabilization and below-ground moisture barrier performance. Marine contractors are piloting ambient-cure hybrids for piling rehabilitation in tidal zones.
- Phenolics:Formaldehyde-based resins providing exceptional moisture and chemical resistance for engineered wood substrates. Industrial laminated beam manufacturers specify these for structural components in high-humidity environments.
Acrylates dominate residential volume; epoxies are gaining share fastest as below-ground performance requirements tighten.
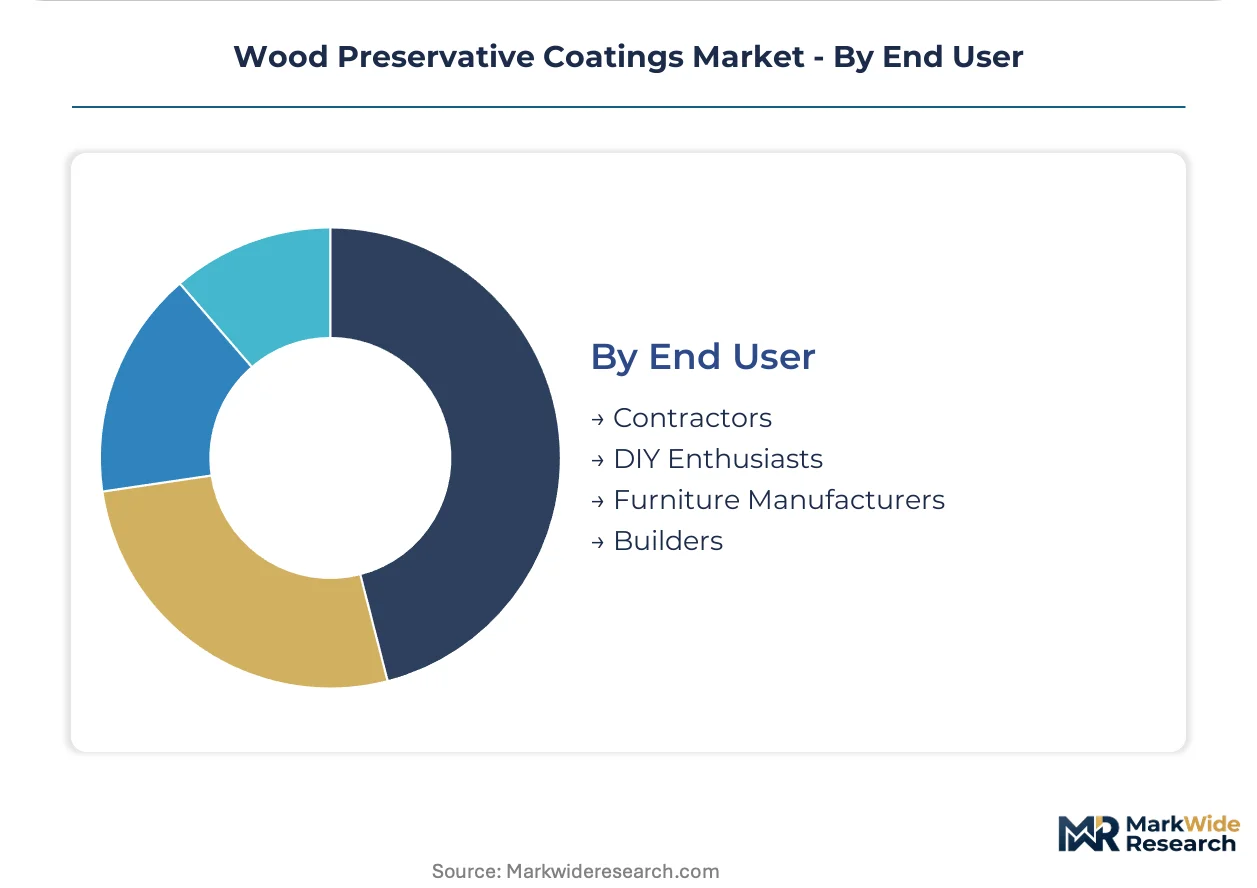
End User:
Procurement authority and technical sophistication vary dramatically, fragmenting distribution channels between big-box retail, specialized distributors, and manufacturer-direct field service.
- Contractors:Professional applicators specifying systems based on labor efficiency, equipment compatibility, and callback risk. Large deck contractors in Oregon and Washington negotiate annual volume agreements bypassing traditional distribution.
- DIY Enthusiasts:Homeowners purchasing through retail channels for maintenance and small-scale restoration projects. These buyers prioritize ease of application and immediate availability over technical performance specifications.
- Furniture Manufacturers:Industrial finishers requiring consistent film build, color matching, and compliance with indoor air quality standards. Powder coating adoption is highest among manufacturers serving hospitality and healthcare segments.
- Builders:Production homebuilders and custom framers specifying pre-treatment or field-applied systems for structural lumber. Southeast builders face the most compressed construction schedules, favoring fast-cure waterborne options.
Contractors control the largest specification share; furniture manufacturers are climbing the fastest as engineered wood component finishing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical throughput underwrites Europe's wood preservative coatings distribution, while the Trans-Siberian rail corridor links Russian timber feedstocks to Asian formulation plants. These infrastructure assets concentrate manufacturing and procurement decisions across three continents.
United States
Residential deck construction in Florida and Georgia pulls waterborne preservative volumes as humidity accelerates fungal decay cycles. EPA FIFRA registration requirements govern biocide efficacy claims for all products entering interstate commerce. Pacific Northwest contractors in Oregon and Washington negotiate direct manufacturer agreements for cedar and redwood restoration projects.
Germany
Industrial pole treatment facilities in North Rhine-Westphalia face compressed REACH Annex XVII compliance timelines for chromated copper arsenate substitution. ECHA authorization procedures tighten biocide substance sunset dates faster than historical reformulation patterns. BASF SE anchors specialized acrylate resin production for exterior joinery exposed to North Sea maritime climates.
China
Marine piling rehabilitation along the Yangtze River Delta drives epoxy-based dimensional stabilization demand for below-ground timber. GB standards and MEE environmental regulations constrain VOC emissions from solvent-based alkyd production. Guangdong province manufacturers pilot hybrid waterborne-epoxy platforms for utility infrastructure specifications.
Canada
Pressure-treated lumber exports from British Columbia to US Southeast builders sustain cross-border preservative coating demand. Health Canada PMRA regulates biocide registration parallel to EPA frameworks without mutual recognition. Quebec's engineered wood component manufacturers specify powder coatings for zero-VOC interior joinery certifications.
Australia
Coastal boardwalk infrastructure in New South Wales and Queensland requires 10-15 year service life warranties against severe decay hazard exposure. TGA and state environmental protection agencies administer chemical safety assessments for timber treatment products. Melbourne-area contractors consolidate procurement toward integrated coating-system suppliers bundling preservatives with application equipment.
Wood Preservative Coatings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in biocide and resin supply. The vendor base clusters around integrated chemical conglomerates with captive biocide manufacturing, mid-cap formulation specialists serving regional contractor networks, and application equipment bundlers capturing specification authority. Three archetypes dominate: integrated biocide-resin manufacturers, regional formulation packagers, and coating-system integrators. Capacity expansion and direct-to-contractor digital channel development represent the dominant competitive moves reshaping distribution economics.
Among integrated biocide manufacturers, Lonza and LANXESS exemplify the upstream control archetype through in-house production of copper-based actives and specialty intermediates. BASF SE anchors European resin supply for waterborne exterior applications. These three entities represent distinct strategic positions—biocide integration, regional chemical specialization, and acrylate polymer leadership—without overlapping functional claims.
| Leading Market Players |
|---|
| Lonza |
| BASF SE |
| Koppers Performance Chemicals |
| PPG Industries Inc. |
| The Sherwin-Williams Company |
| LANXESS |
| Viance |
| Akzo Nobel N.V. |
| Arxada |
| Others |
Value Chain & Pricing Dynamics
South American copper concentrate sourcing anchors upstream cost structures, concentrating margin capture with integrated biocide manufacturers like Lonza while merchant formulation houses absorb feedstock volatility. Waterborne conversion investments and REACH compliance costs are redistributing profitability toward resin specialists and application equipment bundlers downstream.
Pricing Analysis
EPA FIFRA registration requirements dictate the pricing tier structure across the wood preservative coatings market. Three-tier pricing structure across premium, standard, and economy levels separates epoxy-based marine systems with performance warranties from commodity waterborne decking treatments and legacy solvent-based pole coatings. Price differentiation rests on certification grade—EPA-registered biocide claims command 15-25% premiums over baseline formulations—and volume scale, with annual contractor agreements securing 8-12% discounts. Pricing pressure stems from copper and specialty biocide intermediate tightness compressing margins at mid-tier formulation packagers. DIY enthusiasts through retail channels exhibit highest price sensitivity, while industrial pole specifiers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with regional formulation packagers in Germany, China, and the United States who toll-process biocide-resin blends for brand owners. Geographic supply concentration centers on Germany for acrylate resin production, China for epoxy intermediate manufacturing, and the United States for copper-based biocide integration. Raw material dependencies draw from Chilean copper mining, South Korean epoxy resin output, and Saudi petrochemical feedstocks. Supply chain risk manifests as single-source vulnerability for micronized copper actives following recent consolidation among South American mining operations. Distribution runs through integrated coating-system suppliers bundling preservatives with spray equipment and technical field service, bypassing traditional two-step distributor networks in the Pacific Northwest and Florida markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against copper-free preservative platforms accelerated by EU Green Deal chemical sustainability targets. Chromated copper arsenate phase-outs and emerging organic biocide alternatives threaten traditional copper-based market positions.
For Market Incumbents: Entrench specification authority through backward integration into captive biocide manufacturing, mirroring Lonza's integrated cost position. Lock in multi-year contractor volume agreements in the US Southeast and Pacific Northwest before copper-free alternatives achieve scale. Prioritize hybrid waterborne-epoxy R&D to defend pole and piling segments against organic biocide substitutes.
For New Entrants and Emerging Players: Australia's coastal boardwalk rehabilitation market offers underpenetrated white-space for epoxy-based dimensional stabilization systems requiring 10-15 year service warranties. Target agricultural barn and silo treatments in Iowa and Wisconsin where copper-based fungal resistance commands premium positioning. Pursue direct-to-contractor digital procurement platforms bypassing legacy distributor networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulation packagers in North Rhine-Westphalia and Guangdong province carrying stranded solvent-based capacity. Five-to-ten year viability hinges on waterborne conversion execution and hybrid epoxy technology adoption. Monitor EPA registration timeline compression and ECHA biocide sunset date accelerations as inflection signals for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocide Manufacturing | Lonza's captive copper active production sustains cost advantages against merchant buyers facing South American concentrate volatility. |
| Hybrid Waterborne-Epoxy Platform Development | Combining ambient cure convenience with below-ground performance opens utility pole specifications previously reserved for solvent systems. |
| Direct-to-Contractor Digital Channel Buildout | Pacific Northwest deck contractors now negotiate annual volume agreements bypassing traditional two-step distribution networks. |
| REACH Annex XVII Compliance Acceleration | European pole treatment facilities face compressed timelines for chromated copper arsenate substitution toward copper azole alternatives. |
| Application Equipment Bundling | Integrated coating-system suppliers capture specification authority by pairing preservatives with spray system upgrades and field technical service. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at industrial pole treatment facilities, procurement leads at Southeast US homebuilders, distribution channel partners in the Pacific Northwest, and technical R&D directors at resin manufacturers, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from coating-system suppliers, EPA FIFRA registration databases, and ECHA REACH authorization records. Bottom-up volume modeling triangulated with top-down value chain analysis across formulation chemistry segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry platform, application setting severity, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from trend extrapolation of renovation cycle intensity and infrastructure replacement patterns. Industry-specific forecast inputs incorporated marine piling rehabilitation backlogs and utility grid hardening capital commitments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by copper-free preservative entrants or accelerated ECHA biocide sunset timelines would shift outcomes. Quarterly review of EPA registration approval velocities and contractor equipment upgrade rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Vinyl Surface Coatings Market
Coatings
Polyurethane (PU) Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Trim Coatings Market
Coatings
Topcoat Market
Coatings
Fluoropolymer Coating Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Global Surface Protection Films Market
Coatings
Coating Pre-Treatment Market
Coatings
Acrylic Surface Coating Market