
 Middle East Polyamide Market | 2026-2036
Middle East Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Polyamide Market Insights
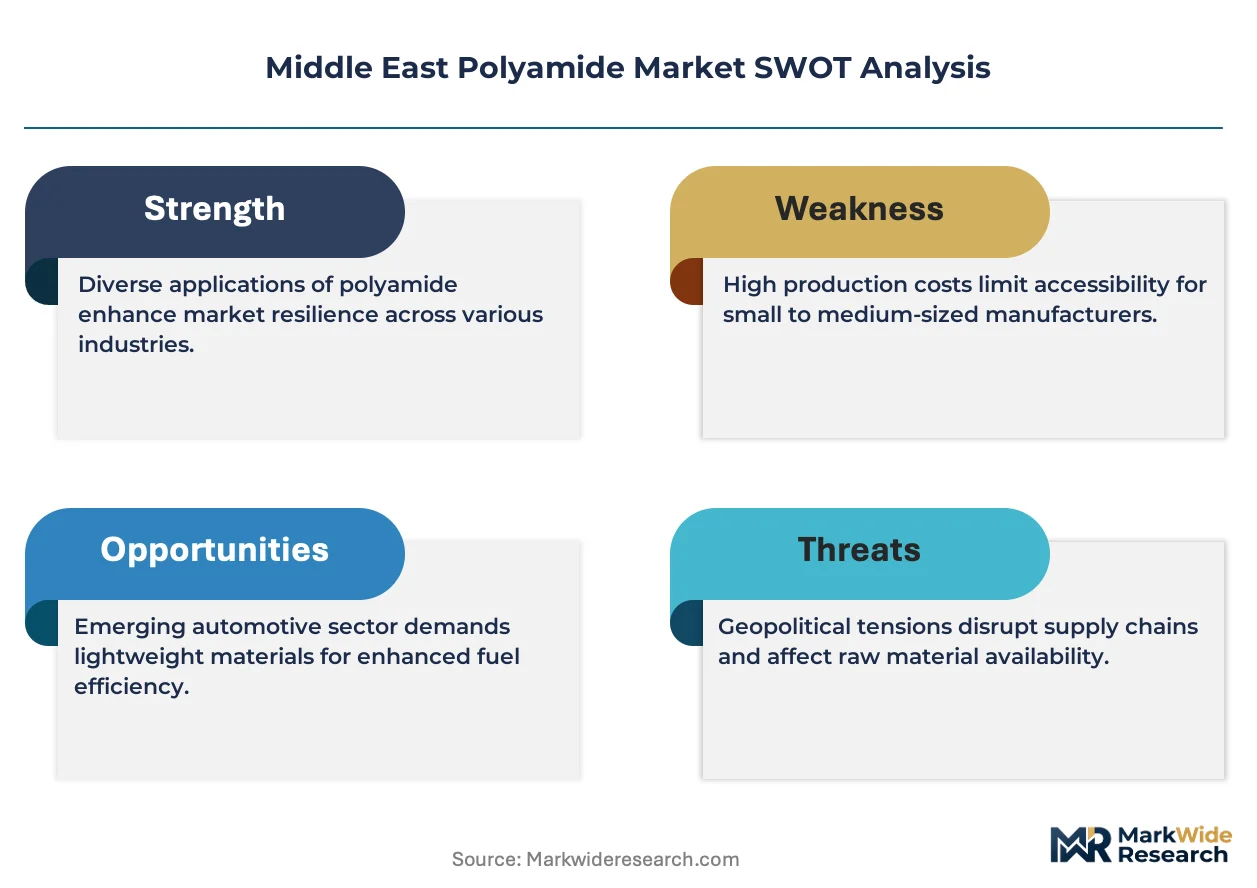
EU Green Deal carbon border adjustments is decoupling Middle East polyamide exporters from traditional European offtake patterns. SABIC leverages its integrated feedstock position in Jubail to sustain cost-advantaged PA 6 and PA 66 output for regional automotive tiers. BASF anchors its technical compounding expertise through localized masterbatch operations serving electrical and consumer goods molders in the UAE. LANXESS differentiates via high-heat PA 6.6 compounds targeting powertrain downsizing requirements among Saudi OEM suppliers.
Polyamides are synthetic thermoplastic polymers characterized by repeating amide linkages along the backbone, typically exhibiting melting points between 220°C and 265°C depending on chain length and crystallinity; PA 6 derives from caprolactam ring-opening polymerization while PA 66 forms from hexamethylenediamine and adipic acid condensation, delivering high tensile strength, abrasion resistance, and chemical stability for engineered components in hostile thermal and mechanical environments. Fibers and resins dominate current Middle East volume offtake, with fiber-grade PA 6 maintaining mature positions in Gulf textile operations while resin formulations capture expanding margin pools from electrical connector and automotive under-hood specifications. PA 46 and PA 12 occupy narrower specialty positions where high crystallization rates and moisture resistance justify premium positioning for fuel system and pneumatic applications.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) product conformity schemes are tightening flame-retardancy and migration testing protocols for electrical-grade polyamide compounds. SFDA and MOHAP medical device frameworks in Saudi Arabia and the UAE respectively create incremental compliance layers for healthcare-oriented PA 12 tubing and packaging applications. Stakeholders must monitor how Gulf Cooperation Council harmonization of chemical substance registration affects import pathways for European and Asian compounders.
Market Dynamics
Saudi Vision 2030 localization mandates are compressing import dependency for polyamide compounds while redirecting procurement toward domestic compounding capacity clustered around Jubail Industrial City.
Growth Catalysts
- Automotive lightweighting specifications:Under-the-hood component requirements from Saudi and UAE OEM suppliers are pulling PA 6 and PA 66 resin volumes into powertrain and structural applications.
- SASO flame-retardancy protocols:Tightened electrical-grade compound standards are forcing formulation upgrades that favor technical compounders with localized testing infrastructure.
- Petrochemical feedstock integration:Caprolactam and adipic acid precursors available within the Eastern Province cluster are shortening supply chains for regional PA 6 and PA 66 production.
Market Restraints
- Caprolactam price volatility:Benzene derivative cost swings transmit directly into PA 6 margin compression for non-integrated compounders lacking captive precursor supply.
- European carbon border adjustments:EU Green Deal CBAM mechanisms are eroding traditional export pathways for Gulf-origin polyamide resins previously absorbed by German and Italian automotive tiers.
- PA 12 supply concentration:Laurolactam precursor dependency on Asian suppliers creates bottleneck risk for medical tubing and fuel system applications requiring moisture-resistant grades.
Strategic Opportunities
- UAE electrical connector molders:ESMA conformity schemes are creating certified compound demand that technical masterbatch operations can capture through localized production.
- Healthcare PA 12 tubing:SFDA and MOHAP medical device frameworks are opening compliance-driven segments for biocompatible polyamide formulations in Saudi and UAE markets.
- Powertrain downsizing compounds:High-heat PA 6.6 specifications for turbocharged engine environments represent formulation margin pools above commodity resin pricing.
Industry Challenges
- Polymer compounding technologist scarcity:Gulf technical institutes produce fewer formulation chemists than industrial localization targets require, forcing reliance on expatriate expertise.
- GCC chemical substance registration harmonization:Divergent national inventory requirements between Saudi Arabia, UAE, and Kuwait are delaying cross-border compound shipments and compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Polyamide Market |
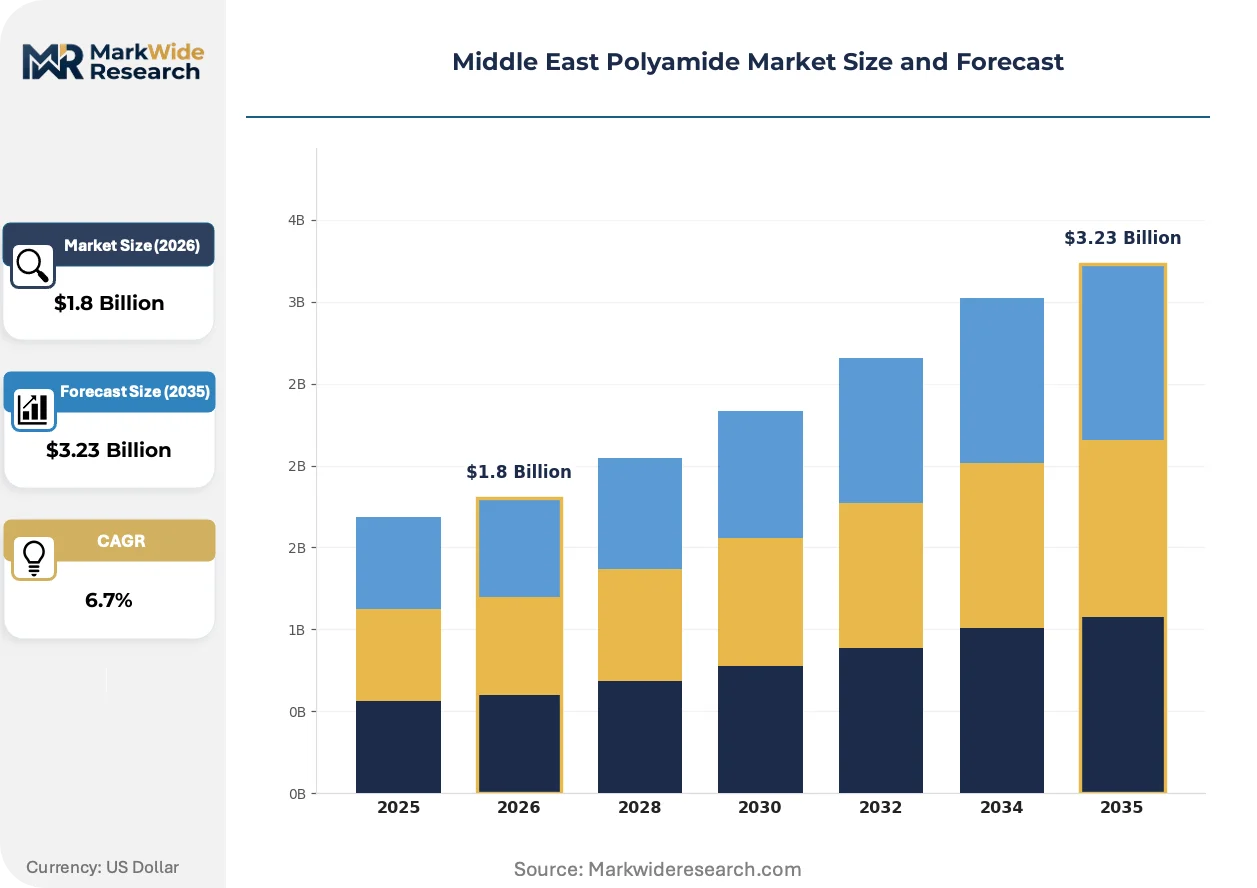
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 46, PA 12 Application: Automotive, Textiles, Electrical, Consumer Goods End User: Manufacturers, Retailers, OEMs, Distributors Form: Fibers, Resins, Films, Granules |
| Companies Covered | BASF, Celanese Corporation, SABIC, Koch Industries, EMS-Chemie Holding AG, Petro Rabigh, LANXESS, Solvay, Arkema, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Polyamide Market Trends and Innovations
Polyamide formulation chemistry is pivoting toward high-heat and halogen-free specifications as automotive electrification and regional regulatory tightening reshape compound performance requirements.
Bio-based polyamide feedstocks derived from castor oil sebacic acid are converging with regional petrochemical producers' diversification strategies. SABIC and regional partners are piloting PA 11 and PA 1010 grades to reduce cradle-to-gate carbon intensity for European automotive export contracts. This convergence is compressing the premium gap between petroleum-derived and renewable-source polyamides in technical compound pricing.
EU Green Deal carbon border adjustment mechanisms are restructuring Middle East export economics. Gulf compounders previously shipping standard PA 6 and PA 66 grades to Italian and German automotive tiers now face embedded carbon cost penalties. The regulation is forcing Eastern Province producers toward lower-emission process configurations and certified product carbon footprint documentation for retained European market access.
Electrical-grade procurement is consolidating around ESMA-certified compounders with in-house flame-retardancy testing. UAE connector molders previously sourcing from European distributors are qualifying domestic masterbatch operations to compress lead times and avoid CBAM exposure. This consolidation is most visible in Dubai and Sharjah industrial zones where electrical component manufacturing clusters have densified.
Middle East Polyamide Market Segmentation
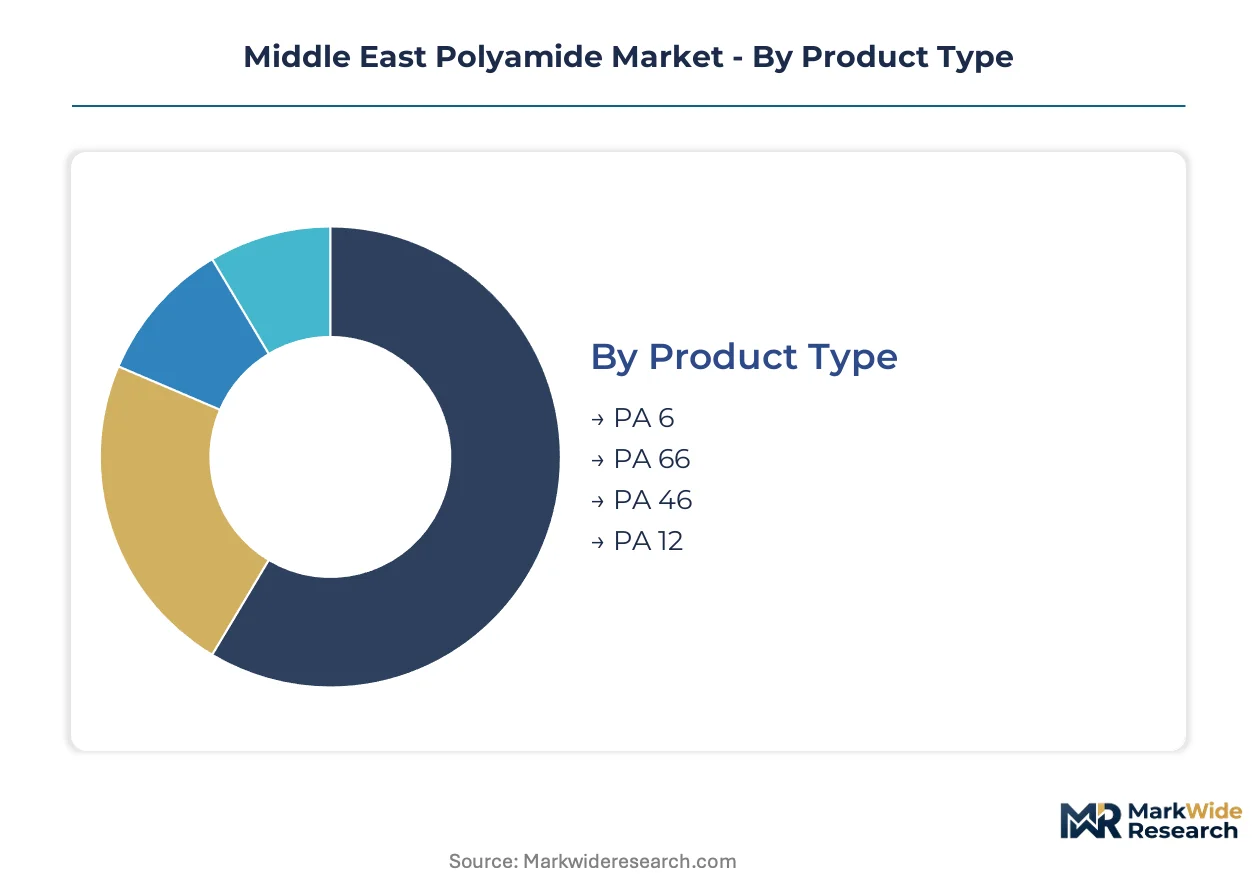
Polyamide demand across the Middle East fragments across technical specifications and conversion formats that dictate margin capture. Understanding how product chemistry, application requirements, and supply form intersect reveals where compounding capacity investments concentrate.
Product Type:
Caprolactam and adipic acid precursor availability within Saudi Arabia's Eastern Province cluster shapes which chemistries achieve cost-advantaged regional production.
- PA 6:Ring-opening polymerization of caprolactam yields this semi-crystalline thermoplastic with melting points near 220°C. Saudi automotive tiers in Jubail Industrial City pull fiber-grade and resin volumes for under-hood components and textile applications where feedstock integration sustains margin.
- PA 66:Condensation polymerization of hexamethylenediamine and adipic acid produces higher crystallinity and thermal resistance than PA 6. UAE electrical connector molders and Saudi powertrain suppliers specify this grade for high-heat environments where dimensional stability under load is non-negotiable.
- PA 46:High crystallization rates suit turbocharged engine components and rapid-cycle injection molding.
- PA 12:Laurolactam-based chemistry delivers moisture resistance for fuel systems and medical tubing in Saudi and UAE healthcare frameworks.
PA 6 absorbs the bulk of installed capacity; PA 66 is expanding most quickly.
Application:
End-use specifications determine formulation complexity and certification requirements that separate commodity compounders from technical specialists.
- Automotive:OEM lightweighting mandates and powertrain downsizing specifications across Saudi Arabia and the UAE drive demand for glass-filled PA 6 and PA 66 compounds. SABIC's integrated Jubail operations supply regional tiers with cost-advantaged resin for structural and under-hood components.
- Textiles:Mature fiber-grade PA 6 consumption persists in Gulf carpet and industrial yarn operations. Saudi Vision 2030 localization targets are redirecting procurement toward domestic spinning capacity rather than imported fiber.
- Electrical:ESMA flame-retardancy protocols and SASO technical regulations force formulation upgrades for connector housings and circuit breaker components.
- Consumer Goods:Appliance housings and power tool components utilize reinforced PA grades where surface finish and impact resistance balance cost.
Automotive claims the largest volume share; electrical applications are climbing the fastest on regulatory tightening.
End User:
Procurement authority and technical specification control vary sharply across the value chain, determining who captures formulation margin.
- Manufacturers:Compounders and converters with in-house extrusion and molding operations specify raw resin grades and additive packages directly. These players cluster around Jubail Industrial City and Dubai's industrial zones where logistics compression matters.
- OEMs:Saudi and UAE automotive assemblers and electrical equipment producers increasingly dictate certified compound specifications that exclude non-qualified suppliers.
- Distributors:Inventory holders bridge fragmented molders with resin supply, though localization mandates are compressing their role.
- Retailers:Indirect procurement channels serve small-scale converters with limited technical specification capabilities.
Manufacturers dominate procurement volume; OEM direct sourcing is gaining share fastest.
Form:
Physical presentation determines conversion economics and logistics configurations across the supply chain.
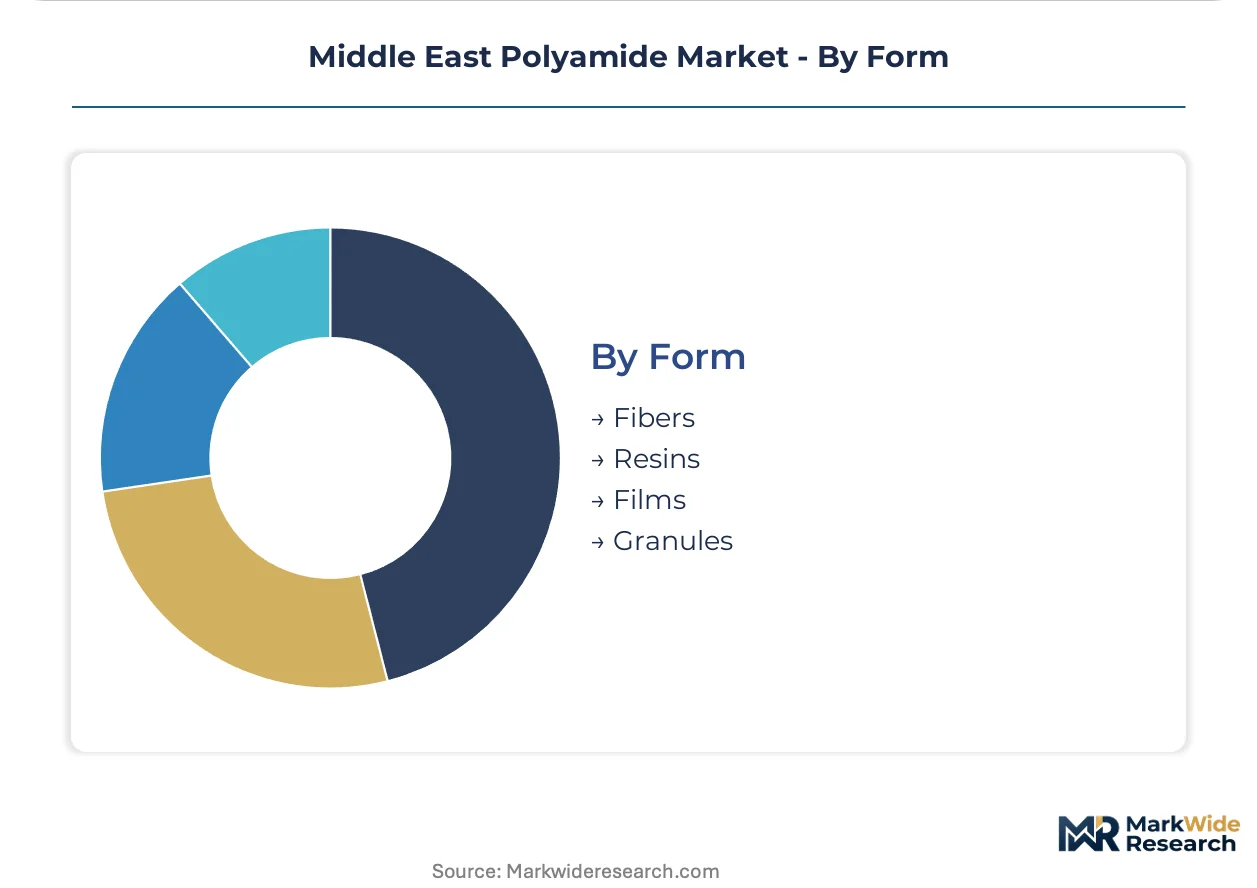
- Resins:Pelletized polymer serves injection molders and extruders across automotive and electrical applications. This form captures the highest value-add downstream where compounding expertise concentrates.
- Fibers:Continuous filament and staple formats feed Gulf textile operations with mature demand patterns.
- Granules:Intermediate sizing suits bulk handling for large-volume processors with dedicated silo infrastructure.
- Films:Cast and oriented PA films serve packaging and industrial lamination with narrower regional demand.
Resins absorb the bulk of installed capacity; fiber demand is expanding most quickly on textile localization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors polyamide production capacity across the Middle East, with Saudi Arabia's Eastern Province petrochemical cluster supplying integrated feedstock for regional PA 6 and PA 66 output.
Saudi Arabia
Automotive OEMs and electrical connector molders drive resin demand for under-the-hood components and circuit housings. SASO flame-retardancy protocols tighten formulation standards for electrical-grade compounds. Jubail Industrial City concentrates domestic compounding capacity where SABIC leverages captive caprolactam supply.
United Arab Emirates
ESMA conformity schemes redirect procurement toward certified local compounders serving Dubai and Sharjah electrical manufacturing zones. Dubai's connector molding clusters densify around masterbatch operations with in-house testing infrastructure. Abu Dhabi industrial zones attract technical compounding investments targeting healthcare tubing applications.
Kuwait
Petrochemical feedstock availability supports limited regional resin distribution rather than integrated compounding. GCC chemical substance registration harmonization delays remain unresolved versus Saudi and UAE pathways. Shuaiba Industrial Area hosts bulk resin handling for re-export to neighboring markets.
Qatar
Ras Laffan Industrial City petrochemical infrastructure supplies precursor chemicals without downstream polyamide compounding. Qatar's procurement patterns favor imported technical compounds for electrical and automotive applications. Domestic manufacturing zones remain underdeveloped for polymer conversion.
Israel
Specialty PA 12 demand for medical tubing and fuel systems outpaces regional supply, creating import dependency. The country's national pharmaceutical regulator maintains stringent biocompatibility standards for healthcare applications. Tel Aviv-area distributors bridge European and Asian compounders with local molders.
Middle East Polyamide Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth. The vendor base stratifies into three tiers: integrated petrochemical producers with captive feedstock, technical compounders with localized testing infrastructure, and distributors bridging non-qualified suppliers with fragmented molders. Two dominant competitive moves define positioning: backward integration into precursor chemicals and geographic expansion of masterbatch operations to compress lead times for certified compounds.
Within the integrated producer tier, SABIC anchors cost-advantaged PA 6 and PA 66 output through its Jubail operations. BASF and LANXESS occupy positions among technical compounders with localized masterbatch and high-heat formulation capabilities. These three exemplify how feedstock control and certification infrastructure separate margin tiers across the regional market.
| Leading Market Players |
|---|
| BASF |
| Celanese Corporation |
| SABIC |
| Koch Industries |
| EMS-Chemie Holding AG |
| Petro Rabigh |
| LANXESS |
| Solvay |
| Arkema |
| Others |
Pricing and Supply Chain Analysis
High-heat formulation chemistry for turbocharged powertrain applications is compressing cost economics toward integrated producers while simultaneously concentrating supply around Jubail Industrial City's captive feedstock infrastructure. This production-method transition simultaneously erodes margin pools for non-integrated compounders and elevates pricing power for SABIC and technical specialists with localized testing capabilities.
Pricing Analysis
Certified compound throughput for ESMA and SASO electrical-grade specifications anchors value-based pricing that rewards flame-retardancy testing infrastructure. Three-tier pricing structure across premium certified, standard technical, and economy commodity levels separates LANXESS high-heat PA 6.6 compounds from regional resin volumes. Price differentiation hinges on certification depth and vertical integration into caprolactam supply. Cost compression in fiber-grade PA 6 is intensifying because Saudi Vision 2030 localization redirects procurement toward domestic spinning capacity. Electrical connector molders in Dubai and Sharjah exhibit lowest price sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Polymer compounding technologist scarcity across Saudi Arabia's Eastern Province and UAE industrial zones constrains masterbatch operation scale-up despite feedstock abundance. Supply concentrates in Saudi Arabia, the UAE, and Germany for technical compounds. Raw material dependencies center on caprolactam, adipic acid, and laurolactam precursors. Single-source vulnerability for PA 12 laurolactam from Asian suppliers creates bottleneck risk for medical tubing applications. Distribution runs through Jubail-based compounders serving regional automotive tiers and Dubai masterbatch operations supplying electrical molders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO flame-retardancy protocols and ESMA conformity schemes erect a cost-of-compliance barrier that favors compounders with localized testing infrastructure over import-dependent distributors. This regulatory moat protects margin pools for certified players while compressing non-qualified supplier viability.
For Market Incumbents: Cement positioning through backward integration into adipic acid precursors and expansion of high-heat formulation capacity serving Saudi powertrain downsizing specifications. Defend against European carbon border adjustment exposure by accelerating certified product carbon footprint documentation for retained automotive tier supply contracts. Prioritize capacity addition in Jubail Industrial City to exploit feedstock integration advantages.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in electrical-grade compounds creates white-space opportunity for ESMA-certified masterbatch operations in Dubai and Sharjah industrial zones. Target healthcare PA 12 tubing applications where SFDA and MOHAP frameworks limit incumbent penetration. Pursue joint venture structures with regional distributors to compress regulatory qualification timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated petrochemical producers seeking technical compounding capabilities. Long-term viability favors compounders with dual certification depth across automotive and electrical verticals. Acquisition target archetype: mid-cap technical compounders with captive testing infrastructure and established OEM qualification status. Monitor EU Green Deal CBAM enforcement intensity as inflection signal for Gulf-origin resin export economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | SABIC's Jubail operations shorten precursor supply chains for cost-advantaged PA 6 output. |
| ESMA Certification Investment | BASF's Dubai masterbatch operations capture electrical connector demand through localized flame-retardancy testing. |
| High-Heat Formulation Expansion | LANXESS targets turbocharged engine specifications with PA 6.6 compounds above commodity resin pricing. |
| Long-term Supply Agreement | Saudi automotive tiers secure qualified compound volumes under Vision 2030 localization mandates. |
| Joint Venture with Regional Distributor | New entrants compress ESMA qualification timelines through partnerships with established UAE channel partners. |
Research Methodology
Independent corroboration across primary interviews with polymer compounding plant managers, automotive Tier 1 procurement leads, electrical connector molder technical directors, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from customs and trade data, Gulf petrochemical industry association reports, SEC filings from listed compounders, and SASO technical regulation documentation. Bottom-up resin volume estimates triangulate with top-down macroeconomic consumption models across the analysis window.
Rate-of-change decomposition across product chemistry tiers, application specifications, end-user procurement authority, and physical form factors structures the analytical framework. CAGRs derive from segment-level growth rate blending weighted by base-year volume shares. Forecast inputs incorporate automotive production schedules from Saudi and UAE OEMs, electrical manufacturing cluster expansion in Dubai and Sharjah, and regulatory harmonization progress across GCC chemical substance registration frameworks.
Inputs from primary stakeholder interviews and published regulatory filings were available through the study window; gaps in real-time caprolactam spot pricing and confidential OEM compound qualification timelines introduce uncertainty bands around near-term volume projections. Forecasts reflect modeling assumptions regarding Saudi Vision 2030 industrial localization pace and EU CBAM implementation intensity. Material deviation in automotive electrification timelines or GCC regulatory harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Bio-Based Polypropylene Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Photocure Resins Market