
 Asia-Pacific Cosmetic Surgery Market | 2026-2036
Asia-Pacific Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cosmetic Surgery Market Insights
MFDS tightened device registration rules is restructuring the cost-of-entry calculus for new clinic operators across South Korea and Thailand. AbbVie leverages its Allergan Aesthetics portfolio to sustain leadership in injectable neurotoxins across Seoul and Singapore. Galderma anchors its position through R&D intensity in biostimulatory fillers, while Alma Lasers dominates the energy-based device segment with manufacturing scale in Israel serving Asia-Pacific distributors.
Cosmetic surgery encompasses surgical and non-surgical procedures that reshape or enhance facial and body structures using implants, energy-based devices, injectable biologics, and excisional techniques, typically performed under local or general anesthesia in accredited facilities. Its primary commercial purpose centers on aesthetic enhancement, reconstructive correction, and age-related restoration for elective-paying consumers. Injection-based procedures command the widest margin pools due to recurring treatment cycles and lower capital requirements, while laser surgery segments expand fastest on the back of MFDS and TGA approvals for fractional and picosecond platforms. Minimally invasive technology segments mature in Japan and Australia where penetration rates already exceed regional averages.
MFDS, TGA, and China's NMPA collectively shape product standards through divergent approval timelines and post-market surveillance requirements that filter which devices reach clinic floors. The EU AI Act and MDR exert indirect pressure on Asia-Pacific manufacturers exporting to European markets, forcing upstream design changes. Stakeholders must monitor regulatory divergence between Seoul's real-time adverse event reporting and Beijing's provincial pilot programs to anticipate which compliance investments will transfer across borders.
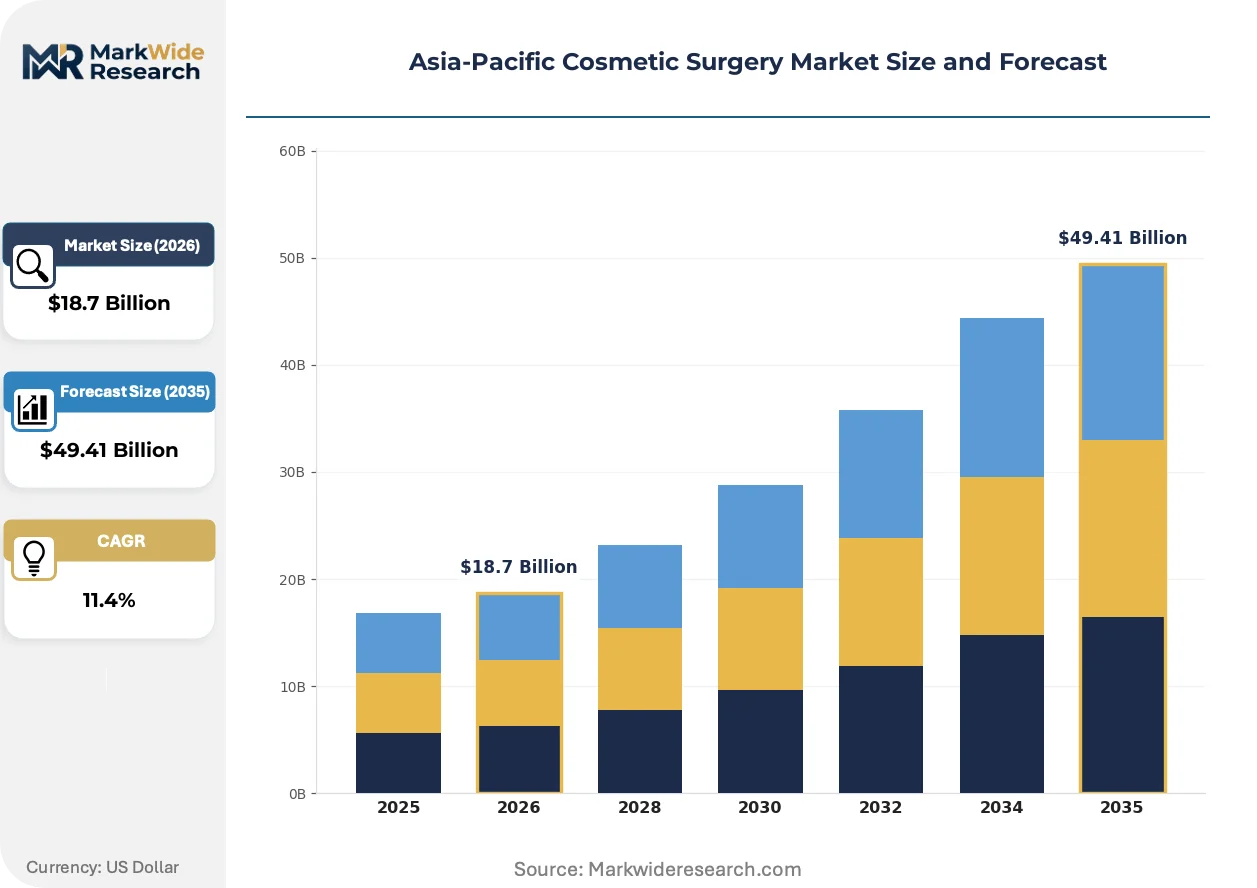
Market Dynamics
MFDS device registration tightening is compressing the competitive set for energy-based platforms across South Korea and Thailand, forcing clinic operators toward compliant capital investments that reshape margin structures and vendor selection criteria.
Growth Catalysts
- Medical tourism flows:North American and Middle Eastern patients are sustaining double-digit patient volume growth at Bangkok's Sukhumvit corridor clinics and Seoul's Gangnam district facilities.
- MFDS regulatory clarity:Tighter laser platform registration rules are filtering out non-compliant devices, creating protected market positions for certified equipment vendors.
- Biostimulatory filler R&D:Injectable portfolios incorporating polylactic acid and calcium hydroxylapatite are extending treatment intervals and locking in recurring revenue streams.
Market Restraints
- Capital intensity for compliance:Picosecond and fractional laser platforms require seven-figure equipment investments that strain independent clinic balance sheets.
- Device supply concentration:Israeli manufacturing hubs dominate energy-based equipment sourcing, exposing Asia-Pacific distributors to shipping cost volatility and currency fluctuation.
- Substitution by topical alternatives:High-potency retinoid and peptide formulations are capturing preventive aesthetic spending among younger demographics.
Strategic Opportunities
- Vietnam and Indonesia penetration:Ho Chi Minh City and Jakarta clinic networks remain undersupplied with accredited neurotoxin and filler distribution.
- Teleconsultation-to-treatment pathways:Digital pre-assessment platforms are compressing patient acquisition costs and expanding catchment radii beyond metropolitan cores.
- NMPA provincial pilot programs:China's decentralized medical device approval trials are creating faster market entry routes for compliant South Korean manufacturers.
Industry Challenges
- Practitioner certification bottlenecks:MFDS-mandated laser safety credentials and TGA injector accreditation requirements are constraining qualified staff availability.
- Legacy EMR integration friction:New energy-based devices require API connectivity with established patient management systems that lack standardized data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cosmetic Surgery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Rhinoplasty, Liposuction, Facelift End User: Female, Male, Medical Tourists, Local Patients Technology: Laser Surgery, Minimally Invasive, Traditional Surgery, Injection-Based Service Type: Outpatient, Inpatient, Post-Operative Care, Consultation |
| Companies Covered | AbbVie, Galderma, Cynosure Lutronic, Johnson & Johnson, Alma Lasers, Cutera, Lumenis, Bausch Health Companies, Merz Pharma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cosmetic Surgery Market Trends and Innovations
Technology convergence between imaging diagnostics and treatment delivery is compressing consultation-to-procedure timelines across Asia-Pacific aesthetic networks. Regulatory divergence between Seoul, Beijing, and Sydney is forcing manufacturers toward modular platform designs.
Picosecond laser systems are expanding into melasma and tattoo removal protocols previously dominated by Q-switched platforms. Dermatology chains in Singapore and Sydney are adopting these devices at replacement-cycle pace. The technology is expanding into lower-tier city clinics that previously deferred capital upgrades due to uncertainty over MFDS compliance timelines.
TGA's 2024 guidance on energy-based device adverse event reporting is extending post-market surveillance obligations for imported laser platforms. Australian distributors now face quarterly safety data submission requirements that increase operational overhead. High-volume clinic networks are responding by consolidating procurement through single-vendor master service agreements that bundle compliance documentation.
Subscription-based treatment packages are displacing single-procedure pricing across Thailand's medical tourism corridors. Bangkok and Phuket clinics now structure neurotoxin and filler programs around annual membership tiers rather than per-unit fees. This shift is most visible among Middle Eastern patient segments seeking bundled accommodation-treatment logistics.
Asia-Pacific Cosmetic Surgery Market Segmentation
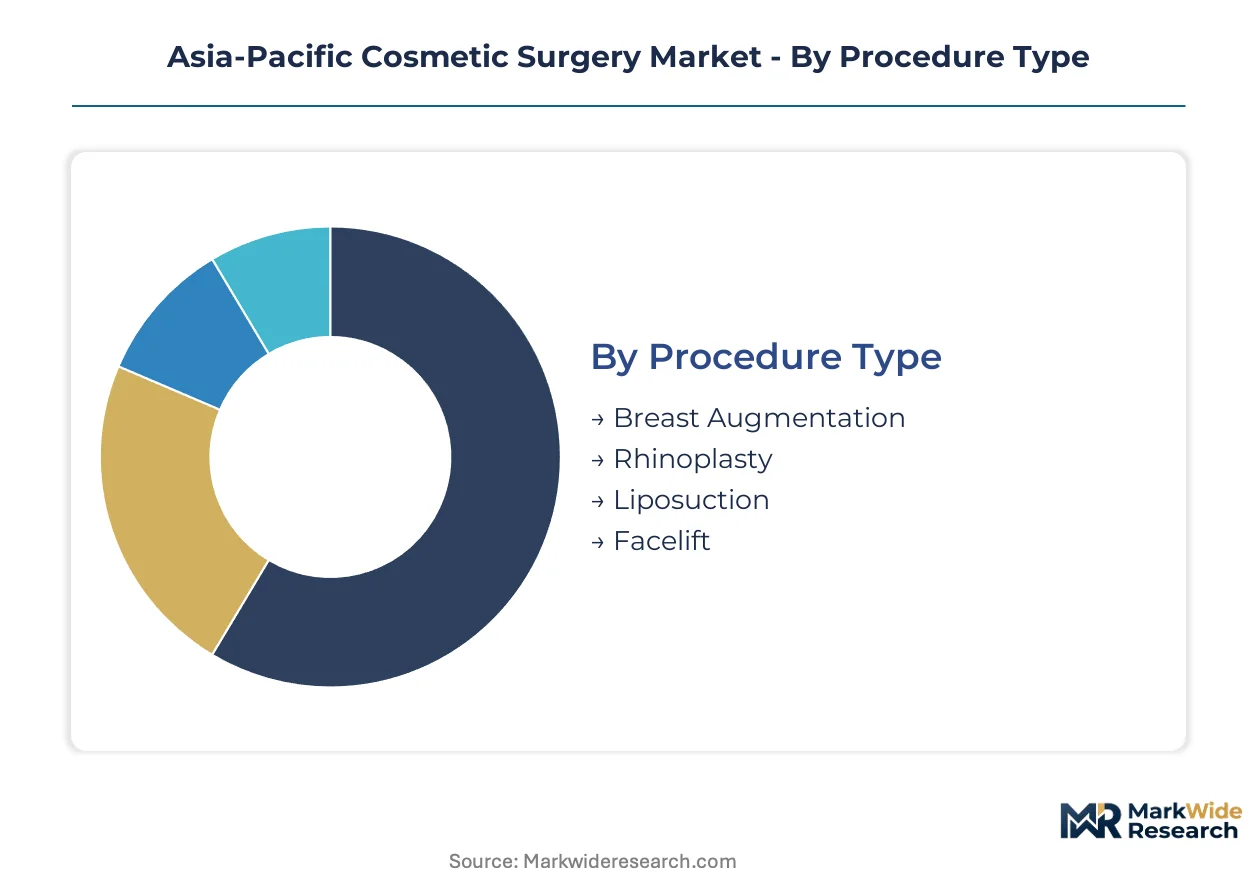
Procedure mix and technology platform choices in Asia-Pacific cosmetic surgery determine capital deployment, regulatory exposure, and margin sustainability for clinic operators. Segmentation clarity enables vendors to align device portfolios with the divergent compliance requirements of South Korea's MFDS, Australia's TGA, and China's NMPA.
Procedure Type:
Laser wavelength specifications and implant material composition differentiate procedure economics across Seoul's Gangnam district and Bangkok's Sukhumvit corridor.
- Breast Augmentation:Silicone gel and saline implant configurations dominate revenue pools in Thailand's medical tourism corridors. Seoul clinics report sustained demand from domestic patients seeking anatomical and round profile variants.
- Rhinoplasty:Structural grafting techniques using autologous cartilage and synthetic implants concentrate surgical expertise in South Korea's university-affiliated hospitals. Bangkok operators capture Middle Eastern patient flows seeking dorsal hump reduction and tip refinement.
- Liposuction:Power-assisted and ultrasound-assisted modalities reduce operative time for high-volume clinic networks.
- Facelift:SMAS plication and deep plane approaches command premium positioning in Sydney and Singapore aesthetic practices.
Mature deployment sits with Breast Augmentation. Newer deployment is concentrated in Rhinoplasty.
End User:
Customer acquisition cost structures diverge sharply between domestic patient bases and medical tourist segments requiring bundled logistics.
- Female:Neurotoxin and filler maintenance cycles generate recurring revenue streams across Japan's metropolitan clinic networks. Pre-emptive aesthetic spending among demographics under 35 is shifting toward biostimulatory injectables with extended treatment intervals.
- Male:Jawline contouring and hair transplantation procedures are expanding fastest among professional demographics in Singapore and Hong Kong. Male patient share is climbing most quickly in Seoul's corporate district clinics.
- Medical Tourists:North American and Middle Eastern visitors sustain double-digit volume growth at Bangkok and Phuket facilities offering accommodation-treatment packages.
- Local Patients:Price-sensitive domestic demand concentrates in Indonesia's emerging clinic networks and Vietnam's Ho Chi Minh City aesthetic practices.
Revenue concentration favors Female segments. Volume expansion is strongest in Medical Tourists.
Technology:
Capital intensity and regulatory approval timelines separate scalable platform categories from bespoke surgical approaches.
- Laser Surgery:Picosecond and fractional platforms for melasma, tattoo removal, and skin resurfacing require MFDS-compliant registration in South Korea. Israeli-manufactured devices dominate procurement pipelines for Asia-Pacific distributors.
- Minimally Invasive:Thread lift and energy-based skin tightening modalities reduce recovery time for working-age patients across Australia's east coast cities. TGA adverse event reporting obligations are extending post-market surveillance costs for clinic networks.
- Traditional Surgery:Excisional techniques with general anesthesia maintain position in structural rhinoplasty and body contouring cases.
- Injection-Based:Hyaluronic acid and biostimulatory fillers command the widest margin pools due to recurring treatment cycles and minimal capital requirements.
Platform maturity concentrates in Traditional Surgery. Technology investment is flowing most heavily into Laser Surgery.
Service Type:
Facility accreditation requirements and reimbursement exposure shape service line profitability across regulated jurisdictions.
- Outpatient:Same-day discharge protocols for injectable and laser procedures maximize throughput in Seoul's high-rent Gangnam district. Ambulatory surgical center licensing requirements filter competitive entry in Japan and Australia.
- Inpatient:Overnight stays for complex body contouring and facial reconstruction concentrate in Thailand's JCI-accredited hospitals serving medical tourist segments.
- Post-Operative Care:Compression garment protocols and follow-up visit bundling differentiate premium clinic positioning.
- Consultation:Digital pre-assessment platforms are compressing patient acquisition costs and expanding catchment radii beyond metropolitan cores.
Operational scale sits with Outpatient services. Capability investment is concentrating in Consultation digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in South Korea's Gangnam district and Bangkok's Sukhumvit corridor, where medical tourism infrastructure and domestic affluence intersect. Thailand and South Korea absorb the majority of North American and Middle Eastern patient flows.
South Korea
Gangnam district clinics drive domestic rhinoplasty and facial contouring volumes through university-affiliated hospital networks. MFDS tightened laser platform registration rules, filtering non-compliant devices from clinic procurement pipelines. Seoul Capital Area facilities now prioritize MFDS-certified picosecond systems from Israeli manufacturers.
Thailand
Bangkok's Sukhumvit corridor and Phuket medical tourism hubs sustain double-digit patient growth from Middle Eastern and North American visitors. The country's national medical device regulator aligns with ASEAN harmonization frameworks while maintaining JCI accreditation standards for hospital-based surgical centers. Bangkok operators structure annual membership tiers for neurotoxin and filler programs targeting Gulf state patients.
Japan
Tokyo and Osaka metropolitan clinic networks exhibit mature penetration rates for minimally invasive modalities exceeding regional averages. METI oversees medical device standards through PMDA approval pathways that extend timelines for novel energy-based platforms. Kanto region practices concentrate outpatient injectable maintenance cycles among working-age female demographics.
Australia
Sydney and Melbourne aesthetic practices command premium positioning for SMAS facelift and thread lift procedures. TGA's 2024 guidance on energy-based device adverse event reporting extends post-market surveillance obligations to quarterly safety data submissions. East coast clinic networks respond through single-vendor master service agreements bundling compliance documentation.
China
Yangtze River Delta and Pearl River Delta urban centers pilot decentralized NMPA medical device approval programs accelerating market entry for compliant South Korean manufacturers. NMPA provincial pilot programs in Shanghai and Guangdong create faster registration routes for biostimulatory fillers and laser platforms. Beijing-Tianjin-Hebei corridor clinics expand teleconsultation-to-treatment pathways compressing patient acquisition costs.
Asia-Pacific Cosmetic Surgery Market Competitive Landscape
Israeli manufacturers anchor the energy-based device tier; Swiss and German pharmaceutical specialists hold positions in injectable biologics. The vendor base separates into three distinct tiers: multinational conglomerates with aesthetic divisions, dedicated laser equipment fabricators, and mid-scale biostimulatory filler developers. Strategic archetypes include vertically integrated device manufacturers, R&D-intensive biologics developers, and medical tourism service consolidators. Competitive moves concentrate on regulatory compliance investments and geographic expansion into Vietnam and Indonesia.
Within the multinational pharmaceutical tier, AbbVie and Galderma exemplify divergent strategic positioning. AbbVie's corporate structure incorporates aesthetic assets through its Allergan Aesthetics portfolio, while Galderma operates as a dedicated dermatology-focused entity. Among laser equipment specialists, Alma Lasers and Lumenis occupy positions reflecting Israeli manufacturing concentration serving Asia-Pacific distribution networks. Cynosure Lutronic represents the mid-scale specialist archetype competing on platform modularity.
| Leading Market Players |
|---|
| AbbVie |
| Galderma |
| Cynosure Lutronic |
| Johnson & Johnson |
| Alma Lasers |
| Cutera |
| Lumenis |
| Bausch Health Companies |
| Merz Pharma |
| Others |
Pricing and Supply Chain Analysis
Picosecond laser platform certification under MFDS rules is compressing procurement timelines for Thai and South Korean clinics while concentrating vendor pricing power among Israeli manufacturers with compliant registration dossiers. This regulatory-driven equipment transition simultaneously elevates capital requirements for clinic operators and tightens supply alternatives for energy-based devices across Bangkok's Sukhumvit corridor and Seoul's Gangnam district.
Pricing Analysis
Volume concentration in outpatient injectables generates recurring revenue streams with minimal capital drag, while laser surgery segments command premium positioning offset by seven-figure equipment amortization. Pricing stratifies across MFDS-certified, TGA-registered, and non-compliant equipment tiers with certification grade as the primary differentiation driver. Cost compression in independent clinic networks is intensifying because subscription-based membership models are displacing per-procedure fees among Middle Eastern medical tourists. Domestic patients in Vietnam and Indonesia exhibit highest price sensitivity, while JCI-accredited hospital networks serving Gulf state visitors maintain lowest sensitivity due to bundled accommodation-treatment logistics.
Supply Chain Analysis
Device refurbishment flows from Seoul's replacement-cycle upgrades are extending operational life for fractional laser platforms in Ho Chi Minh City and Jakarta clinic networks. Israeli manufacturing hubs anchor energy-based equipment sourcing, while Swiss and German pharmaceutical specialists feed injectable biologics pipelines. Supply chain risk centers on single-source vulnerability for picosecond laser components subject to MFDS registration delays. Distribution runs through master service agreements bundling compliance documentation, particularly for Australian clinic networks facing TGA quarterly reporting obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS tightened device registration rules has erected a compliance moat that favors capitalized incumbents with certified laser platforms while filtering marginal operators from Seoul and Bangkok procurement pipelines.
For Market Incumbents: Anchor market position through backward integration into biostimulatory filler R&D and exclusive distribution lock-ups with Israeli equipment manufacturers. Threat substitution by high-potency topical retinoids among under-35 demographics demands portfolio expansion beyond injectable maintenance cycles. Priority lever rests on single-vendor master service agreements that bundle TGA compliance documentation for Australian network expansion. For New Entrants and Emerging Players: Medical tourism service consolidators represent the most penetrable channel partner type for Vietnam and Indonesia market entry where accredited neurotoxin distribution remains undersupplied. White-space targets concentrate in teleconsultation-to-treatment pathway development for Jakarta and Ho Chi Minh City clinic networks. Go-to-market angle should emphasize NMPA provincial pilot program alignment for accelerated China market access. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays by multinational pharmaceutical conglomerates seeking aesthetic device capabilities. Long-term viability favors R&D-intensive biostimulatory filler developers with extended treatment interval portfolios over capital-heavy laser equipment fabricators. Signal to watch is TGA adverse event reporting burden escalation forcing Australian clinic network consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Investment | Creates protected market positions for compliant laser platform vendors across Seoul clinic networks. |
| Biostimulatory Filler R&D Expansion | Extends treatment intervals and locks recurring revenue streams for Galderma and AbbVie portfolios. |
| Teleconsultation Platform Development | Compresses patient acquisition costs for Bangkok operators targeting Middle Eastern medical tourists. |
| Master Service Agreement Consolidation | Bundles TGA compliance documentation for Australian clinic networks facing quarterly reporting. |
| NMPA Pilot Program Alignment | Accelerates market entry for South Korean manufacturers in Shanghai and Guangdong corridors. |
Research Methodology
Regulatory filing databases, hospital procurement records, and medical device registration dossiers formed the secondary backbone for this analysis. Primary interviews with clinic operators, biomedical equipment procurement managers, and dermatology chain executives combined with secondary validation across MFDS, TGA, and NMPA approval timelines. Bottom-up and top-down triangulation reconciled procedure volume estimates with capital expenditure patterns across Seoul, Bangkok, and Sydney metropolitan networks.
Bottom-up modeling anchored volume projections to clinic network expansion rates and equipment replacement cycles, while top-down validation cross-checked against pharmaceutical import data and medical tourism arrival statistics. Segmentation dimensions spanned procedure type, technology platform, end-user demographic, and service delivery model. CAGRs derived from equipment shipment trajectories and injectable unit sales patterns across the analysis window, with specific inputs from biostimulatory filler treatment interval extensions and laser platform compliance-driven procurement delays.
Caveats apply where MFDS registration timeline extensions or NMPA provincial pilot program suspensions could materially shift the outlook for equipment vendor market share. Forecasts reflect assumptions about medical tourism flow sustainability and currency fluctuation exposure for Israeli-manufactured device imports. Practitioners should monitor TGA adverse event reporting burden escalation and substitution rates by topical peptide formulations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market