
 Global Plastic Straps Market | 2026-2036
Global Plastic Straps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Straps Market Foresight
Asian petrochemical producers is pivoting toward higher-grade polymer feedstocks for strap manufacturing. Crown Holdings leverages its beverage packaging infrastructure to backward-integrate into captive strap production for can shipments. Teufelberger sustains Alpine European dominance through specialized high-tenacity polyester lines. Signode Industrial Group LLC competes on automatic strapping machine bundling systems tied to steel and construction logistics.
Plastic straps are extruded polymer bands—typically polypropylene, polyester, or nylon—engineered with specific tensile strengths, elongation rates, and surface textures for load containment and unitization across supply chains. These straps function as primary securing elements in palletized distribution, with break strengths ranging from several hundred to over two thousand pounds depending on material grade and width. Polypropylene straps occupy the volume-dominant position in light-duty bundling and retail packaging applications where cost sensitivity prevails over ultimate strength. Polyester straps represent the fastest-expanding structural category, displacing steel in heavy manufacturing and construction logistics due to superior weather resistance and reduced cargo damage. The technology dimension shows machine-welded systems capturing margin pools as warehouse automation penetrates third-party logistics and e-commerce fulfillment centers.
The US EPA regulates volatile organic compound emissions from strap extrusion processes, while REACH in Europe restricts phthalate plasticizers and mandates substance-of-concern disclosures across polymer supply chains. China's SAMR enforces GB standards for packaging material safety in food-contact and industrial transport applications, creating compliance-driven product differentiation. Japan's METI promotes recycled content targets that reshape virgin resin sourcing strategies for strap producers serving automotive export lanes. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and North America that will increasingly tie strap recyclability to market access permissions.
Market Dynamics
Warehouse automation across third-party logistics networks is compressing demand cycles for machine-compatible polyester strapping, forcing extruders to retool for welded-seam compatibility while virgin resin costs oscillate with petrochemical feedstock volatility.
Growth Catalysts
- China's SAMR packaging safety protocols:GB standards enforcement for food-contact and industrial transport applications creates compliance-driven demand for certified strap grades.
- E-commerce fulfillment center expansion:Automated palletizing operations in Asia-Pacific logistics hubs accelerate consumption of machine-welded polyester straps.
- Automotive component export logistics:Germany's industrial belt generates concentrated demand for high-tensile strapping in containerized outbound freight.
Market Restraints
- Propylene feedstock volatility:Polypropylene strap margins compress when naphtha-cracker output fluctuates with regional refinery maintenance cycles.
- Steel strap substitution persistence:Heavy manufacturing segments in Eastern Europe retain steel for extreme-load applications where polyester elongation rates exceed tolerance thresholds.
- REACH substance disclosure burdens:ECHA mandates for phthalate plasticizer documentation add administrative overhead across polymer supply chains.
Strategic Opportunities
- India's warehouse automation lag:Third-party logistics penetration remains below saturation in tier-2 manufacturing corridors, creating first-mover positioning for machine-strap suppliers.
- Recycled-content mandates:Japan's METI targets for post-consumer resin integration reshape virgin sourcing strategies for automotive export lane suppliers.
- RFID-strap convergence:Embedding track-and-trace chips during extrusion opens unitization-to-visibility service bundles for pharmaceutical cold chains.
Industry Challenges
- Welding technician scarcity:Automated strapping machine maintenance requires electro-mechanical skills that vocational pipelines in Central European logistics markets fail to replenish.
- Dual certification timelines:Simultaneous EU REACH and China NMPA compliance documentation extends product launch cycles by 8-14 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Straps Market |
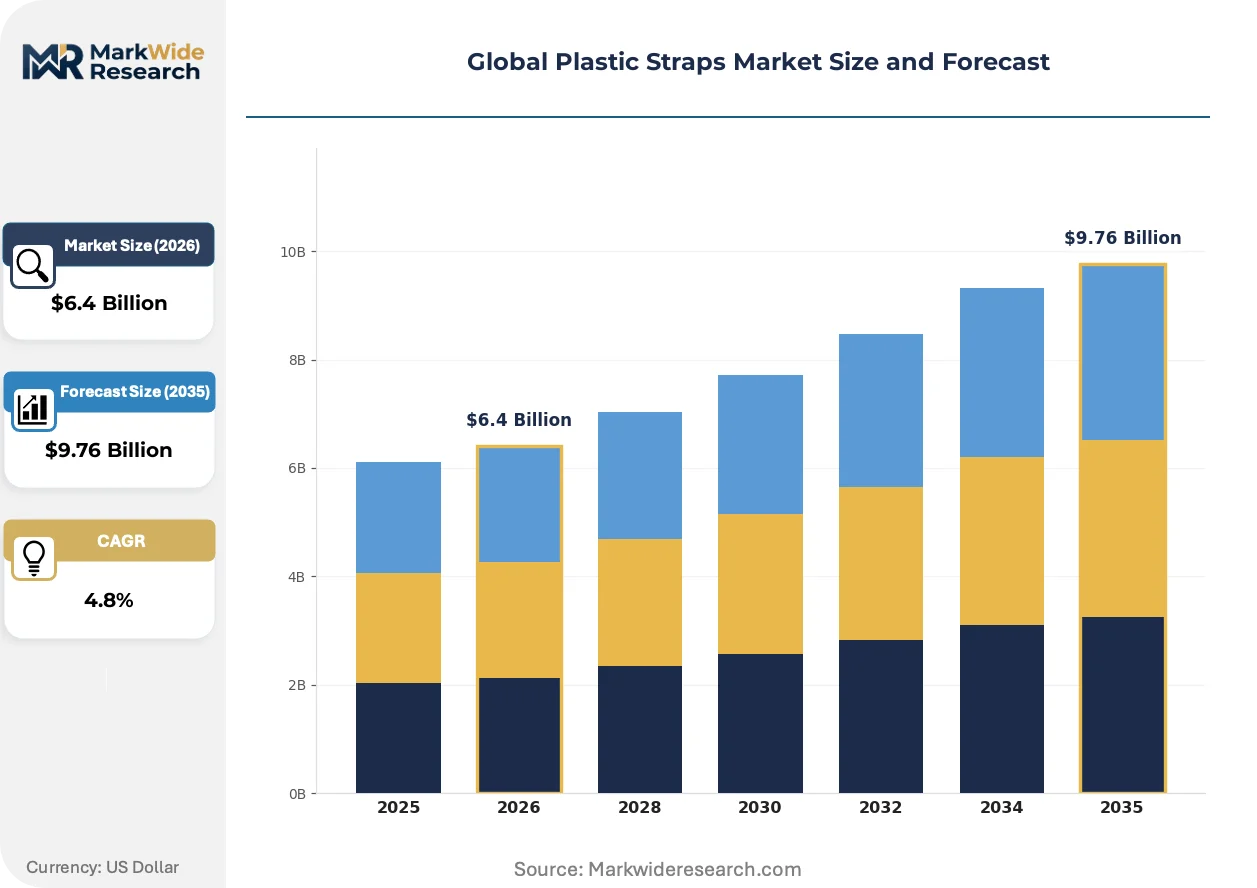
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Nylon, PVC Application: Palletizing, Bundling, Packaging, Securing End User: Manufacturing, Logistics, Retail, Construction Technology: Manual, Semi-Automatic, Automatic, Machine-Welded |
| Companies Covered | Crown Holdings, Teufelberger, Fromm Packaging Systems, Messersì Packaging, Polychem Corporation, Signode Industrial Group LLC, Dubose Strapping, PAC Strapping Products, Mosca GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Straps Market Shifts & Advancements
Extrusion technology and regulatory chemistry are converging to redefine material specifications, while procurement patterns in heavy logistics compress supplier qualification cycles.
Co-extruded polyester-nylon hybrid strapping is unifying tensile strength with weather resistance in a single material specification. Port logistics operators in Rotterdam and Hamburg adopt these grades for containerized export lanes exposed to salt-air corrosion. This unification is compressing the traditional segmentation between steel-replacement polyester and light-duty polypropylene into a mid-tier structural category.
REACH restrictions on phthalate plasticizers force reformulation of flexible strap grades across European supply chains. Compounders must substitute bio-based plasticizers or alternative polymer architectures to maintain elongation performance. Automotive component exporters in Stuttgart and Wolfsburg face the steepest compliance costs, driving backward integration into captive compounding operations.
Consolidated procurement desks at multinational third-party logistics providers now bundle strapping contracts with stretch film and corner board purchasing. This disintermediates regional distributors who previously managed SKU fragmentation across warehouse networks. The compression is most visible in Benelux and Northern France, where DHL Supply Chain and Kuehne+Nagel have centralized packaging spend under category managers.
Global Plastic Straps Market Segmentation
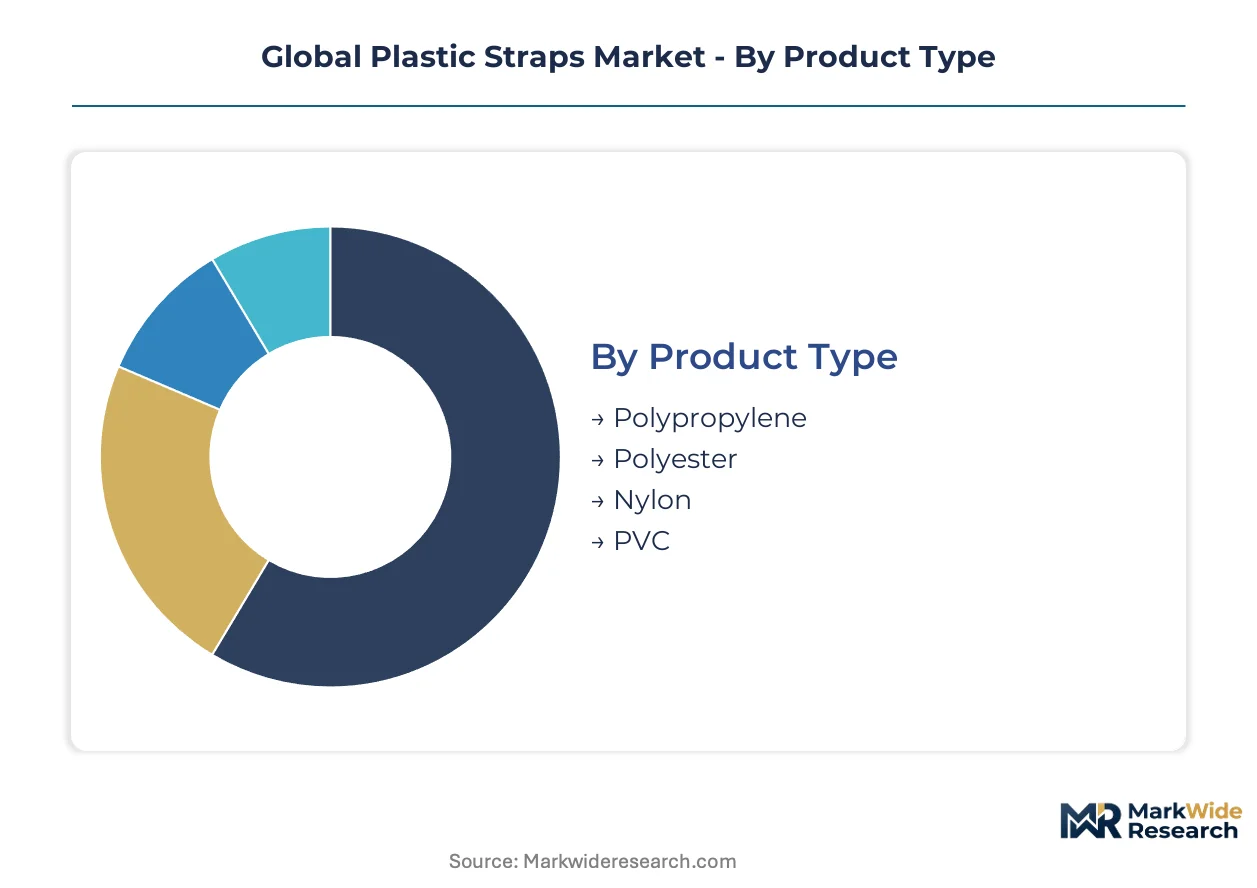
Material selection and welding technology determine unit economics across plastic strap procurement. Segmentation reveals where polyester displaces legacy materials and which automation tiers command premium positioning in logistics contracts.
Product Type:
Extrusion capacity concentrates among petrochemical-integrated producers with backward control over resin feedstocks.
- Polypropylene:Lower-density polymer with 300-600 lb break strength dominates light-duty bundling. Demand clusters in China's retail packaging corridors where SAMR enforces GB standards for food-contact safety.
- Polyester:High-tenacity PET formulations deliver 1,200-2,000 lb tensile capacity with minimal creep under load. Germany's automotive exporters in Stuttgart and Wolfsburg specify these grades for containerized outbound freight to withstand salt-air exposure.
- Nylon:Superior elongation recovery suits shock-load applications in construction material handling. Japanese METI recycled-content targets reshape virgin sourcing for automotive lane suppliers.
- PVC:Legacy specification retained in corrosion-sensitive chemical logistics where flexibility tolerance exceeds strength requirements.
Today's leader: Polyester. Tomorrow's challenger: Nylon hybrid formulations.
Application:
End-use intensity varies directly with load value and damage liability exposure in transit.
- Palletizing:Unitization of stacked goods for forklift handling requires 1,000+ lb break strength. Rotterdam and Hamburg port operators specify co-extruded grades for salt-air containerized export lanes.
- Bundling:Aggregation of discrete items into handling units uses lighter 400-800 lb straps. E-commerce fulfillment centers in China's Yangtze River Delta compress procurement cycles for machine-compatible grades.
- Packaging:Primary containment for consumer goods emphasizes printability and hand-tool compatibility. REACH phthalate restrictions force European compounders into bio-based plasticizer reformulation.
- Securing:Load restraint during transport demands weather-resistant specifications for flatbed and intermodal applications.
Palletizing commands the highest per-meter pricing. Bundling offers the steepest volume expansion trajectory.
End User:
Procurement sophistication separates centralized category management from fragmented spot purchasing.
- Manufacturing:Heavy industrial users in Germany's industrial belt require certified high-tensile grades with batch traceability for automotive component exports.
- Logistics:Third-party providers in Benelux and Northern France consolidate strapping with stretch film under category managers, disintermediating regional distributors.
- Retail:Cost-sensitive volume buyers in India's tier-2 corridors lag in warehouse automation penetration.
- Construction:Eastern European heavy manufacturing retains steel for extreme-load applications where polyester elongation exceeds tolerance thresholds.
Logistics leads in contract value. Manufacturing drives specification intensity.
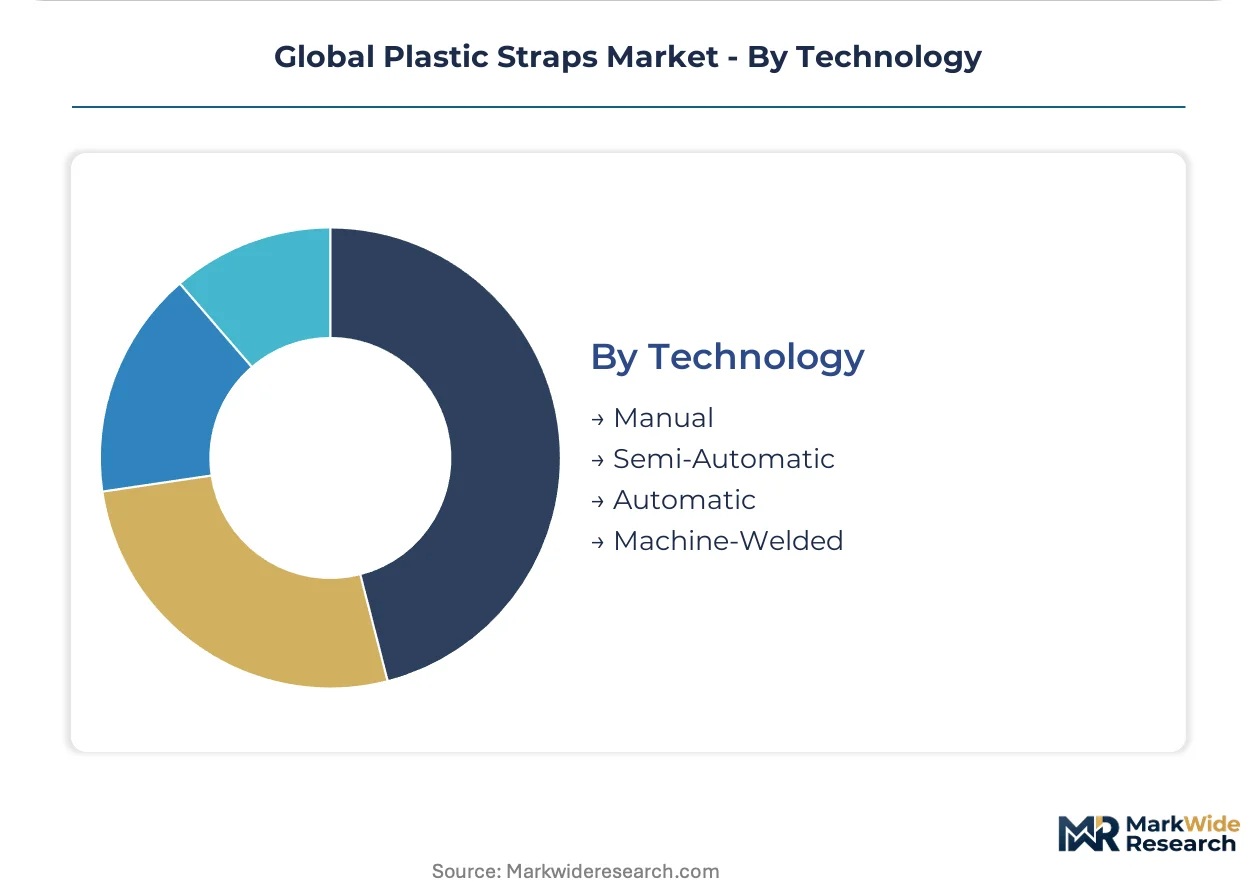
Technology:
Welding method determines labor input, seam reliability, and total applied cost per load unit.
- Manual:Hand-tool tensioning and metal-seal crimping suits low-volume operations with irregular load profiles.
- Semi-Automatic:Table-mounted machines with operator-fed strap reduce cycle times for mid-tier distribution centers.
- Automatic:Arch-type machines with conveyor integration serve high-throughput palletizing lines in Asia-Pacific e-commerce hubs.
- Machine-Welded:Friction-weld or heat-seal systems eliminate metal seals for cost and contamination reduction. Technician scarcity in Central European logistics markets constrains maintenance capacity for these systems.
Machine-Welded captures margin expansion. Automatic delivers volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as extruders migrate toward jurisdictions with streamlined chemical compliance frameworks and lower documentation burdens for polymer formulations.
China
Machine-welded polyester strap demand accelerates in Yangtze River Delta e-commerce fulfillment centers where automated palletizing lines dominate. SAMR enforces GB standards for food-contact packaging safety, forcing compounders into certified resin sourcing. Qingdao and Ningbo port clusters concentrate export-oriented production for containerized automotive components.
Germany
Automotive component exporters in Stuttgart and Wolfsburg specify high-tenacity polyester grades for salt-air containerized freight to overseas markets. ECHA REACH mandates restrict phthalate plasticizers and mandate substance-of-concern disclosures across polymer supply chains. The industrial belt around Baden-Württemberg anchors specification-intensive procurement for outbound logistics.
United States
Third-party logistics networks compress procurement cycles for machine-compatible strapping as warehouse automation penetrates distribution centers. EPA regulations govern volatile organic compound emissions from extrusion processes, particularly in Texas and Ohio petrochemical corridors. Chicago and Atlanta logistics hubs concentrate category-managed packaging spend under consolidated procurement desks.
Japan
METI recycled-content targets reshape virgin resin sourcing strategies for strap producers serving automotive export lanes. PMDA-aligned material safety protocols govern polymer formulations for pharmaceutical and food-contact applications. Nagoya and Osaka industrial zones sustain demand for high-tenacity grades with batch traceability requirements.
India
Tier-2 manufacturing corridors lag in warehouse automation penetration, creating positioning opportunities for machine-strap suppliers as third-party logistics expands. BIS standards enforcement for industrial packaging materials accelerates compliance-driven product differentiation. Gujarat and Maharashtra industrial clusters concentrate light-duty polypropylene demand for retail packaging applications.
Global Plastic Straps Market Competitive Landscape
European producers anchor the specification-intensive tier; Asia-Pacific fabricators hold volume-scale positioning. The vendor base stratifies across three tiers: petrochemical-integrated extruders with captive resin supply, specialized high-tenacity polyester manufacturers, and regional distributors disintermediated by consolidated procurement desks. Two competitive moves dominate: backward integration into polymer compounding operations and geographic expansion through distribution partnerships in underpenetrated logistics corridors.
Within the integrated packaging conglomerate tier, Crown Holdings exemplifies backward integration strategy by leveraging beverage infrastructure into captive strap production. Teufelberger and Signode Industrial Group LLC occupy distinct positioning archetypes—Alpine European specialization versus automatic strapping machine system bundling. These three anchors illustrate how geographic origin and corporate structure shape competitive approach without guaranteeing segment dominance.
| Leading Market Players |
|---|
| Crown Holdings |
| Teufelberger |
| Fromm Packaging Systems |
| Messersì Packaging |
| Polychem Corporation |
| Signode Industrial Group LLC |
| Dubose Strapping |
| PAC Strapping Products |
| Mosca GmbH |
| Others |
Supply & Pricing Matrix
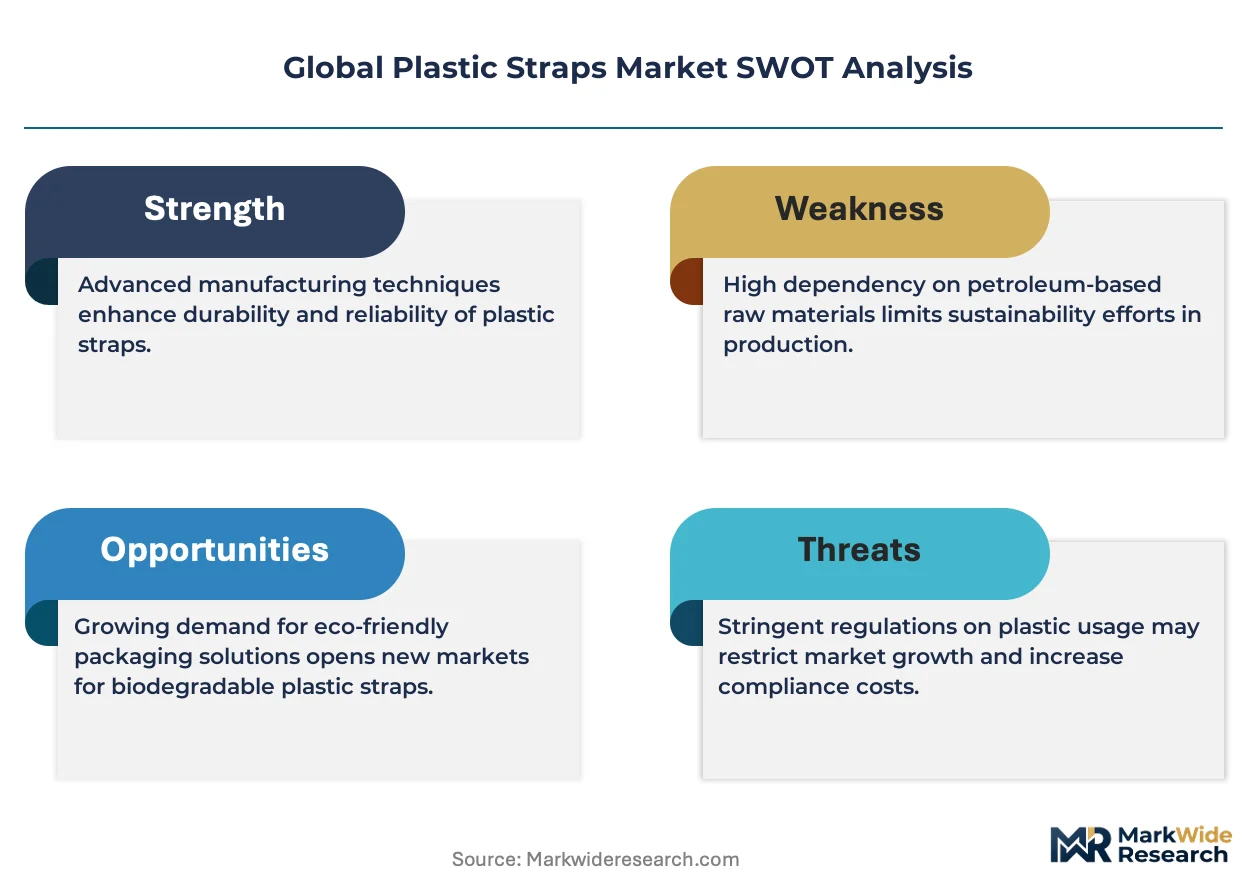
Electro-mechanical welding technician scarcity in Central European logistics markets widens labor-cost differentials between machine-welded premium tiers and hand-tool economy grades. This workforce compression feeds directly into pricing-tier spreads as automated strapping systems command maintenance premiums.
Pricing Analysis
Distributor margin capture concentrates in semi-automatic machine tiers where regional distributors retain pricing power before consolidated procurement desks disintermediate. Three-tier pricing structure across premium certified grades, standard industrial specifications, and economy polypropylene levels separates automotive exporters from retail packaging buyers. Cost compression in standard polyester grades is intensifying because petrochemical feedstock volatility compresses compounder margins. Logistics providers with category-managed contracts show least price sensitivity; India's tier-2 retail corridors exhibit highest.
Supply Chain Analysis
Certification gating through EU REACH substance disclosures and China SAMR GB standards enforcement fragments supplier qualification timelines. Extrusion capacity concentrates in Germany, China, and the United States where petrochemical-integrated producers control resin feedstocks. Raw material sourcing draws from naphtha-cracker output, virgin PET resin, and post-consumer recycled flake streams. Single-source vulnerability runs through Asian petrochemical corridors exposed to refinery maintenance cycles. Distribution runs through multinational third-party logistics procurement desks consolidating packaging spend.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive component exporters and pharmaceutical cold chains shift demand toward certified high-tenacity specifications with batch traceability.
For Market Incumbents: Cement specification-intensive positioning in Germany's automotive belt through captive compounding investments that offset REACH plasticizer reformulation costs. Deepen channel control via direct service contracts with DHL Supply Chain and Kuehne+Nagel procurement desks to neutralize distributor disintermediation. For New Entrants and Emerging Players: Enter via India's tier-2 manufacturing corridors where warehouse automation penetration remains below saturation and BIS standards enforcement creates compliance-driven differentiation. Target machine-strap supply partnerships with expanding third-party logistics networks in Gujarat and Maharashtra industrial clusters. For Investors and Strategic Acquirers: Packaging conglomerates with beverage and industrial logistics footprints are the most active acquirers in this space, seeking backward integration into captive strap production. Five-to-ten year viability hinges on recycled-content compliance capabilities. Signal to monitor: Japan METI recycled resin mandate expansion into automotive export lanes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Crown Holdings leverages beverage infrastructure to capture margin pools in can shipment logistics. |
| Machine-Welded System Bundling | Signode Industrial Group ties automatic strapping equipment to steel and construction sector contracts. |
| Co-extruded Hybrid Grade Development | Rotterdam and Hamburg port operators adopt polyester-nylon unification for salt-air containerized lanes. |
| RFID-Embedded Strap Convergence | Pharmaceutical cold chain visibility bundles open unitization-to-traceability service expansion. |
| Recycled-Content Certification Investment | Japan METI targets reshape virgin resin sourcing for automotive export lane suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included plant managers at extrusion facilities, procurement leads at automotive OEMs and third-party logistics providers, distribution channel partners, and technical R&D directors at compounders. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR GB standards documentation. Bottom-up resin consumption models and top-down logistics spend estimates were triangulated.
Comparable-period anchoring linked forward projections to historical automotive export volumes and e-commerce fulfillment center buildout rates. Segmentation modeling spanned material grade tier, welding technology, end-use intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and petrochemical feedstock cost trajectories. Forecast inputs included machine-welded system penetration rates and REACH compliance timeline assumptions.
Inputs from extruder production disclosures and logistics procurement databases were available through the study window; gaps in tier-2 corridor automation spend introduce uncertainty bands. Forecasts reflect documented assumptions on resin price volatility and regulatory enforcement intensity. Deviation in China SAMR packaging safety protocol expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Plastic Liners Market