
 Packaging Industry in South Africa Market | 2026-2036
Packaging Industry in South Africa Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Industry in South Africa Market Analytics
ISO 22000 certification for food-contact packaging safety is rotating as the primary gatekeeping standard for supplier qualification among South African retailers. Nampak Limited leverages its integrated beverage can and glass operations to sustain supply security for major brewers. Mpact Limited anchors the corrugated segment through containerboard recycling infrastructure that dominates industrial logistics channels.
The packaging industry in South Africa encompasses the design, manufacture, and supply of protective and promotional enclosures using materials such as polyethylene terephthalate, aluminum, and kraft linerboard, typically formed through injection molding, thermoforming, or blown-film extrusion processes to preserve product integrity across distribution chains. Flexible packaging leads volume contribution due to its lightweight properties and cost efficiency in snack and fresh-produce applications, while rigid containers command premium margins in pharmaceutical and personal care segments where barrier performance and child-resistance specifications justify higher unit economics. Paperboard packaging occupies a mature growth trajectory as retail-ready display formats face substitution pressure from plastic reduction mandates.
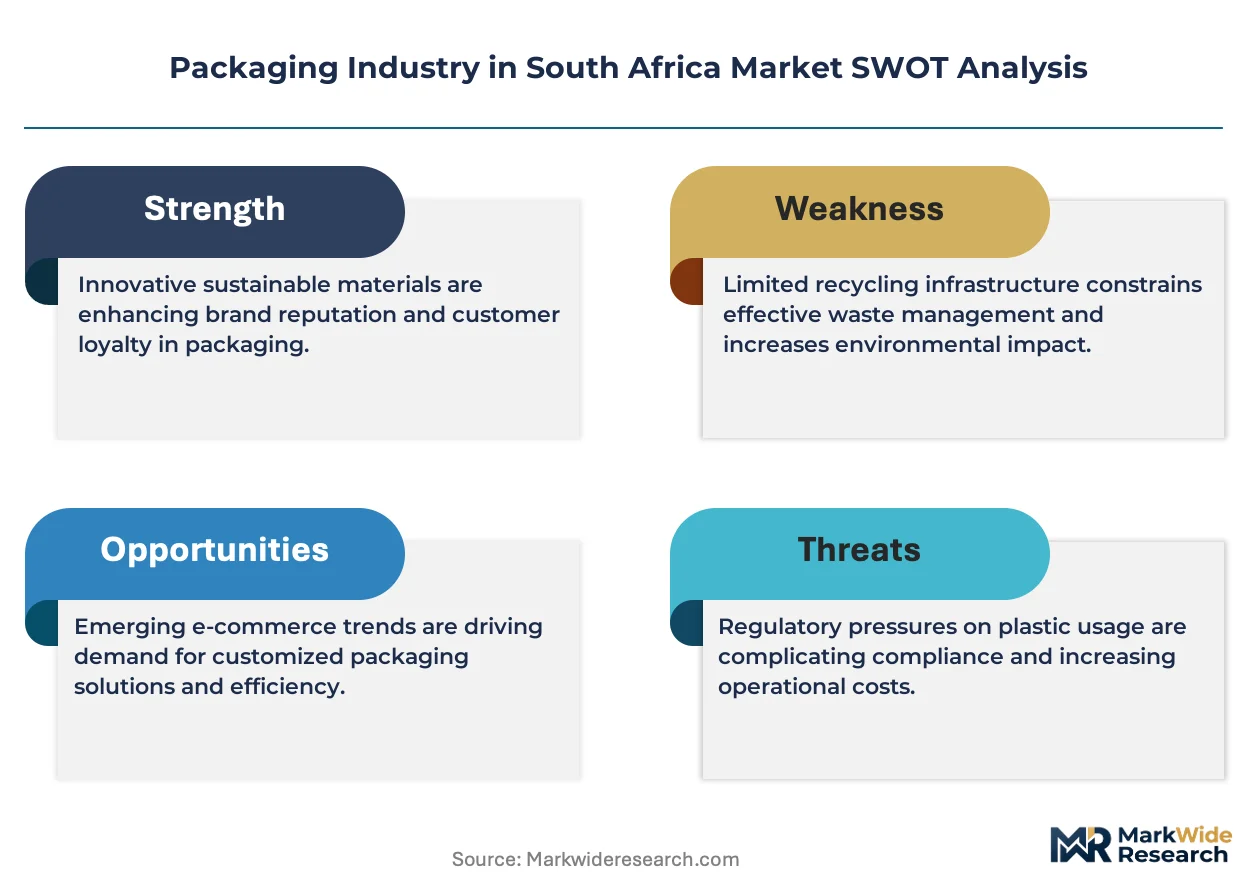
The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that compel brand owners to fund collection and recycling infrastructure, while the South African Bureau of Standards maintains compulsory specifications for food-contact materials under SANS 10330. The National Regulator for Compulsory Specifications governs safety-critical packaging for hazardous chemicals and pressure vessels, creating compliance cost barriers for smaller converters. Stakeholders must monitor evolving biodegradable labeling requirements and recyclate content thresholds that will determine which material technologies retain shelf access in major retail chains.
Market Dynamics
South Africa's extended producer responsibility regulations under the National Environmental Management Waste Act are forcing converters to internalize end-of-life collection costs, compressing margins for single-use plastic formats while redirecting capital toward mechanical recycling infrastructure.
Growth Catalysts
- EPR Compliance Deadlines:Brand owners must fund recycling infrastructure per Department of Forestry, Fisheries and the Environment mandates, creating guaranteed offtake for post-consumer recyclate processors.
- Flexible Packaging Demand:Snack and fresh-produce applications favor lightweight polyethylene terephthalate films for distribution efficiency across Gauteng retail corridors.
- Gauteng Cluster Density:Johannesburg-based converters co-locate near major distribution hubs, reducing logistics costs for beverage and food manufacturers.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin prices track import parity against dollar-denominated crude derivatives, squeezing converter margins unpredictably.
- Collection Infrastructure Gaps:Informal waste picker networks dominate post-consumer recovery, limiting supply security for food-grade recyclate streams.
- Biodegradable Labeling Uncertainty:Absence of unified SANS standards for compostable claims creates liability exposure for converters marketing alternative materials.
Strategic Opportunities
- Western Cape Wine Exports:Premium glass and lightweight corrugated formats for international shipping present margin expansion beyond domestic retail cycles.
- Pharmaceutical Barrier Migration:Cyclic olefin copolymer and multilayer coextrusion technologies address child-resistance specifications in private-label healthcare packaging.
- Retail-Ready Display Formats:Paperboard substitution for shrink-wrapped pallets aligns with major supermarket chains' plastic reduction commitments.
Industry Challenges
- ISO 22000 Certification Bottlenecks:Food-contact safety auditing capacity constraints delay supplier qualification timelines for emerging converters.
- Mechanical Recycling Retrofit Costs:Legacy extrusion lines require capital-intensive modifications to process contaminated post-consumer feedstock at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Industry in South Africa Market |
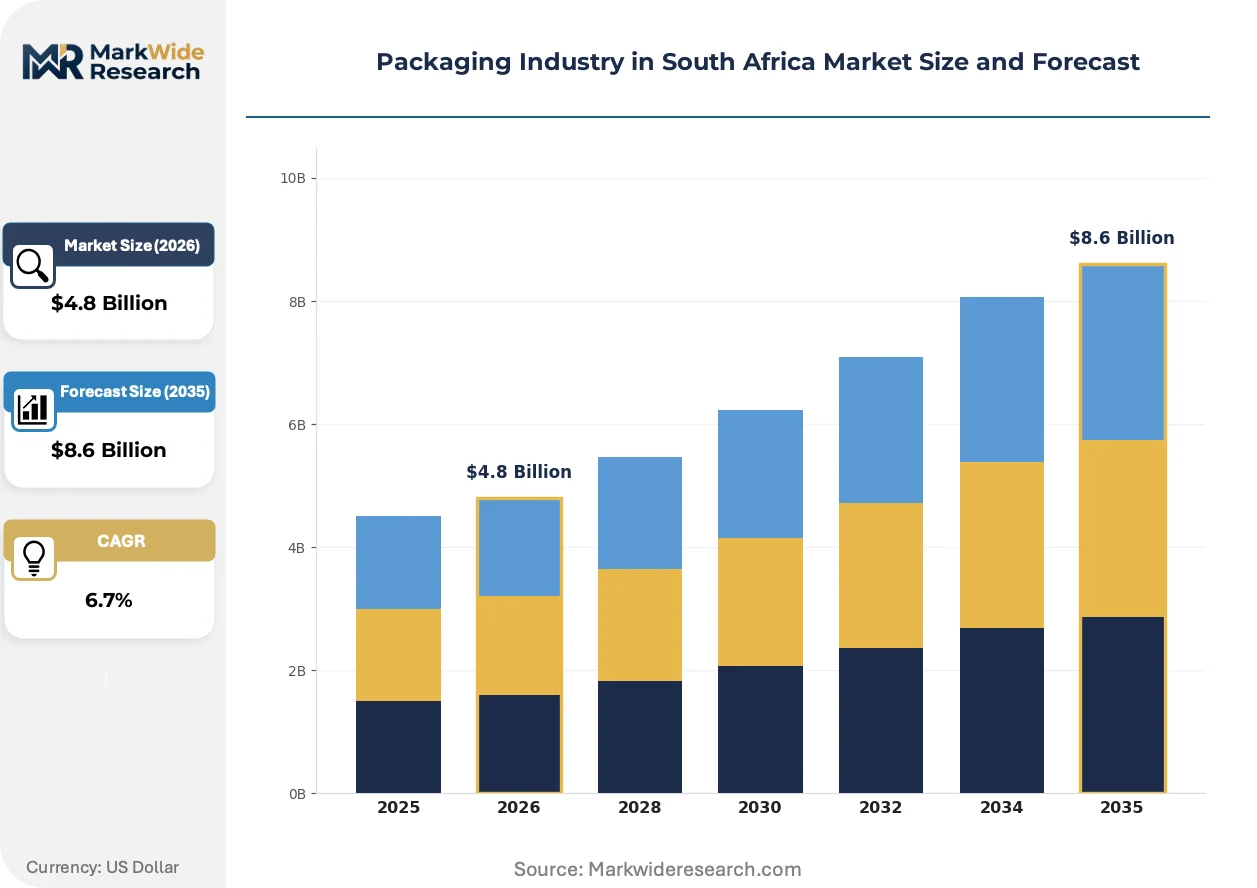
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Paperboard Packaging, Glass Packaging Material: Plastic, Metal, Wood, Paper End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Packaging Type: Single-use, Reusable, Bulk Packaging, Specialty Containers |
| Companies Covered | Nampak Limited, Mpact Limited, Mondi plc, Consol Glass (Pty) Ltd., Smurfit Kappa Group plc, Constantia Flexibles GmbH, Astrapak, Polyoak Packaging Group, Bidvest Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Industry in South Africa Market Evolving Landscape
Material substitution and regulatory compliance are converging to reshape converter technology roadmaps, with sustainability specifications now embedded in retail procurement criteria rather than treated as premium add-ons.
Monolayer polyethylene films with enhanced barrier coatings are supplanting multilayer laminated structures in snack packaging applications. Major retail chains are accelerating qualification timelines for these separable formats to meet recyclate content thresholds. This transition is compressing demand for adhesive lamination equipment while expanding blown-film extrusion capacity.
The National Environmental Management Waste Act's extended producer responsibility framework now mandates audited mass-balance reporting for packaging producers above volume thresholds. Brand owners face penalty structures for non-compliance that escalate with delay. Food and beverage manufacturers are responding by consolidating supplier bases toward converters with integrated recycling partnerships.
Centralized procurement teams at major retailers are imposing standardized sustainability scorecards that weight recyclability above unit cost in supplier selection. Long-standing relationships with family-owned converters are losing share to tier-one suppliers with certified circularity documentation. This behavioral shift is most pronounced in Gauteng province, where retailer headquarters proximity enables direct compliance auditing.
Packaging Industry in South Africa Market Segmentation
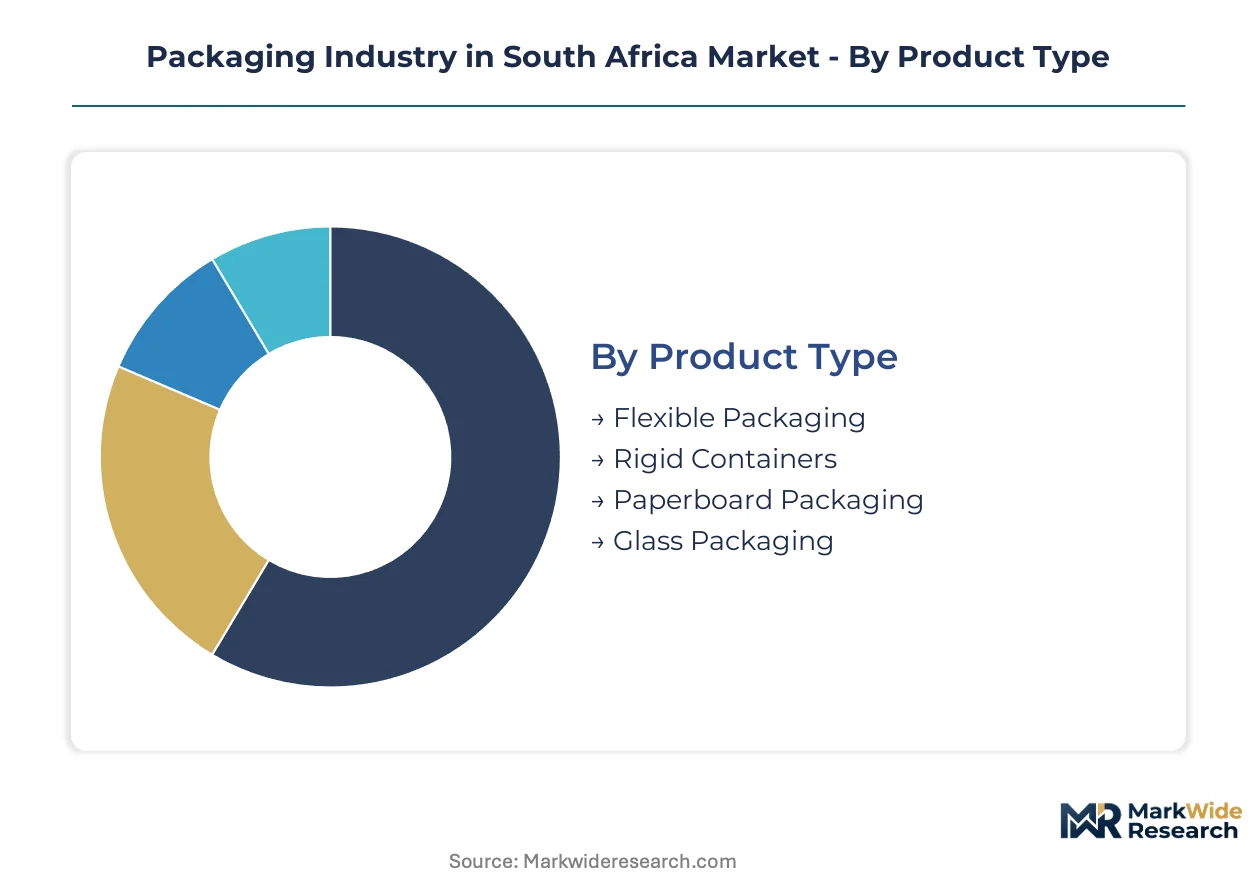
Segmentation reveals how South African converters allocate capital across material technologies and end-use specifications. Understanding these divides exposes where EPR compliance costs and retail procurement shifts concentrate competitive advantage.
Product Type:
Margins compress most severely in commodity formats burdened by extended producer responsibility fees, while premium barrier technologies retain pricing power.
- Flexible Packaging:Polyethylene terephthalate and polypropylene films formed through blown-film extrusion dominate snack and fresh-produce applications. Gauteng retail corridors drive volume concentration as lightweight formats reduce distribution costs for major supermarket chains facing plastic reduction mandates.
- Rigid Containers:Injection-molded polyethylene and polypropylene vessels serve pharmaceutical and personal care segments where child-resistance specifications justify premium unit economics. Demand clusters around Johannesburg-based healthcare product manufacturers requiring ISO 22000 certified supply security.
- Paperboard Packaging:Kraft linerboard and folding carton formats face substitution pressure from plastic reduction commitments despite retail-ready display advantages.
- Glass Packaging:Soda-lime containers retain dominance in premium beverage exports through Western Cape wine corridors.
The dominant share belongs to Flexible Packaging, while Rigid Containers is closing the gap fastest.
Material:
Feedstock cost volatility tracks differently across material classes, with import-parity resin pricing squeezing plastic converters while recycled fiber offers partial insulation.
- Plastic:Polypropylene, polyethylene, and polyethylene terephthalate resins constitute the volume foundation, processed through injection molding, thermoforming, and blown-film extrusion. Nampak Limited and Mpact Limited anchor domestic polymer conversion capacity near Gauteng distribution hubs.
- Metal:Aluminum beverage cans and tinplate aerosol containers serve brewers and household product manufacturers with established collection infrastructure for post-consumer recyclate.
- Wood:Pallet and crate formats support industrial logistics through treated pine and hardwood specifications for export compliance.
- Paper:Containerboard and kraft grades dominate corrugated shipping containers, with Mpact Limited's recycling infrastructure capturing industrial waste streams.
Plastic commands the largest volume position, though Metal is gaining share through beverage can lightweighting investments.
End User:
Regulatory scrutiny intensity varies sharply across end-use categories, with food-contact specifications demanding certified safety management systems.
- Food & Beverage:The largest demand pool spans fresh produce, processed foods, and alcoholic beverages. Department of Forestry, Fisheries and the Environment mandates force brand owners to fund collection infrastructure, consolidating procurement toward converters with mass-balance certification.
- Pharmaceuticals:Cyclic olefin copolymer and multilayer barrier technologies address moisture and oxygen sensitivity for generic drug manufacturers. South African Bureau of Standards specifications under SANS 10330 govern material compliance.
- Personal Care:Premium cosmetic packaging favors glass and rigid plastic formats with decorative finishing capabilities.
- Household Products:Concentrated detergents and cleaning chemicals drive demand for chemical-resistant HDPE containers with child-resistant closures.
Food & Beverage holds the dominant position, while Pharmaceuticals is expanding most quickly through private-label healthcare growth.
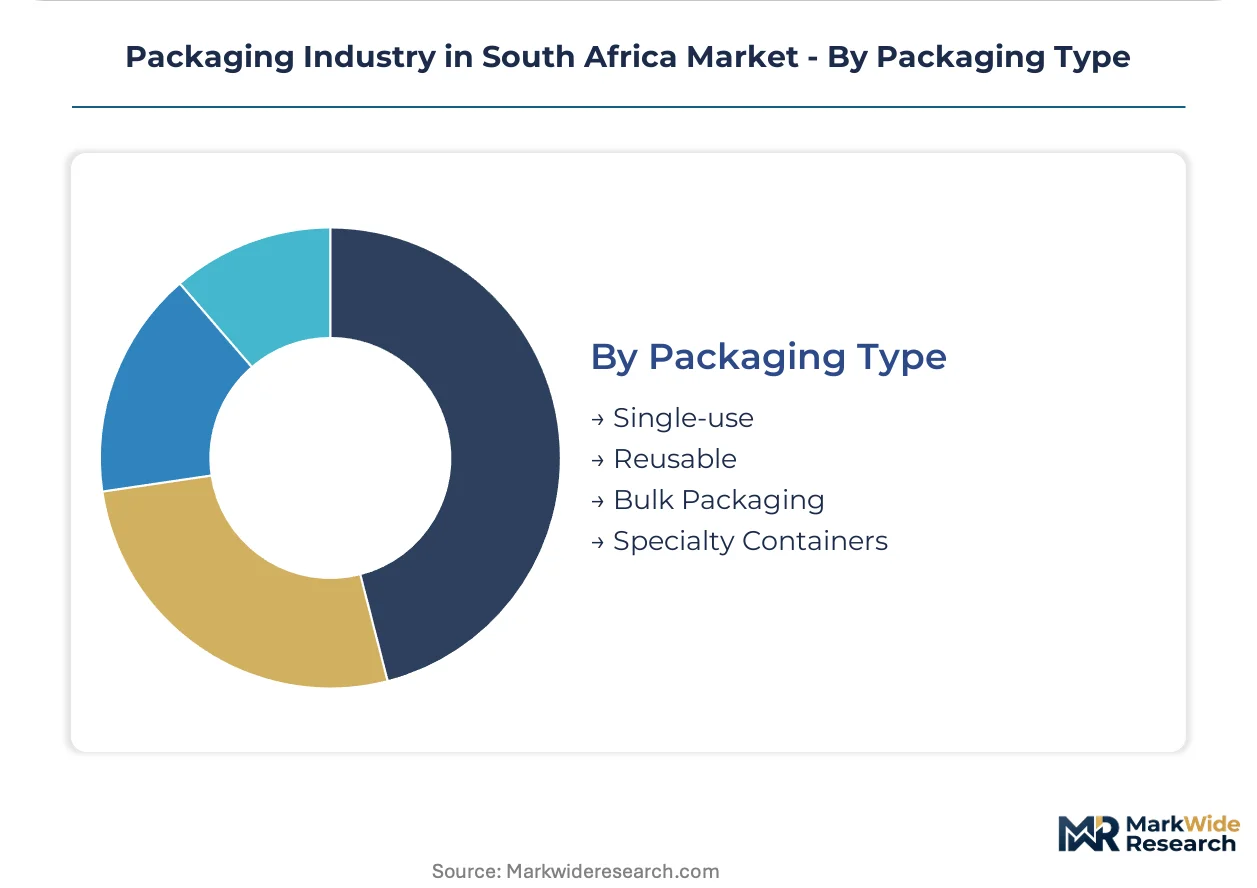
Packaging Type:
Reusable format economics are improving as EPR penalties on single-use alternatives narrow the total-cost gap.
- Single-use:Conventional disposable formats face margin compression from EPR funding obligations and biodegradable labeling uncertainty under evolving SANS standards.
- Reusable:Returnable glass bottle systems and collapsible intermediate bulk containers serve closed-loop beverage and chemical distribution networks.
- Bulk Packaging:Flexible intermediate bulk containers and drum formats support agricultural and mining chemical logistics through Western Cape and Mpumalanga industrial corridors.
- Specialty Containers:Aseptic and modified-atmosphere formats preserve shelf stability for premium food exports requiring extended distribution timelines.
Single-use retains the largest share, though Reusable formats are climbing the fastest as retail chains consolidate supplier bases toward circularity-certified partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging procurement concentrates around food and beverage manufacturers, pharmaceutical distributors, and retail chains seeking ISO 22000 certified supply security. Gauteng province anchors domestic demand through Johannesburg-based converter clusters. Extended producer responsibility mandates reshape capital allocation across provincial industrial corridors.
Gauteng
Johannesburg-based converters cluster near retail distribution hubs serving major supermarket chains. The Department of Forestry, Fisheries and the Environment enforces EPR funding obligations that compress margins for single-use plastic formats. Pretoria-Tshwane industrial zones host mechanical recycling retrofits capturing post-consumer polyethylene terephthalate streams.
Western Cape
Premium wine exports drive demand for lightweight glass and corrugated shipping formats through Cape Town port corridors. The South African Bureau of Standards governs food-contact specifications under SANS 10330 for export compliance. Stellenbosch-Paarl packaging corridors specialize in aseptic and modified-atmosphere technologies for extended shelf stability.
KwaZulu-Natal
Durban port logistics anchor chemical and agricultural bulk packaging demand through flexible intermediate bulk container formats. The National Regulator for Compulsory Specifications oversees hazardous chemical packaging safety standards. Pinetown industrial zones concentrate injection-molded HDPE container production for household detergent manufacturers.
Eastern Cape
Automotive component supply chains generate specialty container demand for precision parts distribution through Gqeberha manufacturing corridors. Provincial environmental affairs departments coordinate with national EPR frameworks for industrial waste stream recovery. East London industrial development zones attract converters serving German OEM packaging specifications.
Mpumalanga
Mining chemical logistics drive bulk drum and intermediate bulk container demand through Witbank-Middelburg industrial corridors. The National Environmental Management Waste Act mandates audited mass-balance reporting for packaging producers above volume thresholds. Nelspruit-based converters serve agricultural chemical distribution networks with returnable format systems.
Packaging Industry in South Africa Market Competitive Landscape
Player mix skews toward integrated material converters with captive recycling infrastructure and specialized barrier technology specialists. Tier-one suppliers with certified circularity documentation consolidate procurement relationships as retail chains impose standardized sustainability scorecards. Two strategic archetypes dominate: integrated polymer-to-package operators leveraging backward control over resin supply, and specialized glass and metal fabricators serving premium beverage export corridors. Competitive moves concentrate on mechanical recycling capacity expansion and mass-balance certification acquisition to secure retail shelf access.
Among South Africa-based integrated converters, Nampak Limited and Mpact Limited exemplify the scale-driven archetype with beverage can, glass, and containerboard operations anchored near Gauteng distribution hubs. Constantia Flexibles GmbH represents the multinational specialist tier with flexible barrier technology capabilities. These three occupy positions within a supplier base where EPR compliance documentation and ISO 22000 certification increasingly determine procurement outcomes.
| Leading Market Players |
|---|
| Nampak Limited |
| Mpact Limited |
| Mondi plc |
| Consol Glass (Pty) Ltd. |
| Smurfit Kappa Group plc |
| Constantia Flexibles GmbH |
| Astrapak |
| Polyoak Packaging Group |
| Bidvest Packaging |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day resin inventory cycles anchor converter working capital requirements, concentrating pricing power among Johannesburg-based suppliers with backward-integrated polymer supply. Gauteng cluster density compresses logistics premiums while EPR compliance fees reshape total delivered cost structures across material tiers.
Pricing Analysis
Cost-plus contracts indexed to Platts polymer assessments dominate converter-procurement relationships, with monthly price adjustments tracking dollar-denominated polypropylene and polyethylene resin movements. Three-tier pricing structure across premium barrier-certified, standard food-contact, and economy industrial grades reflects ISO 22000 certification premiums. Pricing pressure stems from informal waste-picker collection inefficiencies that inflate post-consumer recyclate premiums. Brand owners exhibit lowest price sensitivity in pharmaceutical barrier segments, while snack and fresh-produce manufacturers face acute margin compression.
Supply Chain Analysis
Sixty-day raw material inventory cycles expose converters to petrochemical feedstock volatility, with Saudi Arabia, China, and South Korea supplying the bulk of virgin resin imports. Domestic conversion draws from polypropylene, polyethylene terephthalate, and kraft linerboard inputs. Single-source vulnerability concentrates in specialty cyclic olefin copolymer imports for pharmaceutical applications. Distribution runs through Johannesburg-based converter clusters serving Gauteng retail corridors, with Western Cape and KwaZulu-Natal secondary hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South African packaging market functions as a regulatory-moat industry where EPR compliance documentation and ISO 22000 certification create switching costs that entrench qualified suppliers. Extended producer responsibility mandates erect barriers that favor incumbents with audited mass-balance systems.
For Market Incumbents: Compound defensive positioning through mechanical recycling retrofit investments in Pretoria-Tshwane industrial zones. Acquire post-consumer collection partnerships to secure food-grade recyclate supply security. Threat substitution from monolayer barrier films demands accelerated qualification timelines for separable format portfolios.
For New Entrants and Emerging Players: Lead with Western Cape wine export corridors where premium glass and lightweight corrugated formats command margin expansion beyond domestic retail cycles. Target aseptic and modified-atmosphere technology gaps in Stellenbosch-Paarl packaging corridors. Go-to-market angle emphasizes SANS 10330 export compliance certification.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EPR compliance scale requirements will compress the supplier base toward tier-one converters with certified circularity documentation. Acquisition target archetype: mid-cap flexible film specialists with blown-film extrusion capacity and retail chain sustainability scorecard relationships. Signal to watch is mass-balance certification velocity among family-owned Gauteng converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Retrofit | Captures post-consumer polyethylene terephthalate streams for food-grade recyclate security. |
| Mass-Balance Certification Acquisition | Secures retail shelf access under Department of Forestry, Fisheries and the Environment mandates. |
| Western Cape Export Capacity Expansion | Serves premium wine corridor demand for lightweight glass and corrugated shipping formats. |
| ISO 22000 Certification Investment | Unlocks supplier qualification with major Johannesburg-based retail procurement teams. |
| Flexible Barrier Technology Partnership | Addresses pharmaceutical child-resistance specifications through cyclic olefin copolymer migration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement managers, converter operations directors, and retail sustainability leads; and secondary validation through customs trade records, Department of Forestry, Fisheries and the Environment regulatory filings, and South African Bureau of Standards specification documents. Bottom-up volume modeling triangulated against top-down industry association estimates.
Across the projection horizon, forecasts incorporated material segmentation by flexible, rigid, paperboard, and glass formats alongside end-use demand patterns in food-contact, pharmaceutical, and personal care applications. CAGRs derived from historical trajectory analysis adjusted for EPR implementation phasing and recyclate content threshold escalations. Feedstock cost modeling integrated Platts polymer price indices and rand-dollar exchange volatility assumptions.
The analysis sits within stated boundaries; outcomes outside current EPR enforcement intensity or major resin supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding collection infrastructure development and retail procurement consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market