
 Germany Plastic Packaging Market | 2026-2036
Germany Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Plastic Packaging Market Foresight
The EU Packaging and Packaging Waste Regulation is restructuring procurement criteria across German consumer goods supply chains. Gerresheimer AG leverages its pharmaceutical glass and plastic hybrid expertise to sustain premium positioning in drug delivery formats. Constantia Flexibles Group anchors flexible film supply for dairy and processed meat segments. Klöckner Pentaplast GmbH specializes in rigid PET sheet production for thermoformed trays serving discount retail channels.
Germany plastic packaging encompasses thermoformed, extruded, and molded polymer structures engineered to barrier specifications measured in oxygen transmission rates and moisture vapor transmission rates, serving containment, preservation, and logistics functions for consumer and industrial goods. Polyethylene Terephthalate dominates beverage bottle production due to established collection infrastructure and rPET feedstock availability. Bioplastics represent the fastest-expanding material category, though volume remains constrained by agricultural feedstock costs and industrial composting capacity gaps. Film and pouch formats capture growing share in e-commerce fulfillment applications where weight reduction directly reduces parcel shipping costs.
KBA and the German Environment Agency enforce extended producer responsibility frameworks that obligate brand owners to finance collection and recycling infrastructure, while REACH compliance governs chemical migration limits in food-contact materials. The EU Green Deal's binding recycled content targets for 2030 and 2035 are forcing converters to secure long-term rPET and rPP supply contracts or risk losing retail shelf placement. Stakeholders must monitor enforcement timelines for digital packaging passports and assess whether mechanical recycling investments or chemical recycling partnerships offer superior cost trajectories under evolving EPR fee structures.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter margins while mandating recycled content thresholds that force immediate supply chain reconfiguration across German rigid and flexible packaging segments.
Growth Catalysts
- Extended Producer Responsibility frameworks:KBA enforcement obligates brand owners to finance collection infrastructure, creating contracted demand for rPET and rPP processing capacity.
- Lightweighting in beverage formats:Food and beverage manufacturers are expanding PET bottle gauge reduction programs to cut resin consumption per unit.
- Bavaria's industrial corridor concentration:Automotive and chemical packaging demand clusters around Munich and Nuremberg, generating scale economies for regional converters.
Market Restraints
- Agricultural feedstock cost volatility:Bioplastic resin prices track wheat and corn markets, constraining PLA and starch-blend adoption in price-sensitive dairy segments.
- rPET supply concentration:Post-consumer flake availability depends on fragmented municipal collection systems, creating feedstock bottlenecks for bottle-to-bottle recyclers.
- Industrial composting capacity gaps:Biodegradable films require dedicated anaerobic digestion infrastructure that remains underdeveloped in eastern German states.
Strategic Opportunities
- Digital packaging passports:EU Green Deal traceability mandates create first-mover advantage for converters integrating blockchain-linked material provenance systems.
- E-commerce fulfillment formats:Film and pouch structures are capturing parcel logistics demand where weight reduction directly reduces DHL and Hermes shipping tariffs.
- Chemical recycling partnerships:Pyrolysis and depolymerization investments offer alternative feedstock pathways for food-contact applications where mechanical recycling faces regulatory limits.
Industry Challenges
- REACH compliance timeline compression:Migrating testing protocols for food-contact materials requires accelerated laboratory certification cycles that strain quality assurance departments.
- Multi-material separation complexity:Laminated flexible packaging containing PET, PE, and aluminum layers demands capital-intensive delamination equipment to meet recycling purity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Plastic Packaging Market |
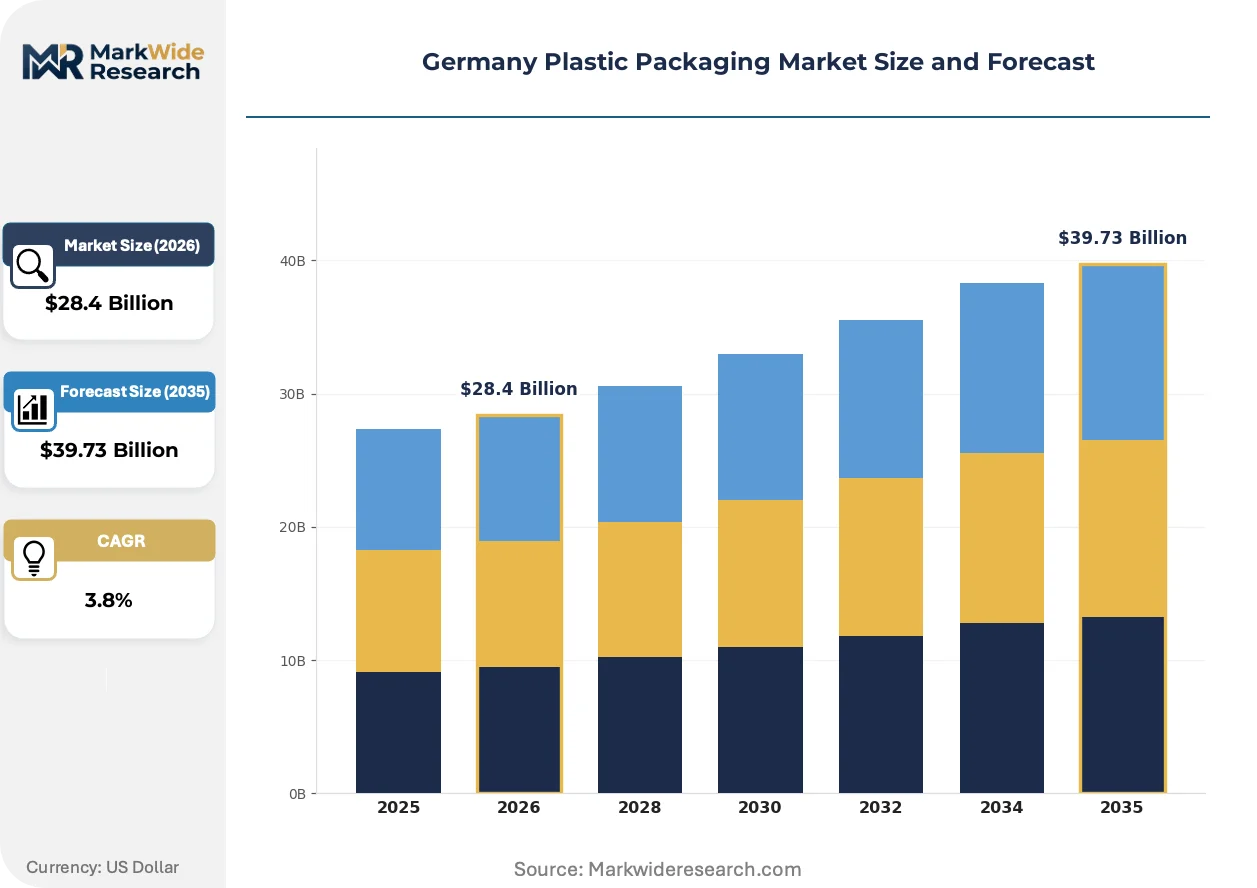
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $39.73 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottle, Film, Container, Tray, Cap, Pouch Material: Polyethylene Terephthalate, High-Density Polyethylene, Polyvinyl Chloride, Polypropylene, Polystyrene, Bioplastics Application: Food & Beverage, Personal Care, Pharmaceuticals, Industrial Goods, Household Chemicals, Agricultural Products End User: Manufacturers, Retail Chains, E-commerce Companies, Wholesalers, Distributors, Brand Owners |
| Companies Covered | Gerresheimer AG, Sealed Air Corporation, Schütz-Werke GmbH & Co. KG, Constantia Flexibles Group, Klöckner Pentaplast GmbH, Amcor Plc, Huhtamaki Oyj, Sonoco Products Company, Mondi Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Plastic Packaging Market Shifts & Advancements
Material science advances and regulatory compliance automation are restructuring competitive advantage in German plastic packaging, with converters racing to integrate traceability and circular feedstock systems before enforcement deadlines crystallize.
Mono-material barrier films are absorbing technical development resources previously allocated to multi-layer laminates. Snack and confectionery packagers are adopting polyethylene-only structures to simplify mechanical recycling streams. This shift is absorbing R&D budgets from conventional high-barrier coextrusion programs as converters prioritize sortability over shelf-life extension.
REACH chemical migration limits are tightening testing protocols for food-contact applications. The German Environment Agency is enforcing lower detection thresholds for oligomers and additives in recycled polymers. Small and mid-sized converters in Baden-Württemberg are outsourcing compliance verification to specialized laboratories to avoid capital expenditure on in-house spectrometry equipment.
Discount retail procurement is consolidating supplier panels around converters offering certified recycled content guarantees. Aldi and Lidl are requiring documentation of post-consumer resin percentages in private-label packaging. This concentration is visible in North Rhine-Westphalia where regional buying cooperatives are excluding uncertified suppliers from tender processes.
Germany Plastic Packaging Market Segmentation
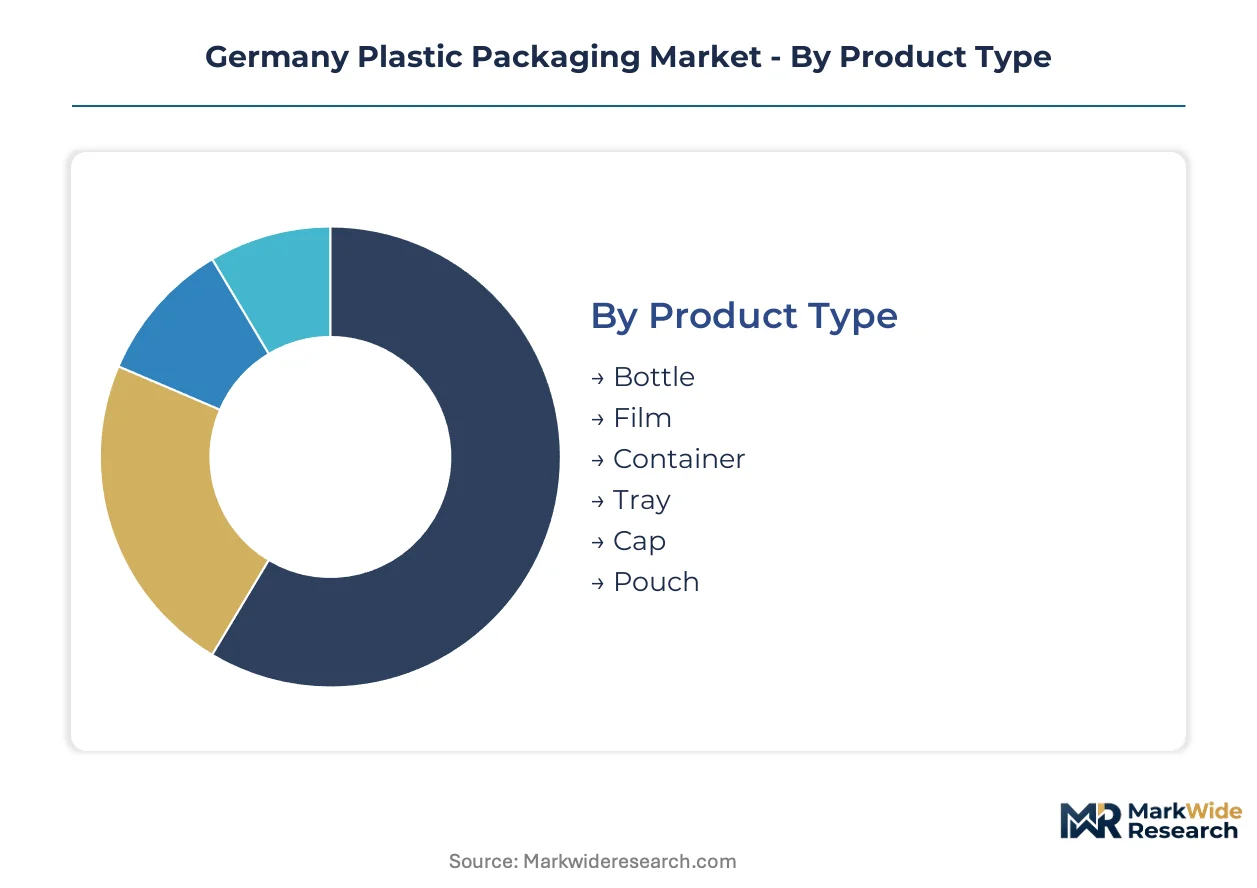
German plastic packaging converters configure production assets around format-specific tooling and barrier specifications. Each segment category carries distinct margin profiles and regulatory exposure under KBA extended producer responsibility frameworks.
Product Type:
Bottle manufacturing concentrates capacity in North Rhine-Westphalia and Bavaria, where PET preform injection and stretch-blow molding lines achieve scale economies.
- Bottle:PET bottles dominate beverage containment with established deposit-return infrastructure feeding rPET supply chains. Demand clusters around discount retail private-label water and carbonated soft drinks in the Rhineland.
- Film:Cast and blown film extrusion serves flexible food packaging with oxygen barrier coextrusion for processed meat and cheese applications. Bavarian dairy processors drive specification tightening for extended shelf-life formats.
- Container:Injection-molded tubs and pails target industrial chemicals and household cleaning products. HDPE resin specifications vary by UN certification requirements for hazardous material transport.
- Tray:Thermoformed PET and PP trays serve fresh produce and ready-meal segments. Discount retailers specify mono-material designs to simplify sortation at mechanical recycling facilities.
- Cap:Closure systems require torque specifications and child-resistant mechanisms for pharmaceutical applications. Polypropylene dominates dairy and beverage screw-cap production.
- Pouch:Stand-up and flat pouch formats capture e-commerce fulfillment demand where weight reduction cuts DHL shipping tariffs. Spouted pouches gain traction in baby food and pet care segments.
Bottle absorbs the bulk of installed capacity; pouch is expanding most quickly.
Material:
Resin selection determines recycling pathway eligibility and EPR fee liability under German packaging ordinance calculations.
- Polyethylene Terephthalate:Dominates beverage and food tray applications with established bottle-to-bottle recycling infrastructure. rPET flake supply constraints force converters into long-term feedstock contracts.
- High-Density Polyethylene:Milk bottles and industrial containers leverage HDPE's chemical resistance and impact strength. Post-consumer bale quality variability complicates food-contact recycling certification.
- Polyvinyl Chloride:Pharmaceutical blister packs and medical device packaging exploit PVC's thermoformability and barrier properties. REACH migration limits constrain food-contact applications.
- Polypropylene:Living hinge caps and thin-wall containers benefit from PP's fatigue resistance. rPP availability lags rPET, forcing reliance on post-industrial scrap streams.
- Polystyrene:Expanded PS protective packaging faces substitution pressure from molded pulp alternatives. Crystal PS remains in pharmaceutical vial and diagnostic tray applications.
- Bioplastics:PLA and starch blends target premium organic food positioning. Industrial composting capacity gaps in eastern states limit geographic deployment.
Polyethylene Terephthalate commands the largest production volume; bioplastics are climbing the fastest.
Application:
End-use specifications fragment converter capabilities across barrier requirements, sterilization compatibility, and regulatory documentation burdens.
- Food & Beverage:The largest demand pool spans modified atmosphere packaging for fresh meat and aseptic filling for dairy. Aldi and Lidl procurement panels enforce recycled content minimums.
- Personal Care:Cosmetic bottles and tubes require fragrance barrier layers and premium decoration compatibility. Airless pump systems drive multi-component assembly complexity.
- Pharmaceuticals:Blister packs, vials, and pre-filled syringes demand USP Class VI certification and extractables testing. Gerresheimer anchors glass-plastic hybrid expertise in this segment.
- Industrial Goods:Lubricant containers and chemical pails specify UN-certified stacking strength and chemical resistance. Automotive suppliers in Baden-Württemberg drive just-in-time delivery requirements.
- Household Chemicals:Trigger sprayers and refill pouches balance child safety with ergonomic dispensing. Concentrate formats reduce shipping volume for e-commerce channels.
- Agricultural Products:Seed and fertilizer packaging requires UV stabilization and moisture barriers. Seasonal demand patterns strain converter capacity planning.
Food & Beverage captures dominant volume share; pharmaceuticals posts the steepest expansion trajectory.
End User:
Customer type determines order pattern predictability, specification complexity, and direct exposure to EPR compliance obligations.
- Manufacturers:Food processors and chemical producers specify packaging inline with filling line speeds and sterilization protocols. Technical service requirements dominate supplier selection.
- Retail Chains:Aldi, Lidl, and Rewe buying cooperatives consolidate supplier panels around certified recycled content guarantees. Private-label packaging specifications are tightening fastest.
- E-commerce Companies:Amazon and Zalando fulfillment centers prioritize damage reduction and dimensional weight optimization. Pouch formats displace corrugated for soft goods.
- Wholesalers:Metro and similar operators demand pallet-efficient secondary packaging and clear labeling for foodservice redistribution. Volume consolidation enables specification standardization.
- Distributors:Industrial chemical distributors require UN-certified packaging with lot traceability for hazardous material compliance. Regional inventory positioning affects lead time requirements.
- Brand Owners:Procter & Gamble and Henkel internalize sustainability messaging through packaging design, driving demand for material provenance documentation.
Manufacturers represent the largest customer base; e-commerce companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's Munich-Nuremberg industrial corridor anchors German plastic packaging demand through automotive and chemical sector concentration. North Rhine-Westphalia's Rhineland chemical complex feeds converter feedstock requirements. Baden-Württemberg's precision manufacturing clusters drive pharmaceutical and industrial packaging specifications.
North Rhine-Westphalia
Discount retail procurement headquarters in the Rhineland drive rigid PET tray and bottle specifications for Aldi and Lidl private-label programs. KBA extended producer responsibility enforcement obligates brand owners to finance collection infrastructure. Düsseldorf and Cologne host converter clusters serving dairy and beverage segments with bottle-to-bottle recycling integration.
Bavaria
Automotive suppliers around Munich demand UN-certified industrial containers and just-in-time delivery packaging for chemical components. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that compress converter margins. Nuremberg's chemical packaging corridor generates scale economies for regional thermoforming and blow-molding operations.
Baden-Württemberg
Pharmaceutical manufacturers in Stuttgart and Mannheim specify USP Class VI certified blister packs and drug delivery systems. REACH chemical migration limits tighten testing protocols for food-contact and medical applications. Small and mid-sized converters outsource compliance verification to specialized laboratories to avoid spectrometry capital expenditure.
Lower Saxony
Agricultural packaging demand concentrates around Hanover for seed and fertilizer applications requiring UV stabilization. Industrial composting capacity gaps in eastern states constrain bioplastic film deployment for organic food segments. Regional converters balance seasonal demand patterns with chemical and food processor contract manufacturing.
Hesse
Frankfurt's logistics and distribution hub drives e-commerce fulfillment packaging demand where weight reduction cuts DHL shipping tariffs. Film and pouch formats displace corrugated for soft goods in Amazon and Zalando supply chains. Central location enables just-in-time supply to Rhineland and Bavarian industrial corridors.
Germany Plastic Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and recycled content guarantee capabilities. The vendor base stratifies between multinational converters with integrated rPET supply chains and regional specialists serving single-format niches. Three archetypes dominate: integrated rigid packaging conglomerates, flexible film specialists, and pharmaceutical-grade hybrid material providers. M&A activity concentrates on chemical recycling technology access, while capacity expansion targets bottle-to-bottle rPET processing.
Within the pharmaceutical-grade tier, Gerresheimer AG exemplifies glass-plastic hybrid expertise for drug delivery formats. Among flexible packaging specialists, Constantia Flexibles Group and Klöckner Pentaplast GmbH occupy positions anchored in dairy and discount retail supply chains respectively. These three represent distinct strategic postures: hybrid material science leadership, flexible film scale, and rigid PET thermoforming specialization.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Sealed Air Corporation |
| Schütz-Werke GmbH & Co. KG |
| Constantia Flexibles Group |
| Klöckner Pentaplast GmbH |
| Amcor Plc |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Mondi Group |
| Others |
Supply & Pricing Matrix
Aldi and Lidl's recycled content mandates for private-label packaging force converters to secure long-term rPET contracts or lose shelf placement, compressing margins and restructuring procurement cost allocation across German supply chains.
Pricing Analysis
Throughput guarantees from bottle-to-bottle recyclers anchor value-based pricing for certified rPET grades, separating premium food-contact resin from standard flake. Price differentiation rests on EPR fee liability and digital packaging passport readiness. Cost compression in commodity PET intensifies as mechanical recycling capacity bottlenecks persist. Discount retailers exhibit highest price sensitivity; pharmaceutical-grade converters show lowest.
Supply Chain Analysis
Direct-to-brand channels handle Aldi and Lidl hyperscale demand through long-term offtake agreements. Feedstock draws from Germany, Netherlands, and Belgium collection systems. Virgin resin dependencies include naphtha-derived ethylene and paraxylene for PET polymerization. Single-source vulnerability concentrates in rPET flake supply from fragmented municipal infrastructure. Distribution runs through converter-owned logistics hubs serving Rhineland retail headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German plastic packaging sits in a material-transition phase where mono-material barrier films displace multi-layer laminates, forcing converters to reallocate R&D budgets from legacy coextrusion programs.
For Market Incumbents: Extend backward integration into rPET washing and flake processing to secure feedstock against KBA enforcement tightening. Add chemical recycling partnerships for food-contact applications where mechanical recycling faces REACH migration limits. Defend margin position by consolidating regional thermoforming capacity in Bavaria's automotive corridor. For New Entrants and Emerging Players: Launch via e-commerce fulfillment formats targeting DHL and Hermes shipping cost reduction. White-space concentrates in spouted pouches for baby food and pet care where incumbent flexible film specialists lack spout assembly expertise. Penetrate through digital packaging passport integration services for mid-sized Baden-Württemberg converters outsourcing compliance. For Investors and Strategic Acquirers: The window for entry favors chemical recycling technology providers with pyrolysis or depolymerization patents. Long-term viability hinges on EU Green Deal recycled content enforcement crystallizing demand for alternative feedstock pathways. Watch industrial composting capacity buildout in eastern German states as bioplastic deployment inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Supply Contracting | Long-term offtake agreements with KBA-licensed recyclers secure shelf placement at Aldi and Lidl. |
| Chemical Recycling Partnership | Pyrolysis investments bypass mechanical recycling limits for food-contact REACH compliance. |
| Digital Passport Integration | Blockchain-linked provenance systems capture EU Green Deal first-mover advantage before enforcement. |
| Mono-Material R&D Pivot | Polyethylene-only barrier films simplify sortation at German mechanical recycling facilities. |
| Bavaria Capacity Expansion | Thermoforming lines near Munich-Nuremberg corridor capture automotive chemical packaging demand. |
Research Methodology
Trade association filings, KBA extended producer responsibility registry data, and EU Packaging and Packaging Waste Regulation impact assessments formed the secondary backbone. Primary interviews with rigid packaging plant managers, flexible film procurement leads at dairy processors, discount retail category buyers, and chemical recycling technology developers validated segment assumptions. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures.
Historical trendline analysis of PET resin consumption and rPET feedstock availability established baseline growth patterns across the projection horizon. Segmentation dimensions included product format, material resin, application end-use, and customer type. CAGRs derived from regression analysis of installed capacity expansion and regulatory mandate enforcement timelines. Forecast inputs incorporated EPR fee structure evolution and industrial composting capacity buildout assumptions.
The model assumes mechanical recycling remains dominant for beverage applications; alternative pathways for chemical recycling would alter the outlook if pyrolysis yields achieve food-contact cost parity. Forecasts reflect base-case assumptions on EU Green Deal timeline adherence and KBA enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
HDPE Jug Market