
 Plastic-Based Egg Packaging Market | 2026-2036
Plastic-Based Egg Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic-Based Egg Packaging Market Outlook
The EU Green Deal is expanding compliance obligations for food-contact plastics across member states, forcing converters to certify recycled-content thresholds. Sealed Air Corporation leverages its global thermoforming footprint to supply major European retailers with rPET clamshells. Berry Global Inc. anchors North American volume through multi-site extrusion and thermoforming operations near poultry belts. Huhtamaki Group differentiates via fiber-plastic hybrid R&D targeting premium private-label channels.
Plastic-based egg packaging denotes thermoformed or injection-molded containers engineered from polyethylene, polypropylene, or polystyrene resins, typically specifying wall thickness of 0.3–0.8 mm to withstand stacking loads of 15–25 kg during refrigerated distribution. These structures protect shell integrity through controlled ventilation and impact absorption from farm grading through retail shelf presentation. Clamshells command the dominant share of consumer-facing formats due to visibility and reclosability, while polyethylene-based trays sustain the highest volume in automated packing lines for egg producers. Polystyrene faces structural decline in food service applications as operators phase out non-recyclable formats under buyer mandates.
The EPA regulates post-consumer recycled content claims under Green Guides enforcement, while FDA maintains 21 CFR 177 compliance for olefin and styrenic polymers in direct food contact. EFSA and ECHA jointly constrain additive chemistries through REACH SVHC listings and migration limits, tightening formulation flexibility for exporters. Stakeholders must monitor evolving extended producer responsibility fee structures and decide whether to absorb compliance costs or pass through to contract poultry integrators.
Market Dynamics
The EU Single-Use Plastics Directive is compressing formulation freedom for converters, forcing rapid migration toward certified recycled-content feedstocks across thermoforming operations.
Growth Catalysts
- REACH SVHC migration limits:ECHA constraints on additive chemistries are accelerating rPET adoption as converters preempt compliance costs through material substitution.
- Centralized packing station consolidation:Germany's farm-to-retail integration demands standardized tray geometries that favor automated thermoforming lines.
- Clamshell visibility premium:Retail grocery chains specify rigid transparent formats to reduce shell breakage during self-service handling.
Market Restraints
- rPET feedstock scarcity:Bottle-to-tray recycling competition limits food-grade flake availability, elevating resin premiums above virgin polypropylene.
- Polystyrene phase-out mandates:Buyer sustainability requirements are structurally eliminating foam formats from food service channels.
- Wall thickness engineering limits:Sub-0.4 mm thermoforming risks stack-load failure under 20 kg pallet compression.
Strategic Opportunities
- Extended producer responsibility fee arbitrage:Early compliance with Germany's VerpackG modulation criteria yields cost advantages versus laggard competitors.
- Fiber-plastic hybrid formats:Premium private-label channels reward bio-based barrier layers that reduce petroleum-derived content.
- Direct-to-integrator contracting:Bypassing distributor markup through captive supply agreements with poultry belt operators.
Industry Challenges
- FDA 21 CFR 177 recertification timelines:Post-consumer content validation for direct food contact extends qualification cycles.
- Multi-site extrusion coordination:Maintaining lot traceability across dispersed thermoforming assets complicates quality audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic-Based Egg Packaging Market |
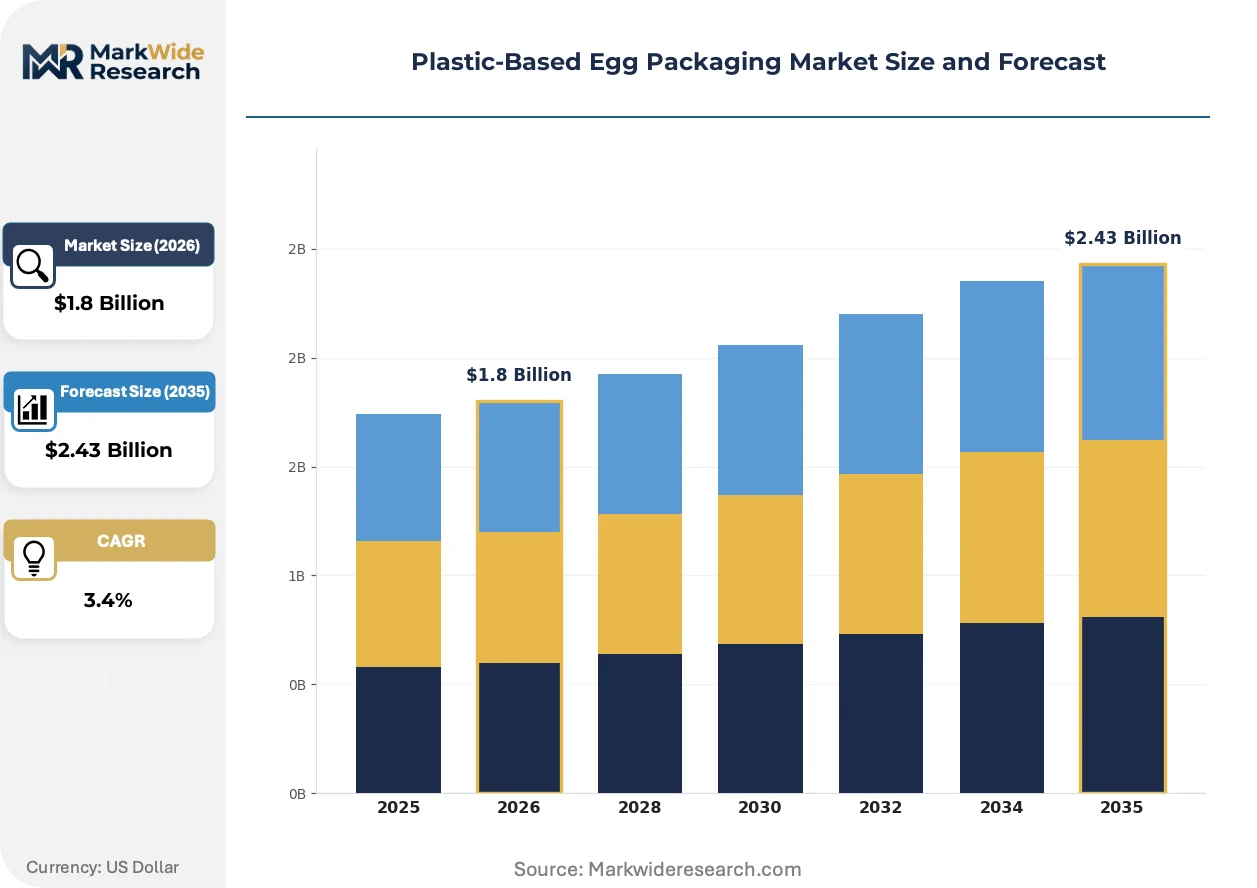
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshells, Trays, Sleeves, Custom Packaging Material Type: Polyethylene, Polypropylene, Polystyrene, Others End User: Retailers, Wholesalers, Food Service, Egg Producers Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Sealed Air Corporation, Winpak Ltd., Berry Global Inc., Sigma Plastics Group, Dart Container Corporation, Huhtamaki Group, Sonoco Products Company, Pactiv Evergreen, Plastipak Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic-Based Egg Packaging Market Strategic Shifts
Material science and regulatory chemistry are converging to redefine acceptable performance thresholds. Thermoformers must now engineer for circularity metrics alongside mechanical specifications.
Thermoformed rPET clamshells are consolidating position as the default consumer-facing format. Major European retailers now specify minimum 50% post-consumer content in RFQ documents. This specification compression is marginalizing virgin polystyrene and polypropylene alternatives in premium retail channels.
EFSA and ECHA jointly tightened additive migration limits through updated REACH SVHC listings in 2024. Converters face reformulation costs for legacy nucleating agents and colorants. German packing stations are responding by consolidating supplier bases to pre-qualified resin compounders with certified food-contact dossiers.
Retail procurement teams now mandate lifecycle assessment documentation alongside unit pricing. Distributor intermediaries lose share to direct mill relationships as buyers seek data transparency. This disintermediation is most pronounced in Netherlands and Denmark supermarket chains with published plastic reduction targets.
Plastic-Based Egg Packaging Market Segmentation
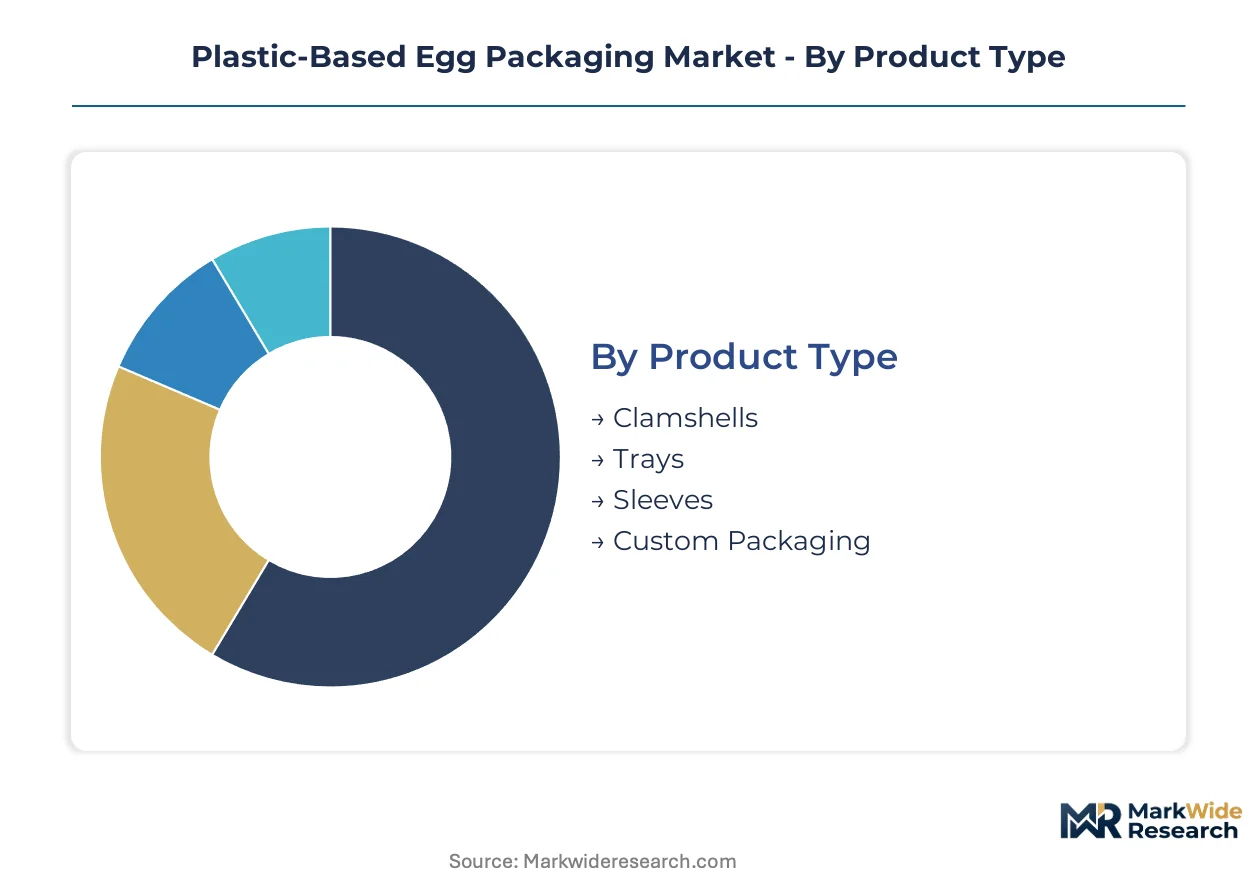
Segmentation in plastic-based egg packaging reveals how material selection, format engineering, and channel configuration determine margin capture. Each dimension carries distinct compliance burdens and automation requirements that shape supplier positioning.
Product Type:
Volume concentrates in automated packing lines, while premium visibility drives consumer-facing formats.
- Clamshells:Thermoformed rigid containers with 0.3–0.8 mm wall thickness provide controlled ventilation and impact absorption for retail display. German supermarket chains specify these transparent formats to reduce shell breakage during self-service handling.
- Trays:Polyethylene-based molded structures dominate automated grading and packing operations with standardized cell geometries. Centralized packing stations across Germany favor these formats for high-speed line integration and pallet stacking efficiency.
- Sleeves:Lightweight shrink-film wraps serve secondary bundling for multi-unit retail promotions.
- Custom Packaging:Branded or private-label formats with modified dimensions target specialty retail channels.
Mature deployment sits with trays. Newer deployment is concentrated in custom packaging for premium private-label differentiation.
Material Type:
Feedstock selection now pivots on recycled-content certification rather than pure cost optimization.
- Polyethylene:Linear low-density grades sustain highest throughput in automated tray thermoforming with consistent melt flow indices. rPET feedstock scarcity has elevated virgin polyethylene premiums above historical spreads.
- Polypropylene:High-impact copolymers deliver stack-load performance for distribution pallets compressed at 15–25 kg. ECHA REACH SVHC constraints on additive chemistries are accelerating material substitution toward certified recycled streams.
- Polystyrene:General-purpose and high-impact grades face structural phase-out under EU Single-Use Plastics Directive mandates.
- Others:Bio-based polyesters and fiber-plastic hybrids target premium channels with petroleum-content reduction claims.
Mature deployment sits with polyethylene. Newer deployment is concentrated in bio-based alternatives for lifecycle assessment documentation.
End User:
Procurement authority shifts from distributors to direct integrator relationships as buyers seek supply chain transparency.
- Retailers:Supermarket chains now mandate minimum 50% post-consumer content in RFQ specifications, marginalizing virgin resin alternatives. Netherlands and Denmark chains with published plastic reduction targets lead this specification compression.
- Wholesalers:Volume aggregation for food service and institutional buyers emphasizes unit cost over material certification.
- Food Service:Operators are phasing out polystyrene foam formats under buyer sustainability mandates.
- Egg Producers:Poultry belt operators seek captive supply agreements to bypass distributor markups.
Mature deployment sits with wholesalers. Newer deployment is concentrated in direct-to-producer contracting for margin capture.
Distribution Channel:
Channel selection determines data transparency requirements and extended producer responsibility fee exposure.
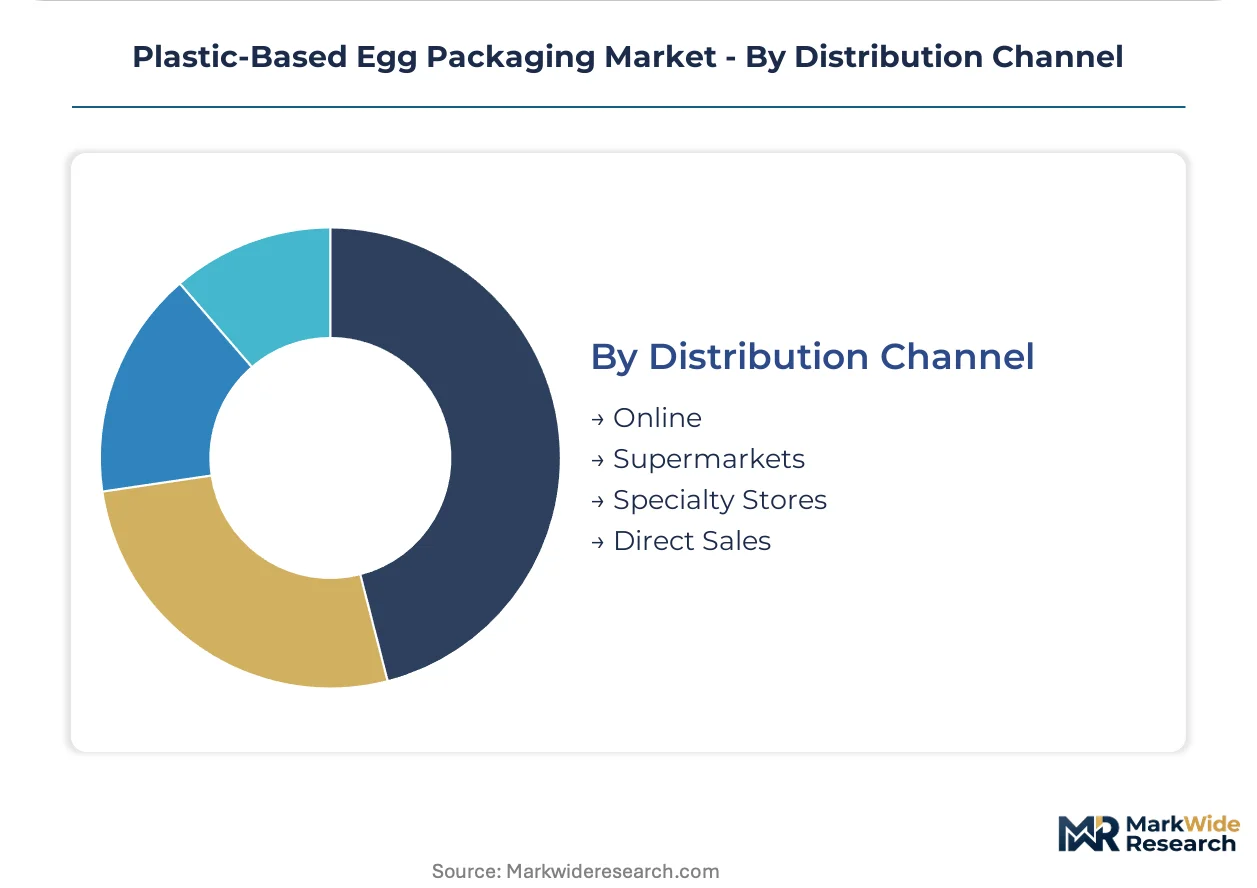
- Online:E-commerce fulfillment demands enhanced crush resistance for last-mile handling.
- Supermarkets:Self-service display requirements drive clamshell specification for visibility and reclosability.
- Specialty Stores:Organic and free-range egg retailers favor fiber-plastic hybrid formats for shelf differentiation.
- Direct Sales:Mill-direct relationships are displacing distributor intermediaries as procurement teams mandate lifecycle assessment documentation alongside unit pricing.
Mature deployment sits with supermarkets. Newer deployment is concentrated in direct sales for compliance data transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centralized packing stations around Hanover and Oldenburg in Germany's Lower Saxony region set the template for automated egg handling infrastructure across Europe. These facilities process volumes that shape tray standardization and clamshell specifications continent-wide. Regulatory pressure from Brussels filters through national implementations that alter competitive positioning in each market.
Germany
Consolidated poultry operations in Lower Saxony and North Rhine-Westphalia drive demand for high-speed polyethylene trays with standardized cell geometries. The country's VerpackG extended producer responsibility framework modulates fees based on recyclability performance, rewarding early compliance investments. Thermoforming clusters around Hanover supply major retail chains with certified recycled-content clamshells meeting 50% post-consumer thresholds.
United States
Integrated egg producers across Iowa, Indiana, and Ohio seek captive supply agreements to bypass distributor markups in procurement. FDA maintains 21 CFR 177 compliance requirements for olefin polymers in direct food contact, extending qualification cycles for post-consumer content validation. Extrusion and thermoforming operations concentrate near poultry belts in the Midwest, serving retail grocery chains expanding rigid plastic clamshell specifications.
Netherlands
Supermarket chains with published plastic reduction targets mandate lifecycle assessment documentation alongside unit pricing in procurement. The EU Green Deal's compliance obligations for food-contact plastics force converters to certify recycled-content thresholds across operations. Distribution networks around Rotterdam and Utrecht favor direct mill relationships over distributor intermediaries for supply chain transparency.
France
Retail procurement teams specify minimum recycled-content percentages in RFQ documents, marginalizing virgin resin alternatives in premium channels. ECHA REACH SVHC listings constrain additive chemistries, accelerating reformulation costs for legacy nucleating agents and colorants. Packing stations in Brittany and Pays de la Loire consolidate supplier bases to pre-qualified resin compounders with certified food-contact dossiers.
Denmark
Organic and free-range egg retailers favor fiber-plastic hybrid formats for shelf differentiation in specialty channels. The EU Single-Use Plastics Directive pressures converters toward recycled-content mandates, compressing formulation freedom across thermoforming operations. Copenhagen-area distribution hubs lead disintermediation trends as buyers seek direct relationships with packaging mills for data transparency.
Plastic-Based Egg Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and material innovation dimensions. The vendor base stratifies between integrated multinational converters with global thermoforming footprints and regional specialists serving single-country poultry belts. Three archetypes dominate: rPET-certified suppliers capturing retail specification mandates, virgin-resin commodity producers defending volume in wholesale channels, and hybrid-format innovators targeting private-label premiumization. Competitive moves concentrate on strategic partnerships with poultry integrators and capacity expansion near high-density production zones.
Among North American fabricators, Berry Global Inc. and Dart Container Corporation occupy positions within the scale-driven commodity tier, while Sealed Air Corporation exemplifies the certified-recycled archetype through its European retail supply relationships. These three anchors illustrate how geographic footprint and material certification separate margin tiers across the competitive landscape.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Winpak Ltd. |
| Berry Global Inc. |
| Sigma Plastics Group |
| Dart Container Corporation |
| Huhtamaki Group |
| Sonoco Products Company |
| Pactiv Evergreen |
| Plastipak Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across Germany's Lower Saxony thermoforming belt maintain pricing discipline through captive relationships with poultry integrators, insulating contract rates from spot resin volatility while passing compliance premiums through to retail buyers under VerpackG modulation frameworks.
Pricing Analysis
Throughput-based pricing anchors contract negotiations between packing stations and thermoforming suppliers, with line-speed guarantees replacing per-unit quotes for high-volume polyethylene tray supply. Price differentiation separates certified rPET clamshells meeting EFSA migration standards from virgin polypropylene alternatives in retail channels, while wholesale buyers prioritize volume scale over certification grade. Cost compression in polystyrene formats is intensifying because food service operators accelerate phase-out mandates, squeezing margins for legacy foam producers. Retail procurement teams exhibit lowest price sensitivity, accepting recycled-content premiums for lifecycle assessment documentation, whereas independent egg producers remain most price-sensitive due to distributor markup exposure.
Supply Chain Analysis
Single-source vulnerability sits with German resin compounders holding certified food-contact dossiers for REACH-compliant additive packages, creating bottleneck risk for converters seeking rapid reformulation. Raw material flows draw from Belgium's rPET flake processors, Saudi Arabia's virgin polyethylene producers, and Netherlands-based nucleating agent specialists, with bottle-to-tray recycling competition constraining food-grade feedstock availability. Tariff exposure on imported polypropylene feedstock elevates input cost volatility for North American extrusion operations near Iowa and Indiana poultry belts. Distribution runs through direct mill relationships displacing wholesaler intermediaries, as Dutch and Danish supermarket chains mandate supply chain transparency for extended producer responsibility compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoformed rPET technology is displacing legacy polystyrene and virgin polypropylene formats across European retail channels, compressing the window for incumbent converters to recertify operations before specification mandates harden.
For Market Incumbents: Extend thermoforming capacity adjacent to Germany's Hanover and Oldenburg packing station clusters to capture consolidated poultry volume, while accelerating FDA 21 CFR 177 recertification for post-consumer content validation to preempt competitor qualification cycles. Defend margin position through backward integration into rPET flake washing operations, securing feedstock priority as bottle-to-tray competition intensifies. For New Entrants and Emerging Players: Enter via fiber-plastic hybrid formats targeting Denmark's organic egg retailers and Netherlands specialty channels, where premium private-label differentiation rewards bio-based barrier layer innovation. White-space availability concentrates in direct-to-integrator contracting models bypassing distributor markups across Midwest US poultry belts, with captive supply agreements offering the most penetrable go-to-market angle for volume scale. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European thermoformers with stranded polystyrene assets and pending VerpackG compliance liabilities, particularly in France's Brittany packing corridor where ECHA REACH reformulation costs are accelerating supplier consolidation. Long-term viability over a five-to-ten year horizon rests on rPET certification infrastructure and direct retail relationships; the signal to watch is German supermarket RFQ specifications crossing seventy percent post-consumer content thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Certification Investment | EFSA-compliant dossiers unlock access to Netherlands and Denmark retail chains with mandated recycled-content floors. |
| Backward Integration into Flake Processing | Bottle-to-tray feedstock priority insulates margin compression from resin scarcity premiums above virgin polypropylene. |
| Direct Mill Relationship Development | Bypassing distributor intermediaries captures markup value while satisfying procurement team lifecycle assessment documentation requirements. |
| Fiber-Plastic Hybrid R&D Scale-Up | Bio-based barrier layers penetrate Denmark organic channels and French premium private-label differentiation strategies. |
| Capacity Expansion Near Poultry Belts | Proximity to Iowa and Indiana integrators reduces logistics costs and enables captive supply contract structures. |
Study Parameters
Independent corroboration across thermoforming plant managers, procurement leads at German packing stations, retail category buyers, resin compounder technical directors, and ECHA regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through EU Green Deal implementation documents, FDA 21 CFR 177 guidance filings, VerpackG fee modulation schedules, and customs trade data on polyethylene and polypropylene resin flows. Bottom-up volume estimates from individual converter capacity and top-down demand calibration from poultry production statistics were triangulated to anchor segmentation outputs.
Rate-of-change decomposition across the analysis window applied volume and value modeling through product type, material grade tier, end-user channel configuration, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth trajectories weighted by base-year revenue contribution, with inputs including ECHA REACH SVHC listing timelines, German centralized packing station consolidation patterns, and retail RFQ specification evolution for post-consumer content thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA migration limit revisions or accelerated EU Single-Use Plastics Directive enforcement waves that could compress qualification timelines beyond converter adaptation capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market