
 Plastic Cutlery Market | 2026-2036
Plastic Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Cutlery Market Outlook
Chinese molded-fiber and thermoforming capacity is hardening export competitiveness in disposable tableware. Fuling leverages integrated resin-to-finished-product operations to sustain cost leadership in polypropylene cutlery exports. Huhtamaki anchors European demand through its broad foodservice packaging portfolio and established quick-service restaurant relationships. Pactiv Evergreen differentiates via North American manufacturing scale and direct distribution to institutional buyers.
Plastic cutlery denotes injection-molded or thermoformed disposable eating implements, typically manufactured from polypropylene or polystyrene resins with wall thicknesses of 1.5–3.0 millimeters and designed for single-use foodservice applications. The primary commercial purpose centers on hygienic, low-cost utensil provision for away-from-home dining, takeout operations, and catered events where washing reusable alternatives proves impractical. Spoons and forks lead product type volumes due to their universality across cuisines and meal occasions, while bio-based plastic formulations represent the fastest-growing material category as foodservice operators seek compliance with emerging packaging regulations. Polypropylene maintains margin concentration through its superior heat resistance and durability relative to polystyrene alternatives.
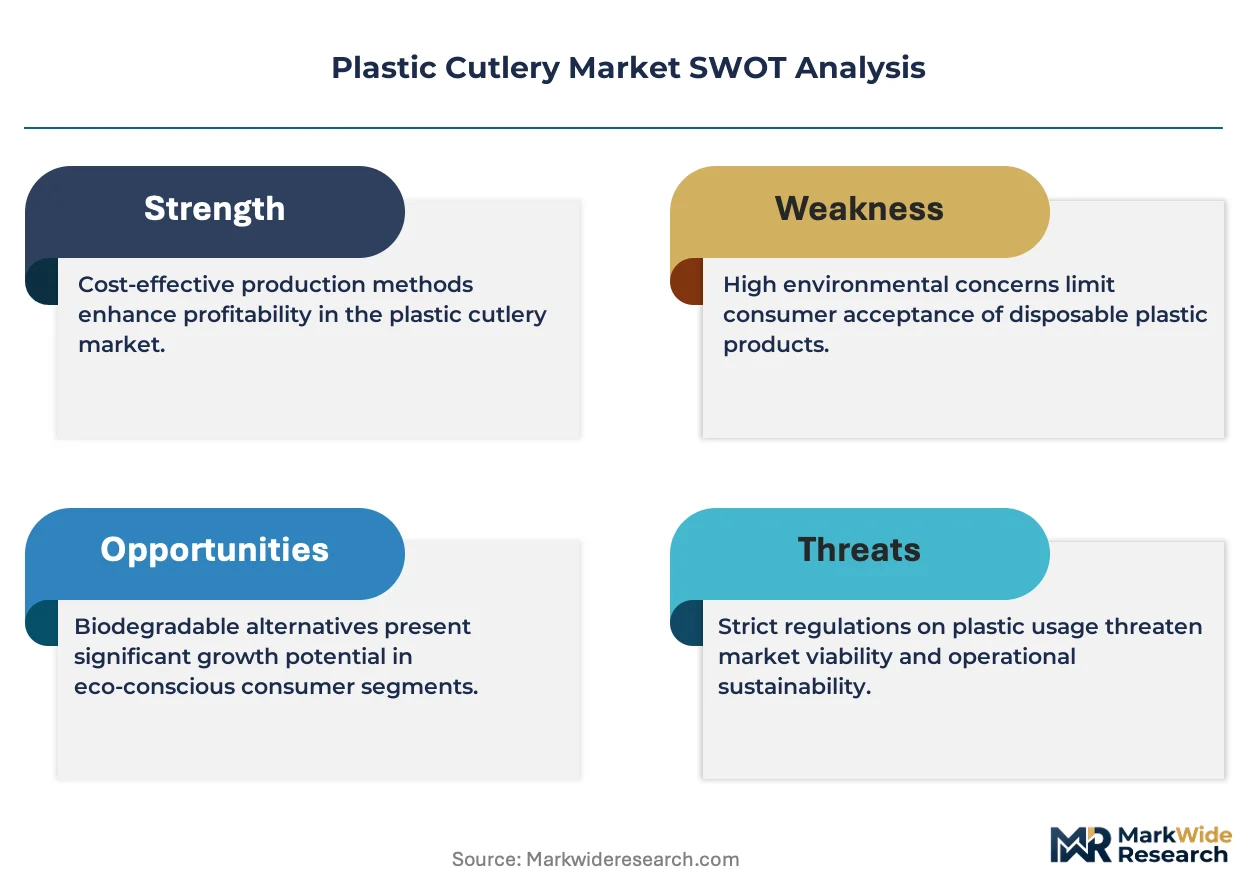
The U.S. Food and Drug Administration governs food-contact material safety, while the EU Single-Use Plastics Directive mandates consumption reduction targets and extended producer responsibility schemes across member states. State-level bans in California, New York, and Washington further fragment compliance requirements for national distributors. Stakeholders must monitor pending U.S. federal packaging legislation and bio-based plastic certification standards to align capacity investments with shifting procurement specifications.
Market Dynamics
The EU Single-Use Plastics Directive is compressing polypropylene cutlery volumes across member states while bio-based alternatives scramble for manufacturing scale. Quick-service restaurant procurement teams now face dual mandates: maintain cost discipline while satisfying corporate sustainability commitments that outpace regulatory minimums.
Growth Catalysts
- On-premise dining normalization:Quick-service restaurants in the United States have restored pre-pandemic traffic patterns, reinstituting institutional procurement contracts for polypropylene fork and spoon volumes that had shifted to retail channels.
- Extended Producer Responsibility schemes:The EU Single-Use Plastics Directive mandates fee structures that favor lighter-weight cutlery designs, incentivizing thermoforming equipment upgrades among converters seeking compliance cost optimization.
- Molded-fiber thermoforming:Chinese manufacturing clusters have achieved production economics that undercut European molded-fiber pricing by double-digit percentages, accelerating export penetration into North American foodservice distribution.
Market Restraints
- Propylene monomer volatility:Polypropylene resin contracts track naphtha and propylene feedstock swings that compress converter margins during upstream price spikes.
- State-level regulatory fragmentation:California, New York, and Washington maintain divergent single-use plastic prohibitions that force national distributors to maintain multiple SKU configurations and compliance documentation systems.
- Polylactic acid performance ceiling:Bio-based alternatives exhibit heat deformation thresholds below 55°C that disqualify them from soup and hot-beverage applications where polypropylene dominates.
Strategic Opportunities
- Quick-service restaurant bio-based mandates:Chains with net-zero commitments by 2030 are pre-qualifying suppliers with certified compostable cutlery portfolios, creating procurement windows ahead of regulatory deadlines.
- Direct distribution bypass:Institutional buyers including hospital systems and university foodservice operations are consolidating vendor lists, favoring converters with in-house logistics networks over distribution intermediaries.
- India foodservice expansion:Organized quick-service penetration in tier-2 Indian cities is generating first-wave disposable cutlery demand from international and domestic chain formats.
Industry Challenges
- Composting infrastructure mismatch:Certified bio-based cutlery requires industrial composting facilities that remain absent in 40-plus U.S. metropolitan markets, creating disposal confusion and brand risk for operators.
- Legacy injection molding retooling:Converters with sunk capital in polypropylene-dedicated tooling face extended payback periods if forced to accelerate bio-based material transitions ahead of equipment depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Cutlery Market |
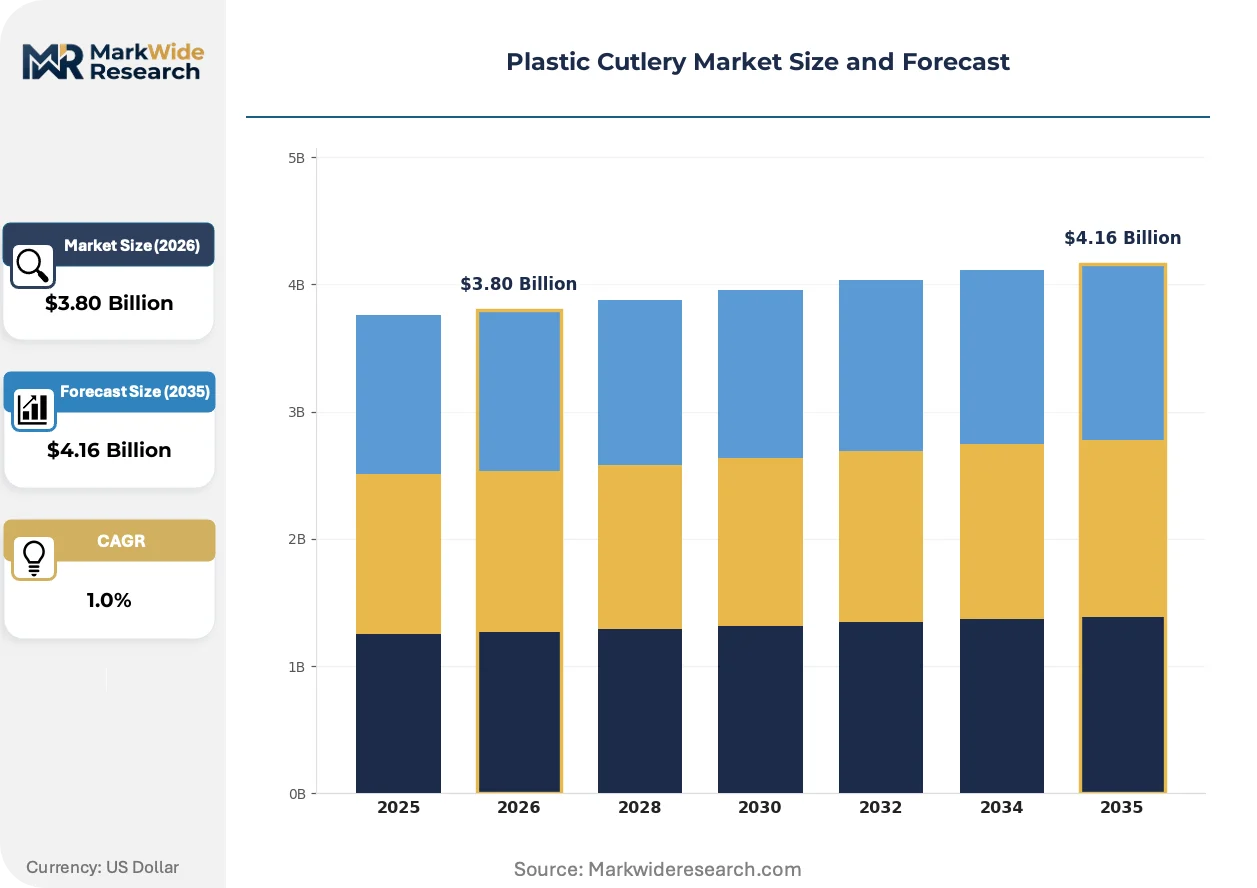
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forks, Knives, Spoons, Serving Utensils Material: Polypropylene, Polystyrene, Bio-Based Plastic, Others End User: Food Services, Retail Stores, Catering Companies, Events Packaging Type: Bagged, Bulk Pack, Individually Wrapped, Eco-Friendly Packaging |
| Companies Covered | Fuling, D&W Fine Pack, Huhtamaki, Tair Chu Enterprise, Anny's Plastic Tableware, Dart Container, Georgia-Pacific, BKS Plastics, Pactiv Evergreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Cutlery Market Strategic Shifts
Bio-based material formulations and manufacturing process intensification are reconfiguring competitive economics in disposable tableware. Converters now compete on certification breadth and composting infrastructure partnerships rather than unit cost alone.
Polylactic acid and polyhydroxyalkanoate blends are rewriting material specifications for quick-service restaurant cutlery tenders. Major chains in the United States and Western Europe now require third-party compostability certification as a table-stakes qualification criterion. This shift is compressing addressable market share for conventional polypropylene converters without bio-based production lines.
REACH authorization procedures for food-contact additives are tightening impurity thresholds for recycled content incorporation. European converters face extended testing timelines for rPP (recycled polypropylene) cutlery formulations intended for single-use applications. Small and mid-scale manufacturers without in-house regulatory affairs capabilities are ceding tender participation to integrated packaging groups with dedicated compliance teams.
Consolidated procurement desks at multi-unit restaurant operators are unbundling cutlery from broader foodservice packaging contracts. Buyers now negotiate utensil specifications separately from cups and containers, enabling material-specific supplier selection. This pattern is most pronounced in the United States, where institutional purchasing cooperatives have established standalone cutlery RFPs with explicit sustainability scoring weights.
Plastic Cutlery Market Segmentation
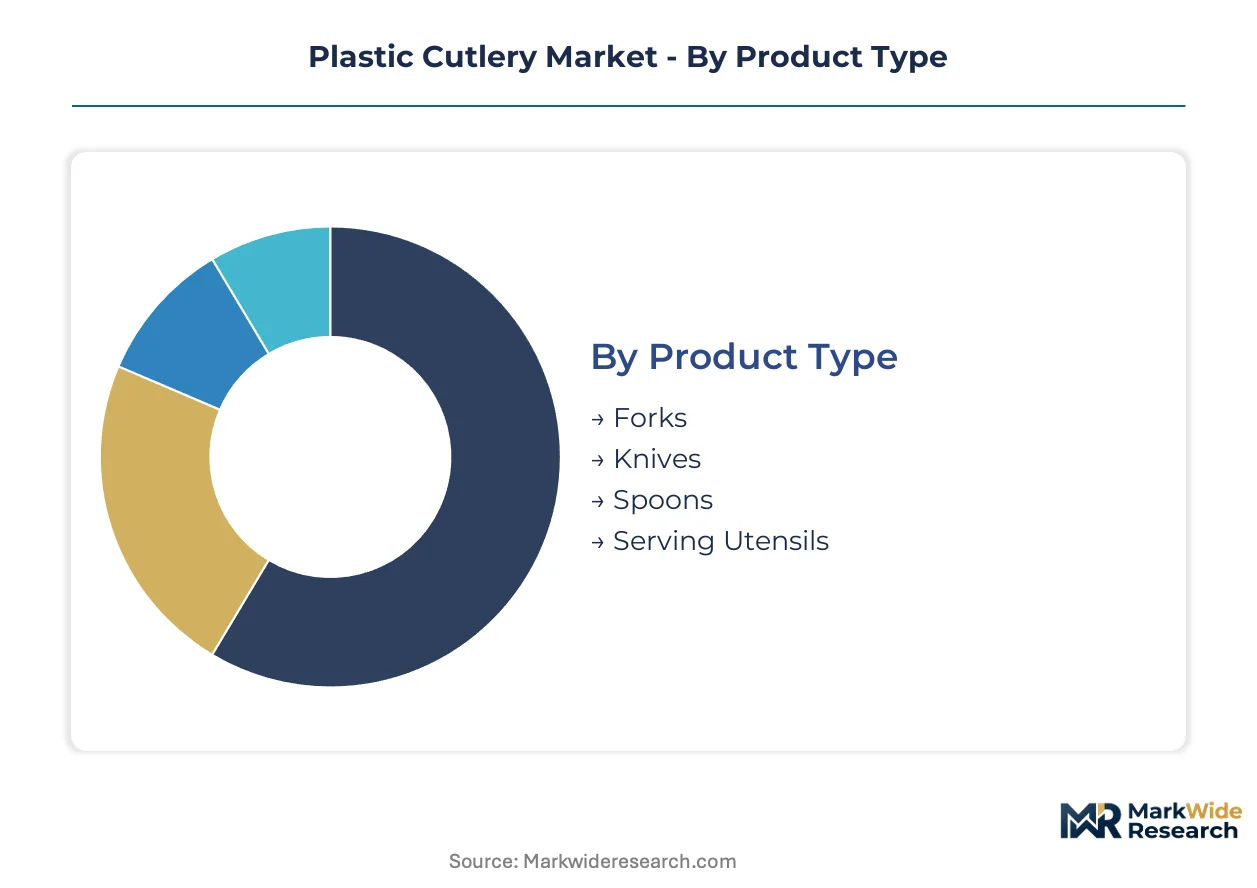
Segmentation in plastic cutlery reveals how procurement specifications diverge across foodservice channels. Material choices and packaging formats now carry compliance weight that rivals unit economics in supplier selection.
Product Type:
Standardization dominates forks and spoons while knives and serving utensils demand higher engineering tolerances for edge retention and load-bearing performance.
- Forks:Four-tine designs in 1.8–2.2 millimeter polypropylene wall thickness handle the broadest menu applications across quick-service and institutional dining. U.S. quick-service restaurant procurement concentrates here due to universality across protein, salad, and carbohydrate formats.
- Spoons:Bowl depth and handle rigidity vary by soup versus dessert applications, with 3.0 millimeter walls specified for hot-liquid service. Demand clusters in U.S. institutional foodservice where heat resistance requirements exclude thinner polystyrene alternatives.
- Knives:Serrated edge retention in injection-molded resins requires higher melt-flow index formulations.
- Serving Utensils:Larger cavity designs for buffet and catering portions carry premium positioning.
Leading the category by volume: Forks. Expanding most quickly: Serving utensils as catered events normalize.
Material:
Cost tiers separate commodity resins from certified alternatives, with compliance premiums widening the spread between polypropylene and bio-based formulations.
- Polypropylene:Homopolymer and random copolymer grades deliver heat deflection temperatures above 100°C, qualifying for soup and hot-beverage applications where polystyrene fails. U.S. institutional buyers sustain volumes despite EU regulatory compression.
- Polystyrene:General-purpose and high-impact grades occupy the economy tier with inferior thermal performance but 15–20% unit cost advantage in cold-service applications.
- Bio-Based Plastic:Polylactic acid and polyhydroxyalkanoate blends carry third-party compostability certifications required by major quick-service chains with net-zero commitments.
- Others:Recycled-content polypropylene and experimental starch blends occupy niche positions pending REACH authorization timelines.
Highest volume concentration: Polypropylene. Steepest expansion trajectory: Bio-based plastic as procurement mandates outpace manufacturing scale.
End User:
Customer type determines order frequency, specification complexity, and sustainability scoring weights in supplier qualification.
- Food Services:Quick-service restaurants and institutional dining operations drive recurring bulk procurement with standardized specifications and direct distribution relationships.
- Retail Stores:Consumer packaged goods channels require retail-ready bagged configurations with barcode and branding compliance.
- Catering Companies:Event-driven demand with high variability in order timing and custom packaging requirements.
- Events:Stadium, festival, and conference procurement increasingly mandates compostable-only specifications.
Primary volume source: Food services. Gaining share fastest: Events as sustainability clauses penetrate temporary foodservice contracts.
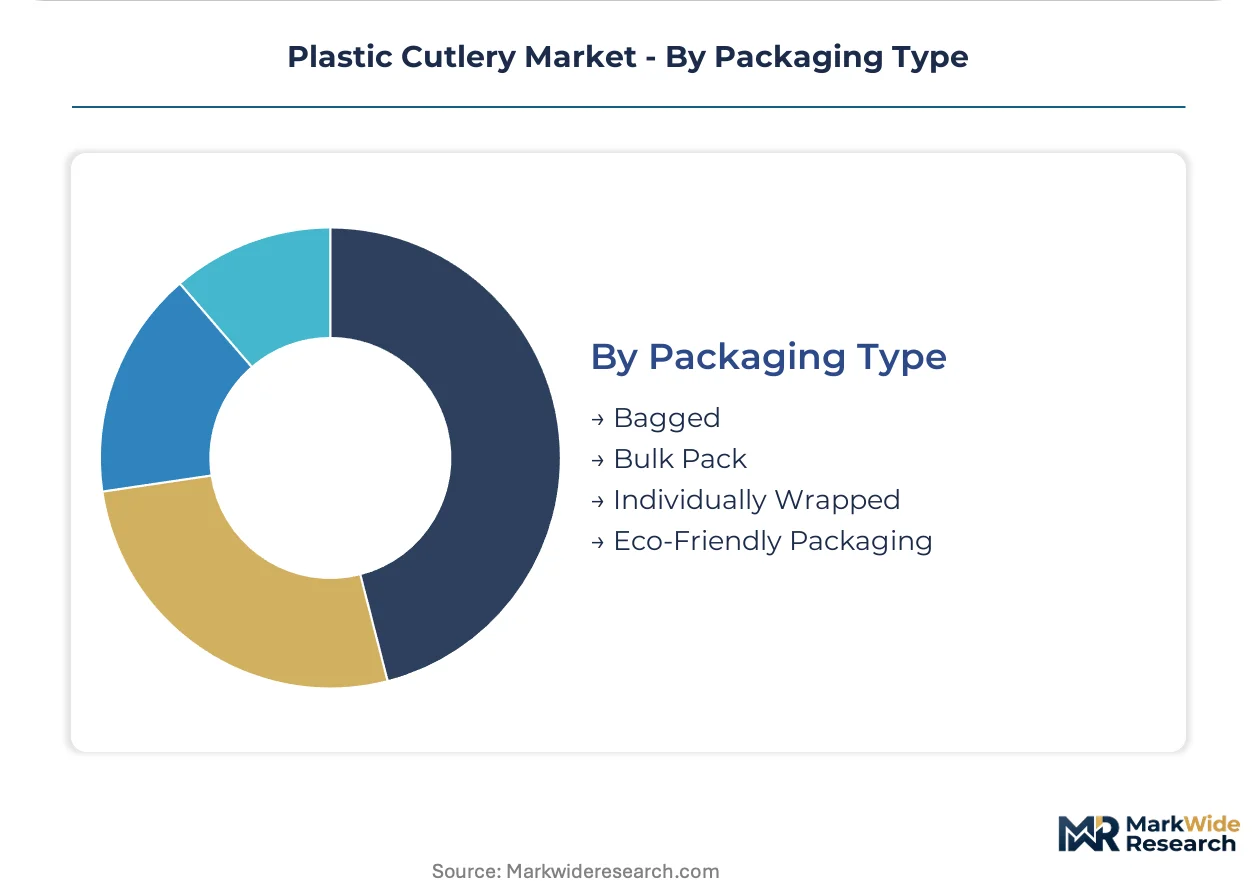
Packaging Type:
Packaging configuration directly affects logistics economics and food safety compliance across distribution channels.
- Bagged:Polyethylene or paper outer bags containing 50–100 units dominate retail and small-foodservice channels where inventory turnover varies.
- Bulk Pack:Unwrapped case quantities of 500–1,000 units minimize per-piece packaging cost for high-throughput institutional kitchens with dedicated storage.
- Individually Wrapped:Polypropylene or paper sleeve enclosures required for healthcare, airline, and grab-and-go retail where cross-contamination protocols apply.
- Eco-Friendly Packaging:Recycled paper or certified compostable film wrappers align with corporate sustainability disclosures.
Dominant configuration: Bulk pack. Climbing the fastest: Eco-friendly packaging as extended producer responsibility fees penalize conventional plastic overwrap.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock availability along the U.S. Gulf Coast anchors North American polypropylene cutlery manufacturing, while Chinese resin-to-finished-product integration drives export pricing power across Asia-Pacific trade corridors.
United States
Quick-service restaurant procurement desks in Dallas and Chicago sustain bulk polypropylene fork and spoon volumes despite sustainability headwinds. The FDA governs food-contact material safety, with state-level bans in California, New York, and Washington fragmenting compliance requirements. Houston-area resin production feeds injection-molding operations across Texas and the Southeast.
China
Molded-fiber thermoforming clusters in Zhejiang and Guangdong provinces have achieved export competitiveness that undercuts European pricing. The MIIT oversees industrial standards for food-contact plastics, while dual carbon goals pressure converters toward bio-based material transitions. Fuling anchors integrated resin-to-cutlery operations in Taizhou.
Germany
REACH authorization procedures tighten impurity thresholds for recycled polypropylene formulations, extending testing timelines for converters. The EU Single-Use Plastics Directive mandates consumption reduction targets across member states. Industrial packaging groups in North Rhine-Westphalia leverage dedicated regulatory affairs teams to maintain tender participation.
India
Organized quick-service penetration in tier-2 cities generates first-wave disposable cutlery demand from international and domestic chain formats. The FSSAI governs food-contact material safety standards. Manufacturing activity concentrates in Maharashtra and Gujarat where foodservice packaging converters serve expanding urban markets.
Japan
Convenience store and railway bento culture sustains premium-tier individually wrapped cutlery specifications. METI oversees industrial standards and circular economy policy implementation. Osaka-based converters supply precision-molded utensils for airline and hospitality channels requiring cross-contamination protocols.
Plastic Cutlery Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and compostability partnerships as differentiation vectors. The vendor base spans integrated resin converters, specialized foodservice packaging groups, and regional injection-molding operations. Three archetypes dominate: Gulf Coast resin-integrated manufacturers, Asian export-oriented thermoformers, and European sustainability-focused converters. Competitive moves concentrate on thermoforming equipment upgrades for lighter-weight compliance and direct distribution bypass of traditional foodservice intermediaries.
Among Asia-Pacific fabricators, Fuling and Tair Chu Enterprise exemplify resin-integrated cost leadership, while Huhtamaki anchors European demand through broad foodservice packaging portfolios. Pactiv Evergreen occupies North American manufacturing scale positions with institutional distribution reach. These three represent distinct geographic and structural archetypes rather than direct competitors across all procurement channels.
| Leading Market Players |
|---|
| Fuling |
| D&W Fine Pack |
| Huhtamaki |
| Tair Chu Enterprise |
| Anny's Plastic Tableware |
| Dart Container |
| Georgia-Pacific |
| BKS Plastics |
| Pactiv Evergreen |
| Others |
Value Chain & Pricing Dynamics
EU Single-Use Plastics Directive compliance gates qualified supply access and premium-tier pricing power, as converters without certified bio-based production lines forfeit quick-service restaurant procurement windows while certified suppliers capture 15–25% price premiums over conventional polypropylene alternatives.
Pricing Analysis
Certification bundling separates quoted prices, with third-party compostability credentials included in premium tiers while bare resin-grade products compete on spot-market terms. Three-tier pricing structure across certified bio-based, virgin polypropylene, and recycled-content grades tracks feedstock volatility and regulatory risk. Price erosion runs through polystyrene alternatives as quick-service restaurants abandon heat-deficient formulations. Institutional buyers in U.S. hospital and university systems exhibit lowest price sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Compostability certification gates supplier qualification for European quick-service tenders and North American chain sustainability programs. Resin-to-finished-product integration concentrates in China, the United States, and Germany, with propylene feedstock availability along the U.S. Gulf Coast and Zhejiang province manufacturing clusters anchoring cost positions. Supply chains draw from polypropylene pellet, polystyrene resin, and polylactic acid biopolymer inputs. Single-source vulnerability in Chinese molded-fiber thermoforming equipment threatens European converter expansion timelines. Distribution runs through institutional procurement cooperatives and direct quick-service restaurant contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around converters with integrated regulatory affairs capabilities, as REACH authorization timelines and composting infrastructure gaps force smaller injection-molding operations into acquisition or exit.
For Market Incumbents: Deepen backward integration into bio-based resin supply through offtake agreements with polylactic acid producers, insulating margin positions from propylene monomer spikes. Expand thermoforming capacity in Texas and Southeast U.S. states to bypass logistics costs serving institutional buyers. Secure third-party compostability certification breadth ahead of quick-service restaurant 2030 net-zero deadlines to defend share against emerging European sustainability-focused entrants. For New Entrants and Emerging Players: EU Single-Use Plastics Directive in member states opens a window for certified bio-based cutlery specialists to capture quick-service procurement windows vacated by polypropylene-dependent incumbents. Target Indian tier-2 city quick-service expansion where organized foodservice penetration generates first-wave disposable utensil demand. Pursue direct distribution partnerships with hospital systems and university foodservice cooperatives, bypassing traditional distribution intermediaries that incumbent converters dominate. For Investors and Strategic Acquirers: Consolidated procurement desk establishment at multi-unit restaurant operators is the leading indicator that standalone cutlery RFPs with explicit sustainability scoring will concentrate supplier selection power among certified converters. Five-to-ten-year viability favors integrated packaging groups with dedicated regulatory compliance teams over pure-play injection molders. Acquisition targets include mid-scale European converters with REACH authorization expertise and idle thermoforming capacity suitable for bio-based material retooling.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Bio-Based Production Line Addition | Third-party compostability credentials unlock quick-service restaurant procurement windows ahead of regulatory deadlines. |
| Direct Distribution Network Buildout | In-house logistics capabilities bypass foodservice intermediaries and capture institutional buyer consolidation benefits. |
| Thermoforming Equipment Upgrade Program | Lighter-weight designs reduce EU Extended Producer Responsibility fees and improve compliance cost economics. |
| Composting Infrastructure Partnership | Collaborations with industrial composting operators resolve disposal confusion and brand risk for operator customers. |
| Recycled Content Formulation Investment | rPP cutlery development addresses REACH authorization timelines and sustainability procurement scoring weights. |
Study Parameters
Independent corroboration across quick-service restaurant procurement executives, foodservice packaging converters, regulatory affairs consultants, and industrial composting operators underwrites the qualitative findings. Primary interview data triangulates against customs and trade flow records, SEC 10-K filings from disclosed foodservice packaging segments, EU Single-Use Plastics Directive implementation reports, and FDA food-contact material guidance documents. Bottom-up demand modeling across quick-service, institutional, retail, and catering channels reconciles with top-down resin consumption estimates.
Comparable-period anchoring to pre-pandemic procurement baselines and post-normalization traffic patterns establishes volume reference points across the projection horizon. Segmentation dimensions span product type, material formulation, end-user channel, and packaging configuration, with explicit modeling of bio-based plastic adoption curves against regulatory phase-in schedules. CAGRs derive from weighted-average growth across segment-specific demand drivers, incorporating propylene feedstock price elasticity and quick-service restaurant traffic recovery assumptions.
The model assumes a particular technology adoption path; alternative pathways for polylactic acid heat-performance improvement or polyhydroxyalkanoate cost reduction would alter the outlook for bio-based displacement timelines. Forecasts reflect assumptions regarding EU member state enforcement consistency and U.S. federal packaging legislation progression. A model refresh is warranted upon material change in quick-service restaurant net-zero commitment acceleration or industrial composting facility buildout rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
China Plastic Packaging Market