
 Middle East and Africa Plastic Packaging Market | 2026-2036
Middle East and Africa Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plastic Packaging Market Foresight
The split between premium barrier films and commodity-grade polyethylene sheeting is realigning procurement patterns across the Middle East and Africa. SABIC leverages its upstream petrochemical base to dominate regional resin supply. Berry Global Inc anchors its position through specialized healthcare and food-grade container lines. Napco National differentiates via integrated manufacturing spanning films, bags, and rigid formats for Saudi industrial buyers.
Middle East and Africa plastic packaging encompasses fabricated polymer structures designed to contain, protect, and distribute goods, typically manufactured through extrusion, blow molding, or thermoforming processes with thicknesses ranging from micron-level films to millimeter-wall containers. Its primary commercial purpose centers on extending shelf stability, enabling bulk logistics, and supporting retail presentation across temperature-variable climates. Polyethylene retains the largest volume share due to cost efficiency and blow-molding compatibility, while PET gains ground in beverage applications demanding clarity and recyclability. Films lead growth trajectory among product types, driven by fresh-produce export requirements and e-commerce fulfillment expansion.
Saudi Standards, Metrology and Quality Organization (SASO) mandates govern material migration limits and labeling protocols for food-contact plastics in the Kingdom. South Africa's National Regulator for Compulsory Specifications enforces polymer identification codes and recyclability thresholds that reshape converter compliance costs. The UAE's Emirates Authority for Standardization and Metrology (ESMA) maintains technical regulations on biodegradable additives and heavy-metal content. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclate-content mandates that will determine which material streams retain market access.
Market Dynamics
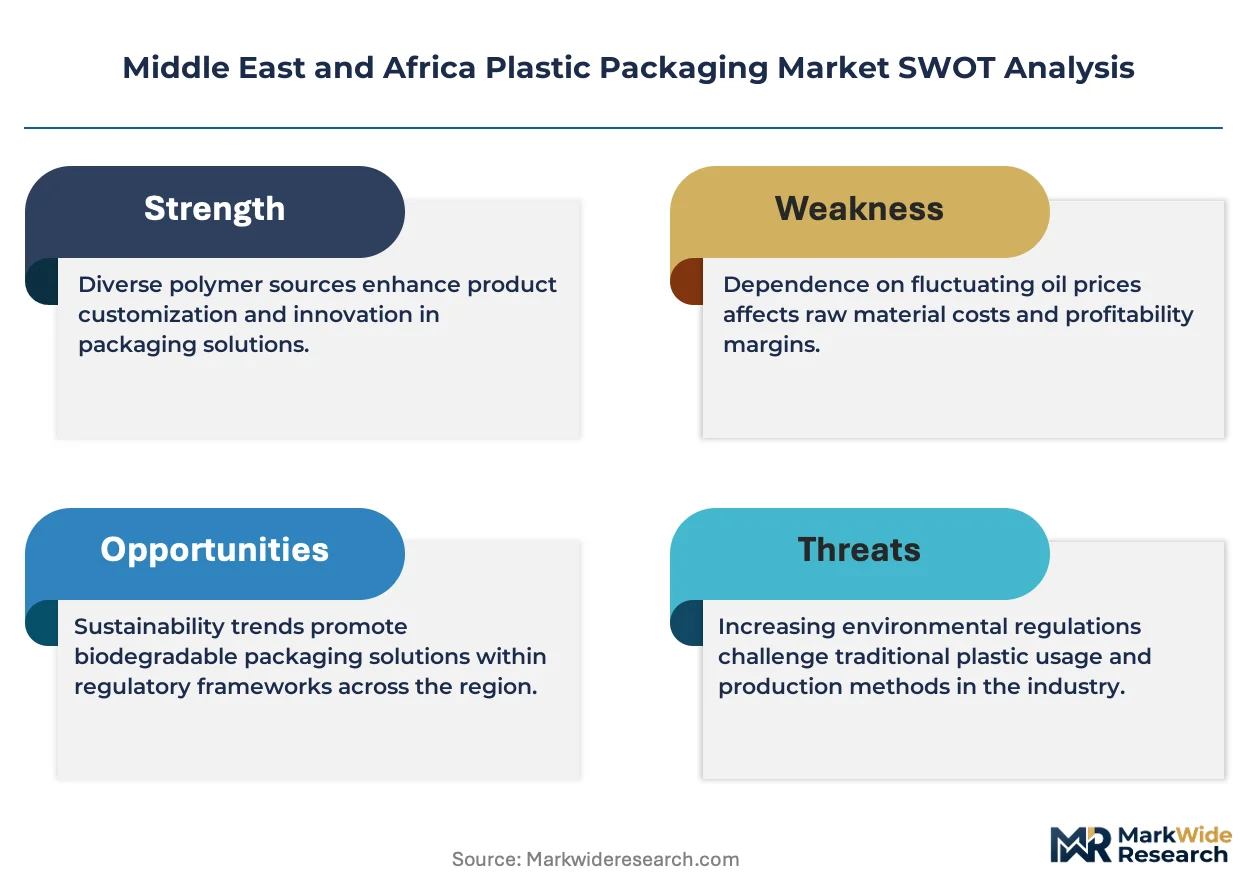
Saudi Arabia's circular economy mandates and the UAE's technical regulations on plastic safety are compressing material specifications across the Middle East and Africa, forcing converters to requalify resin grades and additive packages ahead of recyclate-content deadlines.
Growth Catalysts
- Food-contact compliance mandates:SASO migration limits and ESMA heavy-metal thresholds are accelerating replacement of non-compliant legacy films with certified barrier structures in Saudi Arabia and the UAE.
- Fresh-produce export corridors:Controlled-atmosphere films are gaining traction among Egyptian and Moroccan agricultural exporters targeting European retail chains with extended shelf-life requirements.
- Petrochemical feedstock access:Saudi Arabia's integrated ethylene-to-polymer complexes provide regional converters with cost-advantaged polyethylene supply unavailable to Asian or European competitors.
Market Restraints
- Crude-linked resin volatility:Polyethylene and polypropylene pricing tied to naphtha and ethane feedstocks exposes converters to margin compression when oil benchmarks fluctuate.
- Monoculture supply risk:SABIC and regional Gulf producers control over 70% of virgin resin supply, creating concentration vulnerability for converters without backward integration.
- Mechanical recycling limitations:Contamination rates in post-consumer film streams exceed 15% in most African markets, degrading recyclate quality below food-contact thresholds.
Strategic Opportunities
- Nigerian manufacturing localization:Dangote Refinery's polypropylene output creates captive resin availability for Lagos-based converters serving West African consumer goods demand.
- Extended producer responsibility frameworks:South Africa's pending packaging waste regulations will mandate producer-funded collection systems, opening service-contract opportunities for integrated waste-to-resin operators.
- Chemical recycling convergence:Pyrolysis and gasification technologies paired with polymer production are enabling food-grade recyclate output from mixed plastic waste streams currently landfilled.
Industry Challenges
- Migration testing capacity:SASO and ESMA certification timelines stretch 8-14 months due to limited accredited laboratory availability in the Gulf, delaying product launches.
- Skilled extrusion engineering:Multi-layer coextrusion and barrier coating expertise remains concentrated in European and Asian technical centers, requiring expatriate staffing for complex film projects.
- Legacy equipment retrofit costs:Converters running single-screw extruders face six-figure capital outlays to process higher recyclate percentages without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plastic Packaging Market |
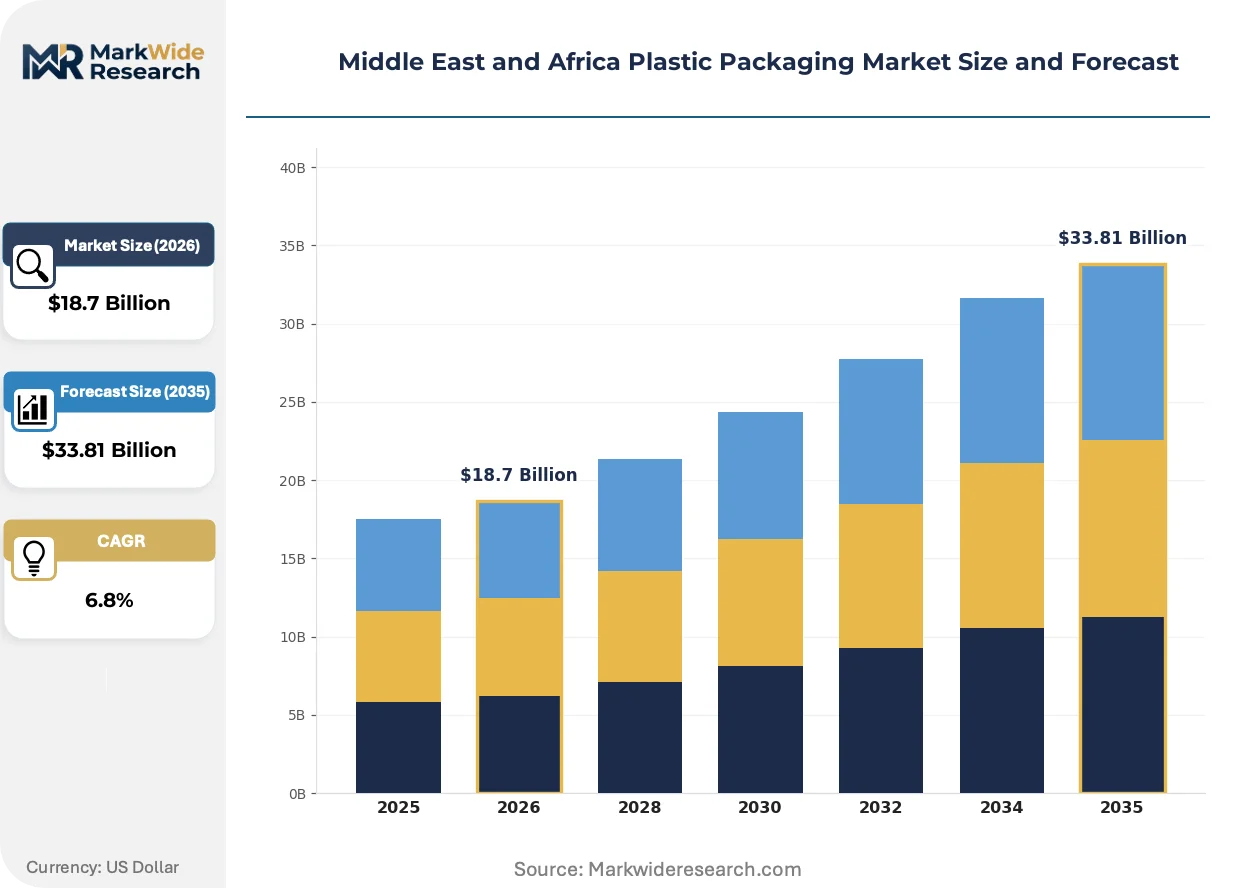
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Boxes, Containers, Films Material: Polyethylene, Polypropylene, PET, PVC End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Application: Retail, Industrial, Agriculture, Healthcare |
| Companies Covered | Berry Global Inc, SABIC, Napco National, Falcon Pack, Zamil Plastic Industries Co., Takween Advanced Industries, Huhtamaki South Africa (Pty) Ltd, ENPI Group, Amcor Group GmbH, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plastic Packaging Market Shifts & Advancements
Active barrier technologies and regulatory compliance automation are compressing product development cycles across the Middle East and Africa. Converters are racing to integrate real-time quality verification and circular material traceability into standard production workflows.
Multi-layer coextrusion with ethylene vinyl alcohol and polyamide barriers is unifying oxygen and moisture protection in a single film structure. Saudi dairy and meat processors are adopting these materials at 20-25% annual expansion rates. The technology is unifying previously separate packaging steps—vacuum forming, gas flushing, and overwrapping—into integrated thermoforming lines that reduce labor and floor space requirements.
SASO's 2024 updates to biodegradable additive standards and the UAE's Emirates Authority for Standardization and Metrology certification pathways for compostable films are creating dual-track compliance frameworks. Industrial consequences include forced separation of oxo-degradable and truly biodegradable material streams in converter portfolios. Food-contact applications in the Gulf Cooperation Council states face the steepest requalification burdens, with several converters abandoning oxo-additive formulations entirely.
Consolidated procurement by Saudi and UAE retail conglomerates is compressing supplier rosters and demanding consolidated invoicing across film, rigid container, and labeling categories. Regional hypermarket chains are replacing fragmented spot purchasing with two-year framework agreements specifying volume commitments and sustainability reporting. Egyptian and Jordanian converters report the most intense margin pressure from this consolidation, lacking the scale to meet minimum volume thresholds.
Middle East and Africa Plastic Packaging Market Segmentation
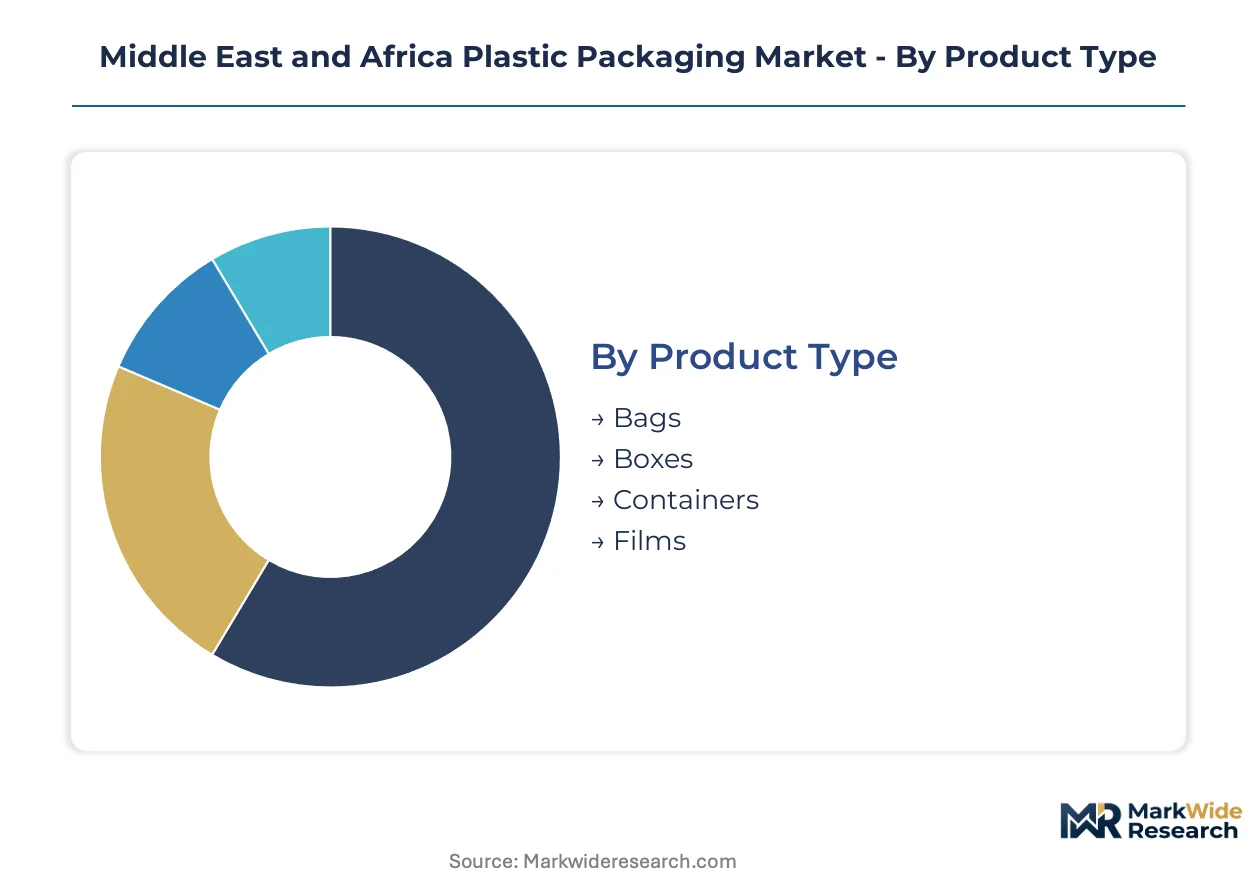
Segmentation in Middle East and Africa plastic packaging reveals how capital deployment, feedstock access, and regulatory pressure distribute value across material grades and product formats. Converters allocate extrusion and molding capacity based on which combinations of resin type, end-use certification, and barrier specification yield the most defensible margins.
Product Type:
Films and containers demand the heaviest upfront investment in multi-layer coextrusion lines and barrier coating equipment, while bags and boxes run on simpler single-screw extruders or thermoforming stations with shorter depreciation cycles.
- Films:Multi-layer coextrusion structures incorporate ethylene vinyl alcohol and polyamide barriers to unify oxygen and moisture protection. Saudi dairy and meat processors are adopting these materials at 20-25% annual expansion rates, driven by SASO food-contact compliance mandates that disqualify legacy monolayer alternatives.
- Containers:Rigid formats span blow-molded bottles, injection-molded tubs, and thermoformed trays with wall thicknesses from 0.5mm to 3mm. Egyptian and Moroccan agricultural exporters targeting European retail chains are concentrating demand for controlled-atmosphere containers with extended shelf-life specifications.
- Bags:Polyethylene sheeting dominates commodity applications from retail carryout to industrial liners, with thickness gradients from 25-micron lightweight to 150-micron heavy-duty specifications.
- Boxes:Corrugated plastic and rigid thermoformed cases serve reusable logistics and produce crating, particularly in South African citrus export corridors and UAE pharmaceutical distribution hubs.
Containers absorb the bulk of installed capacity; films are expanding most quickly.
Material:
Resin selection tracks end-use performance requirements and recyclability positioning under tightening Gulf Cooperation Council regulations.
- Polyethylene:Low-density and linear low-density grades retain the largest volume share due to blow-molding compatibility and cost efficiency. SABIC's integrated ethylene-to-polymer complexes provide Saudi converters with cost-advantaged supply unavailable to Asian or European competitors.
- PET:Bottle-grade and sheet-grade polyethylene terephthalate gains ground in beverage applications demanding clarity and mechanical recyclability. South Africa's National Regulator for Compulsory Specifications enforces polymer identification codes that favor PET's established recycling infrastructure over PVC alternatives.
- Polypropylene:Homopolymer and copolymer grades serve hot-fill containers, caps, and closures with temperature resistance to 120°C. Dangote Refinery's polypropylene output creates captive resin availability for Lagos-based converters serving West African consumer goods demand.
- PVC:Rigid and plasticized formulations persist in blister packaging and medical applications despite environmental pressure, with migration testing requirements under SASO and ESMA protocols constraining food-contact use.
Polyethylene commands the deepest installed base; PET is climbing the fastest on recyclability premiums.
End User:
Customer concentration and certification burden vary sharply across sectors, with pharmaceutical and food-contact applications demanding the most extensive compliance documentation.
- Food & Beverage:Dairy, meat, and fresh-produce packaging dominate volume, with SASO migration limits and ESMA heavy-metal thresholds accelerating replacement of non-compliant legacy films with certified barrier structures in Saudi Arabia and the UAE.
- Pharmaceuticals:Blister packs, vials, and sterile containers require ISO 15378 compliance and child-resistant closure certification. Berry Global Inc anchors regional supply through specialized healthcare container lines with dedicated cleanroom manufacturing.
- Cosmetics:Premium tubes, jars, and airless dispensers emphasize aesthetic differentiation and shelf appeal, with Dubai and Riyadh retail corridors driving demand for metallized and soft-touch finishes.
- Household:Detergent bottles, cleaning spray triggers, and storage containers prioritize cost optimization over barrier performance, with Egyptian and Jordanian converters reporting intense margin pressure from consolidated procurement by Saudi and UAE retail conglomerates.
Food & Beverage holds the largest revenue pool; Pharmaceuticals is gaining share fastest on compliance premiums.
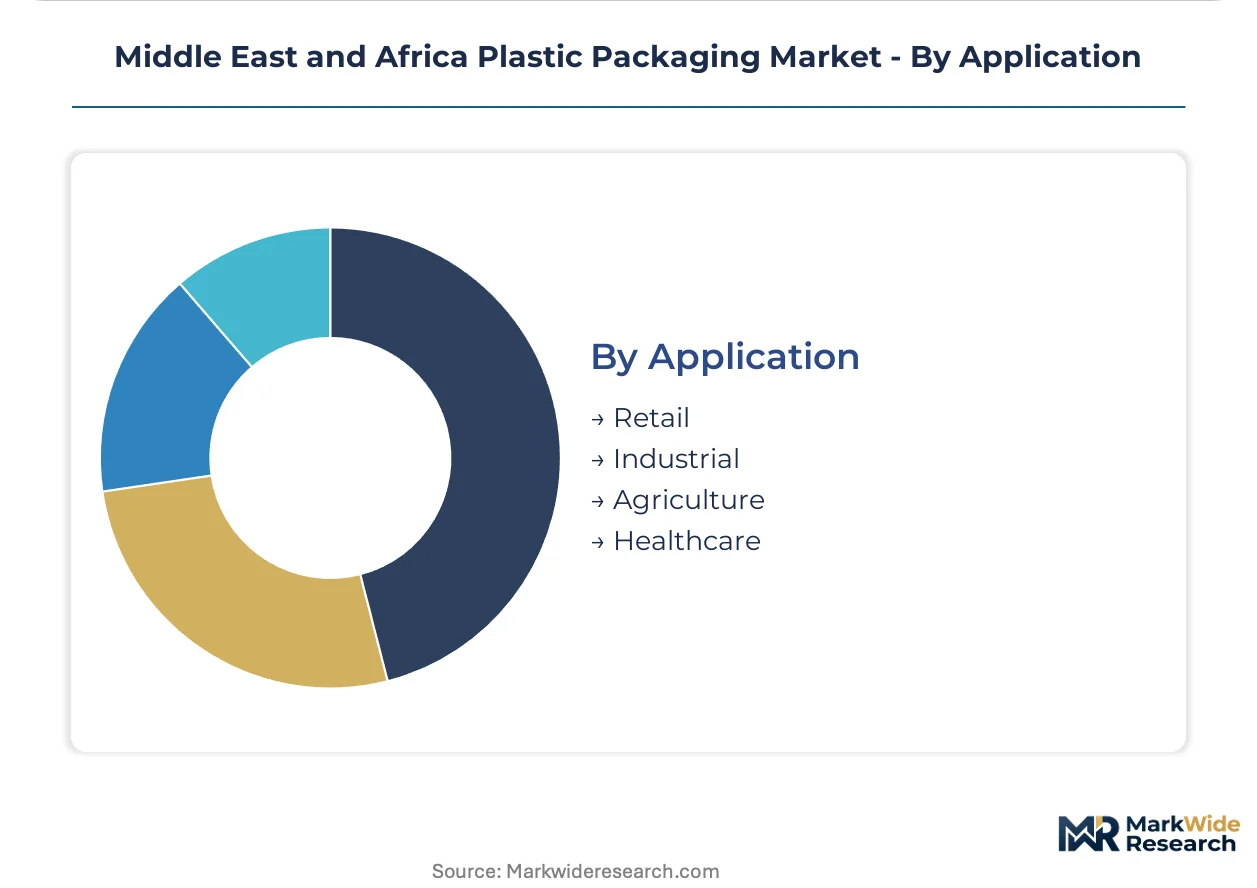
Application:
Channel requirements dictate format mix, with retail and healthcare demanding the most sophisticated barrier and presentation specifications.
- Retail:Hypermarket and e-commerce fulfillment formats emphasize shelf-ready presentation, tamper evidence, and consolidated invoicing across film, rigid container, and labeling categories. Regional chains are replacing fragmented spot purchasing with two-year framework agreements specifying volume commitments and sustainability reporting.
- Healthcare:Sterile barrier systems, unit-dose packaging, and temperature-controlled distribution demand multi-layer structures with validated seal integrity. SASO and ESMA certification timelines stretch 8-14 months due to limited accredited laboratory availability in the Gulf.
- Industrial:Bulk sacks, drum liners, and pallet wrap prioritize tensile strength and UV stability for construction and chemical logistics across the GCC and North Africa.
- Agriculture:Mulch films, silage wrap, and controlled-atmosphere produce packaging serve export-oriented farming in Egypt, Morocco, and South Africa, with European retail chain specifications driving barrier performance requirements.
Retail commands the deepest customer relationships; Healthcare is expanding most quickly on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors Middle East and Africa plastic packaging activity through Saudi Arabia's integrated ethylene-to-polymer complexes. The region's demand concentrates in Gulf Cooperation Council petrochemical corridors and North African export agriculture zones. Regulatory divergence between SASO compliance mandates and South Africa's extended producer responsibility frameworks is fragmenting converter strategies.
Saudi Arabia
Dairy and meat processors in Riyadh and Jeddah are adopting multi-layer barrier films at 20-25% annual expansion rates. SASO migration limits and heavy-metal thresholds are accelerating replacement of non-compliant legacy films with certified structures. Jubail's petrochemical integration provides regional converters with cost-advantaged polyethylene supply unavailable to Asian or European competitors.
United Arab Emirates
Dubai's retail conglomerates are consolidating procurement across film, rigid container, and labeling categories through two-year framework agreements. ESMA technical regulations on biodegradable additives and heavy-metal content are creating dual-track compliance frameworks for compostable films. Sharjah's logistics infrastructure supports large-scale packaging consumption for re-export throughout the Gulf and East Africa.
South Africa
Citrus export corridors in the Western Cape are driving demand for controlled-atmosphere containers with extended shelf-life specifications. The National Regulator for Compulsory Specifications enforces polymer identification codes and recyclability thresholds that reshape converter compliance costs. Johannesburg-based converters face pending packaging waste regulations mandating producer-funded collection systems.
Egypt
Agricultural exporters in the Nile Delta are targeting European retail chains with barrier film requirements for fresh-produce shipments. The country's national standards body maintains technical regulations on food-contact plastics that align with Gulf Cooperation Council protocols. Alexandria's port infrastructure supports controlled-atmosphere film distribution across Mediterranean trade routes.
Nigeria
Lagos-based converters are positioning to capture West African consumer goods demand through localized manufacturing. Dangote Refinery's polypropylene output creates captive resin availability for domestic packaging production. The Lekki Free Trade Zone is emerging as a concentration point for industrial film and container fabrication serving Nigerian retail expansion.
Middle East and Africa Plastic Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and barrier technology sophistication. The market structure divides between petrochemical-integrated resin suppliers, specialized healthcare and food-grade container fabricators, and integrated film-to-rigid converters serving industrial buyers. Three archetypes dominate: upstream-integrated resin producers with captive polymer supply, compliance-specialized healthcare packaging operators with cleanroom manufacturing capabilities, and diversified regional converters spanning multiple product formats. Competitive moves concentrate on strategic partnerships with retail conglomerates and portfolio diversification into barrier coating technologies.
Among Gulf-based petrochemical-integrated operators, SABIC represents the upstream-resin archetype through its ethylene-to-polymer complexes. Berry Global Inc exemplifies the compliance-specialized tier with healthcare and food-grade container lines. Napco National occupies a position as an integrated manufacturer spanning films, bags, and rigid formats for Saudi industrial buyers.
| Leading Market Players |
|---|
| Berry Global Inc |
| SABIC |
| Napco National |
| Falcon Pack |
| Zamil Plastic Industries Co. |
| Takween Advanced Industries |
| Huhtamaki South Africa (Pty) Ltd |
| ENPI Group |
| Amcor Group GmbH |
| Others |
Supply & Pricing Matrix
Consolidated procurement by Saudi and UAE retail conglomerates is compressing supplier margins and forcing converters toward long-term framework agreements that sacrifice spot-market pricing flexibility for volume security.
Pricing Analysis
Food-contact certification premiums anchor pricing stratification across barrier film grades. Three-tier pricing structure across premium, standard, and economy levels separates SASO-compliant multi-layer structures from commodity polyethylene sheeting. Cost compression in Egyptian and Jordanian converter tiers is intensifying because these players lack scale to meet minimum volume thresholds demanded by consolidated buyers. Household and industrial segments exhibit highest price sensitivity; pharmaceutical and dairy applications tolerate premium pricing for compliance assurance.
Supply Chain Analysis
Freight costs from Jubail Industrial City to North African conversion hubs erode margin competitiveness for Saudi resin against local Mediterranean supply. Raw material flows draw from Saudi ethylene-to-polymer complexes, Egyptian naphtha crackers, and Nigerian Dangote polypropylene output. Single-source vulnerability concentrates around SABIC's dominance of virgin polyethylene supply. Distribution runs through Sharjah logistics corridors for Gulf re-export and Alexandria port infrastructure for Mediterranean trade routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Migration testing capacity constraints at Gulf-accredited laboratories create a supply bottleneck that props pricing for certified barrier structures and delays competitive entry.
For Market Incumbents: Anchor market position through backward integration into captive resin supply and dedicated cleanroom manufacturing for healthcare applications. SASO's tightening migration limits threaten non-compliant legacy film portfolios; invest in multi-layer coextrusion capability to defend certification tier access. Prioritize two-year framework agreements with retail conglomerates to lock volume commitments ahead of new entrant qualification. For New Entrants and Emerging Players: Enter via Nigerian manufacturing localization leveraging Dangote Refinery polypropylene availability and underserved West African consumer goods demand. Target Lagos-based industrial film production serving Nigerian retail expansion. Pursue chemical recycling partnerships to bypass mechanical recycling quality limitations and access food-grade recyclate markets. For Investors and Strategic Acquirers: Re-rating potential sits with compliance-specialized healthcare packaging operators given SASO and ESMA certification timeline bottlenecks. Long-term viability favors converters with demonstrated cleanroom manufacturing and ISO 15378 track records. Monitor extended producer responsibility framework implementation in South Africa as inflection indicator for waste-to-resin operator valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Coextrusion Capacity Expansion | Enables SASO-compliant barrier film production for Saudi dairy processors replacing legacy monolayer structures. |
| Chemical Recycling Technology Partnership | Unlocks food-grade recyclate from mixed plastic streams currently landfilled across African markets. |
| Backward Integration into Resin Supply | Reduces exposure to SABIC pricing power and crude-linked polyethylene volatility for Egyptian converters. |
| Cleanroom Manufacturing Certification | Qualifies access to pharmaceutical blister pack and sterile container premiums in Dubai healthcare corridors. |
| Extended Producer Responsibility Service Contract | Captures producer-funded collection system mandates under South Africa's pending packaging waste regulations. |
Research Methodology
Independent corroboration across converter procurement directors, petrochemical supply planners, and retail category buyers underwrites the qualitative findings. Primary fieldwork engaged extrusion engineering specialists, SASO accreditation laboratory managers, and agricultural export logistics coordinators. Secondary validation drew from customs trade databases, SASO technical regulation filings, and SEC disclosures by listed packaging operators. Bottom-up resin demand modeling and top-down end-use consumption estimates were cross-referenced for triangulation.
Rate-of-change decomposition across material grade, product format, end-use sector, and regional production hub informed the analytical framework. Segmentation dimensions spanned polyethylene versus PET versus polypropylene resin families, films versus containers versus bags versus boxes, food-contact versus pharmaceutical versus cosmetics versus household applications, and Saudi Arabia versus UAE versus South Africa versus Egypt versus Nigeria geographic clusters. CAGRs were derived from installed capacity expansion announcements, petrochemical feedstock cost trajectories, and regulatory compliance deadline impacts. Forecast inputs incorporated Dangote Refinery polypropylene ramp schedules and South African extended producer responsibility implementation timelines.
Revisions become necessary when crude-linked resin volatility exceeds historical bands, SASO accelerates migration limit timelines, or chemical recycling yields fail to achieve food-contact thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
PET Clamshell Market