
 Asia-Pacific Plastic Bottles and Containers Market | 2026-2036
Asia-Pacific Plastic Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Plastic Bottles and Containers Market Outlook
Multi-source resin procurement is shifting toward captive petrochemical partnerships across the Asia-Pacific plastic bottles and containers landscape. Amcor plc leverages its integrated blow-molding footprint to sustain supply consistency for beverage multinationals. Berry Global Inc anchors regional production through specialized HDPE container lines serving personal care brands. Zhejiang Xinlei Packaging Co Ltd competes on high-volume PET output for domestic Chinese beverage labels.
Asia-Pacific plastic bottles and containers comprise thermoformed and blow-molded vessels manufactured from polyethylene terephthalate, high-density polyethylene, and polyvinyl chloride resins, typically ranging from 100 milliliters to above five liters in calibrated neck-finish diameters for automated filling lines. These vessels store, protect, and distribute liquid and semi-solid consumables across temperature-variable supply chains spanning tropical monsoon climates. PET bottles command the dominant volume position due to carbonated soft drink and bottled water proliferation, while HDPE containers capture margin pools in pharmaceutical and household chemical segments where chemical resistance and moisture barriers prove critical. The 500ml-1L size band experiences accelerated replenishment cycles as single-serve consumption patterns expand in Indonesian and Vietnamese urban centers.
China's SAMR enforces GB standards for food-contact plastics that dictate migration limits and additive transparency, while India's BIS operates mandatory certification schemes for polyethylene packaging materials under the Food Safety and Standards Act. Japan's METI coordinates with JIS standards bodies to regulate recycled content thresholds in beverage-grade PET applications. Stakeholders must monitor evolving extended producer responsibility frameworks across ASEAN member states to preempt compliance-driven cost restructuring.
Market Dynamics
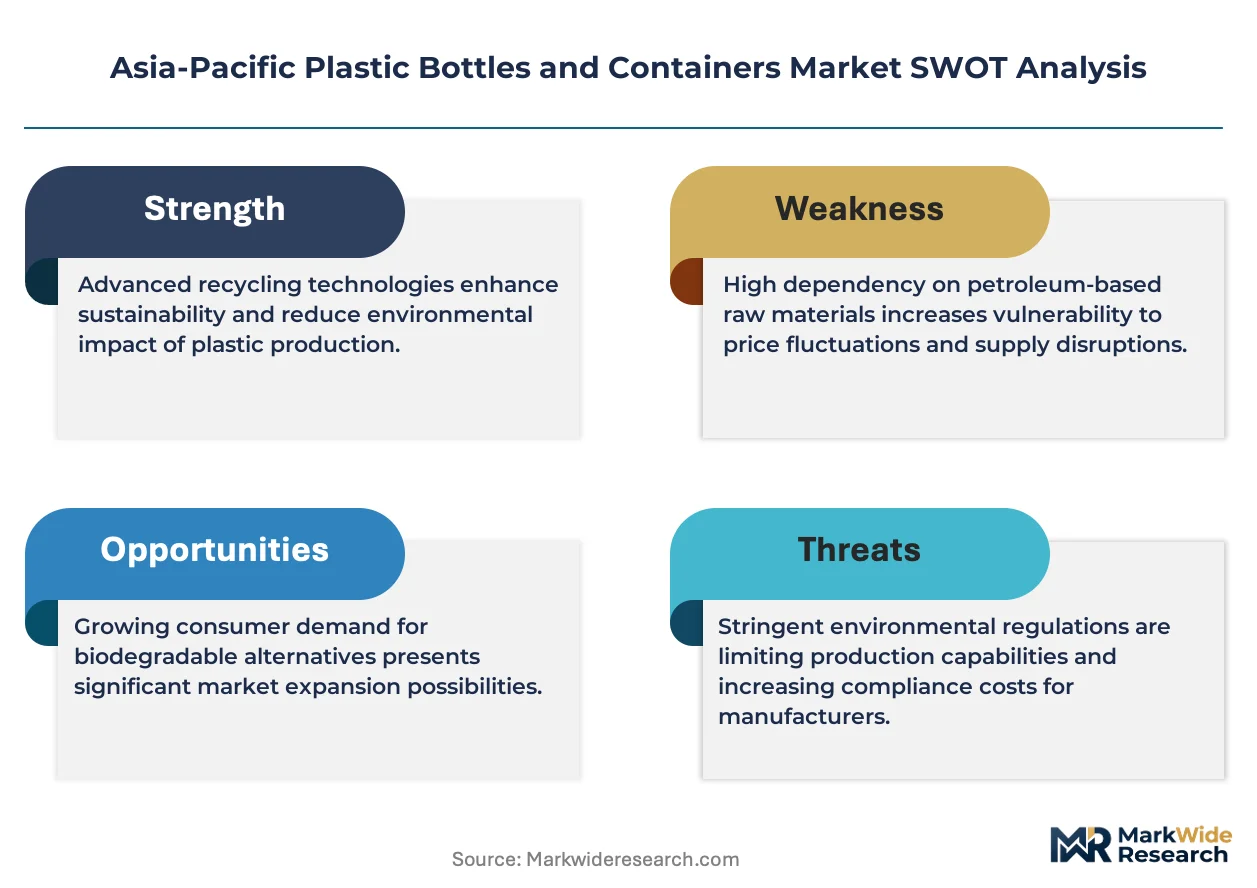
Asia-Pacific plastic bottles and containers face intensifying regulatory pressure on food-contact material safety and recycled content mandates, forcing converters to reconfigure resin sourcing and blow-molding operations across Southeast Asian production networks.
Growth Catalysts
- India's BIS certification expansion:Mandatory polyethylene packaging standards under FSSAI enforcement are compelling domestic processors to upgrade quality systems, pulling compliant capacity expansion in Maharashtra and Gujarat.
- Carbonated beverage line extensions:Southeast Asian bottlers are scaling PET procurement for single-serve formats, tightening supply relationships with regional blow-molding specialists serving tropical distribution chains.
- China's dual carbon framework:Provincial energy intensity targets are accelerating rPET integration in beverage-grade applications, creating captive demand for chemically recycled feedstocks.
Market Restraints
- Crude-linked resin volatility:Naphtha-derived PET and HDPE pricing swings compress converter margins when polymer producers pass through feedstock costs without lag.
- Import dependency in specialty additives:Antioxidant and UV stabilizer supply concentrates among Northeast Asian chemical majors, exposing Southeast Asian compounders to freight and tariff discontinuities.
- Mechanical recycling contamination ceilings:Food-contact rPET remains constrained by legacy additive legacy and colorant variability, limiting closed-loop substitution rates in premium beverage segments.
Strategic Opportunities
- Vietnam's underpenetrated personal care segment:HDPE bottle demand from shampoo and conditioner brands lags regional per-capita benchmarks, offering first-mover positioning for specialized extrusion-blow molders.
- Japan's METI recycled content thresholds:Beverage-grade rPET mandates are creating premium pricing tiers for verified circular material, rewarding early compliance investments.
- Direct-to-retailer digital procurement platforms:Regional e-commerce enablers are disintermediating traditional distributor networks for mid-volume pharmaceutical and cosmetic container orders.
Industry Challenges
- Blow-molding technician scarcity:Specialized machine calibration and mold maintenance skills lag capacity expansion in Indonesian and Vietnamese greenfield plants.
- Extended BIS certification timelines:Indian laboratory backlog and documentation requirements delay new product launches by quarters, freezing working capital in pre-qualified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Plastic Bottles and Containers Market |
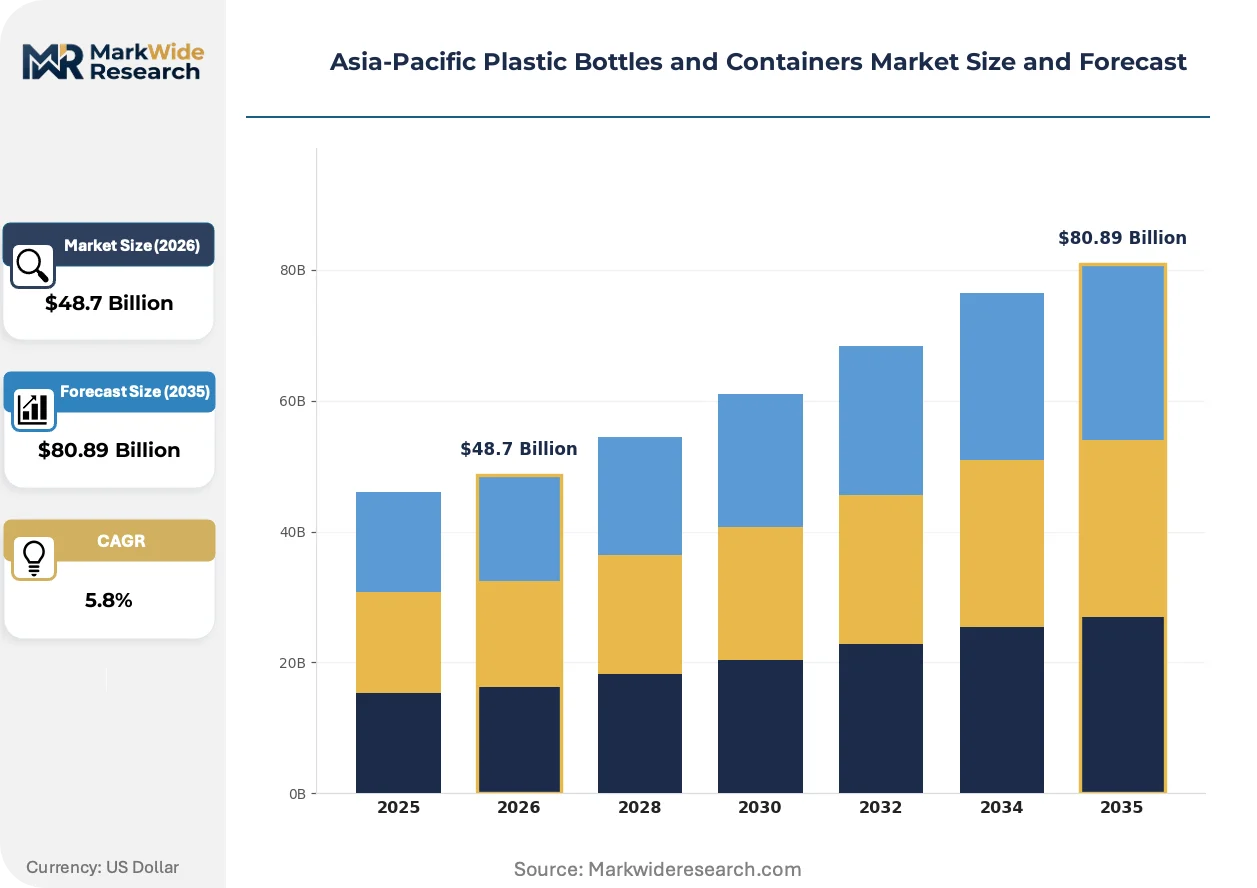
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Containers, PVC Bottles, LDPE Bottles End User: Beverage Industry, Personal Care, Pharmaceutical, Household Size: 100ml-500ml, 500ml-1L, 1L-5L, Above 5L Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Silgan Holdings Inc., Berry Global Inc, Amcor plc, Zhejiang Xinlei Packaging Co Ltd, Manjushree Technopack Limited, ALPLA Werke Alwin Lehner GmbH & Co KG, Pact Group Holdings Ltd., Shanghai Zijiang Enterprise Group Co. Ltd., Gerresheimer AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Plastic Bottles and Containers Market Strategic Shifts
Material science advances and regulatory compliance automation are compressing product development cycles while fragmenting buyer-supplier power dynamics across Asia-Pacific packaging networks.
Lightweighting technology is absorbing structural resin volume from conventional PET bottle designs without sacrificing top-load strength or barrier performance. Japanese beverage multinationals are adopting 20-25% weight-reduced preforms for still water lines, forcing regional converters to retool injection-stretch blow-molding parameters. This compression is absorbing legacy thick-wall designs from premium private-label portfolios.
China's GB standards for food-contact plastics are tightening migration limit testing protocols and additive disclosure requirements under SAMR enforcement. Converters must now maintain batch-level traceability documentation for downstream brand audits, elevating quality management system investments. Pharmaceutical and infant nutrition segments are most affected, with several multinational formulators requiring third-party laboratory verification beyond statutory minimums.
Single-serve consumption patterns are rotating procurement volumes toward 500ml-1L size bands in Indonesian and Vietnamese urban retail channels. Traditional multi-liter household formats face demand compression as convenience-store penetration expands and cold-chain dairy and juice brands fragment their SKU portfolios. This rotation is forcing blow-molding asset reconfiguration toward higher-cavitation, shorter-changeover equipment configurations.
Asia-Pacific Plastic Bottles and Containers Market Segmentation
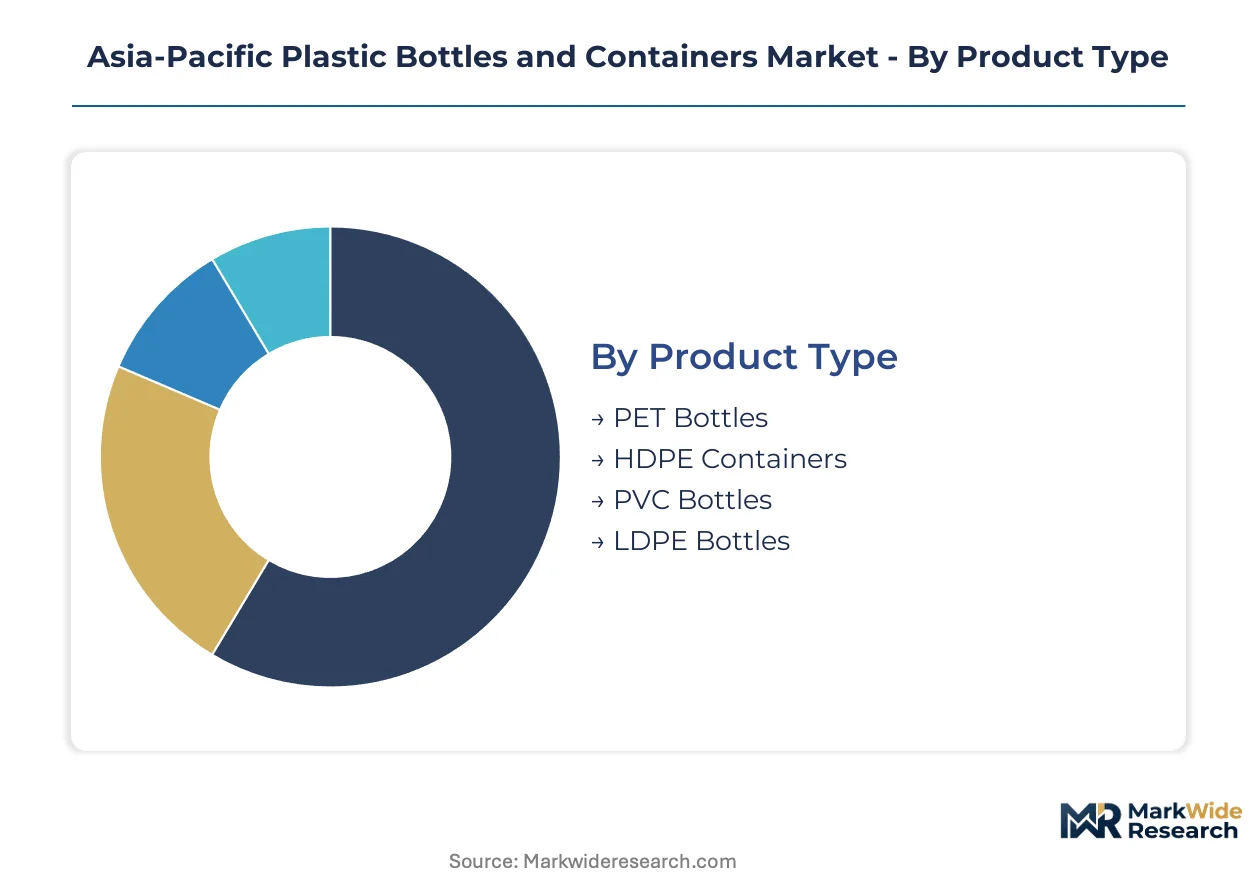
Segmentation in Asia-Pacific plastic bottles and containers reveals how resin selection, filling line specifications, and retail channel requirements fragment procurement decisions across beverage, pharmaceutical, and personal care supply chains.
Product Type:
Converters differentiate their asset bases by barrier performance, chemical resistance, and recyclability credentials that brand owners specify in master service agreements.
- PET Bottles:Biaxially oriented polyethylene terephthalate delivers clarity, carbonation retention, and lightweight strength for automated filling lines. Demand concentrates in Indonesian and Vietnamese beverage bottlers expanding single-serve water and carbonated soft drink portfolios under tropical distribution stress.
- HDPE Containers:High-density polyethylene offers moisture barriers and chemical resistance through extrusion-blow or injection-blow processes. Maharashtra and Gujarat polymer processors supply pharmaceutical tablet bottles and household chemical jugs where BIS certification mandates tighten material traceability.
- PVC Bottles:Polyvinyl chloride retains niche positions in edible oil and certain chemical applications requiring oxygen exclusion, though food-contact migration limits under China's GB standards constrain expansion.
- LDPE Bottles:Low-density polyethylene serves squeeze-dispense personal care and pharmaceutical applications where flexibility and stress-crack resistance outweigh structural rigidity requirements.
PET bottles sit at the top of the volume ranking, with HDPE containers climbing the fastest as pharmaceutical and personal care brands diversify their packaging specifications.
End User:
Each end-use vertical imposes distinct regulatory, aesthetic, and supply security demands that reshape converter qualification protocols and resin sourcing strategies.
- Beverage Industry:Carbonated soft drink and bottled water brands drive PET preform procurement at scale, with Japanese beverage multinationals adopting lightweighted designs that force regional blow-molding retooling.
- Personal Care:Shampoo, conditioner, and lotion brands in Vietnam's underpenetrated market create first-mover opportunities for specialized HDPE extrusion-blow molders serving premium positioning requirements.
- Pharmaceutical:Tablet bottles, syrup containers, and ophthalmic dispensers demand batch-level traceability documentation under China's SAMR enforcement and India's CDSCO oversight, elevating quality system investments.
- Household:Cleaning chemical and disinfectant containers prioritize chemical resistance and child-resistant closure compatibility, with procurement consolidating among converters holding captive additive compounding capabilities.
Beverage Industry maintains the dominant share position, with Personal Care expanding most quickly as Southeast Asian urban consumption patterns professionalize.
Size:
Volume band selection reflects retail channel infrastructure, cold-chain penetration, and household purchasing power gradients across metropolitan and tier-two city networks.
- 500ml-1L:Single-serve formats absorb procurement volume rotation as Indonesian and Vietnamese convenience-store penetration expands, forcing blow-molding asset reconfiguration toward higher-cavitation equipment with shorter changeover intervals.
- 100ml-500ml:Travel-size personal care, pharmaceutical samples, and premium beverage trial packs serve aviation retail and e-commerce sampler strategies, with demand clustering in Japan's metropolitan corridor.
- 1L-5L:Family-size edible oil, household chemical, and bulk beverage formats retain stable demand in Indian and Chinese wholesale club and traditional trade channels.
- Above 5L:Institutional catering, industrial chemical, and water dispenser refill segments concentrate in commercial and food-service supply chains with specialized logistics requirements.
500ml-1L holds the volume leadership position, with 100ml-500ml gaining share fastest as sampling and travel-retail strategies proliferate.
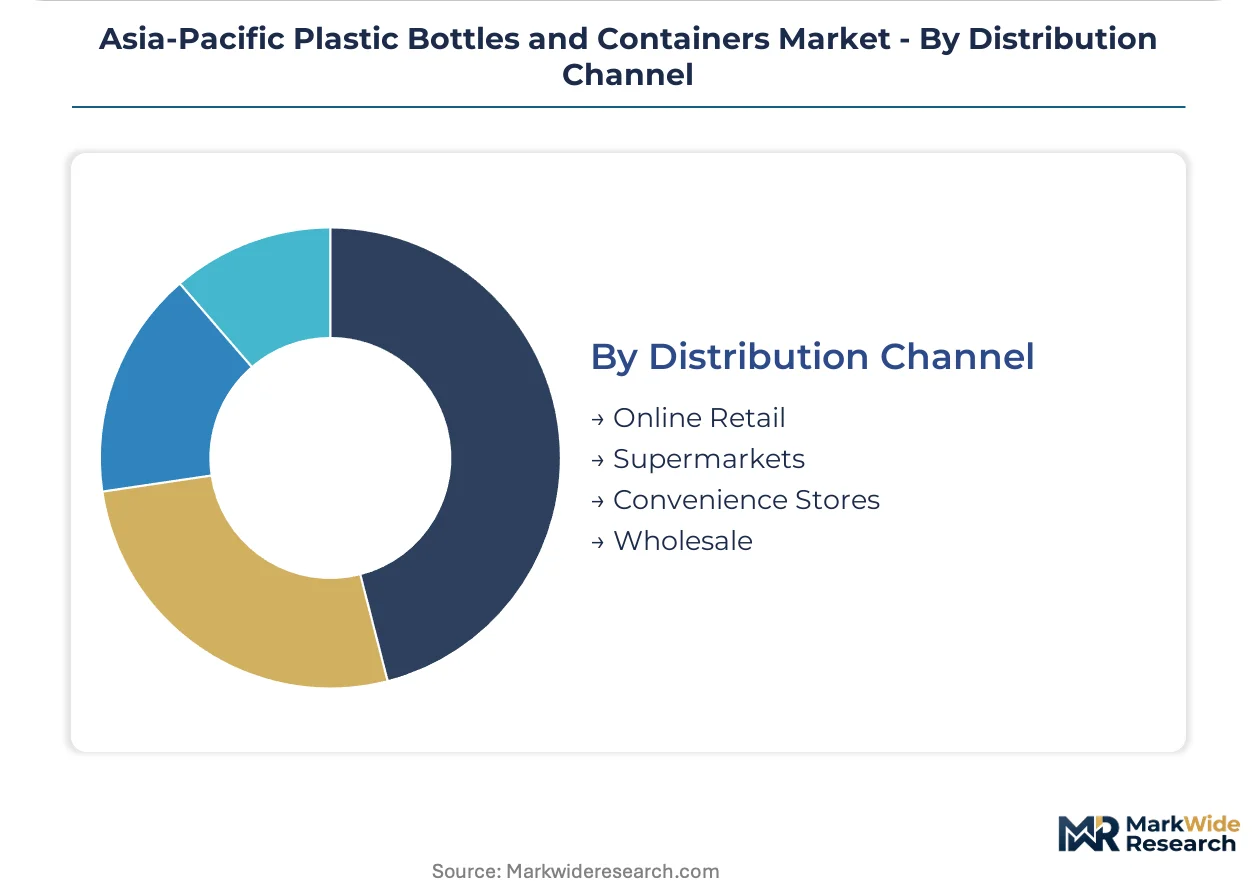
Distribution Channel:
Channel selection determines order fragmentation, lead time compression, and inventory positioning requirements that separate high-velocity retail from project-based institutional supply.
- Convenience Stores:7-Eleven, Lawson, and domestic chains across Thailand, Indonesia, and Vietnam drive replenishment velocity for single-serve beverage formats with strict on-shelf availability penalties.
- Supermarkets:Hypermarket and supermarket banners in China and India consolidate multi-liter household formats with promotional display requirements that strain converter seasonal capacity planning.
- Online Retail:Direct-to-consumer pharmaceutical and cosmetic container orders through regional e-commerce enablers disintermediate traditional distributor networks for mid-volume buyers.
- Wholesale:Cash-and-carry and institutional food-service channels in India's western states and China's provincial cities aggregate bulk-format demand with price-sensitive procurement practices.
Convenience Stores command the highest throughput velocity, with Online Retail climbing fastest as digital procurement platforms capture mid-volume pharmaceutical and cosmetic orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat polymer processing clusters anchor Asia-Pacific plastic bottles and containers capacity, serving domestic Indian demand and export buyers across Southeast Asian beverage supply chains. SAMR enforcement of GB standards in China and BIS certification mandates in India are restructuring converter qualification protocols. Regional procurement patterns concentrate in coastal manufacturing belts with integrated petrochemical feedstock access.
China
Carbonated beverage line extensions by domestic water brands are scaling PET preform procurement across Zhejiang and Guangdong provinces. SAMR enforces GB standards for food-contact plastics that mandate batch-level additive traceability and migration limit documentation. The Yangtze River Delta blow-molding corridor is retooling for lightweighted 500ml formats demanded by Japanese beverage multinationals.
India
Pharmaceutical tablet bottle demand from CDSCO-regulated formulators is pulling HDPE container capacity expansion in Maharashtra. BIS certification under FSSAI enforcement mandates polyethylene packaging quality system upgrades that freeze working capital in pre-qualified inventory. Gujarat polymer processors are capturing household chemical jug contracts through captive additive compounding capabilities.
Japan
METI-coordinated recycled content thresholds for beverage-grade rPET are creating premium pricing tiers for verified circular material. JIS standards bodies regulate recycled polymer integration in food-contact applications with third-party laboratory verification requirements. Kanto region converters are absorbing 20-25% weight-reduced preform specifications for still water lines.
Vietnam
Shampoo and conditioner brands are generating HDPE bottle demand that lags regional per-capita benchmarks, offering positioning opportunities for specialized extrusion-blow molders. Convenience-store penetration in Ho Chi Minh City and Hanoi is accelerating single-serve procurement rotation toward 500ml-1L formats. Northern industrial zones are attracting greenfield blow-molding investment facing technician scarcity in machine calibration skills.
Indonesia
Carbonated soft drink bottlers are tightening supply relationships with regional blow-molding specialists serving tropical distribution chains with high humidity barrier requirements. The country's national food safety regulator enforces food-contact material specifications that complicate import resin qualification. Java-based polymer processors are reconfiguring assets toward higher-cavitation equipment for shorter changeover intervals.
Asia-Pacific Plastic Bottles and Containers Market Competitive Environment
Global majors compete with regional champions across resin sourcing partnerships and blow-molding asset footprints. The market structures around three tiers: integrated petrochemical converters with captive feedstock, specialized pharmaceutical and personal care container fabricators, and high-volume beverage-grade PET specialists serving tropical distribution networks. Consolidation pressure is concentrating procurement relationships among converters holding multi-site certification across BIS, GB, and JIS standards. Competitive moves center on backward integration into rPET chemical recycling and geographic expansion into Vietnam's underpenetrated personal care segment.
Among Australia and New Zealand-based packaging groups, Pact Group Holdings Ltd. and Amcor plc occupy positions spanning integrated rigid packaging and flexible film portfolios. Silgan Holdings Inc. and Berry Global Inc. represent North American-headquartered multinationals with regional blow-molding footprints serving beverage and household chemical verticals. Zhejiang Xinlei Packaging Co Ltd. and Shanghai Zijiang Enterprise Group Co. Ltd. exemplify Chinese domestic champions competing on high-volume PET output for local beverage labels. Manjushree Technopack Limited anchors Indian converter capacity in Maharashtra and Gujarat polymer clusters. ALPLA Werke Alwin Lehner GmbH & Co KG and Gerresheimer AG sit within European-origin specialist tiers focused on pharmaceutical-grade barrier performance and precision molding tolerances.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Berry Global Inc |
| Amcor plc |
| Zhejiang Xinlei Packaging Co Ltd |
| Manjushree Technopack Limited |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Pact Group Holdings Ltd. |
| Shanghai Zijiang Enterprise Group Co. Ltd. |
| Gerresheimer AG |
| Others |
Value Chain & Pricing Dynamics
Beverage multinational procurement concentration in Southeast Asian bottling networks anchors contract-based long-term offtake agreements that compress spot-market exposure for regional converters. This buyer archetype dominance forces pricing discipline through volume-commitment thresholds and penalty structures for supply disruption.
Pricing Analysis
Naphtha-derived resin pass-through clauses dominate converter-brand contracts, exposing margins to polymer producer pricing decisions without lag buffers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with BIS- and GB-compliant material commanding spreads over uncertified supply. Cost compression in standard-tier PET preforms is intensifying because beverage brands are consolidating procurement relationships. Price-sensitive household chemical buyers in India's wholesale channels resist premium positioning, while pharmaceutical formulators show lowest sensitivity due to batch-traceability requirements.
Supply Chain Analysis
Blow-molding technician scarcity in Indonesian and Vietnamese greenfield plants constrains output scaling despite installed capacity expansion. Manufacturing gravity centers on China, India, and Vietnam, with polymer processing clusters drawing from naphtha crackers, imported PET resin, and specialty additive compounders. Single-source vulnerability in antioxidant and UV stabilizer supply from Northeast Asian chemical majors exposes Southeast Asian compounders to freight discontinuities. Distribution runs through coastal manufacturing belts with integrated petrochemical feedstock access, feeding downstream beverage bottlers and pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by Japanese beverage multinationals adopting 20-25% weight-reduced preform specifications that demand premium converter capabilities.
For Market Incumbents: Lock in captive rPET chemical recycling partnerships before METI-mandated recycled content thresholds harden feedstock competition. Defend position by accelerating multi-site certification across BIS, GB, and JIS standards to freeze out regional challengers facing documentation backlogs. Capacity addition in Maharashtra and Gujarat polymer clusters captures pharmaceutical tablet bottle demand from CDSCO-regulated formulators. For New Entrants and Emerging Players: Lightweighting technology adoption gaps among Vietnamese extrusion-blow molders present a technology-first wedge into shampoo and conditioner bottle supply. Target Vietnam's underpenetrated personal care segment through specialized HDPE production lines serving premium positioning requirements. Go-to-market leverage rests on direct-to-retailer digital procurement platforms that disintermediate traditional distributor networks for mid-volume cosmetic orders. For Investors and Strategic Acquirers: Beverage packaging conglomerates are the most active acquirer in this space, consolidating regional blow-molding specialists to secure tropical distribution chain relationships. Long-term viability favors converters with backward integration into chemically recycled feedstocks and multi-standard certification portfolios. Watch for BIS certification timeline compression as the inflection signal indicating regulatory capacity constraints are easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Chemical Recycling | Captive feedstock supply secures compliance with Japan's METI recycled content mandates. |
| Multi-Site Certification Investment | Simultaneous BIS, GB, and JIS qualification locks out competitors facing laboratory backlogs. |
| Lightweighting Technology Deployment | 20-25% preform weight reduction meets Japanese beverage multinational specifications. |
| Digital Procurement Platform Launch | Direct-to-retailer channels capture mid-volume pharmaceutical and cosmetic container orders. |
| Greenfield Capacity in Vietnam | Northern industrial zone positioning targets underpenetrated personal care HDPE demand. |
Study Parameters
Bottom-up beverage and pharmaceutical modeling reconciled against top-down polymer processing capacity tracking forms the analytical core of this study. Primary interviews with blow-molding plant managers, beverage procurement leads, pharmaceutical regulatory affairs directors, and polymer distribution channel partners combined with secondary validation from customs records, BIS certification registries, SEC filings of listed packaging groups, and SAMR enforcement bulletins. Triangulation between resin consumption estimates and converter output surveys anchors volume integrity.
Input-output matrices map PET and HDPE resin flows through injection-stretch blow-molding and extrusion-blow assets across the analysis window. Segmentation dimensions include resin type, end-use vertical, size band, and distribution channel, with CAGRs derived from regression against macroeconomic drivers and regulatory implementation schedules. Forecast inputs incorporate polymer price elasticity coefficients and certification penetration curves by country.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude-linked resin volatility and extended producer responsibility framework adoption across ASEAN member states. Material deviation in BIS certification processing speeds or METI recycled content threshold acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
Poland Plastic Bottles Market