
 Industrial Maintenance Services Market | 2026-2036
Industrial Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Maintenance Services Market Outlook
Buyer concentration among facility managers and large OEMs is pivoting toward integrated service contracts that bundle predictive analytics with on-site labor. General Electric leverages its digital twin platform to anchor long-term agreements across power generation clients. Siemens AG competes through regional service hubs that sustain rapid response capabilities for European industrial corridors.
Industrial maintenance services encompass the inspection, repair, overhaul, and optimization of production equipment, infrastructure, and control systems to sustain operational availability and safety compliance. These services integrate vibration analysis, thermal imaging, and lubricant testing to detect mechanical degradation before functional failure occurs. Predictive maintenance commands expanding budgets as IoT-enabled sensor networks reduce unplanned downtime across continuous-process industries. Condition-based maintenance is maturing fastest in energy verticals, where margin pools concentrate around turbine and generator overhaul cycles.
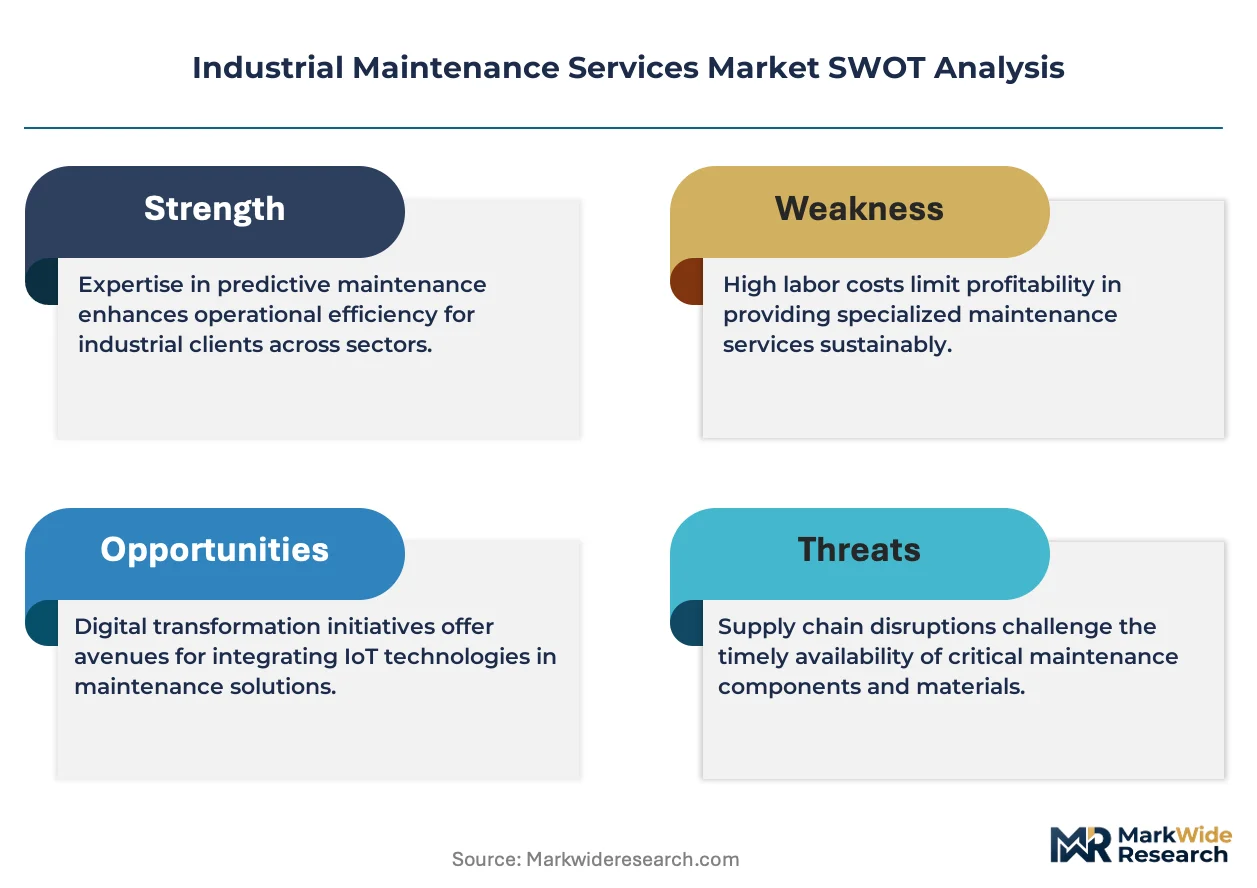
OSHA machinery safety standards, EPA emissions monitoring rules, and EU machinery directives shape service scope by mandating documented inspection intervals and certified technician qualifications. The EU AI Act introduces algorithmic accountability requirements for automated diagnostic systems deployed in European facilities. Stakeholders must monitor how regulatory divergence between US federal standards and EU machinery frameworks affects cross-border service contract structuring.
Market Dynamics
Aging power generation infrastructure across OECD economies is forcing systematic overhaul cycles that compress maintenance intervals and expand contract scopes for specialized service providers.
Growth Catalysts
- EU F-Gas Regulation:Mandatory leak detection protocols for fluorinated greenhouse gases are expanding service mandates for refrigeration and HVAC systems across German and French industrial facilities.
- Predictive analytics platforms:Vibration analysis and thermal imaging systems are reducing unplanned downtime in continuous-process industries, anchoring multi-year service agreements.
- German industrial density:Export-oriented manufacturing clusters in the Ruhr and Bavaria sustain premium maintenance contracts requiring rapid response capabilities.
Market Restraints
- Certified technician scarcity:EU machinery directives mandate documented qualifications that constrain labor supply and extend onboarding timelines for service firms.
- Specialized tooling capex:Turbine overhaul equipment requires seven-figure capital commitments that barrier mid-tier providers from generator maintenance segments.
- Input cost volatility:Rare earth magnet prices for precision diagnostic equipment fluctuate with Chinese export quotas, compressing margin predictability.
Strategic Opportunities
- India's PLI scheme:Manufacturing incentives are attracting industrial capacity that will require localized maintenance infrastructure as assets mature.
- Digital twin convergence:Physics-based simulation platforms are merging with IoT sensor networks to enable remote diagnostics for offshore energy installations.
- EU AI Act tailwind:Algorithmic accountability requirements for automated diagnostic systems create compliance service revenue streams for European facilities.
Industry Challenges
- Legacy control system integration:Proprietary SCADA architectures from the 1990s resist interoperability with modern predictive platforms, forcing costly middleware development.
- Skill bifurcation:Technicians must simultaneously master mechanical overhaul craft and data analytics interpretation, stretching training programs.
- OSHA documentation timelines:Machinery safety inspection records require multi-year retention systems that burden smaller service firms with compliance infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Maintenance Services Market |
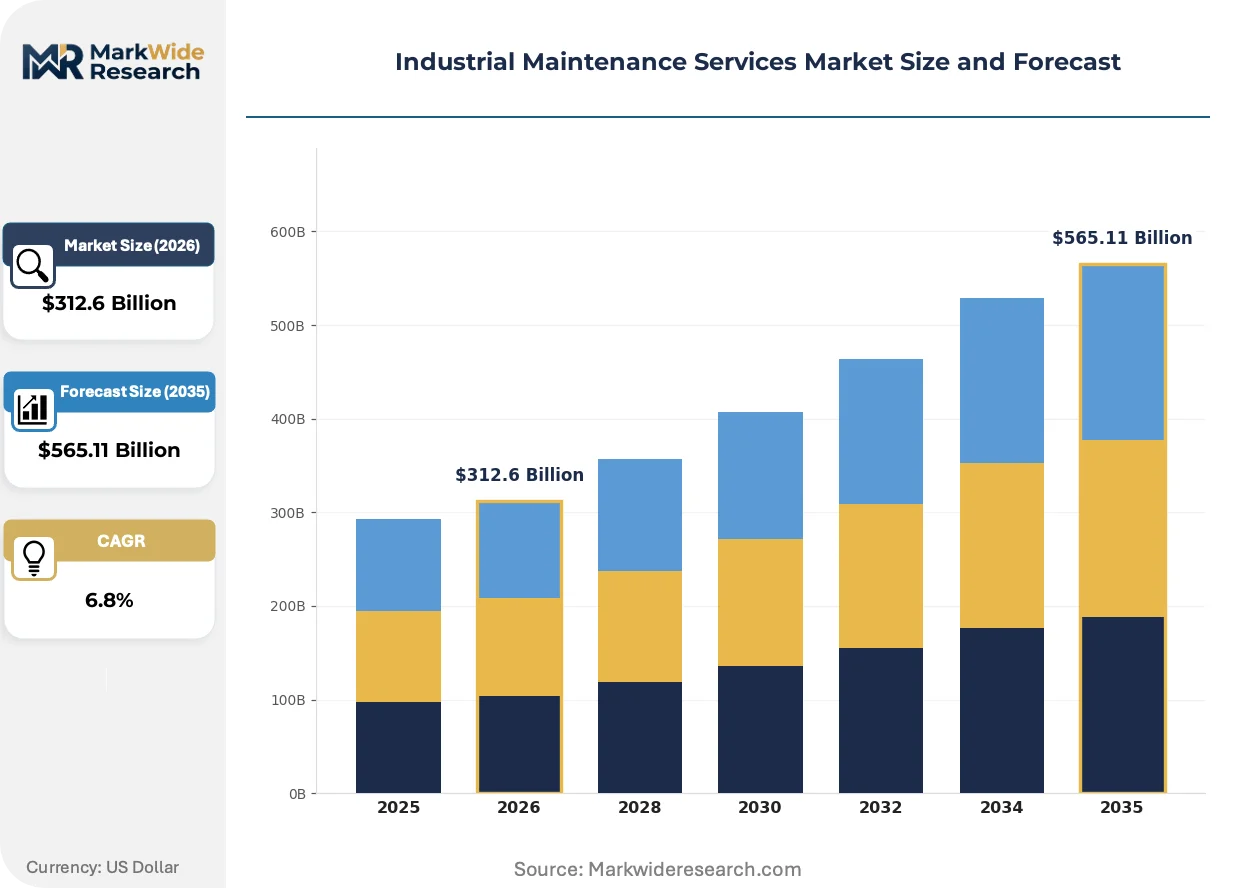
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Predictive Maintenance, Preventive Maintenance, Corrective Maintenance, Condition-Based Maintenance Industry Vertical: Manufacturing, Energy, Transportation, Agriculture Technology: IoT, AI, Robotics, Automation End User: OEMs, Tier-1 Suppliers, Facility Managers, Maintenance Contractors |
| Companies Covered | Emerson, General Electric, Siemens AG, NAES Corporation, Rockwell Automation, ABB, Honeywell, Total Resource Management, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Maintenance Services Market Strategic Shifts
Digital instrumentation is penetrating maintenance workflows at accelerating velocity, compressing detection-to-repair cycles while regulatory frameworks harden accountability requirements for automated systems.
Edge computing architectures are integrating vibration sensors and thermal cameras directly into production equipment. Power generation utilities are deploying these systems fastest, with offshore wind farms leading adoption. Real-time anomaly detection is integrating with work-order automation, collapsing response latency from days to hours.
The EU AI Act is mandating explainability standards for diagnostic algorithms deployed in European industrial facilities. Maintenance providers must now document decision pathways for automated fault classification. Energy verticals face the steepest compliance burden, with German turbine operators restructuring service contracts to allocate algorithmic liability.
Asset owners are unbundling corrective maintenance from preventive programs, creating separate procurement streams for emergency response versus scheduled overhaul. Facility managers in US chemical processing clusters are pioneering this split-contract model. The shift concentrates margin in predictive service tiers while commoditizing break-fix labor pools.
Industrial Maintenance Services Market Segmentation
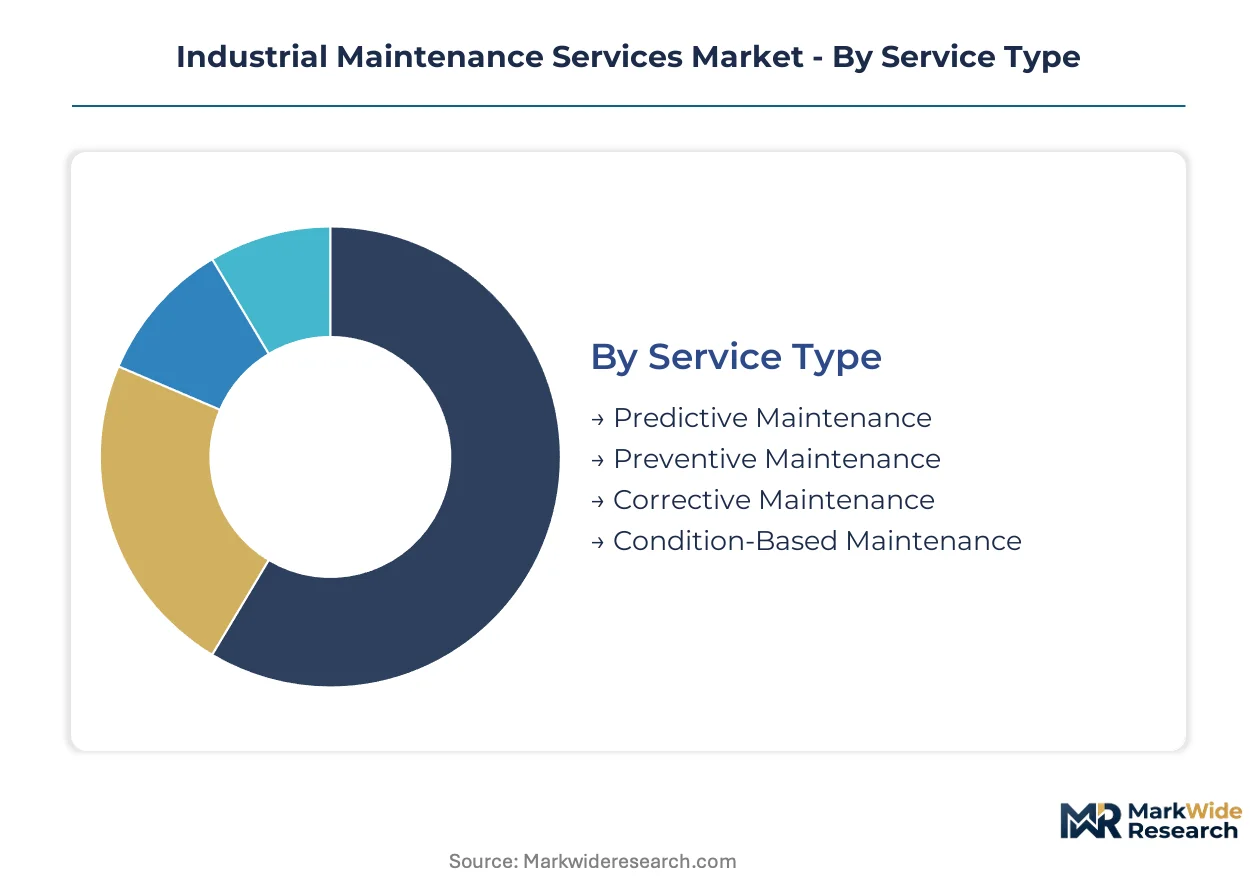
Maintenance service providers structure offerings around equipment criticality, regulatory exposure, and data maturity. Segmentation clarity determines contract pricing, technician specialization, and technology investment priorities.
Service Type:
Supply concentration in predictive platforms is reshaping how providers bundle labor and analytics.
- Predictive Maintenance:Algorithms process vibration, thermal, and lubricant data to forecast component failure before functional breakdown. German turbine operators and US chemical processors anchor demand as margin pools concentrate around continuous-process assets.
- Condition-Based Maintenance:Real-time sensor triggers initiate work orders only when degradation thresholds breach, compressing maintenance intervals versus calendar-based schedules. Offshore wind installations in the North Sea and Baltic are adopting these systems fastest.
- Preventive Maintenance:Scheduled inspection protocols dominate legacy asset bases where sensor retrofit costs exceed replacement economics.
- Corrective Maintenance:Break-fix response commands spot pricing premiums but faces margin compression as predictive systems reduce emergency incidence.
Predictive maintenance absorbs the bulk of installed capacity; condition-based maintenance is expanding most quickly.
Industry Vertical:
Cost tier differentiation separates premium-certified providers from commodity labor pools.
- Energy:Power generation utilities command the steepest compliance burdens, with FERC reliability standards and EU F-Gas leak detection mandates structuring contract scopes. Turbine overhaul cycles concentrate revenue in specialized providers.
- Manufacturing:Export-oriented German automotive and machinery clusters sustain premium service contracts requiring rapid response capabilities and documented technician qualifications.
- Transportation:Fleet maintenance programs balance uptime guarantees against parts inventory carrying costs, with rail operators leading predictive adoption.
- Agriculture:Seasonal equipment utilization patterns favor preventive schedules over capital-intensive sensor networks.
Energy verticals absorb the bulk of installed capacity; manufacturing applications are climbing the fastest.
Technology:
Application maturity separates pilot deployments from scaled implementations.
- IoT:Edge-integrated vibration and thermal sensors feed real-time dashboards, with power generation utilities deploying fastest. OSHA documentation requirements and EU machinery directives mandate data retention systems that burden smaller providers.
- AI:Automated fault classification faces EU AI Act explainability mandates that restructure liability allocation in service contracts. German turbine operators now require documented decision pathways for algorithmic diagnostics.
- Robotics:Automated inspection drones and crawler systems penetrate hazardous environments, reducing technician exposure in chemical processing and offshore energy.
- Automation:Work-order routing and parts procurement systems integrate with enterprise ERP platforms, collapsing administrative overhead.
IoT deployments absorb the bulk of installed capacity; AI-enabled diagnostics are gaining share fastest.
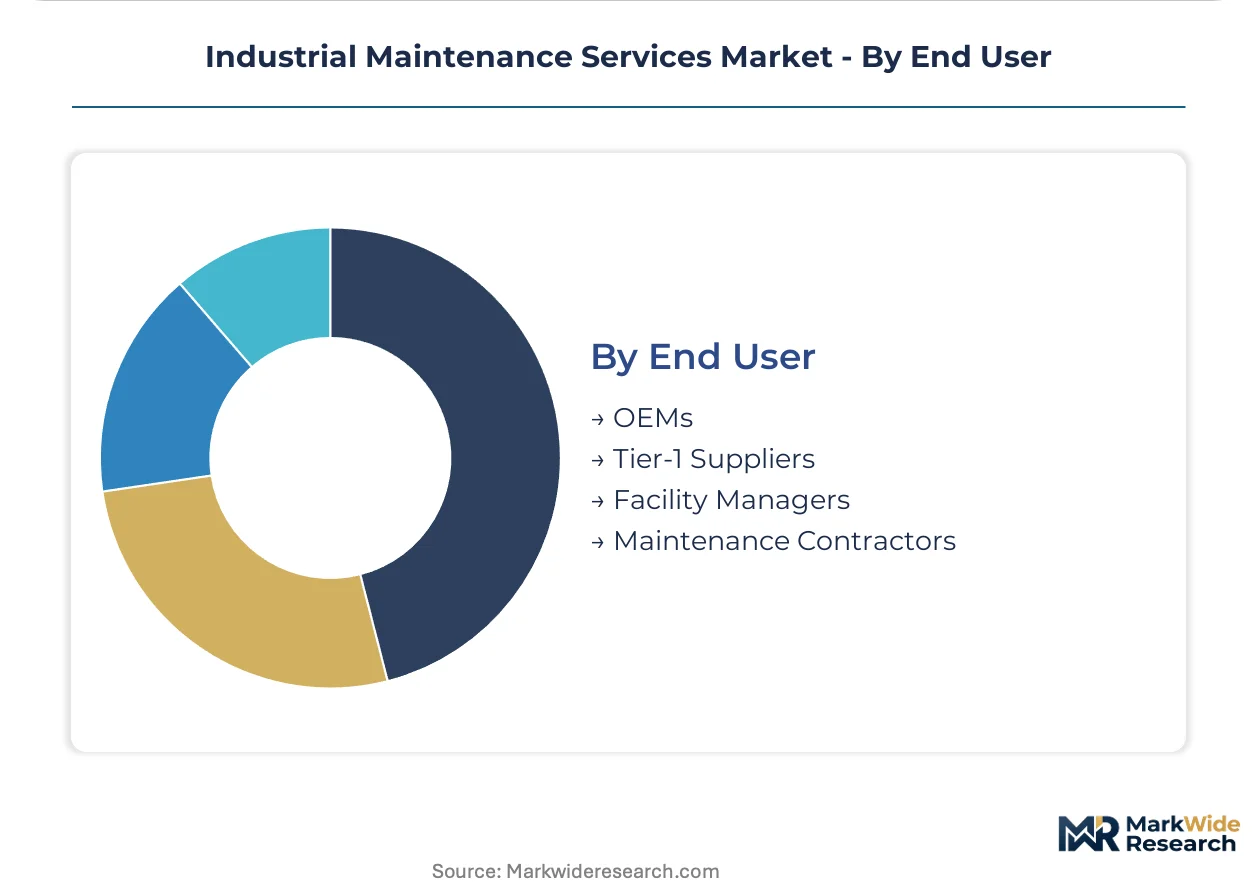
End User:
Customer type determines procurement structure and contract duration.
- Facility Managers:Integrated service contracts bundle predictive analytics with on-site labor, concentrating buyer power among large industrial campuses. US chemical processing clusters are unbundling corrective from preventive programs.
- OEMs:Original equipment manufacturers anchor long-term agreements through digital twin platforms, capturing aftermarket revenue across equipment lifecycles.
- Maintenance Contractors:Third-party service providers compete on technician availability and specialized tooling access, with mid-tier players barred from turbine overhaul segments by seven-figure capital requirements.
- Tier-1 Suppliers:Automotive and aerospace component manufacturers demand just-in-time maintenance to synchronize with production schedules.
Facility managers absorb the bulk of procurement volume; OEM service arms are capturing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr Valley steelworks and Bavarian automotive clusters anchor European maintenance demand. German industrial density sustains premium service contracts. US shale infrastructure and aging coal fleets drive North American overhaul cycles.
United States
Shale gas processing facilities and aging coal-fired power stations compress turbine maintenance intervals. EPA emissions monitoring rules mandate documented inspection protocols for rotating equipment. Houston's petrochemical corridor concentrates predictive service contracts among continuous-process operators.
Germany
Export-oriented machinery manufacturers and automotive OEMs sustain rapid-response maintenance agreements. EU F-Gas Regulation mandates leak detection protocols for industrial refrigeration systems. Ruhr industrial clusters and Bavarian automotive belts anchor premium service provider networks.
China
Coal-fired power capacity expansion and steel mill modernization drive systematic overhaul demand. MIIT equipment safety standards structure certified technician qualification requirements. Yangtze River Delta manufacturing zones concentrate condition-based maintenance deployments.
India
PLI scheme manufacturing incentives attract industrial capacity requiring localized maintenance infrastructure. CEA grid reliability standards mandate documented equipment inspection for power generation assets. Gujarat and Maharashtra industrial corridors anchor emerging predictive service markets.
Japan
Precision machinery exporters and nuclear restart programs sustain specialized overhaul demand. METI energy efficiency directives structure maintenance protocols for industrial equipment. Kansai manufacturing clusters and Chubu industrial zones concentrate premium service contracts.
Industrial Maintenance Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital diagnostics and AI-enabled fault classification. The vendor base stratifies across integrated industrial conglomerates, specialized predictive analytics platforms, and regional rapid-response contractors. Three archetypes dominate: full-service OEMs anchoring long-term agreements, technology specialists licensing diagnostic platforms, and labor-focused contractors competing on technician availability. Dominant competitive moves include strategic partnerships between sensor manufacturers and analytics software vendors, plus backward integration into proprietary IoT hardware.
Among US-based industrial conglomerates, General Electric and Emerson occupy positions exemplifying the full-service OEM archetype through digital twin and automation platforms. Siemens AG represents the European integrated industrial model. These three anchor the competitive structure without exhaustive market share claims.
| Leading Market Players |
|---|
| Emerson |
| General Electric |
| Siemens AG |
| NAES Corporation |
| Rockwell Automation |
| ABB |
| Honeywell |
| Total Resource Management |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet price indices for precision diagnostic equipment cascade through service provider cost structures, compressing margins in mid-tier predictive maintenance tiers while premium OEM-anchored contracts absorb volatility through long-term parts procurement agreements.
Pricing Analysis
Warranty bundling separates OEM digital twin platforms from unbundled break-fix labor pools, with General Electric and Siemens anchoring subscription-based predictive analytics against spot-priced corrective maintenance. Three-tier pricing structure across premium-certified, standard-compliant, and economy-labor levels reflects technician qualification depth under EU machinery directives. Cost compression in economy tiers intensifies as certified technician scarcity extends onboarding timelines. Facility managers at continuous-process chemical plants exhibit lowest price sensitivity; mid-tier maintenance contractors face acute margin pressure from tooling capex requirements.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds reshape sourcing patterns for sensor hardware and precision diagnostic components entering localized maintenance infrastructure. Supply concentration centers on Germany for turbine overhaul equipment, China for rare earth magnet assemblies, and Japan for precision vibration sensors. Component dependencies include thermal imaging arrays, edge-computing nodes, and certified lubricant testing kits. Single-source vulnerability concentrates in Chinese rare earth processing capacity. Distribution runs through OEM captive service networks and third-party contractor procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial maintenance services constitute a consolidation play as seven-figure turbine overhaul tooling requirements force mid-tier providers toward acquisition or exit.
For Market Incumbents: Hedge algorithmic liability exposure by restructuring service contracts to document EU AI Act explainability pathways for automated fault classification. Deepen backward integration into proprietary IoT sensor hardware to lock out technology specialists licensing diagnostic platforms. Threat substitution from AI-enabled fault classification startups demands preemptive certification investment. For New Entrants and Emerging Players: The gap between premium OEM-anchored digital twin contracts and economy break-fix labor pools offers white-space entry at the mid-market predictive analytics tier. Target India's PLI scheme manufacturing corridors before asset maturity drives localized maintenance demand. Lead with edge-computing sensor deployment as the go-to-market wedge against legacy preventive schedules. For Investors and Strategic Acquirers: The window for entry favors specialized predictive analytics platforms with proven EU AI Act compliance documentation. Long-term viability hinges on algorithmic accountability service revenue streams hardening into recurring contract structures. Watch German turbine operator contract restructuring as the inflection signal for liability allocation standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary IoT Hardware | Captive sensor supply locks out platform competitors from predictive maintenance contracts. |
| EU AI Act Compliance Documentation | Explainability pathway records create defensible service revenue in German turbine operations. |
| Regional Service Hub Expansion | Rapid-response capabilities anchor premium contracts across Ruhr and Bavarian industrial belts. |
| Digital Twin Platform Convergence | Physics-based simulation merges with sensor networks for offshore energy remote diagnostics. |
| Certified Technician Training Programs | Documented qualifications under EU machinery directives constrain competitor labor supply. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this industrial maintenance services analysis. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combined with secondary sources including OSHA enforcement databases, EU machinery directive implementation reports, and power utility procurement disclosures. Bottom-up service contract value aggregation triangulated against top-down industrial capacity estimates.
Data-stream reconciliation across predictive platform deployment tallies, certified technician qualification registries, and turbine overhaul cycle frequencies generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type tier, industry vertical exposure, technology maturity stage, and end-user procurement structure. CAGRs derived from equipment installed base aging curves and regulatory mandate implementation timelines. Forecast inputs incorporated F-Gas Regulation compliance deadlines and PLI scheme manufacturing capacity ramps.
Inputs from OSHA, EPA, and EU regulatory databases were available through the study window; gaps in mid-tier contractor financial disclosures introduce uncertainty bands around market concentration estimates. Forecasts reflect assumptions regarding technician training pipeline expansion and sensor hardware cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Industrial Maintenance Products Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
3D Concrete Printing Services Market
Construction Services
MENA Architectural Services Market
Construction Services
Construction TIC Market
Construction Services
Hardbanding Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Global Industrial Services Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Train Contractor Market
Construction Services
Excavating Contractor Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Global Construction Scaffolding Rental Market