
 Global Pharmaceutical Grade Silica Gel Market | 2026-2036
Global Pharmaceutical Grade Silica Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Grade Silica Gel Market Foresight
Buyer concentration among large pharmaceutical contract packagers is repositioning procurement leverage toward volume-tiered supply agreements. Evonik Industries leverages its integrated precipitated silica platform to sustain cost advantages across pharmaceutical desiccant grades. BASF anchors European supply through controlled pore-size manufacturing lines that dominate high-purity bead segments. W.R. Grace & Co. competes on cGMP-certified production infrastructure that extends into diagnostic packaging applications.
Pharmaceutical grade silica gel refers to amorphous silicon dioxide processed to meet pharmacopeial purity standards, typically exhibiting surface areas between 300 and 800 square meters per gram and controlled pore diameters optimized for moisture adsorption in drug stability applications. Bead formulations occupy the largest volume share due to standardized flow properties in high-speed packaging lines, while powder grades capture premium positioning in direct-compression tablet formulations where particle size distribution governs blend uniformity. Capsule segments are gaining structural traction as pre-filled desiccant canisters replace loose-fill systems in single-dose biologic packaging.
USP-NF monographs, FDA container closure guidance, and EMA stability testing requirements collectively elevate barrier performance standards for moisture-sensitive drug products. The FDA's emphasis on ICH Q1A stability protocols is forcing packagers to document desiccant capacity versus headspace volume ratios in regulatory filings. Manufacturers must monitor evolving pharmacopeial silica gel monograph revisions and regional divergence between USP and EP testing methodologies.
Market Dynamics
The pharmaceutical grade silica gel market is reconfiguring around FDA container closure integrity enforcement, which is compressing supplier qualification timelines and elevating purity documentation burdens across contract packaging networks.
Growth Catalysts
- Biologics packaging expansion:Moisture-sensitive monoclonal antibodies and cell therapies are driving silica gel canister adoption in single-dose vial configurations. CDSCO stability guidelines in India are accelerating parallel qualification requirements.
- REACH chemical safety alignment:ECHA substance registration protocols are harmonizing impurity thresholds across European pharmaceutical desiccant supply chains, reducing multi-jurisdictional compliance friction for exporters.
- Diagnostic test kit surge:Lateral flow and molecular diagnostic platforms are embedding silica gel sachets directly into pouch laminates, creating incremental volume pull from IVD contract manufacturers.
Market Restraints
- Sodium silicate feedstock volatility:Energy-intensive precipitation chemistry ties silica gel production to natural gas and soda ash price swings, compressing margin visibility for mid-scale producers.
- German supply concentration:Rhineland chemical clusters control precipitated silica precursor capacity, creating geographic chokepoints that amplify disruption risk from regional energy policy shifts.
- Clay desiccant substitution:Bentonite and molecular sieve alternatives are capturing economy-tier pharmaceutical packaging applications where moisture capacity requirements fall below critical thresholds.
Strategic Opportunities
- Brazilian ANVISA harmonization:Pending alignment with ICH Q1A stability protocols will unlock pre-qualified desiccant demand from São Paulo-based generic pharmaceutical exporters targeting MERCOSUR markets.
- Pre-filled canister systems:Automated insertion equipment compatible with high-speed blister lines is displacing manual sachet placement in European contract packaging facilities.
- Japan PMDA serialization integration:Track-and-trace mandates for secondary packaging are creating bundled procurement opportunities linking desiccant supply to authentication technology providers.
Industry Challenges
- cGMP auditor scarcity:Qualified pharmaceutical excipient inspectors are concentrated among legacy certification bodies, extending facility qualification timelines for new market entrants.
- USP-NF monograph divergence:Pending revisions to silica gel testing methodologies are creating temporary uncertainty in specification negotiations between packagers and API manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Grade Silica Gel Market |
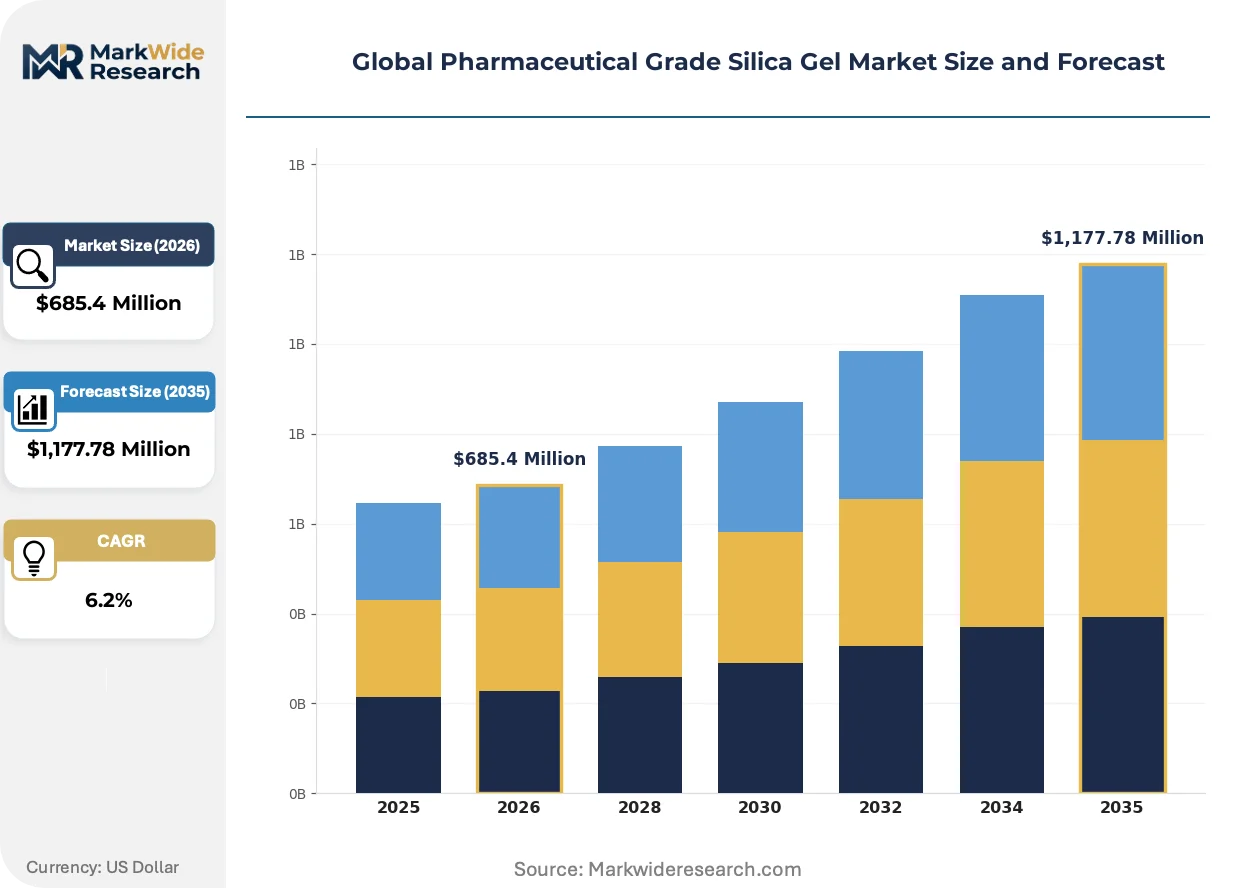
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beads, Granules, Powder, Sheets, Capsules Purity Grade: Pharmaceutical USP, Food Grade, Technical Grade, Analytical Grade, Cosmetic Grade Application: Drug Formulation, Moisture Control, Packaging Protection, Catalyst Carrier, Adsorbent End User Industry: Pharmaceutical Manufacturers, Biotechnology Firms, Diagnostic Labs, Contract Research Organizations |
| Companies Covered | Evonik Industries, BASF, W.R. Grace & Co., Clariant International, Solvay S.A., Cabot Corporation, Hubei Xingfa Chemicals Group, Mitsubishi Chemical Corporation, Sibelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Grade Silica Gel Market Shifts & Advancements
Moisture management technologies are converging with pharmaceutical packaging automation, compressing the gap between desiccant performance specification and line-speed compatibility requirements.
Indicating silica gel formulations with cobalt chloride-free color change indicators are absorbing regulatory scrutiny as REACH Annex XVII restrictions on cobalt compounds tighten across European pharmaceutical supply chains. German contract packagers are qualifying these alternatives ahead of mandatory phase-out deadlines. The transition is absorbing technical service capacity from specialty chemical distributors.
EMA's revised Annex 1 sterile manufacturing guidelines are extending container closure integrity validation requirements to non-sterile solid dosage forms, forcing desiccant suppliers to document adsorption kinetics under accelerated stability conditions. High-potency oncology packaging in the Netherlands and Belgium is experiencing the most acute compliance pressure. Secondary packaging specifications now routinely incorporate headspace moisture modeling.
Consolidated procurement by top-tier pharmaceutical contract packagers is compressing supplier rosters and extending master service agreement durations. Volume-tiered pricing with technical support bundling is displacing transactional spot purchasing in North American and Western European markets. This concentration is most visible in Illinois and New Jersey packaging corridors serving branded generic manufacturers.
Global Pharmaceutical Grade Silica Gel Market Segmentation
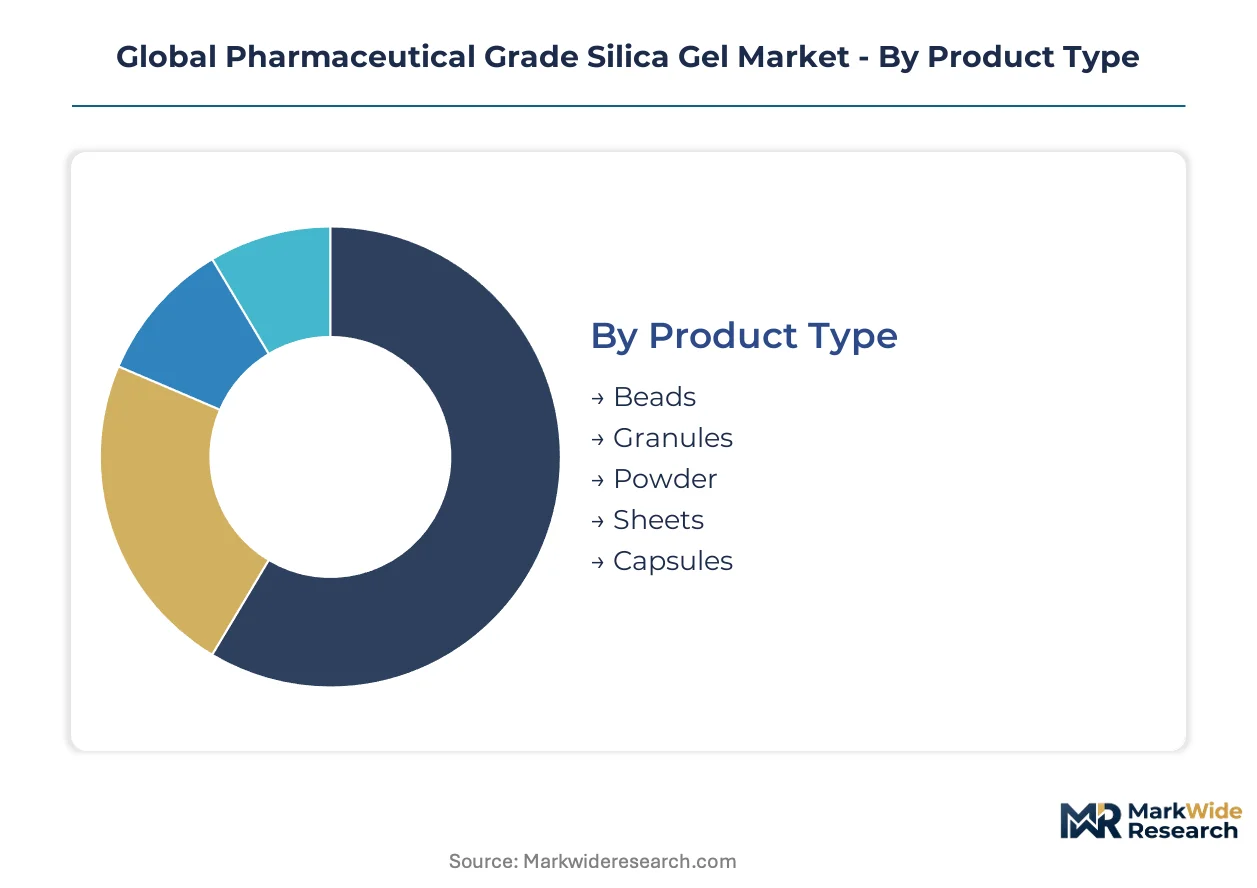
Pharmaceutical grade silica gel procurement varies sharply across product formats and purity tiers, with packaging automation requirements and regulatory filing standards driving divergent specification demands. Contract packagers maintain parallel qualification tracks for legacy formats and next-generation canister systems.
Product Type:
Packaging line upgrades and desiccant insertion automation are reconfiguring volume distribution across physical formats, with high-speed compatibility now outweighing unit cost in sourcing decisions.
- Beads:Spherical amorphous silicon dioxide with controlled particle size distribution enables consistent flow through automated dispensing equipment. German contract packaging corridors serving European pharmaceutical networks concentrate demand here, driven by FDA container closure integrity documentation requirements for high-volume solid dosage lines.
- Capsules:Pre-formed canister configurations eliminate manual sachet handling and integrate directly with track-and-trace serialization systems. Demand concentrates in Illinois and New Jersey packaging hubs serving branded generic manufacturers, with EMA Annex 1 sterile manufacturing guidelines extending validation requirements to these formats.
- Granules:Irregular particle geometry suits bulk desiccant applications where flow properties are secondary to adsorption capacity.
- Powder:Fine particle grades serve direct-compression tablet formulations where blend uniformity depends on precise particle size distribution.
- Sheets:Laminated configurations embed within pouch structures for diagnostic test kits and lateral flow devices.
Beads sits at the top of the volume ranking, with Capsules climbing the fastest.
Purity Grade:
Cost tiers separate qualification-intensive pharmaceutical applications from industrial and cosmetic segments where impurity thresholds remain less stringent.
- Pharmaceutical USP:Meets USP-NF monograph specifications for silicon dioxide with rigorous heavy metal and microbial limit testing. Biopharmaceutical manufacturers in the Netherlands and Belgium specify this grade for high-potency oncology packaging under EMA stability protocol pressure.
- Food Grade:Complies with FDA food contact substance regulations and serves nutraceutical packaging where pharmaceutical filing requirements do not apply. Indian generic exporters targeting CDSCO stability guidelines drive volume in this tier.
- Technical Grade:Standard purity for industrial moisture control applications outside regulated pharmaceutical environments.
- Analytical Grade:Ultra-high purity for laboratory and quality control reference standards with traceable certification.
- Cosmetic Grade:Meets personal care formulation standards where silicon dioxide functions as viscosity modifier rather than desiccant.
Pharmaceutical USP commands the premium tier by margin, while Food Grade expands most quickly behind nutraceutical packaging growth.
Application:
Customer type and end-use environment determine whether silica gel functions as active ingredient, processing aid, or protective packaging component.
- Moisture Control:Headspace desiccation in drug product containers prevents hydrolytic degradation of moisture-sensitive APIs. Monoclonal antibody and cell therapy packaging in single-dose vial configurations concentrates demand here, with ICH Q1A stability protocols mandating documented capacity-to-headspace ratios.
- Packaging Protection:Secondary barrier systems in bottle and blister configurations extend shelf life for solid dosage forms. São Paulo-based generic pharmaceutical exporters targeting MERCOSUR markets are pre-qualifying desiccant systems ahead of pending ANVISA harmonization with ICH standards.
- Drug Formulation:Direct incorporation as glidant or anti-caking agent in tablet and capsule manufacturing.
- Catalyst Carrier:High surface area support for pharmaceutical synthesis and biocatalytic processes.
- Adsorbent:Purification media for API manufacturing and solvent recovery operations.
Moisture Control holds the largest installed base, with Packaging Protection gaining share fastest on biologics packaging expansion.
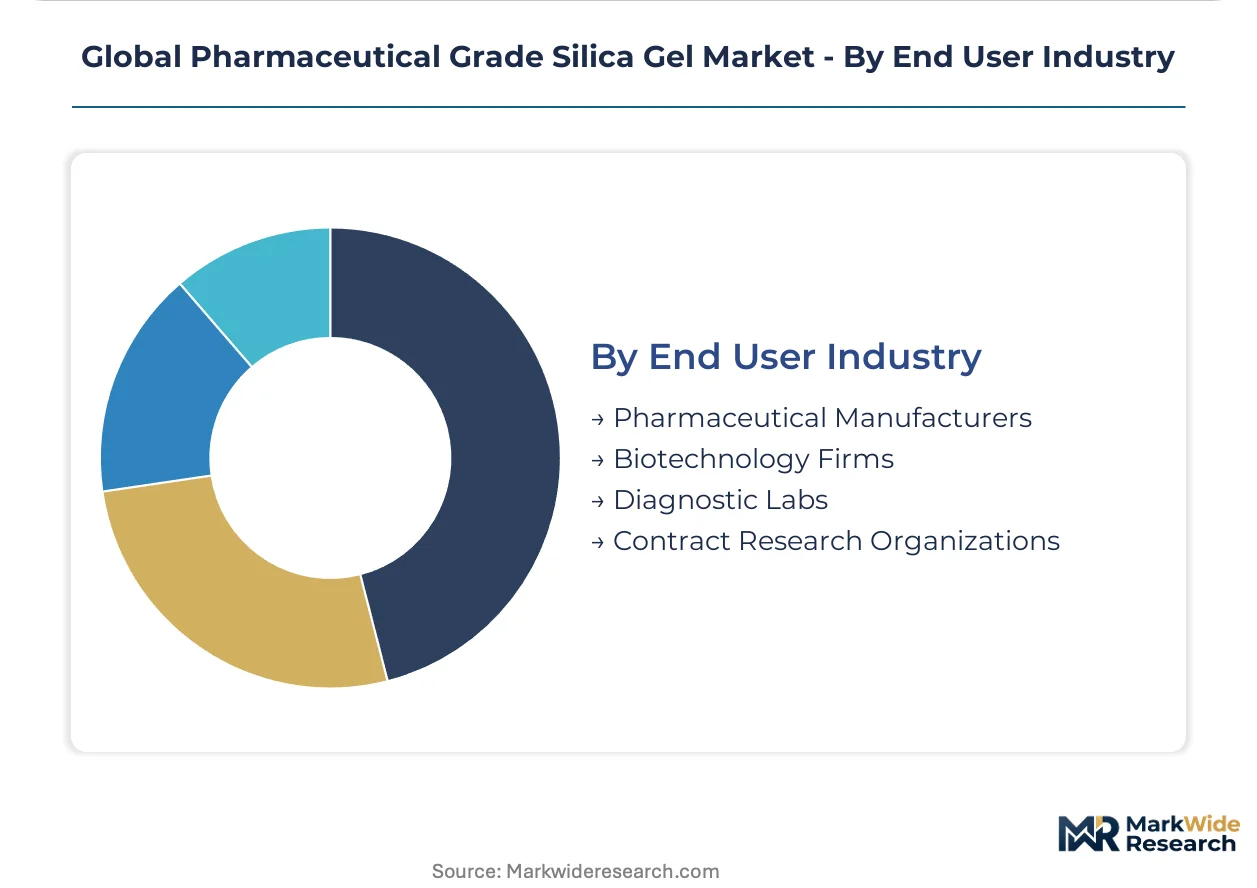
End User Industry:
Procurement scale and technical service requirements fragment the customer base across integrated manufacturers and outsourced service providers.
- Pharmaceutical Manufacturers:Branded and generic drug producers with captive packaging operations or direct contract packaging relationships. Volume-tiered supply agreements with technical support bundling dominate procurement in North American and Western European markets.
- Biotechnology Firms:Developers of monoclonal antibodies, cell therapies, and other moisture-sensitive biologics with specialized cold chain and stability requirements. Japanese PMDA serialization mandates are creating bundled procurement opportunities linking desiccant supply to authentication technology providers.
- Diagnostic Labs:Clinical and research laboratories with intermittent, specification-driven purchasing for assay development and quality control.
- Contract Research Organizations:Service providers managing stability studies and regulatory filing support with variable, project-based demand.
Pharmaceutical Manufacturers represent the dominant procurement volume, with Biotechnology Firms showing the steepest expansion trajectory on biologics pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands precipitated silica precursor capacity while the United States drives biologics packaging innovation, creating divergent regional specializations in pharmaceutical grade silica gel procurement.
United States
FDA container closure integrity enforcement compresses supplier qualification timelines for Illinois and New Jersey contract packaging corridors. ICH Q1A stability protocols mandate documented desiccant capacity-to-headspace ratios in regulatory filings. Branded generic manufacturers concentrate procurement through volume-tiered supply agreements with technical support bundling.
Germany
Rhineland chemical clusters control precipitated silica precursor capacity, amplifying disruption risk from regional energy policy shifts. ECHA REACH substance registration protocols harmonize impurity thresholds across European pharmaceutical desiccant supply chains. Specialized chemical producers in North Rhine-Westphalia serve European pharmaceutical contract packaging networks with controlled pore-size manufacturing lines.
India
CDSCO stability guidelines accelerate parallel qualification requirements for moisture-sensitive biologic drug packaging. Generic pharmaceutical exporters in Maharashtra and Gujarat target pre-qualified desiccant systems ahead of expanded regulatory alignment. Mumbai-based contract manufacturers expand silica gel use in moisture-sensitive packaging for domestic and export markets.
Japan
PMDA track-and-trace mandates for secondary packaging create bundled procurement opportunities linking desiccant supply to authentication technology providers. Monoclonal antibody and cell therapy developers in the Kanto region specify pharmaceutical USP grade for high-potency oncology packaging. Tokyo-area biotechnology firms drive specialized cold chain and stability requirements for single-dose vial configurations.
Brazil
Pending ANVISA harmonization with ICH Q1A stability protocols unlocks pre-qualified desiccant demand from São Paulo-based generic pharmaceutical exporters. MERCOSUR market access depends on documented adsorption kinetics under accelerated stability conditions. Southeastern pharmaceutical manufacturing clusters prepare qualification tracks for legacy formats and next-generation canister systems.
Global Pharmaceutical Grade Silica Gel Market Competitive Landscape
German producers anchor the premium-tier supply base; American and Belgian specialists hold positions in cGMP-certified production infrastructure. The market structures around three tiers: integrated chemical conglomerates with precipitated silica platforms, mid-scale regional manufacturers serving contract packaging networks, and specialty distributors providing technical service capacity. Consolidation pressures compress supplier rosters as top-tier pharmaceutical contract packagers extend master service agreement durations. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Within the integrated chemical tier, Evonik Industries and BASF exemplify archetypes of backward-controlled supply chains. W.R. Grace & Co. occupies a position among cGMP-certified infrastructure specialists. These three entities represent the concentration of European pharmaceutical desiccant manufacturing capacity, with each anchoring distinct competitive vectors around platform integration, pore-size control, and regulatory certification depth.
| Leading Market Players |
|---|
| Evonik Industries |
| BASF |
| W.R. Grace & Co. |
| Clariant International |
| Solvay S.A. |
| Cabot Corporation |
| Hubei Xingfa Chemicals Group |
| Mitsubishi Chemical Corporation |
| Sibelco |
| Others |
Supply & Pricing Matrix
USP-grade certification separates pharmaceutical desiccant producers from technical-grade commodity suppliers, creating a bifurcation where premium pricing power concentrates with cGMP-certified manufacturers while mid-scale competitors absorb feedstock volatility. This tier divergence manifests in procurement patterns: large contract packagers lock in multi-year technical service agreements with certified suppliers, whereas smaller generic manufacturers trade spot purchases against sodium silicate cost swings.
Pricing Analysis
Capacity additions in China are reshaping price floors for technical-grade silica gel, compressing margins for non-certified producers serving nutraceutical and diagnostic packaging segments. Three-tier pricing structure across pharmaceutical USP, food-grade, and technical levels reflects the cost of qualification documentation and auditor retention. Pricing pressure stems from energy-intensive precipitation chemistry tying production to natural gas volatility. Small-scale Indian generic exporters exhibit highest price sensitivity, while biopharmaceutical developers in the Netherlands and Belgium prioritize adsorption kinetics documentation over unit cost.
Supply Chain Analysis
Pharmacopeial certification gating restricts qualified supply to German Rhineland clusters, Chinese precipitated silica hubs, and select American cGMP facilities. Raw material dependencies center on sodium silicate from soda ash processing, sulfuric acid for precipitation pH control, and cobalt-free indicating dyes for REACH compliance. Single-source vulnerability concentrates in Rhineland energy policy exposure, where natural gas price spikes transmit directly to precipitation chemistry economics. Distribution runs through European pharmaceutical contract packaging networks, North American branded generic corridors, and emerging São Paulo-based MERCOSUR export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pharmaceutical grade silica gel hinges on premium-tier migration as biologics packaging demands displace commodity technical-grade volume, with feedstock volatility absorption separating integrated producers from margin-compressed assemblers.
For Market Incumbents: To counter clay desiccant substitution in economy-tier pharmaceutical applications, backward integration into sodium silicate production secures margin visibility against soda ash price swings, while cGMP auditor capacity expansion compresses qualification timelines for new biopharmaceutical customers. Controlled pore-size manufacturing line upgrades in North Rhine-Westphalia defend bead format dominance against capsule system displacement. For New Entrants and Emerging Players: CDSCO stability guideline alignment in India opens a window for pre-qualified desiccant supply to Maharashtra and Gujarat generic exporters, where technical-grade qualification requirements remain less stringent than FDA or EMA tiers. Target diagnostic test kit laminates for lateral flow device integration, leveraging lower regulatory filing burdens compared to drug product packaging. Partner with São Paulo-based contract manufacturers ahead of pending ANVISA harmonization to secure first-mover positioning in MERCOSUR pre-qualification tracks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale producers lack captive sodium silicate supply and cGMP certification depth simultaneously. Five-to-ten-year viability favors integrated chemical conglomerates with precipitated silica platforms over regional assemblers exposed to feedstock volatility. Acquisition target archetype: German or Belgian specialty distributors with technical service capacity and existing pharmaceutical packager relationships. Signal to watch: EMA Annex 1 sterile manufacturing guideline extension to non-sterile solid dosage forms, which would accelerate headspace moisture modeling documentation requirements and disqualify uncertified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply insulates margin from Rhineland natural gas policy volatility. |
| cGMP Certification Expansion | Qualified auditor access compresses facility qualification timelines for biopharmaceutical entrants. |
| Pre-filled Canister System Development | Automated insertion compatibility captures share from manual sachet placement in European contract packaging. |
| Cobalt-free Indicating Formulation Transition | REACH Annex XVII alignment ahead of mandatory phase-out secures German contract packager qualification. |
| Diagnostic Test Kit Laminate Partnership | Lateral flow device integration opens incremental volume from IVD contract manufacturers with lower filing burdens. |
Research Methodology
Bottom-up moisture control application modeling reconciled against top-down precipitated silica capacity tracking forms the analytical core of this study. Primary interviews with pharmaceutical packaging engineers, regulatory affairs specialists at contract manufacturing organizations, procurement directors at branded generic producers, and technical service managers at specialty chemical distributors were validated against secondary sources including FDA container closure guidance documents, EMA stability testing protocols, USP-NF silica gel monographs, and customs trade data for sodium silicate derivatives. Triangulation across stakeholder perspectives and documentary sources ensures specification accuracy across purity grades and regional regulatory clusters.
Input-output matrices map silica gel demand to biologics packaging expansion, diagnostic test kit production, and solid dosage form protection across the projection horizon. Segmentation dimensions include product format (bead, capsule, powder), purity tier (pharmaceutical USP, food-grade, technical), application function (moisture control, packaging protection, drug formulation), and end-user industry (pharmaceutical manufacturers, biotechnology firms, diagnostic labs). CAGRs derive from capacity utilization trends, regulatory filing velocity, and substitution elasticity against molecular sieve and clay alternatives. Forecast inputs incorporate ICH Q1A stability protocol adoption curves and REACH chemical safety alignment timelines.
Revisions become necessary when FDA container closure integrity enforcement intensifies beyond current guidance timelines, EMA Annex 1 sterile manufacturing extensions accelerate, or Rhineland energy policy disruptions alter precipitated silica precursor economics. Forecasts reflect documented assumptions regarding qualification timeline compression and feedstock cost transmission. A model refresh is warranted upon material change in biopharmaceutical pipeline moisture sensitivity profiles or cobalt compound restriction phase-out schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Sulphonamides Market