
 Antibiotics Active Pharmaceutical Ingredient (API) Market | 2026-2036
Antibiotics Active Pharmaceutical Ingredient (API) Market Size, Share, and Industry Trends Forecast 2026-2036
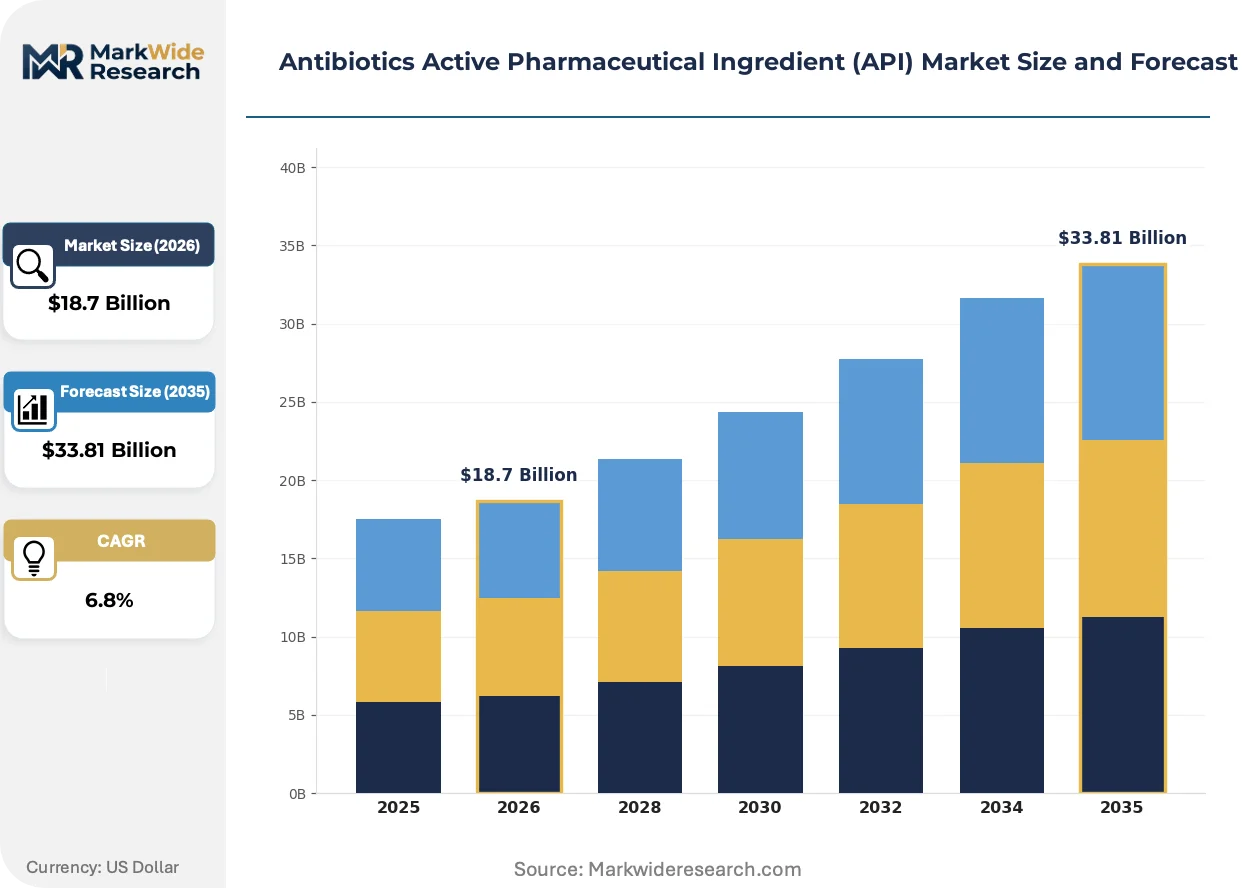
Antibiotics Active Pharmaceutical Ingredient (API) Market Outlook
The EU Green Deal is shifting procurement criteria for antibiotic APIs across European hospital networks and pharmaceutical buyers. Sun Pharmaceutical Industries leverages backward integration into fermentation infrastructure to secure cost advantages in penicillin production. Merck & Co. anchors its position through synthetic chemistry leadership in cephalosporin intermediates. Aurobindo Pharma competes aggressively on semi-synthetic macrolide volumes from Indian manufacturing campuses.
Antibiotics Active Pharmaceutical Ingredient denotes the biologically active core substance used in antibacterial drug formulations, typically manufactured through fermentation of microbial strains or multi-step organic synthesis with defined purity thresholds exceeding 99.5 percent and strict endotoxin controls for injectable grades. These molecules serve as the therapeutic foundation for finished dosage forms targeting bacterial infections across human and veterinary medicine. Penicillins retain the largest revenue pool among API types due to sustained hospital demand for beta-lactam therapy, while macrolides represent the fastest-expanding category driven by respiratory infection protocols in emerging markets. Synthetic manufacturing processes command premium pricing for complex cephalosporin intermediates, whereas fermentation-based production dominates volume output for tetracyclines and foundational penicillin cores.
FDA quality mandates, EMA GMP inspections, and India's CDSCO manufacturing licensing framework collectively shape market access barriers and supplier qualification timelines for antibiotic API producers. REACH compliance in Europe and China's NMPA environmental audits for fermentation facilities are forcing capital upgrades in wastewater treatment and solvent recovery systems. Stakeholders must monitor regulatory divergence between FDA Quality Management Maturity incentives and EU GMP Annex 1 revisions to anticipate which manufacturing geographies will absorb the next wave of contract manufacturing investment.
Market Dynamics
Hospital procurement of parenteral antibiotic formulations is accelerating as healthcare systems consolidate purchasing power and demand endotoxin-controlled injectable grades. The FDA's Quality Management Maturity program is compressing supplier qualification timelines while raising purity thresholds above 99.5 percent.
Growth Catalysts
- EU Green Deal procurement criteria:European hospital networks now mandate environmental footprint disclosures for antibiotic API sourcing, redirecting contract awards toward fermentation facilities with solvent recovery systems.
- India's CDSCO manufacturing licensing framework:Streamlined approvals for penicillin fermentation campuses are attracting contract manufacturing investment from multinational pharmaceutical buyers seeking cost-advantaged beta-lactam cores.
- Respiratory infection protocols:Emerging market hospital systems are expanding macrolide formularies, pulling semi-synthetic API volumes from Indian manufacturing clusters.
Market Restraints
- Penicillin G acylase cost volatility:Enzyme input prices for semi-synthetic cephalosporin intermediates fluctuate with agricultural commodity cycles, squeezing margin predictability for synthetic chemistry producers.
- Fermentation capacity concentration:Bulk tetracycline output depends on wastewater-treatment-compliant facilities clustered in China's Shandong province, creating single-geography supply vulnerability.
- EMA GMP Annex 1 revision friction:Contamination control requirements for sterile API manufacturing are extending facility validation timelines by 12-18 months for European contract manufacturers.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing zone:Underpenetrated fermentation infrastructure offers greenfield API capacity for penicillin and macrolide producers seeking alternatives to Indian and Chinese supply bases.
- Continuous flow synthesis convergence:Integration of photochemical reactors with solid-phase extraction is enabling miniaturized cephalosporin intermediate production at distributed manufacturing sites.
- Direct hospital contracting channels:Bypassing traditional wholesale distribution, API producers are establishing captive supply agreements with IDN procurement consortia in the United States.
Industry Challenges
- Fermentation microbiologist talent scarcity:Industrial strain optimization expertise is concentrating at legacy penicillin producers, constraining new entrant scale-up capabilities.
- Endotoxin testing certification bottlenecks:LAL assay validation for injectable-grade API release is extending quality control timelines at CDMOs without in-house horseshoe crab hemolymph processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotics Active Pharmaceutical Ingredient (API) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | API Type: Penicillins, Cephalosporins, Tetracyclines, Macrolides Manufacturing Process: Synthetic, Semi-Synthetic, Fermentation, Isolation End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutes, Hospitals Form: Powder, Liquid, Granule, Tablet |
| Companies Covered | Sun Pharmaceutical Industries, Merck & Co., Aurobindo Pharma, Boehringer Ingelheim International, AbbVie, Dr. Reddy's Laboratories, Cipla, Alkem Laboratories, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotics Active Pharmaceutical Ingredient (API) Market Strategic Shifts
Continuous manufacturing technologies are compressing batch cycle times for complex antibiotic intermediates while regulatory frameworks reward quality system maturity with abbreviated inspection frequencies. These shifts are reconfiguring capital deployment patterns across fermentation and synthetic chemistry asset bases.
Single-use bioreactor systems for penicillin fermentation are electrifying facility reconfiguration economics. Mid-scale Indian and Chinese producers are adopting disposable vessel technologies to avoid stainless steel cleaning validation burdens. This electrifying shift is enabling rapid product changeover between beta-lactam and macrolide campaigns without cross-contamination risk.
REACH compliance deadlines for solvent emissions are forcing fermentation facilities to install closed-loop recovery systems. European API producers face capital commitments exceeding €15 million per site for wastewater treatment upgrades. Cephalosporin intermediate manufacturers in Germany and Italy are responding by consolidating production at purpose-built greenfield sites with integrated environmental controls.
Hospital procurement consortia are unbundling API sourcing from finished dosage form contracts. Large integrated delivery networks in the United States now negotiate direct penicillin and macrolide API supply agreements, bypassing traditional wholesale channels. This disintermediation is most visible in the southeastern states where IDN consolidation has concentrated purchasing power among three major health systems.
Antibiotics Active Pharmaceutical Ingredient (API) Market Segmentation
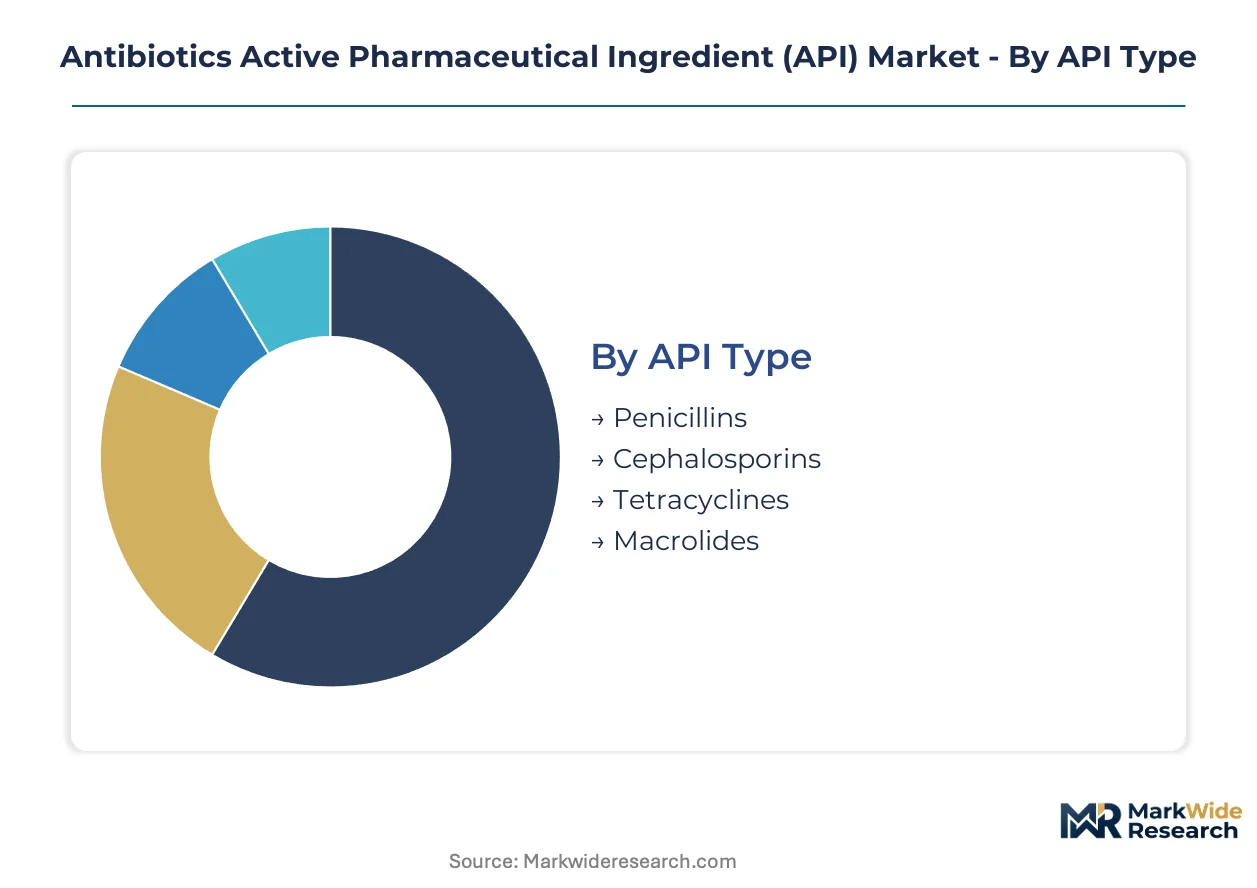
Antibiotic API procurement decisions hinge on purity thresholds, manufacturing geography, and endotoxin specifications that vary sharply across therapeutic classes and end-use applications. Buyers segment supply bases by fermentation versus synthetic routes to balance cost, regulatory compliance, and volume scalability.
API Type:
Hospital formularies drive purchasing concentration toward beta-lactam cores with established resistance profiles and respiratory infection protocols.
- Penicillins:Beta-lactam cores manufactured through fermentation of Penicillium chrysogenum strains achieve purity thresholds exceeding 99.5 percent for injectable grades. Demand concentrates in Indian manufacturing clusters serving hospital procurement consortia seeking cost-advantaged beta-lactam therapy.
- Macrolides:Semi-synthetic erythromycin derivatives require multi-step organic synthesis with strict endotoxin controls for parenteral formulations. Respiratory infection protocols in emerging market hospital systems are expanding macrolide formularies fastest.
- Cephalosporins:Complex intermediate synthesis commands premium pricing for sterile API grades.
- Tetracyclines:Fermentation-based bulk output dominates volume production from Shandong province facilities.
Penicillins lead on scale; macrolides lead on momentum.
Manufacturing Process:
Process selection determines capital intensity, environmental compliance burden, and regulatory inspection frequency across supplier qualification programs.
- Fermentation:Microbial strain cultivation in stainless steel or single-use bioreactor systems dominates penicillin and tetracycline volume output. India's CDSCO streamlined licensing is attracting contract manufacturing investment for beta-lactam fermentation campuses.
- Synthetic:Multi-step organic chemistry with defined stereochemistry produces cephalosporin intermediates and macrolide building blocks. REACH compliance deadlines in Europe are forcing €15 million capital commitments per site for solvent recovery systems.
- Semi-Synthetic:Enzymatic conversion of fermentation-derived precursors balances cost and complexity for macrolide production.
- Isolation:Natural product extraction serves niche glycopeptide and aminoglycoside APIs with limited synthetic alternatives.
Fermentation dominates volume economics; synthetic commands margin premiums.
End User:
Procurement consolidation is reshaping channel structures as integrated delivery networks bypass traditional wholesale distribution.
- Pharmaceutical Companies:Multinational buyers backward integrate into fermentation infrastructure or secure captive supply agreements with Indian and Chinese producers. FDA Quality Management Maturity incentives are compressing supplier qualification timelines for qualified vendors.
- Contract Manufacturers:CDMOs face extended LAL assay validation timelines without in-house horseshoe crab hemolymph processing capabilities.
- Hospitals:IDN procurement consortia in the southeastern United States negotiate direct API supply agreements, disintermediating wholesale channels.
- Research Institutes:Small-volume, high-purity requirements for clinical trial materials command specialized production runs.
Pharmaceutical companies anchor volume demand; hospitals are gaining procurement leverage fastest.
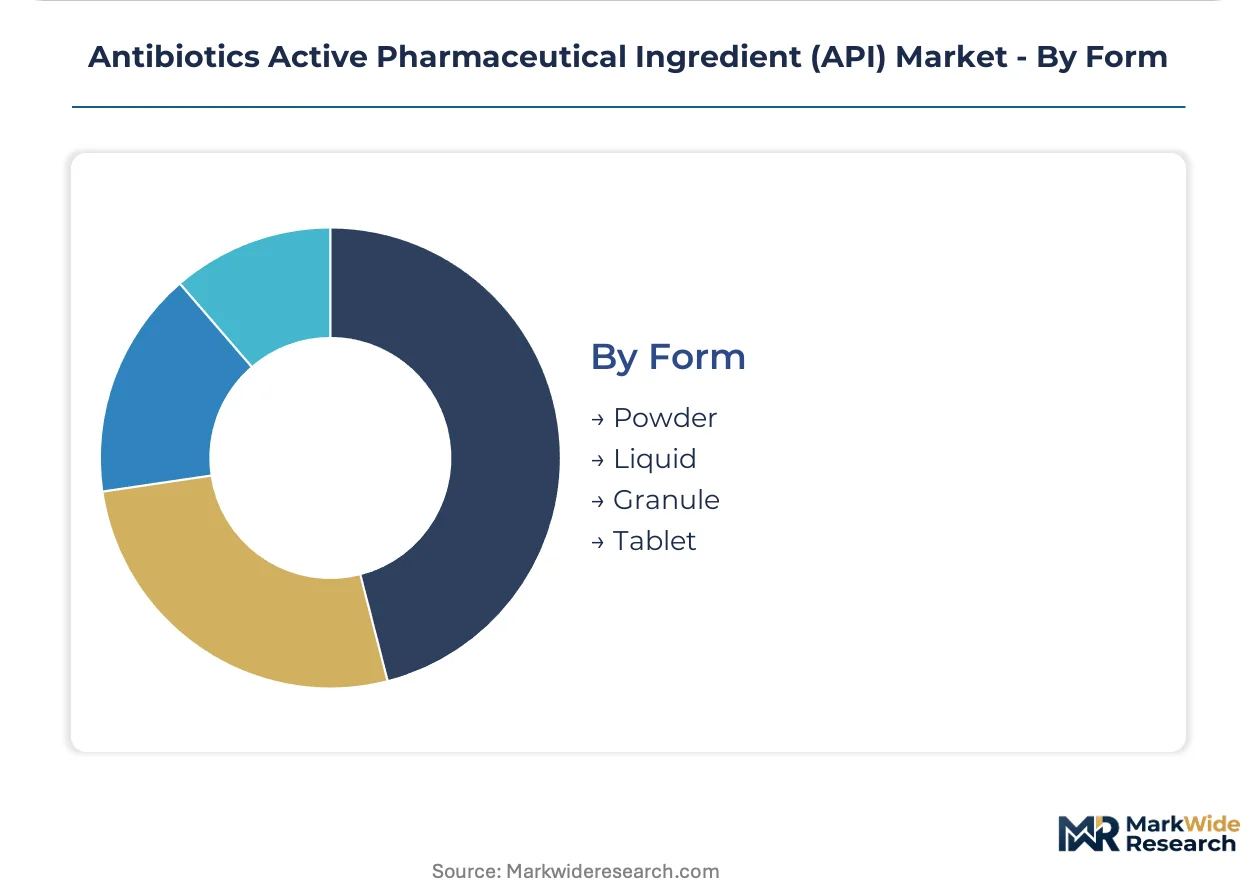
Form:
Physical presentation determines stability, handling protocols, and downstream formulation compatibility for finished dosage manufacturing.
- Powder:Crystalline or amorphous bulk API with defined particle size distribution for tablet compression or sterile reconstitution. Parenteral-grade powders require endotoxin-controlled manufacturing environments extending facility validation timelines.
- Liquid:Solution or suspension formulations for immediate-use injectables and oral syrups.
- Granule:Agglomerated particles for direct compression or capsule filling with improved flow properties.
- Tablet:Pre-formulated API-excipient combinations for hospital pharmacy compounding.
Powder leads on manufacturing throughput; liquid concentrates value in sterile applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern antibiotics API industry traces its industrial lineage to mid-20th century fermentation breakthroughs in the United Kingdom and subsequent scale-up in the United States, before manufacturing gravity shifted toward cost-optimized Asian production bases.
United States
Hospital procurement consortia in the southeastern states now negotiate direct penicillin and macrolide API supply agreements, bypassing traditional wholesale distribution channels. FDA Quality Management Maturity incentives compress supplier qualification timelines for qualified vendors. Integrated delivery networks in Texas and Florida anchor the fastest-growing direct contracting channels.
India
CDSCO streamlined licensing for penicillin fermentation campuses attracts contract manufacturing investment from multinational pharmaceutical buyers. Maharashtra and Gujarat host concentrated fermentation infrastructure serving global beta-lactam demand. Sun Pharmaceutical Industries leverages backward integration into fermentation assets to secure cost advantages.
China
NMPA environmental audits for fermentation facilities force capital upgrades in Shandong province wastewater treatment systems. Tetracycline bulk output depends on compliant facilities clustered in this eastern coastal region. REACH-equivalent domestic standards are consolidating production at purpose-built greenfield sites.
Germany
EMA GMP Annex 1 revision friction extends sterile API facility validation timelines by 12-18 months for contract manufacturers. Cephalosporin intermediate producers face €15 million capital commitments per site for solvent recovery systems. Bavarian and North Rhine-Westphalian chemical parks consolidate synthetic chemistry production at integrated environmental control sites.
Switzerland
Swissmedic oversight of sterile manufacturing maintains premium positioning for high-purity cephalosporin intermediates. Basel-region chemical engineering expertise anchors synthetic route development for complex antibiotic building blocks. Domestic producers command margin premiums through regulatory compliance leadership.
Antibiotics Active Pharmaceutical Ingredient (API) Market Competitive Environment
Capital-heavy fermentation operators compete with asset-light synthetic chemistry specialists across distinct manufacturing economics. The supplier base organizes into three tiers: integrated pharmaceutical conglomerates with captive fermentation assets, mid-scale contract manufacturers serving hospital procurement channels, and specialized intermediate producers focused on cephalosporin building blocks. Dominant competitive moves include backward integration into fermentation infrastructure and geographic diversification beyond Chinese and Indian supply bases.
Within the integrated pharmaceutical tier, Sun Pharmaceutical Industries and Merck & Co. exemplify divergent strategic positions. Sun Pharmaceutical anchors cost-competitive penicillin output through Indian fermentation scale. Merck & Co. occupies a position defined by synthetic chemistry leadership in cephalosporin intermediates. Among mid-scale Indian producers, Aurobindo Pharma represents aggressive volume competition in semi-synthetic macrolide segments.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries |
| Merck & Co. |
| Aurobindo Pharma |
| Boehringer Ingelheim International |
| AbbVie |
| Dr. Reddy's Laboratories |
| Cipla |
| Alkem Laboratories |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consortia in the southeastern United States anchor pricing power through direct API contracting, compressing wholesale margins and forcing three-tier pricing stratification across injectable-grade, oral-grade, and bulk-intermediate categories. This buyer concentration shifts pricing leverage toward volume-scaled fermentation producers with FDA Quality Management Maturity certification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates endotoxin-controlled sterile grades from oral-formulation powders and unprocessed fermentation broths. Price differentiation hinges on FDA certification tier and geographic delivery cost from Indian or Chinese manufacturing clusters. Pricing pressure stems from penicillin G acylase cost volatility tied to agricultural commodity cycles. Contract manufacturers exhibit highest price sensitivity, while integrated pharmaceutical conglomerates with captive fermentation assets absorb input fluctuations through backward integration economics.
Supply Chain Analysis
Direct-to-hospital channels handle consolidated IDN procurement demand, bypassing traditional wholesale distribution. Geographic supply concentration centers on India, China, and Germany for fermentation infrastructure, synthetic chemistry expertise, and sterile finishing capabilities respectively. Raw material dependencies include corn steep liquor for microbial cultivation, specialized enzyme inputs for semi-synthetic conversion, and solvent systems for crystallization. Single-source vulnerability persists in Shandong province tetracycline fermentation capacity. Distribution runs through captive supply agreements, spot-market intermediates, and long-term offtake contracts with multinational pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary expansion for beta-lactam and macrolide therapy anchors this market as a stable compounder, with inpatient infection protocols driving predictable volume absorption across economic cycles.
For Market Incumbents: Anchor defensive positioning through fermentation capacity consolidation in Maharashtra and Gujarat manufacturing clusters. Prioritize CDSCO licensing maintenance and FDA Quality Management Maturity certification renewal to compress supplier qualification timelines. Defend against emerging Vietnamese fermentation entrants by locking long-term offtake agreements with southeastern U.S. IDN procurement consortia. Channel control through direct hospital contracting represents the critical lever for margin protection. For New Entrants and Emerging Players: India's CDSCO streamlined licensing framework opens a window for mid-scale penicillin fermentation investment with abbreviated approval timelines. Target Vietnam's underpenetrated pharmaceutical manufacturing zones as the most penetrable geography for greenfield API capacity. Macrolide semi-synthetic production serves as the fastest-expanding white-space segment driven by respiratory infection protocol adoption. A go-to-market angle emphasizing single-use bioreactor flexibility enables rapid product changeover between beta-lactam and macrolide campaigns. For Investors and Strategic Acquirers: Integrated delivery networks and multinational pharmaceutical buyers represent the most active acquirer categories in this space, seeking captive supply security through fermentation asset ownership. Long-term viability frames around 5-10 year hospital procurement consolidation trends and regulatory divergence between FDA and EMA quality mandates. Acquisition target archetypes include mid-scale Indian CDMOs with CDSCO licensing and sterile API validation capabilities. Monitor EMA GMP Annex 1 revision implementation timelines as the signal for European contract manufacturing distress and consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Sun Pharmaceutical secures cost advantages in penicillin cores through captive microbial strain cultivation infrastructure. |
| FDA Quality Management Maturity Certification | Abbreviated inspection frequencies reward mature quality systems with faster supplier qualification for hospital procurement channels. |
| Single-Use Bioreactor Adoption | Mid-scale Indian producers avoid stainless steel cleaning validation burdens while enabling rapid beta-lactam to macrolide campaign switching. |
| Direct Hospital Contracting Channels | IDN procurement consortia in Texas and Florida bypass wholesale distribution through captive penicillin and macrolide supply agreements. |
| REACH-Compliant Solvent Recovery Systems | German cephalosporin intermediate producers consolidate at purpose-built greenfield sites with integrated €15 million environmental controls. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, regulatory affairs leads at CDSCO and FDA, hospital procurement directors at southeastern U.S. IDNs, and pharmaceutical buyer sourcing executives with secondary validation against FDA 483 inspection observations, EMA GMP inspection databases, CDSCO manufacturing licensing records, and customs trade data for antibiotic API import flows. Bottom-up facility capacity assessments and top-down hospital procurement spend estimates provided triangulation anchors.
Historical reference periods spanning fermentation yield improvements, regulatory inspection frequency shifts, and hospital procurement consolidation waves anchored the projection framework across the analysis window. Segmentation dimensions modeled include API type, manufacturing process route, end-user channel structure, and endotoxin specification tier. CAGRs derived from volume absorption curves tied to inpatient infection protocol expansion and pricing trajectories reflecting input cost volatility and certification premium dynamics. Forecast inputs incorporated CDSCO licensing approval velocity and EMA GMP Annex 1 revision implementation friction.
Revisions become necessary when FDA Quality Management Maturity program criteria shift, EU Green Deal procurement mandates accelerate, or NMPA environmental audit intensity disrupts Shandong province tetracycline output. Forecasts reflect documented assumptions around hospital formulary stability and fermentation microbiologist labor supply. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market