
 Global Active Pharmaceutical Ingredients CDMO Market | 2026-2036
Global Active Pharmaceutical Ingredients CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Global Active Pharmaceutical Ingredients CDMO Market Foresight
Continuous manufacturing is rewriting how active pharmaceutical ingredients are produced, replacing batch processes with real-time flow chemistry that slashes cycle times and variability. Lonza Group leverages its biologics network to anchor high-potency antibody-drug conjugate production in Switzerland and Singapore. Thermo Fisher Scientific sustains analytical dominance through integrated testing platforms that span drug substance to finished dose. Samsung Biologics competes on mammalian cell culture scale, operating what ranks among the world's largest single-site biologics manufacturing campuses.
An active pharmaceutical ingredients contract development and manufacturing organization is a third-party entity that designs, synthesizes, and produces drug substances under GMP conditions, typically handling molecular weights from 200 Da for small molecules to 150 kDa for monoclonal antibodies and purities exceeding 99.5% for commercial batches. Its primary purpose is to let pharmaceutical sponsors avoid capital-intensive manufacturing infrastructure while accessing specialized chemistries and regulatory filing support. Small molecules still occupy the largest revenue pool, though biologics segments are pulling investment toward single-use bioreactor capacity and continuous downstream processing. Peptide manufacturing is accelerating as GLP-1 receptor agonist demand outstrips internal capacity at major sponsors, drawing CDMOs into solid-phase synthesis scale-up.
FDA inspections under the Drug Supply Chain Security Act, EMA's revised GMP Annex 1 for sterile manufacture, and WHO prequalification standards collectively determine which CDMOs can supply regulated markets, creating a compliance moat that favors established players with dedicated regulatory affairs teams. India's CDSCO and China's NMPA are adding their own data integrity requirements, forcing multinational CDMOs to maintain parallel quality systems. Stakeholders must monitor which CDMOs are committing capital to continuous processing and modular facility designs before capacity constraints force sponsor portfolios into suboptimal partnerships.
Market Dynamics
Continuous flow chemistry is compressing batch cycle times and forcing CDMOs to reconfigure fixed-asset footprints or lose sponsor contracts to modular competitors. This technological inflection redistributes competitive advantage toward players with capital reserves for real-time process analytical technology deployment.
Growth Catalysts
- EMA's tightened GMP Annex 1:Sterile manufacturing mandates for advanced therapy medicinal products are driving sponsors toward CDMOs with dedicated containment infrastructure and isolator technology.
- GLP-1 peptide synthesis:Solid-phase manufacturing demand for diabetes and obesity therapeutics is pulling capacity investment away from traditional small-molecule campaigns.
- Switzerland's clustered biologics hubs:Cantonal tax incentives and proximity to Novartis and Roche headquarters concentrate high-potency antibody-drug conjugate development.
Market Restraints
- Single-use consumables cost volatility:Bioprocess bags and connectors face resin supply constraints from petrochemical feedstock fluctuations, squeezing margin on mammalian cell culture campaigns.
- Indian API intermediate concentration:Reliance on Hyderabad and Ahmedabad for key starting materials creates geographic vulnerability to monsoon logistics disruptions and power grid instability.
- High-potency containment capex floors:Occupational exposure band 5 facilities require $200M+ investment for isolated filling lines, excluding mid-tier CDMOs from oncology antibody-drug conjugate work.
Strategic Opportunities
- Brazil's ANVISA alignment with FDA:Mutual recognition agreements for GMP inspections open regulated-market supply pathways for Latin American manufacturing investment.
- Continuous downstream processing convergence:Simulated moving bed chromatography integrated with single-use tangential flow filtration enables 40% footprint reduction for monoclonal antibody purification.
- Korea's MFDS orphan drug incentives:Tax credits and expedited review for rare disease APIs attract sponsor partnerships for low-volume, high-margin peptide manufacturing.
Industry Challenges
- Process analytical technology skill scarcity:Spectroscopy and chemometric modeling expertise for real-time release testing outpaces university training programs in India and Eastern Europe.
- Legacy ERP integration with digital twins:Batch record systems from the 2000s require multimillion-dollar middleware overhauls to connect with AI-driven predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Active Pharmaceutical Ingredients CDMO Market |
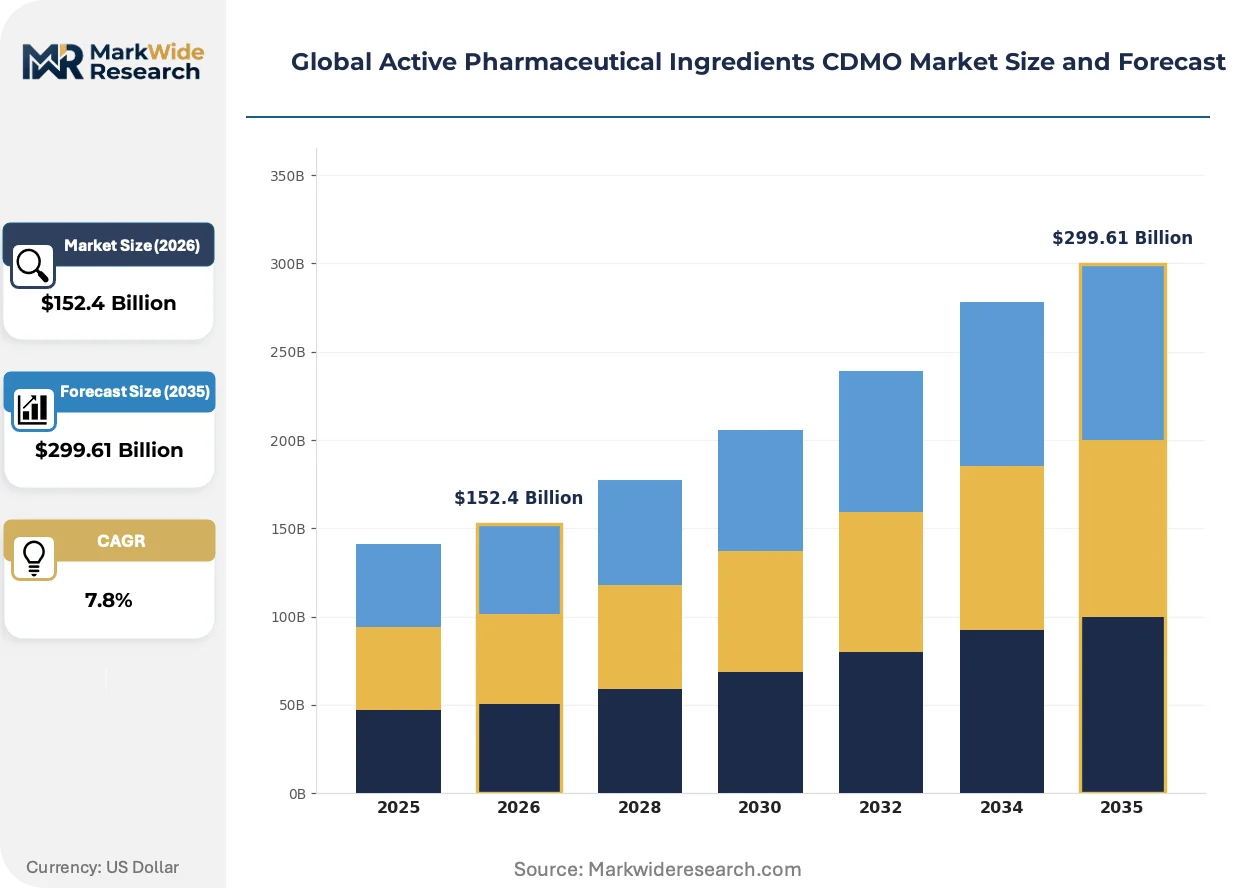
| Market Size in 2026 | $152.4 Billion |
| Market Size in 2035 | $299.61 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Peptides, Oligonucleotides, Radiopharmaceuticals Service Type: Synthesis, Analytical & Testing, Process Development, Formulation Support, Regulatory Services Therapy Area: Oncology, Neurology, Cardiovascular, Infectious Diseases, Immunology, Endocrinology End User: Pharmaceutical Companies, Biotechnology Firms, Generic Drug Manufacturers, Research Institutes |
| Companies Covered | Lonza Group, Thermo Fisher Scientific Inc., Catalent Inc., Cambrex Corporation, Recipharm AB, CordenPharma International, Samsung Biologics, Siegfried Holding AG, Piramal Pharma Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Active Pharmaceutical Ingredients CDMO Market Shifts & Advancements
Modular facility architectures and real-time quality verification are collapsing development-to-commercialization timelines. These shifts reward CDMOs with standardized platform processes and punish those locked into rigid stainless-steel infrastructures.
Continuous manufacturing is migrating from early-phase feasibility studies to commercial-scale small-molecule API production. Mid-sized sponsors in oncology and antiviral segments are adopting flow chemistry for kiloton campaigns to reduce solvent waste and variability. The technology is migrating from batch-replacement experiments to default process design, compressing regulatory filing timelines and enabling geographic flexibility through containerized production units.
FDA's quality-by-design mandates under ICH Q8-Q12 guidelines now require predefined design spaces and control strategies prior to commercial approval. This regulatory architecture forces CDMOs to invest in mechanistic modeling and multivariate data analysis capabilities before engaging Phase III sponsors. Small-molecule generic API manufacturers face the steepest compliance curve, as their historical reliance on empirical optimization conflicts with the agency's demand for first-principles understanding.
Sponsor technical diligence now prioritizes CDMOs with integrated drug-substance-to-drug-product capabilities, collapsing the traditional two-vendor model. Large pharmaceutical buyers are consolidating supplier lists and demanding single-point accountability for CMC regulatory submissions. This concentration is most visible in Switzerland and Singapore, where clustered hubs enable sponsor technical staff to co-locate with CDMO development teams during critical transfer phases.
Global Active Pharmaceutical Ingredients CDMO Market Segmentation
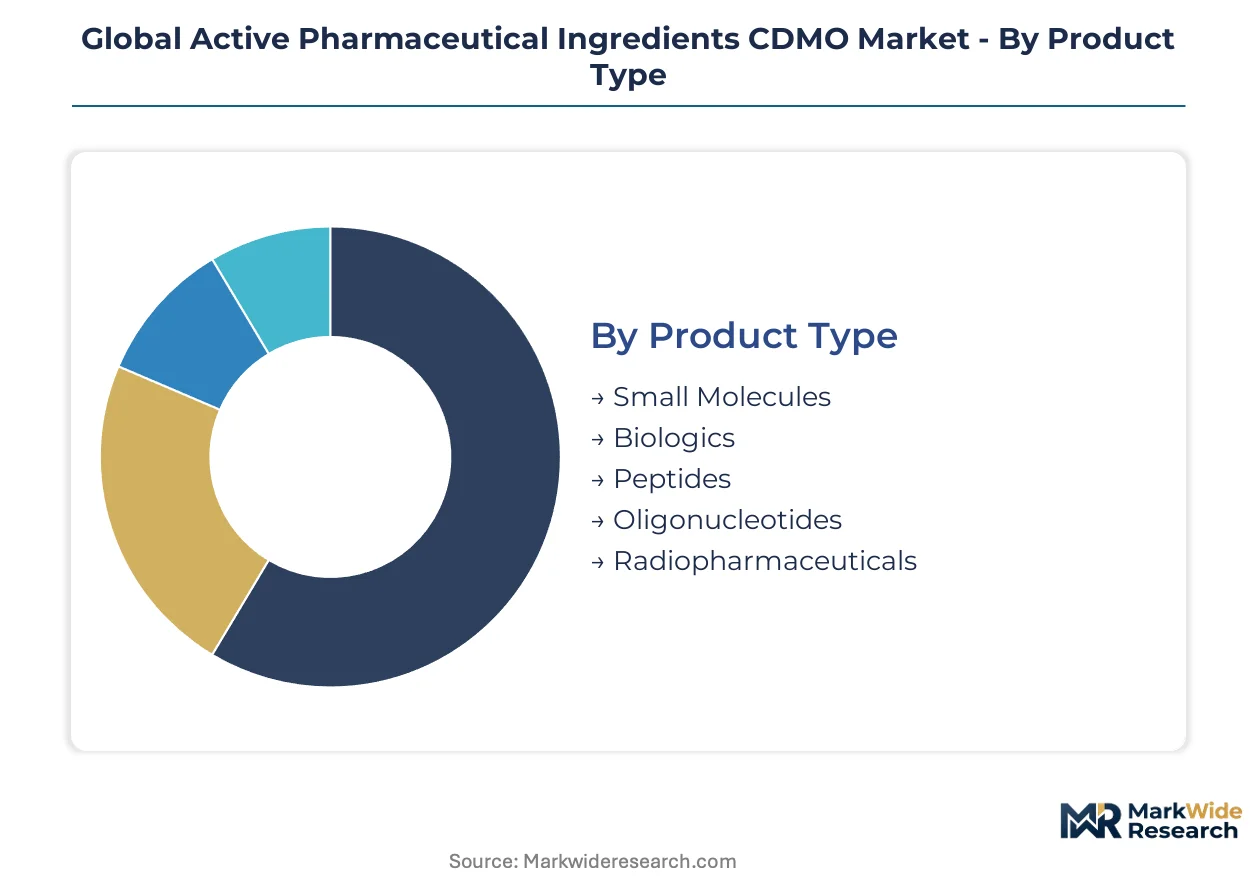
Segmentation in the API CDMO market determines capital allocation patterns and partnership structures. Cycle times vary dramatically across molecular classes, with small-molecule campaigns completing in months while biologics programs stretch across years. Understanding these velocity differentials helps sponsors align portfolio timelines with CDMO capability matrices.
Product Type:
Small molecules turn inventory fastest with standardized synthetic routes, while radiopharmaceuticals require just-in-time production due to isotope half-life constraints. Cycle velocity directly dictates facility utilization rates and working capital intensity across CDMO networks.
- Small Molecules:Synthetic organic compounds typically below 900 Da manufactured through batch or continuous flow chemistry. Demand concentrates in India and China for generic API intermediates, though Switzerland and Singapore capture high-value oncology small molecules where containment infrastructure justifies premium positioning.
- Biologics:Proteins and monoclonal antibodies exceeding 5 kDa produced via mammalian or microbial cell culture. Samsung Biologics and Lonza Group anchor capacity in South Korea and Switzerland, drawing sponsor investment toward single-use bioreactor platforms that compress changeover timelines between campaigns.
- Peptides:Solid-phase synthesis drives production of GLP-1 receptor agonists for diabetes and obesity indications.
- Oligonucleotides:Antisense and siRNA therapeutics require specialized phosphoramidite chemistry with stringent purity thresholds.
- Radiopharmaceuticals:Isotope-tagged diagnostics and therapeutics demand cyclotron-adjacent production with 6-72 hour distribution windows.
Small molecules anchors the volume base while peptides gains share at the steepest rate.
Service Type:
Cost tier stratification separates commodity synthesis from high-margin regulatory services, with analytical capabilities occupying the middle tier. CDMOs bundle services to capture margin expansion as sponsors progress from early-phase to commercial supply.
- Synthesis:Route scouting, kilo-lab scale-up, and commercial manufacturing of drug substances. Thermo Fisher Scientific and Cambrex dominate high-potency chemistry in North America and Europe, leveraging containment infrastructure that mid-tier competitors cannot replicate.
- Analytical & Testing:Method development, stability studies, and release testing under ICH Q2(R1) guidelines. Integrated CDMOs co-locate analytical suites with manufacturing to compress batch release timelines and reduce sponsor quality oversight burden.
- Process Development:Design space definition, scale-up validation, and technology transfer to commercial facilities.
- Formulation Support:Preformulation, solubility enhancement, and compatibility studies bridging drug substance to drug product.
- Regulatory Services:CMC documentation, agency correspondence, and inspection readiness preparation.
Synthesis commands the largest revenue pool while regulatory services delivers the highest margin contribution.
Therapy Area:
Application-driven demand concentrates in oncology and immunology, where high-potency handling requirements create capability moats. Cardiovascular and infectious disease programs face pricing pressure from generic competition, compressing CDMO margins unless specialized delivery technologies are involved.
- Oncology:Cytotoxic small molecules, antibody-drug conjugates, and targeted protein degraders requiring occupational exposure band 4-5 containment. Switzerland's Basel region and Singapore's Tuas Biomedical Park cluster ADC manufacturing due to proximity to Roche, Novartis, and regional sponsor R&D headquarters.
- Neurology:Blood-brain barrier penetration challenges drive demand for lipid nanoparticle and prodrug formulation expertise.
- Cardiovascular:Statins and anticoagulants face commoditization pressure from Indian and Chinese API manufacturers.
- Infectious Diseases:Antiviral and antibiotic campaigns surge during pandemic preparedness initiatives but contract between public health emergencies.
- Immunology:Monoclonal antibodies for autoimmune conditions require mammalian cell culture capacity at 10,000L+ scale.
- Endocrinology:GLP-1 peptides and insulin analogs pull solid-phase synthesis investment away from traditional small-molecule infrastructure.
Oncology anchors the volume base while endocrinology climbs the fastest on obesity therapeutic demand.
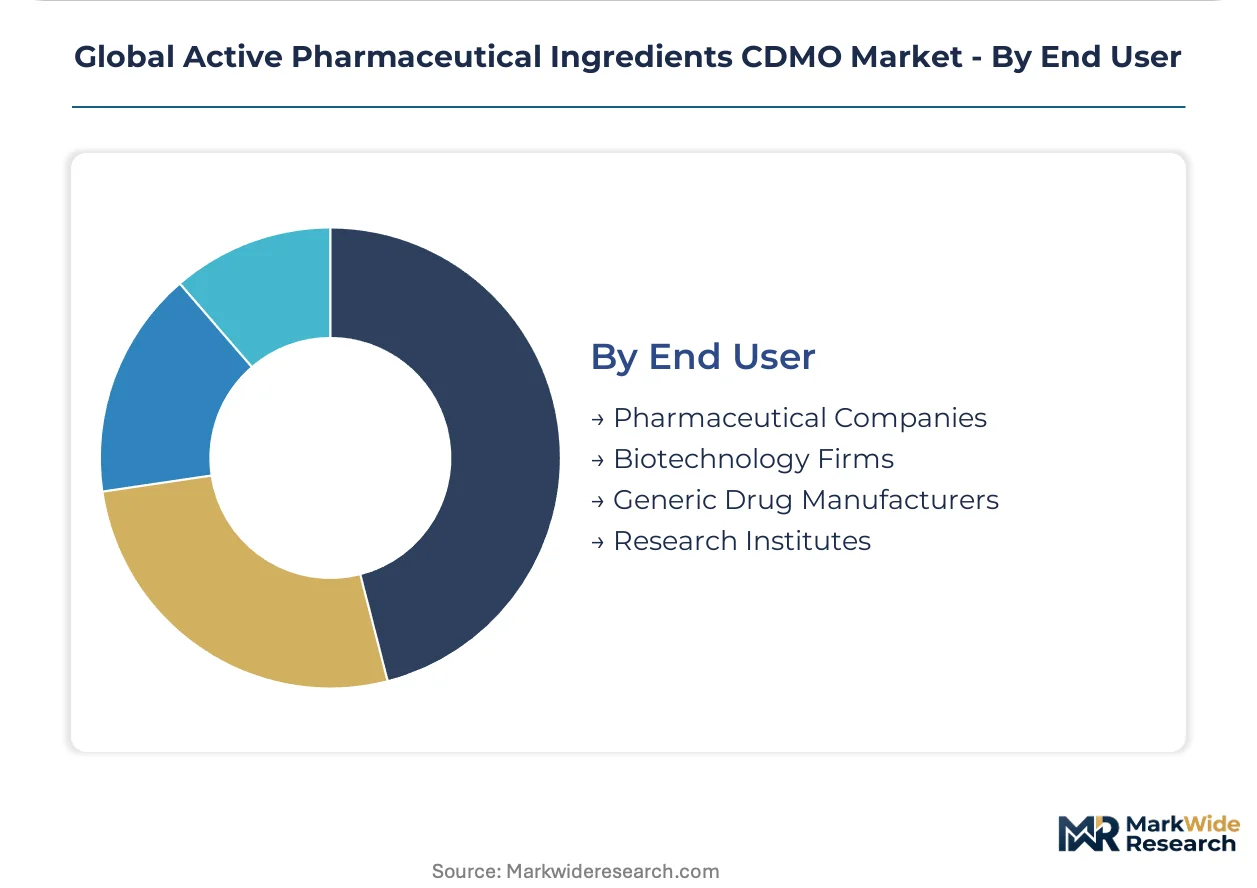
End User:
Customer type determines contract structure, with large pharmaceutical companies demanding integrated drug-substance-to-drug-product accountability while biotechnology firms prioritize speed and flexibility over scale. Generic manufacturers squeeze pricing through competitive tender processes.
- Pharmaceutical Companies:Multinational sponsors like Pfizer, Merck, and AstraZeneca consolidate supplier lists and demand single-point CMC accountability. These buyers co-locate technical staff with CDMO development teams in Switzerland and Singapore during critical technology transfer phases.
- Biotechnology Firms:Venture-backed developers prioritize speed-to-IND and flexible capacity reservation agreements over long-term commercial supply commitments.
- Generic Drug Manufacturers:Cost-driven procurement from India and China concentrates on commoditized API intermediates with thin margin structures.
- Research Institutes:Academic and government laboratories require small-batch GMP production for investigator-initiated trials and rare disease programs.
Pharmaceutical companies anchors the volume base while biotechnology firms expands most quickly on cell and gene therapy pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports API intermediates to regulated markets in Europe and North America, while Switzerland and Singapore capture high-value biologics campaigns through clustered manufacturing hubs.
Switzerland
Basel's cantonal tax incentives draw antibody-drug conjugate manufacturing for Roche and Novartis pipelines. Swissmedic enforces stringent GMP standards for high-potency containment facilities. The Basel region clusters Lonza Group and Siegfried Holding AG operations alongside sponsor R&D headquarters.
Singapore
Tuas Biomedical Park anchors mammalian cell culture capacity for diabetes and obesity therapeutic supply. The Economic Development Board offers tax holidays for biologics manufacturing investment. Samsung Biologics and Lonza Group operate integrated development-to-commercialization campuses in the city-state.
United States
Massachusetts and North Carolina concentrate cell and gene therapy CDMO capacity near Boston and Research Triangle Park sponsors. FDA quality-by-design mandates under ICH Q8-Q12 require predefined design spaces before commercial approval. Thermo Fisher Scientific maintains analytical testing dominance through integrated platforms spanning drug substance to finished dose.
India
Hyderabad and Ahmedabad supply generic API intermediates to European and North American generic manufacturers. CDSCO data integrity requirements force multinational CDMOs to maintain parallel quality systems. Piramal Pharma Solutions anchors high-potency chemistry capacity in Mumbai and Ahmedabad for export markets.
South Korea
Songdo International Business District clusters biologics manufacturing for regional sponsor supply. MFDS orphan drug incentives attract partnerships for low-volume peptide manufacturing. Samsung Biologics operates among the world's largest single-site mammalian cell culture campuses in Incheon.
Global Active Pharmaceutical Ingredients CDMO Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where capital reserves determine access to high-potency containment and continuous processing capabilities. The vendor base stratifies between integrated platforms offering drug-substance-to-drug-product accountability and specialized boutiques serving early-phase sponsors. Two dominant archetypes emerge: diversified life science conglomerates with analytical dominance and pure-play CDMOs with geographic concentration in Switzerland or Singapore. Competitive moves center on capacity expansion in single-use bioreactor platforms and strategic partnerships to secure GLP-1 peptide synthesis campaigns.
Within the integrated-platform tier, Thermo Fisher Scientific and Lonza Group exemplify channel-controlling archetypes through analytical testing networks and biologics manufacturing scale. Samsung Biologics occupies a position at the capacity-driven end, representing the scale-specialist archetype with mammalian cell culture infrastructure. Piramal Pharma Solutions sits within the emerging-market pure-play tier, anchoring high-potency chemistry capabilities for export to regulated markets. These three company structures illustrate how geographic origin and corporate form signal strategic positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Lonza Group |
| Thermo Fisher Scientific Inc. |
| Catalent Inc. |
| Cambrex Corporation |
| Recipharm AB |
| CordenPharma International |
| Samsung Biologics |
| Siegfried Holding AG |
| Piramal Pharma Solutions |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp petrochemical corridor channels solvent and reagent feedstock costs directly into API CDMO pricing tiers, concentrating cost advantages among Swiss and Singaporean hubs with integrated logistics while forcing Indian and Chinese competitors into sharper price competition on generic intermediates.
Pricing Analysis
Batch-process pricing gaps against continuous manufacturing platforms now exceed containment-infrastructure premiums, with stainless-steel legacy facilities bleeding margin to modular competitors deploying real-time process analytical technology. Pricing stratifies across premium, standard, and economy tiers based on occupational exposure band certification and single-use bioreactor scale. Cost compression in generic small-molecule intermediates is intensifying because Indian CDMOs face CDSCO data integrity compliance investments. Biotechnology firms exhibit highest price sensitivity due to venture-capital runway constraints, while large pharmaceutical companies prioritize single-point CMC accountability over unit cost.
Supply Chain Analysis
Petrochemical-derived solvents and phosphoramidite reagents anchor upstream cost structures for peptide and oligonucleotide synthesis, drawing supply security focus toward vertically integrated feedstock producers. Manufacturing concentrates in Switzerland, Singapore, and South Korea for high-potency biologics, with India and China dominating generic API intermediate output. Single-source vulnerability haunts the single-use bioprocess bag segment due to resin supply constraints from concentrated polymer producers. Distribution runs through sponsor-integrated logistics networks for temperature-sensitive biologics, while small molecules move via established pharmaceutical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API CDMO demand tracks biopharmaceutical R&D cycle recovery, with sponsor outsourcing intensity climbing as pipeline advancement resumes post-capital-contraction period.
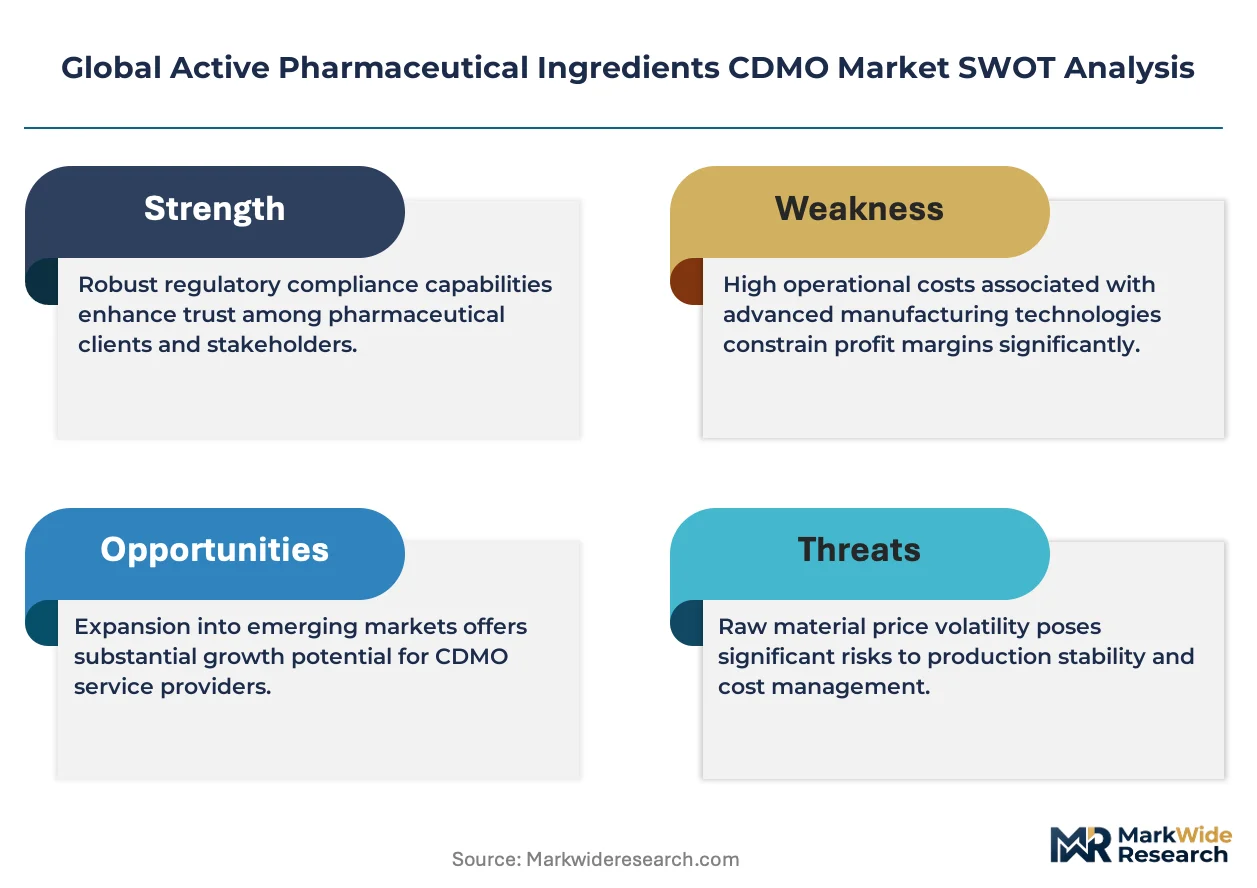
For Market Incumbents: Insulate high-potency containment capabilities through isolator-technology upgrades that EMA's revised GMP Annex 1 mandates, while securing GLP-1 peptide synthesis campaigns before capacity scarcity forces sponsor portfolio diversion. Backward integration into solid-phase synthesis resin supply hedges phosphoramidite cost volatility threatening margin structures. For New Entrants and Emerging Players: Establish a beachhead in radiopharmaceutical CDMO services where cyclotron-proximity requirements create geographic moats against scale competitors. Korea's MFDS orphan-drug incentive zone offers penetrable regulatory entry with tax-credit offsets for low-volume peptide manufacturing investment. Go-to-market positioning should emphasize modular facility architectures enabling sponsor co-location during technology transfer phases. For Investors and Strategic Acquirers: Pure-play peptide synthesis specialists with solid-phase scale-up capabilities represent acquisition targets positioned for GLP-1 demand inflection. Long-term viability hinges on continuous processing technology maturation across the analysis window. Watch FDA quality-by-design enforcement intensity as signal for sponsor consolidation toward integrated-platform CDMOs versus fragmented vendor bases.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Flow chemistry deployment compresses batch cycle times and reduces solvent waste for oncology API campaigns. |
| Single-Use Bioreactor Capacity Expansion | Samsung Biologics and Lonza Group anchor mammalian cell culture scale for monoclonal antibody supply security. |
| High-Potency Containment Investment | Isolator-technology facilities in Switzerland meet EMA sterile manufacturing mandates for antibody-drug conjugates. |
| GLP-1 Peptide Synthesis Partnership | Solid-phase manufacturing alliances capture diabetes and obesity therapeutic demand outpacing sponsor internal capacity. |
| Regulatory Affairs Integration | Dedicated CMC documentation teams navigate FDA ICH Q8-Q12 design-space requirements for commercial approval pathways. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, CMC program managers, and CDMO procurement directors anchored the qualitative base, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and sponsor annual disclosures. Bottom-up capacity assessments triangulated with top-down spending pattern analysis across the projection horizon.
Scenario-bracketing framed volume and value outputs across molecular class, service tier, therapy area, and end-user archetype dimensions. CAGRs derived from sponsor pipeline advancement rates, capacity utilization trajectories, and regulatory approval velocity assumptions. Forecast inputs incorporated continuous manufacturing adoption curves and GLP-1 peptide demand elasticity parameters.
Sensitivities concentrate around biopharmaceutical capital market conditions, EMA inspection enforcement intensity, and single-use consumables resin supply stability. Cross-checking against sponsor R&D spending disclosures and CDMO backlog reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market