
 Sulphonamides Market | 2026-2036
Sulphonamides Market Size, Share, and Industry Trends Forecast 2026-2036
Sulphonamides Market Outlook
Hospital procurement consolidation is expanding across integrated delivery networks, pulling volume toward centralized formulary decisions. Teva Pharmaceutical Industries Ltd leverages its broad generic portfolio to sustain contract wins with these consolidated buyers. Pfizer Inc. anchors hospital trust through legacy brand recognition in anti-infective therapy. Sun Pharmaceutical Industries Ltd competes on cost-engineered sulfamethoxazole supply to price-sensitive institutional channels.
Sulphonamides are synthetic antimicrobial agents containing the sulfonamide functional group (SO₂NH₂), manufactured through chlorosulfonation of acetanilide followed by amination, primarily used to inhibit bacterial folate synthesis in systemic and topical infections. Sulfamethoxazole dominates prescription volume due to its fixed-dose pairing with trimethoprim, while oral delivery mode captures the largest patient-access footprint across outpatient settings. Injectable formulations command premium positioning in sepsis and surgical prophylaxis where rapid therapeutic levels prove critical.
FDA antimicrobial stewardship requirements, EMA's tightened environmental risk assessments for API discharge, and India's CDSCO bulk drug park incentives collectively reshape manufacturing location decisions and product registration pathways. The EU REACH framework adds compliance cost layers for European formulation exporters sourcing Chinese intermediates. Stakeholders must monitor regulatory divergence between FDA abbreviated new drug application bioequivalence standards and emerging WHO prequalification requirements for sulphonamide fixed-dose combinations.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins across North America and Western Europe, forcing API suppliers to restructure contract terms around volume guarantees and formulary exclusivity rather than price competition alone.
Growth Catalysts
- Antimicrobial Stewardship Mandates:FDA's tightened prescribing guidelines are sustaining demand for established sulphonamide therapies with proven resistance profiles in institutional settings.
- India's Bulk Drug Park Incentives:CDSCO-backed manufacturing clusters are attracting sulfamethoxazole API investment through subsidized land and duty exemptions on imported intermediates.
- Fixed-Dose Combination Standardization:WHO prequalification pathways for sulfamethoxazole-trimethoprim combinations are opening procurement access in donor-funded health programs across sub-Saharan Africa.
Market Restraints
- API Supply Concentration:Chinese intermediate manufacturers control 70% of chlorosulfonation feedstock, exposing formulators to single-source disruption risk during environmental compliance crackdowns.
- Resistance Surveillance Requirements:ECDC and CDC resistance tracking protocols are narrowing empirical prescribing windows for sulphonamides in uncomplicated urinary tract infections.
- Substitute Antibiotic Classes:Fluoroquinolones and cephalosporins are displacing sulphonamides in outpatient respiratory indications where rapid symptom resolution drives physician preference.
Strategic Opportunities
- Topical Dermatology Expansion:Silver sulfadiazine formulations for burn care are penetrating Middle Eastern hospital networks where trauma center construction is accelerating.
- EMA Environmental Risk Assessments:Tighter API discharge standards are creating first-mover advantage for European manufacturers with closed-loop wastewater systems and green chemistry certifications.
- Direct-to-Pharmacy Distribution:Bypassing wholesale intermediaries is enabling generic API suppliers to capture margin in India's fragmented retail pharmacy sector.
Industry Challenges
- Chlorosulfonation Expertise Scarcity:The specialized chemical engineering talent required for SO₂NH₂ functional group synthesis is retiring faster than training programs replace it.
- Bioequivalence Study Backlogs:FDA abbreviated new drug application queues are extending time-to-market for generic sulfamethoxazole-trimethoprim entrants by 18-24 months.
- Legacy Equipment Retrofit Costs:Batch reactor systems at mid-scale API plants require capital-intensive upgrades to meet current good manufacturing practice containment standards for potent compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulphonamides Market |
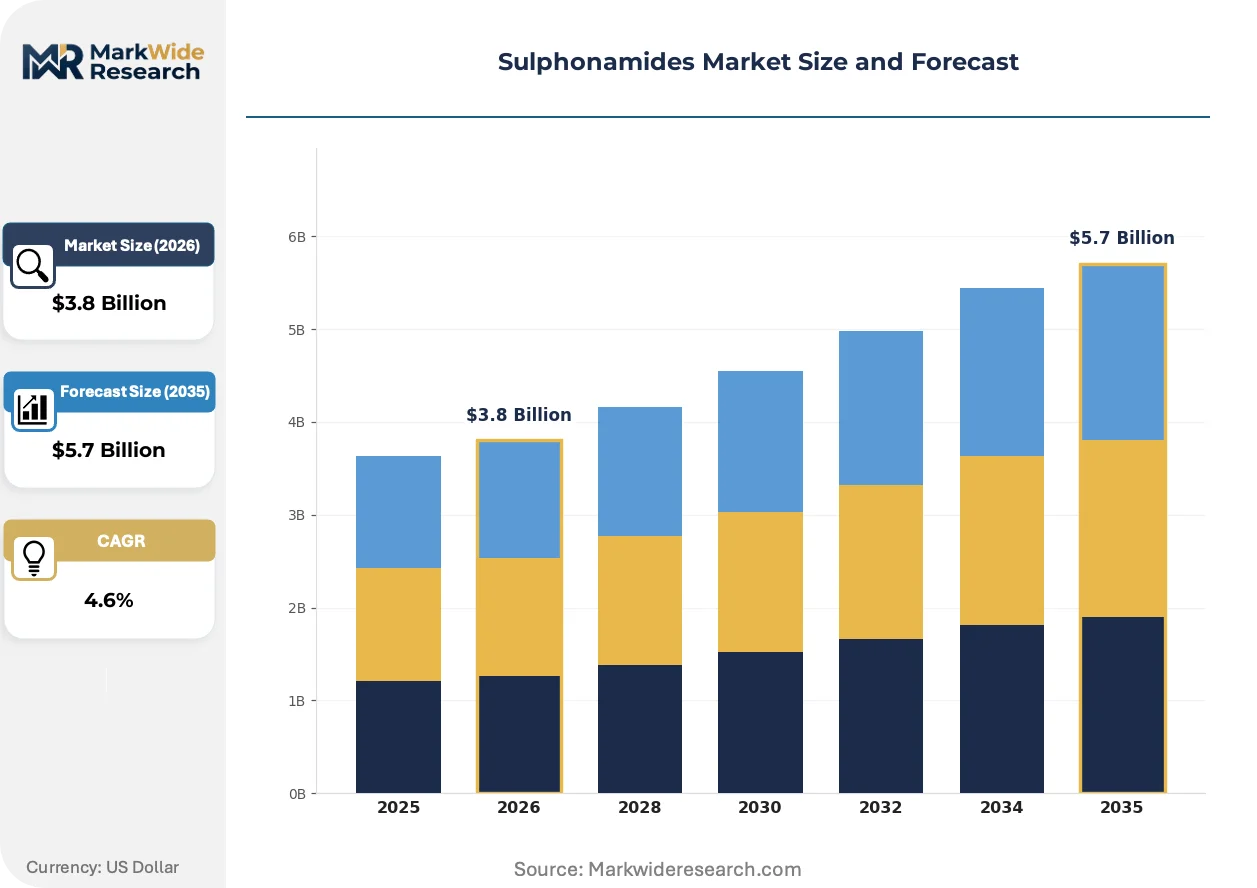
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfanilamide, Sulfadiazine, Sulfamethoxazole, Sulfaguanidine Application: Human Medicine, Veterinary Medicine, Agriculture, Laboratory Research Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Pharma Companies, Research Institutions |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd, Sandoz Group AG, Sun Pharmaceutical Industries Ltd, Aurobindo Pharma, Cipla Ltd, Dr. Reddy’s Laboratories Ltd, F. Hoffmann-La Roche Ltd, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulphonamides Market Strategic Shifts
Continuous manufacturing platforms and real-time release testing are displacing batch processing in sulphonamide API synthesis, while regulatory pressure on environmental discharge is accelerating green chemistry adoption across European and North American production sites.
Continuous flow chemistry is consolidating sulfamethoxazole API manufacturing by enabling precise temperature and pressure control during chlorosulfonation reactions. Large generic houses in India and contract manufacturers in Germany are retrofitting pilot plants with microreactor arrays to reduce solvent waste and improve yield consistency. This technology is consolidating production economics around capital-intensive continuous systems, squeezing smaller batch operators unable to fund the transition.
REACH authorization requirements for chlorosulfonic acid intermediates are forcing European formulators to document supply chain substance safety data across tier-two and tier-three suppliers. The industrial consequence is a supplier audit burden that favors vertically integrated manufacturers with in-house intermediate capability. Generic exporters sourcing Chinese chlorosulfonation output are most affected, responding by establishing captive Indian API subsidiaries or qualifying alternative Eastern European feedstock sources.
Integrated delivery networks are consolidating formulary decision-making through centralized pharmacy and therapeutics committees, displacing individual hospital purchasing autonomy. This procurement concentration is compressing vendor count per therapeutic class to two or three preferred suppliers with multi-year contract locks. The shift is most visible in United States health systems exceeding 50 hospital beds, where pharmacy benefit managers now coordinate anti-infective purchasing across statewide networks.
Sulphonamides Market Segmentation
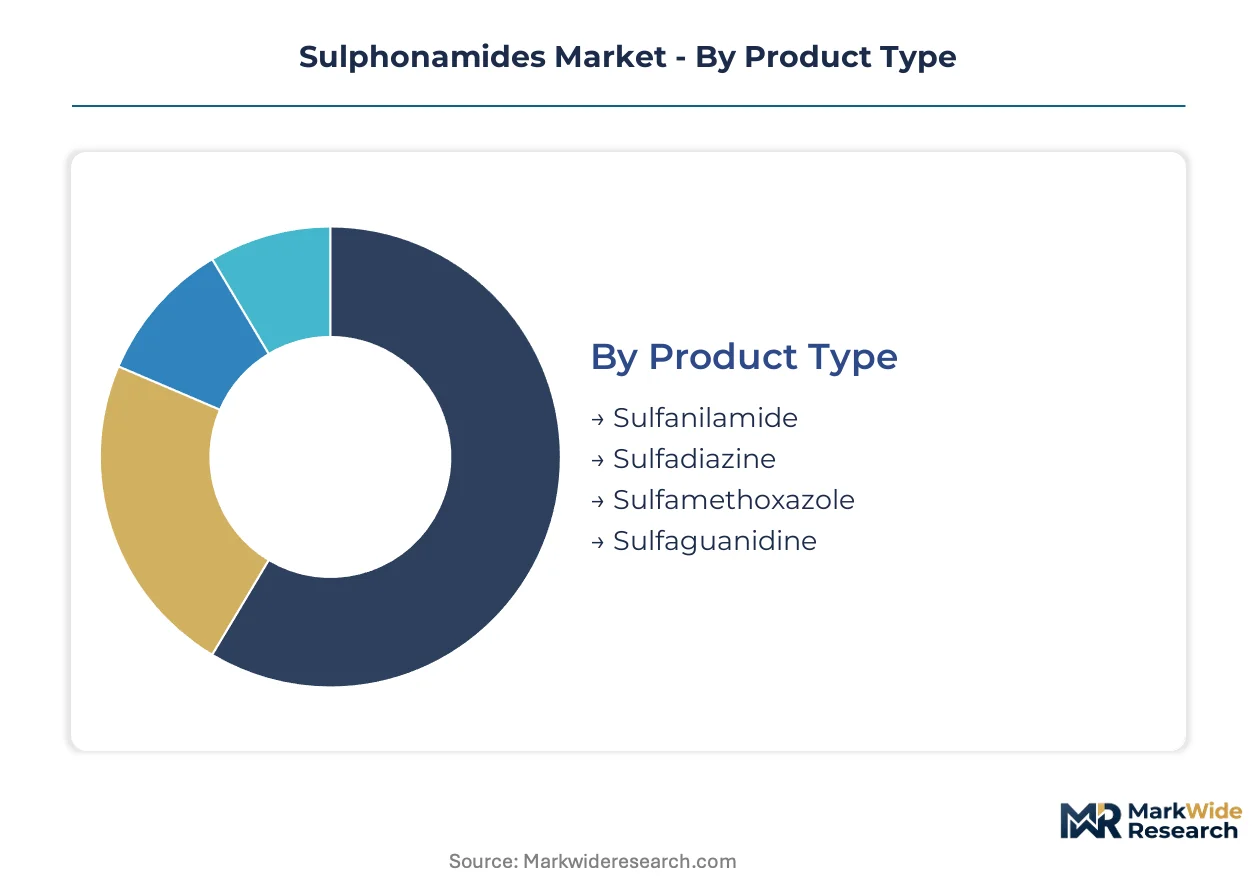
Sulphonamides demand fragments across four distinct category axes, each commanding separate procurement workflows and regulatory pathways. Product chemistry determines API sourcing strategy, while delivery mode dictates manufacturing capital intensity and margin structure.
Product Type:
Upgrade cycles in sulphonamide therapy track resistance surveillance patterns and combination therapy standardization across institutional formularies.
- Sulfamethoxazole:The dominant prescription volume driver, manufactured through chlorosulfonation of 3-amino-5-methylisoxazole and paired with trimethoprim in fixed-dose combinations. Hospital procurement networks in the United States and Germany concentrate purchasing through centralized anti-infective contracts, with formulary placement hinging on bioequivalence documentation and resistance surveillance data. The molecule anchors generic portfolio strategy for integrated delivery networks seeking single-source antibiotic stewardship compliance.
- Sulfadiazine:A short-acting agent with established cerebrospinal fluid penetration, synthesized via condensation of sulfanilyl chloride with 2-aminopyrimidine. Demand concentrates in Indian hospital networks managing toxoplasmosis prophylaxis in immunocompromised patients, where cost-engineered supply from domestic API manufacturers displaces imported alternatives. The segment faces narrowing empirical prescribing windows as resistance tracking protocols tighten.
- Sulfanilamide:The foundational sulphonamide scaffold, now largely supplanted by derivatives in systemic therapy but retained in topical and veterinary applications.
- Sulfaguanidine:A poorly absorbed intestinal antiseptic, confined to veterinary enteric infections and select agricultural prophylaxis programs.
Volume placements concentrate in Sulfamethoxazole; the faster expansion belongs to Sulfadiazine.
Application:
Cost tier segmentation separates mass-market generic supply from premium-positioned specialty formulations requiring dedicated manufacturing containment.
- Human Medicine:Systemic anti-infective therapy dominates, spanning uncomplicated urinary tract infections, prophylaxis in immunocompromised patients, and combination regimens for resistant organisms. FDA antimicrobial stewardship guidelines and EMA environmental risk assessments are reshaping prescribing protocols and manufacturing location decisions simultaneously. Hospital pharmacy committees now demand resistance surveillance integration with formulary placement.
- Veterinary Medicine:Growth concentrates in livestock prophylaxis and companion animal therapeutics, particularly in Brazil and India's poultry production corridors. Regulatory divergence between FDA veterinary feed directive requirements and EU ban on growth-promoting antibiotic use is fragmenting product registration pathways and forcing geographic market specialization.
- Agriculture:Confined to aquaculture and specialty crop applications with tightening residue monitoring requirements.
- Laboratory Research:Niche demand for cell culture selection markers and enzymatic inhibition studies, sourced through specialized chemical distributors.
Human Medicine captures the dominant value share; Veterinary Medicine climbs the fastest as protein demand escalates in emerging economies.
Delivery Mode:
Patient access patterns and acute care requirements split manufacturing investment between high-volume oral solid dose and capital-intensive sterile injectable capacity.
- Oral:Tablets and suspensions command the largest patient-access footprint across outpatient settings, with sulfamethoxazole-trimethoprim fixed-dose combinations standardized in WHO essential medicines lists. Indian generic houses leverage cost-engineered API supply to dominate procurement in donor-funded health programs across sub-Saharan Africa. The segment faces margin compression as hospital procurement consolidation squeezes vendor pricing.
- Injectable:Intravenous and intramuscular formulations command premium positioning in sepsis, surgical prophylaxis, and nosocomial infections where rapid therapeutic levels prove critical. Manufacturing requires current good manufacturing practice containment investments and dedicated sterile filling lines, limiting supplier count to vertically integrated API-formulator operations. FDA abbreviated new drug application backlogs are extending time-to-market for generic entrants.
- Topical:Silver sulfadiazine burn creams and ophthalmic solutions serve specialized dermatology and trauma center networks.
- Intravenous:A subset of injectable delivery with distinct stability and compatibility requirements for ICU infusion protocols.
Oral formulations anchor volume economics; Injectable delivery gains share fastest as hospital-acquired infection protocols tighten.
End User:
Customer concentration and procurement sophistication determine contract structure, with integrated delivery networks extracting volume guarantees in exchange for formulary exclusivity.
- Hospitals:Centralized pharmacy and therapeutics committees across United States health systems exceeding 50 beds now coordinate anti-infective purchasing through pharmacy benefit managers. Formulary decisions hinge on antimicrobial stewardship compliance, resistance surveillance integration, and multi-year price protection. Teva Pharmaceutical Industries and Pfizer anchor preferred vendor status through legacy contract relationships and broad portfolio breadth.
- Clinics:Outpatient prescribing concentrates in uncomplicated infections, with physician preference shifting toward rapid symptom resolution alternatives where formulary permissiveness allows.
- Pharma Companies:API procurement for combination product development and contract manufacturing organization tolling arrangements, with Indian bulk drug park incentives attracting sulfamethoxazole intermediate investment.
- Research Institutions:Specialized chemical procurement for microbiology and pharmacology studies, sourced through academic distributors with material safety data sheet documentation requirements.
Hospitals consolidate procurement volume; Research Institutions expand fastest as resistance mechanism studies intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement networks in the United States and Germany concentrate purchasing power through centralized formulary committees, while India's bulk drug park incentives attract sulfamethoxazole API investment from global generic houses.
United States
Integrated delivery networks exceeding 50 hospital beds now coordinate anti-infective purchasing through pharmacy benefit managers, with formulary decisions hinging on FDA antimicrobial stewardship compliance. The FDA's tightened prescribing guidelines sustain demand for established sulphonamide therapies with documented resistance profiles. New Jersey and Pennsylvania host concentrated manufacturing of sterile injectable formulations serving sepsis protocols.
Germany
EMA environmental risk assessments for API discharge are reshaping manufacturing location decisions among European formulators sourcing Chinese intermediates. REACH authorization requirements for chlorosulfonic acid intermediates force documentation of supply chain substance safety data across tier-two and tier-three suppliers. Bavaria's chemical manufacturing corridor sees retrofitting of batch reactor systems to meet current good manufacturing practice containment standards.
India
CDSCO-backed bulk drug park incentives in Gujarat and Telangana attract sulfamethoxazole API investment through subsidized land and duty exemptions on imported intermediates. Domestic API manufacturers displace imported alternatives in cost-sensitive institutional channels. Maharashtra's generic formulation clusters expand direct-to-pharmacy distribution bypassing wholesale intermediaries.
China
Chinese intermediate manufacturers control the majority of chlorosulfonation feedstock, exposing formulators to single-source disruption risk during environmental compliance crackdowns under MEE oversight. Zhejiang and Jiangsu provinces concentrate SO₂NH₂ functional group synthesis capacity. NMPA registration pathways for generic sulfamethoxazole-trimethoprim face bioequivalence study backlogs extending time-to-market.
Brazil
Veterinary medicine demand concentrates in livestock prophylaxis and companion animal therapeutics, particularly in São Paulo and Paraná poultry production corridors. ANVISA regulatory divergence from FDA veterinary feed directive requirements fragments product registration pathways. Local formulators specialize in geographic market adaptation for growth-promoting antibiotic applications.
Sulphonamides Market Competitive Environment
Indian producers anchor one tier through cost-engineered API supply and bulk drug park incentives; European and North American specialists hold formulary positioning through legacy brand recognition and antimicrobial stewardship compliance. The vendor base splits between vertically integrated API-formulator operations and toll manufacturers dependent on external chlorosulfonation feedstock. Three archetypes dominate: scale-driven generic houses with captive Indian subsidiaries, heritage pharmaceutical companies with hospital trust relationships, and mid-tier regional formulators serving price-sensitive institutional channels. Competitive moves concentrate on backward integration into intermediate manufacturing and multi-year contract locks with consolidated procurement networks.
Within the heritage pharmaceutical tier, Pfizer Inc. and F. Hoffmann-La Roche Ltd exemplify companies whose institutional presence rests on decades of anti-infective therapy deployment. Among scale-driven generic specialists, Teva Pharmaceutical Industries Ltd and Sun Pharmaceutical Industries Ltd occupy positions shaped by portfolio breadth and Indian manufacturing footprint respectively. Dr. Reddy's Laboratories Ltd represents the mid-tier regional archetype with concentrated API-formulator integration in domestic bulk drug corridors.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd |
| Sandoz Group AG |
| Sun Pharmaceutical Industries Ltd |
| Aurobindo Pharma |
| Cipla Ltd |
| Dr. Reddy's Laboratories Ltd |
| F. Hoffmann-La Roche Ltd |
| GSK plc |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks exceeding 50 hospital beds now coordinate anti-infective purchasing through pharmacy benefit managers, compressing vendor margins and forcing a contract-based long-term offtake model with multi-year price protection clauses. This buyer concentration enables formulary exclusivity in exchange for volume guarantees, squeezing smaller batch operators unable to fund continuous manufacturing transitions.
Pricing Analysis
High-volume oral sulfamethoxazole-trimethoprim combinations run on thin margins anchored by Indian API supply, while sterile injectable formulations command premium positioning through FDA bioequivalence certification and dedicated sterile filling infrastructure. Price differentiation hinges on GMP containment grade and antimicrobial stewardship compliance documentation, with hospital pharmacy committees demanding resistance surveillance integration as a non-negotiable entry ticket. Cost compression in the oral generic tier is intensifying as procurement consolidation extracts volume discounts from Teva and Sun Pharmaceutical. Price-sensitive institutional channels in India and sub-Saharan Africa favor cost-engineered supply from domestic API manufacturers, whereas United States health systems prioritize formulary security over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled sterile injectables is reshaping regional manufacturing footprints, with New Jersey and Pennsylvania facilities serving sepsis protocols across eastern United States health systems. API synthesis concentrates in India and China, with Gujarat and Telangana bulk drug parks attracting sulfamethoxazole investment through CDSCO incentives while Zhejiang and Jiangsu provinces control chlorosulfonation feedstock. Raw material dependencies rest on chlorosulfonic acid intermediates, 3-amino-5-methylisoxazole, and sulfanilyl chloride, exposing formulators to single-source vulnerability during MEE environmental compliance crackdowns. Distribution runs through pharmacy benefit managers coordinating statewide networks, bypassing traditional wholesale intermediaries in fragmented retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated API-formulator operations as hospital procurement networks compress vendor counts to two or three preferred suppliers per therapeutic class. Weaker batch-reactor operators without continuous manufacturing capability face forced exit as capital requirements escalate.
For Market Incumbents: Extend formulary lock-in through multi-year antimicrobial stewardship compliance contracts with integrated delivery networks, embedding resistance surveillance data sharing as a switching cost. Deepen upstream control over chlorosulfonation intermediates via captive Indian API subsidiaries to insulate against Chinese environmental compliance disruptions. Prioritize green chemistry certifications for European REACH authorization as a competitive moat against generic exporters sourcing Chinese feedstock.
For New Entrants and Emerging Players: Capture white-space in topical dermatology expansion across Middle Eastern trauma center networks where silver sulfadiazine demand outpaces established supply relationships. Target direct-to-pharmacy distribution in Maharashtra's fragmented retail sector, bypassing wholesale intermediaries to capture margin compression from consolidated hospital procurement. Lead with EMA environmental risk assessment pre-clearance as a differentiated entry credential for European formulation contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier regional formulators with existing API-formulator integration in Indian bulk drug corridors, where CDSCO incentives and subsidized land reduce capital intensity for capacity expansion. Long-term viability hinges on backward integration into chlorosulfonation expertise as retiring chemical engineering talent creates capability scarcity. Watch FDA abbreviated new drug application queue clearance rates as the inflection signal for generic sulfamethoxazole-trimethoprim time-to-market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosulfonation | Insulates formulators from Chinese intermediate disruption risk under MEE oversight. |
| Continuous Manufacturing Retrofit | Enables precise temperature control during SO₂NH₂ synthesis, reducing solvent waste. |
| Green Chemistry Certification | Unlocks first-mover advantage for European manufacturers under tightened REACH authorization. |
| Direct-to-Pharmacy Distribution | Bypasses wholesale intermediaries in India's fragmented retail pharmacy sector. |
| Antimicrobial Stewardship Partnership | Secures formulary placement through FDA-compliant resistance surveillance integration. |
Study Parameters
Independent corroboration across hospital formulary directors, API plant managers in Gujarat and Telangana, regulatory affairs leads at EMA and FDA, and procurement officers at United States pharmacy benefit managers underwrites the qualitative findings. Secondary validation draws from FDA abbreviated new drug application filings, EMA environmental risk assessment submissions, CDSCO bulk drug park incentive documentation, and customs data tracking chlorosulfonic acid intermediate trade flows. Bottom-up patient-volume modeling across outpatient and inpatient settings triangulates against top-down pharmaceutical expenditure audits from hospital procurement databases.
Rate-of-change decomposition separates volume expansion from price erosion dynamics across the analysis window, with segmentation modeling spanning product chemistry, delivery mode, application vertical, and end-user procurement sophistication. CAGRs derive from iterative reconciliation of API capacity buildout timelines, formulary placement probability weighted by antimicrobial stewardship compliance status, and substitution elasticity estimates for fluoroquinolone and cephalosporin competitors. Forecast inputs incorporate chlorosulfonation feedstock availability scenarios under Chinese environmental enforcement regimes and FDA bioequivalence study backlog clearance assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between FDA and WHO prequalification requirements, Chinese intermediate supply disruption under MEE crackdowns, and chlorosulfonation expertise scarcity as specialized chemical engineering talent retires. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market