
 Calcium Citrate Market | 2026-2036
Calcium Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Citrate Market Analysis
Software-defined formulation services is pivoting how calcium citrate suppliers monetize their portfolios, shifting value from bulk powder transactions to certified premix subscriptions. Jungbunzlauer leverages its Swiss fermentation heritage to dominate pharmaceutical-grade citrate production. Gadot Biochemical Industries Ltd anchors Israel's specialized mineral salt exports through vertical integration from Dead Sea brine extraction. Dr. Paul Lohmann GmbH KG differentiates via custom chelation technologies for infant nutrition and clinical applications.
Calcium citrate, the calcium salt of citric acid with the molecular formula Ca₃(C₆H₅O₇)₂, delivers 21% elemental calcium by weight and achieves superior bioavailability in gastric environments independent of food intake, driving its preference over carbonate in proton pump inhibitor users and elderly populations. Tablets and capsules lead volume due to established compliance patterns among retail consumers, while powder formats capture margin pools through bulk supply contracts with nutraceutical companies seeking in-house encapsulation flexibility. Single-ingredient formulations remain mature in drug store channels, whereas multi-vitamin and functional food applications accelerate through health food stores and online retail expansion.
The US FDA enforces Current Good Manufacturing Practice regulations for dietary supplements under 21 CFR Part 111, compelling calcium citrate producers to maintain batch records and contaminant testing protocols that raise compliance costs but protect market access. EFSA in Europe evaluates health claims under Regulation 1924/2006, restricting promotional language around bone density unless substantiated by human intervention studies. India's FSSAI mandates BIS certification for imported mineral premixes, creating procedural barriers for non-domestic suppliers. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional fortification mandates to anticipate specification shifts before contract renegotiations.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating production among fermentation-capable manufacturers with dedicated USP-grade facilities.
Growth Catalysts
- Proton pump inhibitor co-prescription protocols:Gastric acid-independent absorption properties position calcium citrate as the preferred calcium source for acid-suppression therapy patients, expanding hospital formulary inclusion.
- EFSA bone health claim substantiation pathways:Approved health claims under Regulation 1924/2006 enable direct-to-consumer marketing of clinically validated bone density benefits.
- Geriatric nutrition fortification mandates:National dietary guidelines across developed economies now specify bioavailable calcium formats for populations over 65.
Market Restraints
- Citric acid feedstock volatility:Fermentation-derived citric acid supply fluctuates with Brazilian sugarcane harvest cycles and energy input costs.
- Rhine-Ruhr production cluster concentration:Over 40% of European pharmaceutical-grade capacity sits within 200 kilometers of Jungbunzlauer's Ladenburg facility.
- Calcium carbonate substitution pressure:Lower-cost carbonate formats retain dominance in non-clinical applications where gastric acid presence is assumed.
Strategic Opportunities
- Infant formula mineral premix contracts:Custom chelation specifications for hypoallergenic pediatric nutrition create multi-year supply agreements with tier-one dairy processors.
- Direct-to-practitioner distribution channels:Functional medicine clinics and integrative health networks bypass retail markup structures for bulk therapeutic dosing.
- FSSAI import certification arbitrage:Early BIS compliance investment unlocks preferential access to India's expanding nutraceutical manufacturing base.
Industry Challenges
- USP-NF monograph revision tracking:Quarterly pharmacopeial updates require continuous analytical method validation and certificate of analysis reissuance.
- Cross-contamination prevention infrastructure:Dedicated production lines for allergen-free infant nutrition grades demand capital-intensive facility segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Citrate Market |
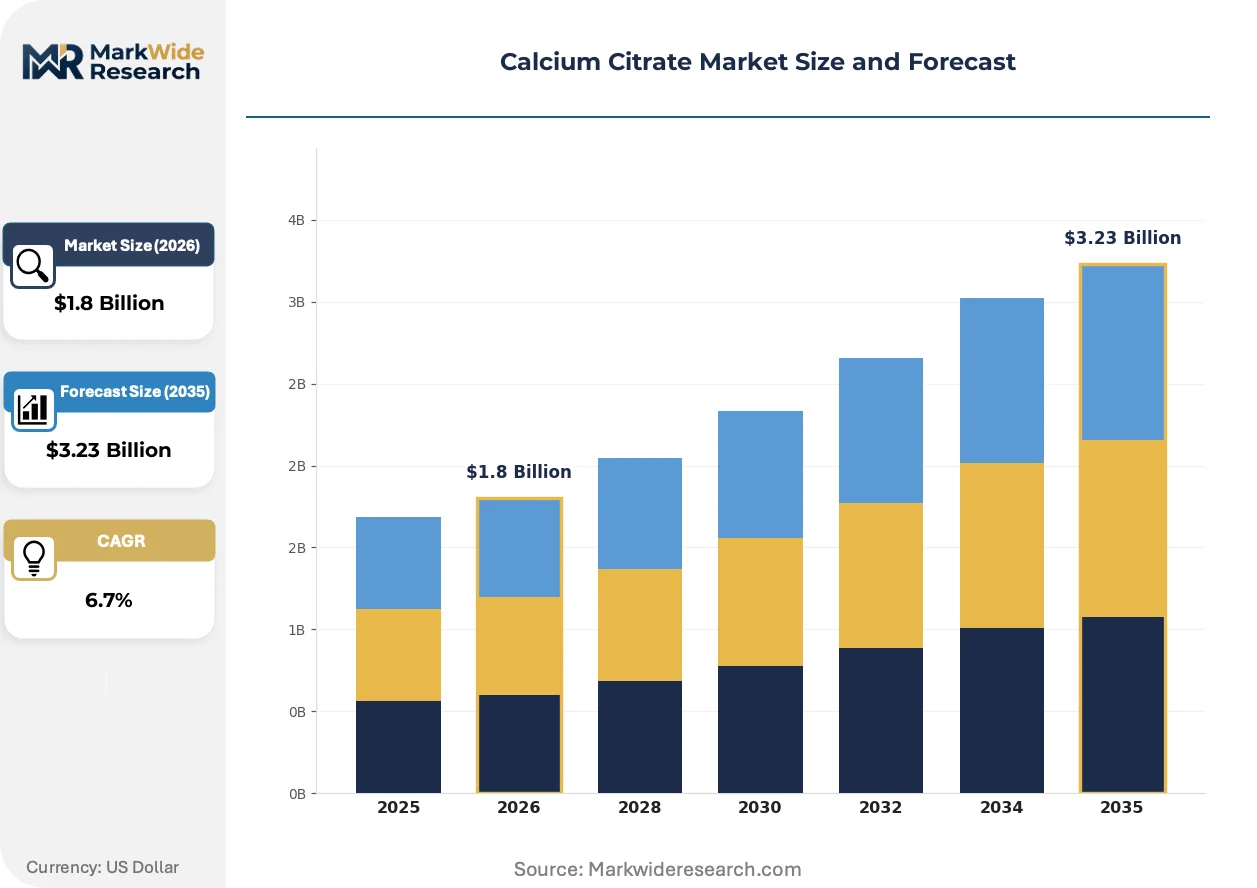
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powder, Liquid Formulation Type: Single Ingredient, Multi-Vitamin, Functional Food, Dietary Supplement End User: Retail Consumers, Healthcare Providers, Nutraceutical Companies, Sport Nutrition Distribution Channel: Online Retail, Drug Stores, Supermarkets, Health Food Stores |
| Companies Covered | Jungbunzlauer, Jost Chemical, Gadot Biochemical Industries Ltd, Dr. Paul Lohmann GmbH KG, Sucroal SA, RZBC GROUP, Adani Pharmachem Private Limited, Aditya Chemicals Limited, Balchem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Citrate Market Emerging Trajectories
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times while reshaping quality assurance economics for mineral salt producers.
Direct compression-grade calcium citrate with optimized particle size distribution is rewriting tablet formulation economics. Nutraceutical contract manufacturers are adopting this material to eliminate wet granulation steps, cutting production time by half. The technology is compressing capital requirements for mid-scale entrants while eroding the advantage of legacy wet-processing specialists.
REACH Annex XVII restrictions on residual solvents and heavy metal impurities are tightening specification windows for citrate salts entering European cosmetic and pharmaceutical applications. Manufacturers must now demonstrate sub-ppm contaminant levels through validated ICP-MS protocols. German and Swiss suppliers with in-house analytical capabilities are capturing specification-premium contracts while importers face rejection rates at Rotterdam customs.
Subscription-based premix procurement is displacing spot-market mineral purchasing among mid-sized nutraceutical brands. Health food store chains and direct-to-consumer supplement brands now contract for 12-month certified supply with quarterly adjustment clauses. This pattern is most visible in North American and Australian markets where inventory carrying costs and certificate freshness requirements outweigh bulk discount incentives.
Calcium Citrate Market Segmentation
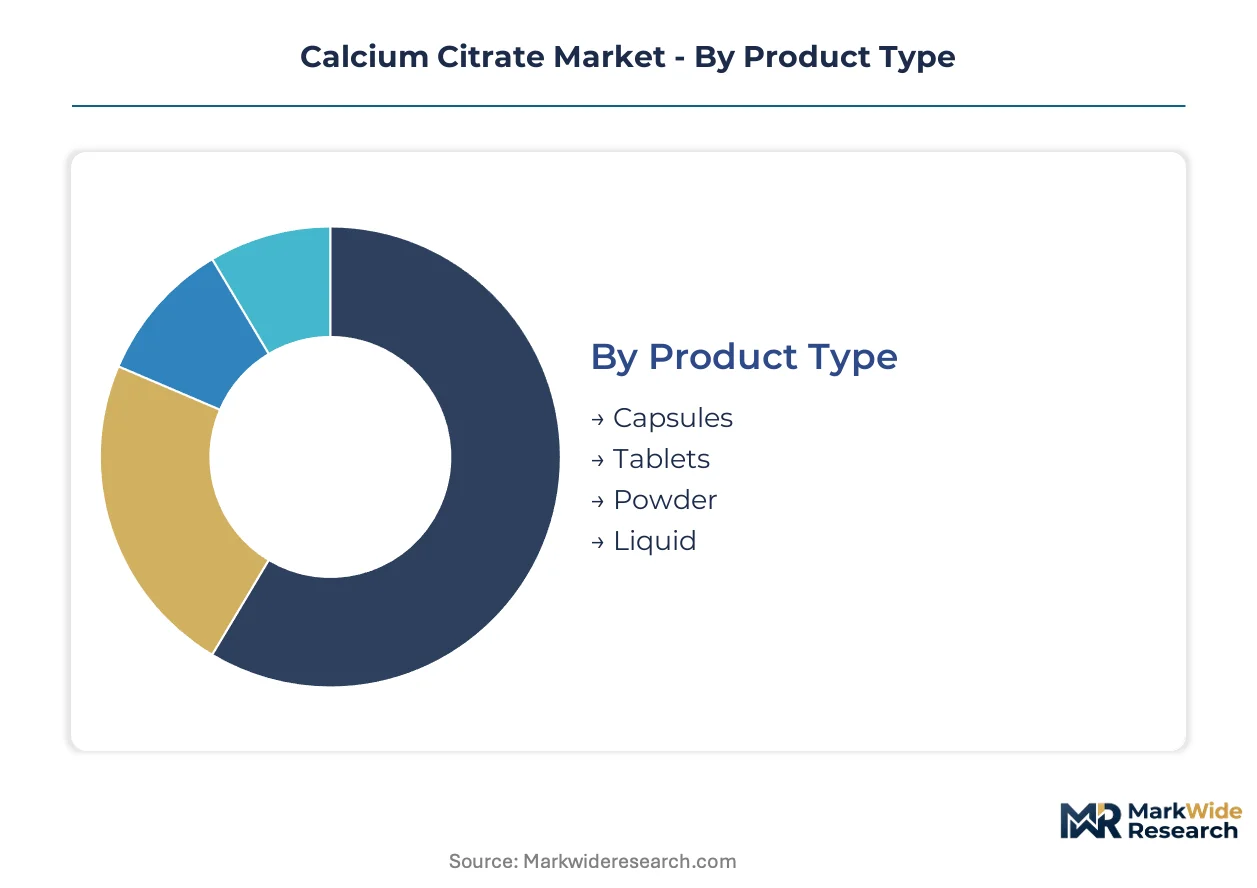
Calcium citrate suppliers configure production assets around formulation complexity and certification grade rather than commodity volume. Segmentation discipline separates pharmaceutical-grade contracts from mass-market dietary supplement supply, with pricing spreads reflecting analytical validation burdens.
Product Type:
Particle engineering specifications determine compression behavior and dissolution profiles across oral delivery formats.
- Tablets:Direct compression-grade material with optimized particle size distribution eliminates wet granulation steps for contract manufacturers. Demand concentrates among retail consumers in drug store channels where established compliance patterns favor familiar unit-dose formats.
- Powder:Bulk supply contracts with nutraceutical companies seeking in-house encapsulation flexibility capture margin pools through volume scale. This segment gains share fastest among mid-sized brands building certified premix capabilities.
- Capsules:Hard gelatin and vegetarian shell formats serve proton pump inhibitor users requiring gastric acid-independent absorption without tablet disintegration variables.
- Liquid:Pediatric and geriatric applications favor suspension formats for populations with dysphagia or dose-titration needs.
Mature deployment sits with Tablets. Newer deployment is concentrated in Powder.
Formulation Type:
Regulatory claim substantiation requirements stratify value capture across single-ingredient versus multi-component positioning.
- Single Ingredient:Drug store channels dominate volume for standalone calcium citrate with USP-grade certification. EFSA bone health claim substantiation under Regulation 1924/2006 enables direct-to-consumer marketing of clinically validated benefits in European markets.
- Multi-Vitamin:Mineral premix contracts with tier-one dairy processors for infant nutrition create multi-year supply agreements with custom chelation specifications.
- Functional Food:Beverage fortification and bakery applications require modified particle surface properties to prevent grittiness and mineral off-notes.
- Dietary Supplement:Subscription-based premix procurement is displacing spot-market purchasing among health food store chains and direct-to-consumer brands.
Revenue concentration favors Single Ingredient. Steepest expansion trajectory appears in Multi-Vitamin.
End User:
Prescription protocols versus self-directed supplementation create divergent specification and certification requirements.
- Healthcare Providers:Hospital formulary inclusion for acid-suppression therapy patients drives pharmaceutical-grade demand with batch record documentation.
- Nutraceutical Companies:In-house encapsulation and tablet manufacturing operations source bulk powder for flexible formulation pipelines.
- Retail Consumers:Established compliance patterns favor familiar tablet and capsule formats in drug store and supermarket channels.
- Sport Nutrition:Functional medicine clinics and integrative health networks bypass retail markup structures for bulk therapeutic dosing.
Volume leadership rests with Retail Consumers. Emerging specification intensity concentrates in Healthcare Providers.
Distribution Channel:
Certificate freshness requirements and inventory carrying costs reshape procurement patterns across physical and digital retail.
- Online Retail:Direct-to-consumer supplement brands contract for certified supply with quarterly adjustment clauses, favoring subscription economics over bulk discount incentives.
- Drug Stores:Single-ingredient formulations remain mature in this channel with established consumer recognition and pharmacist recommendation protocols.
- Health Food Stores:Multi-vitamin and functional food applications accelerate through specialist retail with trained staff capable of explaining bioavailability advantages.
- Supermarkets:Mass-market positioning competes primarily on unit price with calcium carbonate substitution pressure strongest in this channel.
Established penetration dominates Drug Stores. Channel shift momentum concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Germany and Israel while consumption spreads across aging populations in developed economies. Pharmaceutical-grade certification requirements favor established fermentation facilities over new market entrants. Regional regulatory divergence shapes specification standards and procurement patterns.
Germany
Hospital formulary expansion for acid-suppression therapy patients drives pharmaceutical-grade demand. EFSA health claim substantiation under Regulation 1924/2006 enables direct bone density marketing to consumers. The Rhine-Ruhr corridor hosts Jungbunzlauer's Ladenburg facility and Dr. Paul Lohmann GmbH KG operations, anchoring over 40% of European USP-grade capacity within 200 kilometers.
United States
Proton pump inhibitor co-prescription protocols expand calcium citrate inclusion in hospital formularies. FDA enforces Current Good Manufacturing Practice regulations under 21 CFR Part 111, compelling batch record documentation and contaminant testing. Direct-to-practitioner distribution channels through functional medicine clinics bypass retail markup structures for therapeutic dosing.
India
Expanding nutraceutical manufacturing base seeks certified mineral premix imports for domestic formulation. FSSAI mandates BIS certification for imported mineral premixes, creating procedural barriers for non-domestic suppliers. Early compliance investment unlocks preferential access to contract manufacturers in Maharashtra and Gujarat pharmaceutical zones.
Israel
Specialized mineral salt exports leverage Dead Sea brine extraction for vertical integration advantages. The national pharmaceutical regulator maintains alignment with USP-NF monograph standards for export market access. Gadot Biochemical Industries Ltd anchors production clusters serving European and North American pharmaceutical customers.
China
Domestic dietary supplement brands accelerate certified premix procurement through subscription contracts. NMPA oversight of health food registration creates compliance pathways for imported mineral ingredients. RZBC GROUP and regional fermentation specialists supply carbonate-competing citrate formats for mass-market positioning.
Calcium Citrate Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across certification tiers. Fermentation-capable manufacturers with dedicated USP-grade facilities capture pharmaceutical contracts while commodity traders serve mass-market dietary supplement channels. Three archetypes dominate: integrated brine-to-citrate operators, custom chelation specialists, and regional fermentation-scale suppliers. Competitive moves center on pharmacopeial certification acquisition and infant nutrition grade facility segregation.
Within the integrated mineral salt tier, Gadot Biochemical Industries Ltd exemplifies backward integration from Dead Sea resource extraction. Among German custom chelation specialists, Dr. Paul Lohmann GmbH KG occupies a position serving pediatric and clinical applications. At the fermentation-scale end, Jungbunzlauer anchors pharmaceutical-grade citrate production leveraging Swiss heritage technical capabilities.
| Leading Market Players |
|---|
| Jungbunzlauer |
| Jost Chemical |
| Gadot Biochemical Industries Ltd |
| Dr. Paul Lohmann GmbH KG |
| Sucroal SA |
| RZBC GROUP |
| Adani Pharmachem Private Limited |
| Aditya Chemicals Limited |
| Balchem Corporation |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII restrictions on residual solvents and heavy metal impurities gate qualified supply for European cosmetic and pharmaceutical applications, compressing the supplier base capable of commanding premium-tier pricing while forcing importers toward Rotterdam customs rejection.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects USP-NF monograph revision tracking costs and dedicated allergen-free production line investments. Three-tier pricing structure across pharmaceutical, food-grade, and technical citrate levels separates certified premix subscriptions from spot-market bulk transactions. Cost-down pressure on mass-market dietary supplement grades accelerates because calcium carbonate substitution retains dominance in non-clinical channels. Retail consumers through supermarket channels exhibit highest price sensitivity; hospital formulary buyers demonstrate lowest sensitivity due to co-prescription protocol requirements.
Supply Chain Analysis
Skilled fermentation technicians and analytical chemists concentrate in Germany's Rhine-Ruhr corridor and Switzerland's Basel region, constraining capacity expansion for USP-grade citrate production. Manufacturing gravity centers on Germany, Israel, and China, with raw material dependencies spanning Brazilian sugarcane-derived citric acid, Dead Sea brine mineral extraction, and energy inputs for fermentation scale-up. Single-source vulnerability concentrates in Jungbunzlauer's Ladenburg facility anchoring over 40% of European pharmaceutical-grade capacity. Distribution runs through certified premix suppliers serving nutraceutical contract manufacturers and direct-to-practitioner channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-capable USP-grade facility scarcity props pricing power for qualified suppliers, creating a supply-constrained market structure favoring incumbents with dedicated analytical capabilities and pharmacopeial certification depth.
For Market Incumbents: Cement pharmaceutical-grade certification moats through continuous manufacturing platform investments that compress batch cycle times while raising rival capital requirements. Defend against commodity carbonate substitution by expanding infant nutrition grade facility segregation for multi-year dairy processor contracts. Prioritize backward integration into citric acid feedstock through long-term Brazilian sugarcane processor agreements. For New Entrants and Emerging Players: Direct-to-practitioner distribution channels offer the most penetrable white-space target, bypassing retail markup structures where Jungbunzlauer and Dr. Paul Lohmann GmbH KG hold entrenched positions. India's FSSAI BIS certification arbitrage presents secondary entry opportunity through early compliance investment unlocking Maharashtra and Gujarat pharmaceutical zone access. Lead with subscription-based premix procurement models displacing spot-market purchasing among mid-sized North American nutraceutical brands. For Investors and Strategic Acquirers: US FDA 21 CFR Part 111 enforcement actions against non-compliant dietary supplement facilities are the leading indicator that pharmaceutical-grade certification depth will command acquisition premiums over commodity-scale capacity. Long-term viability frames around fermentation technical capabilities and pharmacopeial relationship depth rather than volume scale. Target acquisition archetype: custom chelation specialists with infant nutrition grade facilities and established dairy processor relationships. Watch EFSA bone health claim substantiation pathway expansion as signal for European direct-to-consumer marketing premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| USP-Grade Facility Certification | FDA 21 CFR Part 111 compliance unlocks hospital formulary inclusion for acid-suppression therapy protocols. |
| Backward Integration into Feedstock | Long-term Brazilian sugarcane agreements hedge citric acid volatility from harvest cycle fluctuations. |
| Infant Nutrition Grade Segregation | Allergen-free production lines capture multi-year premix contracts with tier-one dairy processors. |
| Continuous Manufacturing Transition | Real-time release testing platforms compress batch cycle times while reshaping quality assurance economics. |
| FSSAI BIS Compliance Investment | Early certification unlocks preferential access to India's expanding Maharashtra and Gujarat pharmaceutical zones. |
Methodological Framework
Document review covered US FDA 21 CFR Part 111 guidance documents, EFSA Regulation 1924/2006 health claim registers, and USP-NF monograph revisions, complemented by interviews with fermentation plant managers, nutraceutical procurement leads, hospital formulary directors, and infant nutrition R&D directors. Secondary validation drew from customs/trade data, SEC 10-K filings of listed mineral salt producers, and pharmacopeial update notifications. Bottom-up volume triangulation across product type, formulation complexity, and certification grade segments converged with top-down market sizing from production capacity assessments.
Segment-level outputs across the projection horizon reflect granular modeling of pharmaceutical-grade versus food-grade versus technical citrate tiers, oral delivery format preferences, and regional regulatory cluster divergence. CAGRs were derived from elasticity-adjusted demand curves incorporating proton pump inhibitor prescription trends, geriatric nutrition fortification mandate adoption, and infant formula mineral premix contract velocity. Industry-specific inputs included Brazilian sugarcane harvest cycle patterns and quarterly pharmacopeial monograph revision frequencies.
The model holds under stable REACH Annex XVII enforcement intensity and USP-NF revision cadence; deviation in EFSA bone health claim expansion pace or FSSAI import certification stringency would shift volume trajectories. Forecasts reflect documented assumptions around fermentation capacity expansion timelines and carbonate substitution elasticity in mass-market channels. A small set of named triggers—citric acid feedstock volatility, pharmacopeial specification tightening, and regional fortification mandate adoption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharma Grade Synthetic Camphor Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Global Glycine Supplement Market