
 France Active Pharmaceutical Ingredients (API) Market | 2026-2036
France Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
France Active Pharmaceutical Ingredients (API) Market Foresight
Continuous bioprocessing is rewriting how France-based API manufacturers scale mammalian cell cultures for monoclonal antibodies. Sanofi leverages its Lyon biologics hub to sustain end-to-end fermentation capacity. Merck KGaA anchors high-purity excipient supply chains serving Paris-Saclay biotech startups. Boehringer Ingelheim differentiates through enzymatic catalysis platforms that slash solvent waste at its Strasbourg site.
Active pharmaceutical ingredients are the pharmacologically active substances in drug products, synthesized through chemical routes or biotechnological methods including recombinant DNA fermentation and cell culture, with purity typically exceeding 99.5% and stringent impurity profiling under ICH Q3A/Q3B guidelines. Antibiotics and peptides command mature volume bases but face margin compression from Indian and Chinese generic competition, while oncology and immunology APIs attract premium pricing due to complex synthesis pathways and orphan drug exclusivity. Hormone APIs occupy a specialized niche where biosimilar entry remains constrained by immunogenicity validation requirements.
ANSM enforces GMP inspections aligned with EMA directives and ICH Q7 guidelines, while REACH compliance governs solvent discharge from API synthesis facilities. The EU Green Deal pushes manufacturers toward enzymatic biocatalysis and continuous flow chemistry to replace batch organic synthesis. Stakeholders must monitor how France's national pharmaceutical sovereignty strategy reshapes local production incentives versus import dependency for high-potency APIs.
Market Dynamics
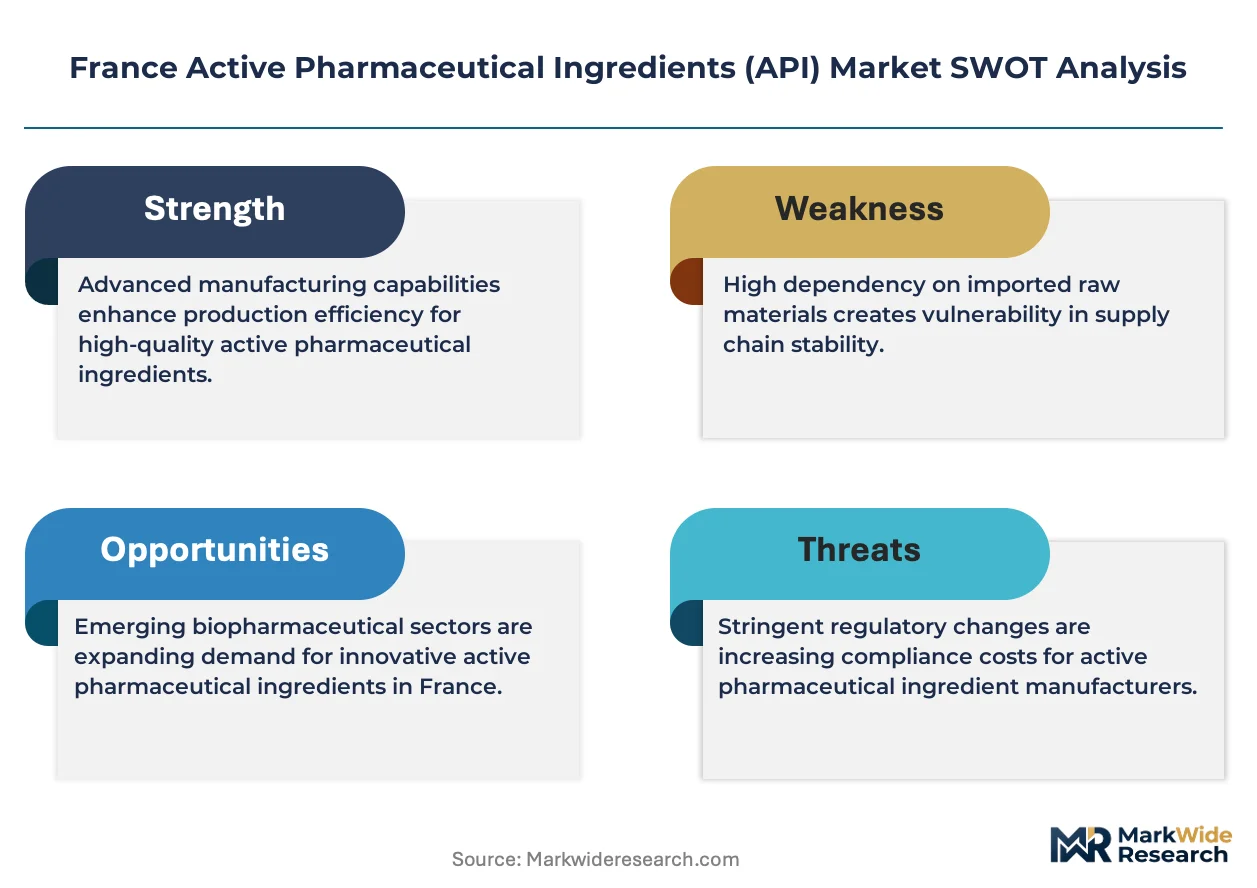
France's API sector faces a structural squeeze between biologics manufacturing complexity and ANSM's tightening GMP enforcement, forcing domestic producers to choose between capital-intensive upgrades and contract manufacturing exits.
Growth Catalysts
- Biologics manufacturing expansion:Monoclonal antibody demand from Île-de-France oncology clusters pulls investment into mammalian cell culture capacity.
- EU Green Deal biocatalysis mandates:REACH solvent discharge limits accelerate enzymatic platform adoption across Rhône-Alpes synthesis facilities.
- ANSM GMP harmonization:EMA-aligned inspection protocols create competitive moats for French producers against non-EU generic imports.
Market Restraints
- Indian and Chinese API import concentration:Generic antibiotic and peptide feedstock dependence exposes margin compression risks from Asian cost structures.
- High-potency API containment capex:Isolation technology and dedicated HVAC systems for cytotoxic compounds demand eight-figure facility investments.
- EMA centralized approval timelines:Novel API marketing authorization procedures extend commercialization cycles beyond three years.
Strategic Opportunities
- CDMO service bundling:Integrated drug-substance-to-drug-product offerings capture biotech outsourcing from Paris-Saclay incubators.
- Continuous flow chemistry retrofitting:Batch-to-continuous conversion at legacy Strasbourg sites reduces solvent inventory and batch failure rates.
- Orphan drug API niche:Small-volume, high-complexity synthesis for rare disease indications commands pricing premiums with limited biosimilar threat.
Industry Challenges
- Bioprocess engineer scarcity:Mammalian cell culture and single-use system expertise concentrates among competing Lyon and Paris employers.
- Legacy facility compliance gaps:Pre-2010 stainless steel infrastructure requires costly retrofitting to meet ICH Q7 data integrity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Active Pharmaceutical Ingredients (API) Market |
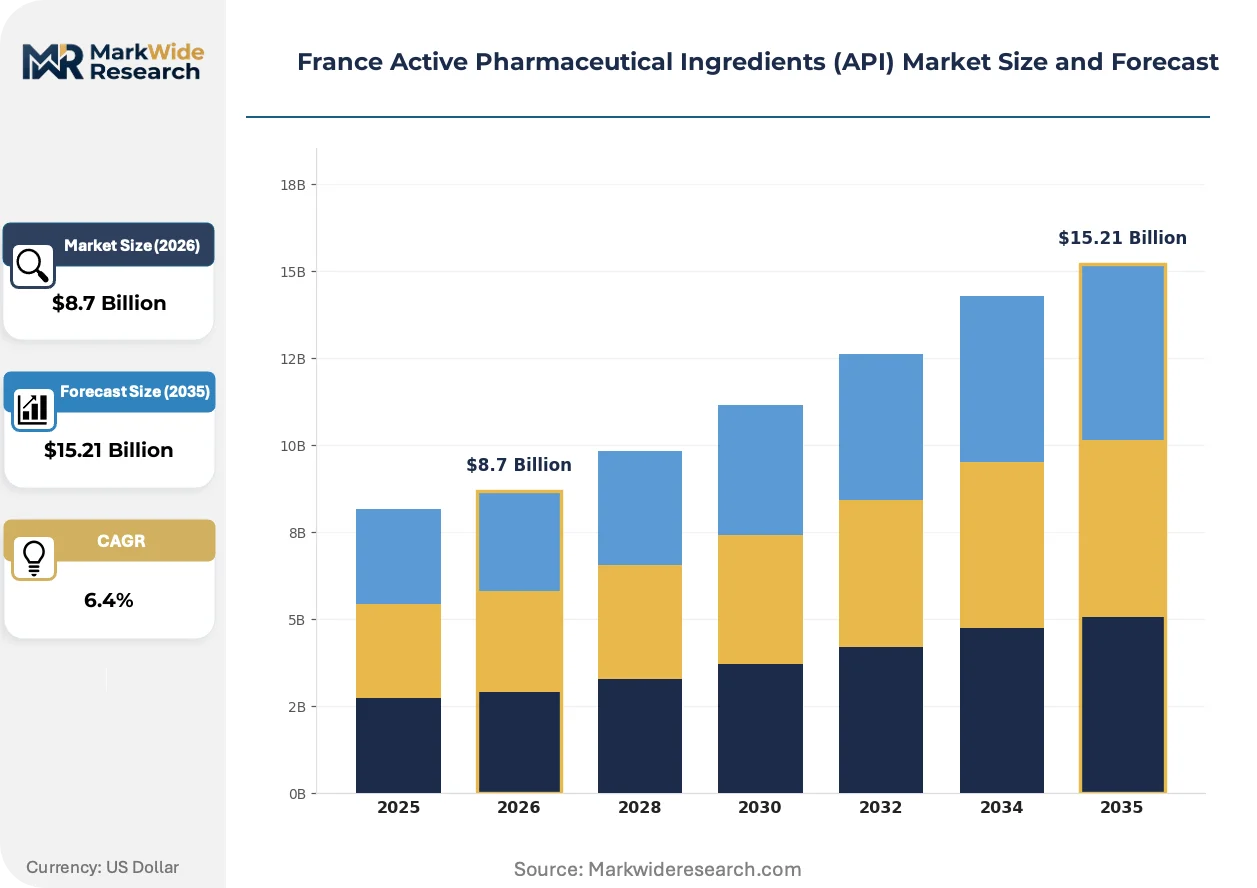
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Antivirals, Hormones, Enzymes, Peptides Therapy Area: Oncology, Cardiovascular, Neurology, Endocrinology, Dermatology, Immunology End User: Pharmaceutical Manufacturers, Biotech Firms, Research Laboratories, Contract Research Organizations, Veterinary Medicine Producers Distribution Channel: Direct Sales, Wholesale Distributors, Online Pharmacies, Medical Supply Chains, Exporters |
| Companies Covered | Merck KGaA, Viatris Inc, Pfizer Inc, Boehringer Ingelheim, Teva Pharmaceutical Industries Ltd, Novartis AG, BASF SE, Aurobindo Pharma, Sanofi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Active Pharmaceutical Ingredients (API) Market Shifts & Advancements
Continuous processing technologies and enzymatic platforms are redrawing capital deployment patterns across French API manufacturing, while regulatory pressure on environmental footprints accelerates facility modernization timelines.
Continuous bioprocessing is migrating from stainless steel batch fermentation to single-use perfusion systems in mammalian cell culture operations. CDMOs serving Paris-Saclay biotech startups adopt these platforms to compress campaign changeover times. The technology is migrating from early-phase clinical supply toward commercial-scale antibody production, displacing conventional fed-batch economics.
ANSM's alignment with EMA GMP inspection frequency increases is tightening documentation and data integrity requirements for API release. French manufacturers face unannounced audits with expanded scope for computer system validation and supplier qualification. High-potency oncology API sites in Lyon and Strasbourg invest in dedicated containment infrastructure to preempt regulatory action.
Biotech procurement teams consolidate supplier panels from multi-source commodity API purchasing toward strategic partnerships with integrated CDMOs. Early-stage companies prioritize end-to-end drug substance and drug product capabilities over transactional API sourcing. This consolidation concentrates contract awards among Île-de-France and Rhône-Alpes facilities with demonstrated regulatory inspection histories.
France Active Pharmaceutical Ingredients (API) Market Segmentation
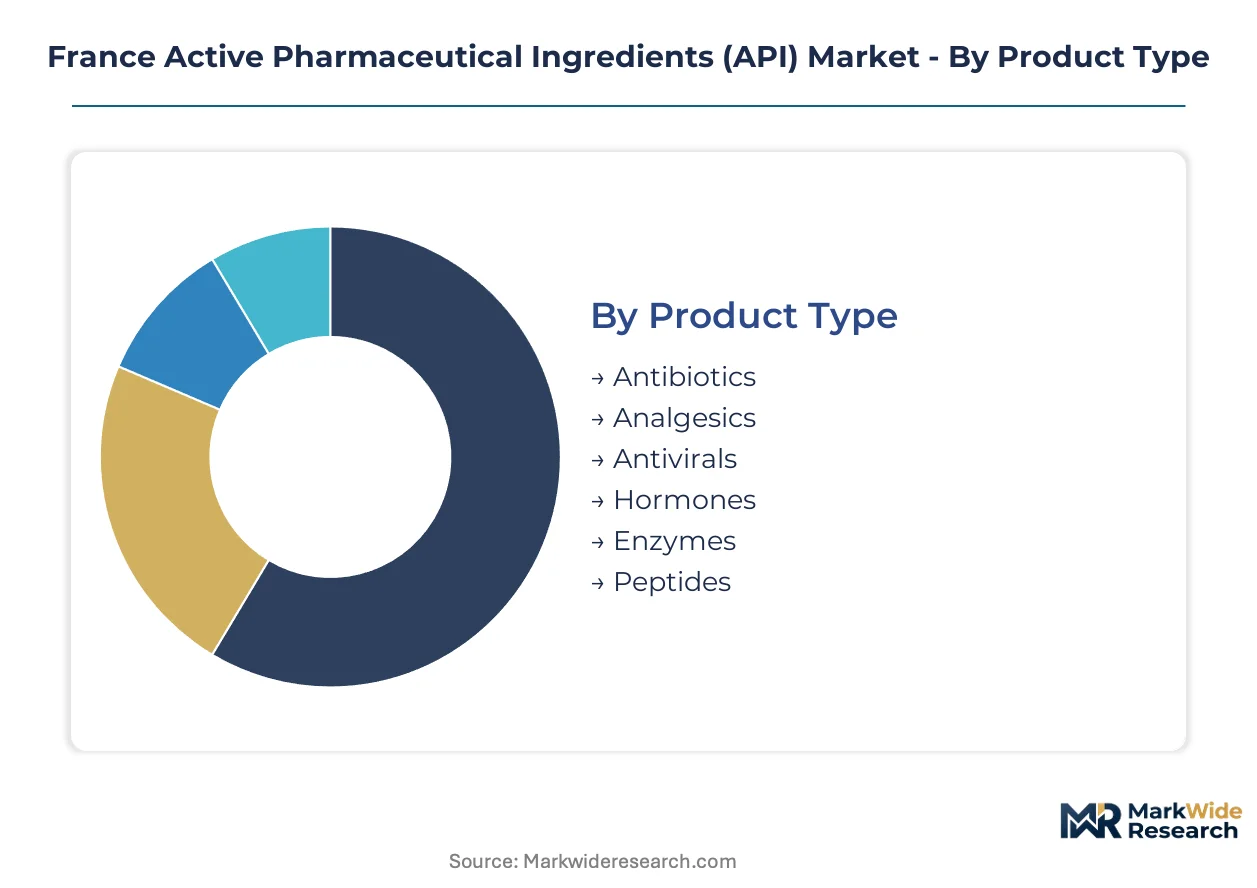
API segmentation in France reveals how manufacturing complexity and regulatory pathways shape procurement priorities across therapeutic categories. Distinct cycle times from synthesis to commercial release create divergent investment profiles for each segment cluster.
Product Type:
Antibiotics turn inventory fastest through standardized fermentation protocols, while peptide APIs stretch cycle times through multi-step solid-phase synthesis and exacting purity validation.
- Antibiotics:Beta-lactam and macrolide APIs rely on mature fermentation infrastructure with well-characterized impurity profiles under ICH Q7. Lyon-based manufacturers serve generic drug producers facing price pressure from Indian import competition.
- Analgesics:Non-opioid NSAID APIs command steady volume from over-the-counter and prescription channels, with acetaminophen and ibuprofen feedstock dominating Rhône-Alpes chemical synthesis output.
- Antivirals:Nucleoside analog APIs require specialized containment for high-potency handling, attracting premium positioning from Île-de-France CDMOs serving hepatitis and emerging infectious disease pipelines.
- Hormones:Steroid and peptide hormone APIs face constrained biosimilar entry due to immunogenicity validation requirements, preserving margin structures for Strasbourg enzymatic biocatalysis specialists.
- Enzymes:Recombinant therapeutic enzymes demand mammalian or microbial expression systems with glycosylation control, concentrating production among Paris-Saclay biotech clusters with perfusion bioreactor capacity.
- Peptides:Synthetic peptide APIs spanning GLP-1 agonists to antimicrobial peptides require SPPS or recombinant routes with rigorous counter-ion specification, extending lead times for commercial campaigns.
Antibiotics dominate installed base. Peptides are where expansion concentrates.
Therapy Area:
Margin tiers separate chronic disease maintenance APIs from oncology and immunology segments where complex synthesis commands pricing premiums.
- Oncology:Cytotoxic and targeted therapy APIs including kinase inhibitors and antibody-drug conjugate payloads require dedicated high-containment facilities with isolator technology and specialized waste handling.
- Cardiovascular:Statin and anticoagulant APIs operate at commodity scale with established generic competition, driving Rhône-Alpes producers toward continuous flow chemistry for cost position.
- Neurology:CNS-active APIs face blood-brain barrier permeability challenges and DEA scheduling constraints for controlled substances, limiting supplier qualification to audited specialty manufacturers.
- Endocrinology:Diabetes and thyroid APIs span synthetic small molecules to recombinant biologics, with insulin analog production concentrating in Lyon mammalian cell culture hubs.
- Dermatology:Topical API formulations prioritize particle size distribution and polymorph control for bioavailability, serving both prescription and cosmeceutical channels through Paris-region formulators.
- Immunology:Monoclonal antibody and cytokine APIs for autoimmune indications pull investment into single-use bioprocessing systems, with Île-de-France CDMOs capturing biotech outsourcing demand.
Cardiovascular commands volume scale. Immunology is climbing the fastest.
End User:
Customer sophistication stratifies procurement from transactional commodity purchasing to strategic partnerships demanding integrated drug-substance-to-drug-product capabilities.
- Pharmaceutical Manufacturers:Large-cap innovators and generic houses maintain internal API capacity for core products while outsourcing specialty synthesis to qualified CDMOs with proven ANSM inspection histories.
- Biotech Firms:Venture-backed developers prioritize speed-to-IND over unit cost, consolidating supplier panels among Île-de-France and Rhône-Alpes facilities with integrated CMC capabilities.
- Research Laboratories:Academic and institutional buyers source gram-to-kilogram quantities of reference standards and investigational APIs through catalog distributors with expedited customs clearance.
- Contract Research Organizations:CROs managing early-phase clinical trials require API supply with flexible batch sizing and rapid analytical method transfer to support adaptive trial designs.
- Veterinary Medicine Producers:Animal health APIs operate under distinct pharmacovigilance frameworks with species-specific residue limits, sourcing through specialized distributors serving European agrochemical channels.
Pharmaceutical Manufacturers anchor procurement volume. Biotech Firms are gaining share fastest.
Distribution Channel:
Channel economics reflect inventory risk allocation and regulatory documentation burdens across the API value chain.
- Direct Sales:Strategic accounts with annual contract values exceeding threshold levels receive dedicated account management and custom synthesis prioritization from API producers with established GMP facilities.
- Wholesale Distributors:Regional chemical and pharmaceutical distributors maintain buffer inventory for standard catalog items, offering credit terms and consolidated sourcing for mid-tier manufacturers.
- Online Pharmacies:B2B procurement platforms serve research and compounding segments with transparent pricing and rapid fulfillment for non-controlled catalog APIs.
- Medical Supply Chains:Hospital-centric purchasing cooperatives aggregate demand for critical care APIs with continuity-of-supply requirements under national pharmaceutical sovereignty frameworks.
- Exporters:French API producers with EMA-approved facilities leverage mutual recognition agreements to supply North African and Middle Eastern markets through specialized trade intermediaries.
Direct Sales commands relationship value. Exporters are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's API trade balance tilts toward specialty biologics exports while generic small-molecule feedstocks flow in from Asian manufacturing hubs. Domestic production clusters concentrate where ANSM inspection density and academic research institutions overlap.
Île-de-France
Paris-Saclay biotech incubators generate monoclonal antibody demand that pulls CDMO investment into mammalian cell culture capacity. ANSM maintains its headquarters here, intensifying inspection frequency for facilities within the region. Genopole d'Évry and neighboring biotech parks anchor contract manufacturing growth for early-phase clinical supply.
Auvergne-Rhône-Alpes
Lyon's biologics hub sustains end-to-end fermentation infrastructure serving oncology and immunology pipelines. The EU Green Deal's REACH solvent discharge limits accelerate enzymatic platform adoption across regional synthesis facilities. Saint-Genis-Laval and Grenoble clusters concentrate perfusion bioreactor operations for commercial-scale antibody production.
Grand Est
Strasbourg enzymatic biocatalysis specialists reduce solvent waste through continuous flow chemistry retrofits at legacy sites. France's national pharmaceutical sovereignty strategy channels investment toward high-potency API containment infrastructure here. Alsace chemical parks leverage cross-border German supply chains while maintaining ANSM GMP compliance for EMA centralized approvals.
Provence-Alpes-Côte d'Azur
Sophia Antipolis technology park draws biotech procurement teams seeking integrated drug-substance-to-drug-product capabilities. The region's CRO density supports rapid analytical method transfer for adaptive clinical trial designs. Marseille's port infrastructure facilitates API export logistics toward North African markets under mutual recognition agreements.
France Active Pharmaceutical Ingredients (API) Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated pharmaceutical innovators and specialized CDMOs serving outsourced demand. Large-cap innovators maintain captive API capacity for core products while divesting commodity synthesis. Strategic archetypes include vertically integrated biologics manufacturers, enzymatic biocatalysis specialists, and regional CDMOs with proven ANSM inspection histories. Competitive moves center on M&A-driven capability consolidation and continuous processing technology licensing.
Within the integrated innovator tier, Sanofi and Boehringer Ingelheim occupy positions exemplifying end-to-end biologics manufacturing and enzymatic platform specialization respectively. Among diversified chemical-pharma conglomerates, Merck KGaA anchors high-purity excipient supply chains serving domestic biotech clusters. These three entities represent distinct strategic postures: captive biologics production, green chemistry leadership, and critical input supply security.
| Leading Market Players |
|---|
| Merck KGaA |
| Viatris Inc |
| Pfizer Inc |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries Ltd |
| Novartis AG |
| BASF SE |
| Aurobindo Pharma |
| Sanofi |
| Others |
Supply & Pricing Matrix
Rhône-Alpes to Paris-Saclay logistics corridors concentrate API freight costs, with temperature-controlled biologics transport commanding premium surcharges that widen price spreads between batch chemical synthesis and mammalian cell culture outputs. ANSM inspection density in Île-de-France adds compliance overhead that feeds into downstream oncology API pricing tiers.
Pricing Analysis
Next-generation continuous flow chemistry platforms command 40-60% premiums over legacy batch fermentation systems, while prior-generation stainless steel infrastructure faces accelerated depreciation. Pricing stratifies across premium, standard, and economy tiers defined by GMP certification grade and containment technology level. Cost compression in generic antibiotic APIs intensifies as Indian import competition erodes Rhône-Alpes fermentation margins. Generic pharmaceutical manufacturers exhibit highest price sensitivity, while orphan drug developers accept premium positioning for small-volume high-complexity synthesis.
Supply Chain Analysis
Tariff exposure between India and France dominates supply chain risk planning for generic API feedstocks. Active pharmaceutical ingredient sourcing draws from India, China, and domestic Rhône-Alpes synthesis clusters. Key input dependencies include fermentation media, specialized solvents under REACH compliance, and single-use bioreactor components. Single-source vulnerability concentrates in high-potency cytotoxic compound isolation technology. Distribution runs through direct sales for strategic accounts and wholesale distributors for standardized catalog items.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's API sector is accelerating through a regulatory-technology inflection as ANSM's EMA-aligned GMP enforcement and EU Green Deal biocatalysis mandates simultaneously reshape capital deployment requirements.
For Market Incumbents: Insulate core biologics capacity through backward integration into perfusion bioreactor component supply. Prioritize ANSM inspection readiness investments at Lyon and Strasbourg facilities to preempt regulatory action. Defend against CDMO consolidation pressure by locking multi-year offtake agreements with Paris-Saclay biotech incubators.
For New Entrants and Emerging Players: Grand Est's enzymatic biocatalysis specialization offers underpenetrated white space for green chemistry platform licensing. Target orphan drug API niches where immunogenicity validation requirements constrain biosimilar entry. Accelerate market access through partnerships with established CDMOs holding proven ANSM inspection histories rather than greenfield facility construction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMOs with demonstrated continuous processing capabilities and regulatory inspection track records. Long-term viability hinges on exposure to biologics manufacturing expansion versus commodity small-molecule exposure. Monitor ANSM unannounced audit frequency as early signal for competitive moat durability among qualified French producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Retrofitting | Legacy Strasbourg batch facilities reduce solvent inventory and REACH compliance costs through enzymatic platform conversion. |
| High-Potency API Containment Investment | Dedicated isolator infrastructure at Lyon sites preempts ANSM regulatory action on cytotoxic compound handling. |
| CDMO Service Bundling | Integrated drug-substance-to-drug-product offerings capture biotech outsourcing from Paris-Saclay incubators. |
| Orphan Drug API Specialization | Small-volume synthesis for rare disease indications commands pricing premiums with limited biosimilar threat. |
| Bioprocess Engineering Talent Acquisition | Mammalian cell culture expertise concentration among competing Lyon and Paris employers creates hiring urgency. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with drug development executives, regulatory affairs leads at ANSM and EMA, CDMO procurement managers, and hospital formulary directors. Secondary validation incorporated FDA filings, EMA centralized approval databases, REACH compliance registries, and French customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across therapeutic category and manufacturing technology dimensions.
Calibration against historical capacity utilization rates and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation modeling spanned product type, therapy area, end user sophistication, and regional production cluster. CAGRs derived from fitted growth curves incorporating biologics pipeline expansion, generic import penetration rates, and ANSM inspection frequency trends. Forecast inputs included mammalian cell culture capacity additions and enzymatic biocatalysis adoption curves.
Practitioners should monitor ANSM inspection protocol revisions and EU Green Deal solvent discharge regulation amendments for early signals of forecast variance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market