
 Industrial Motor Brakes Market | 2026-2036
Industrial Motor Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Motor Brakes Market Foresight
Aftermarket maintenance contracts and predictive brake-wear monitoring is hardening into a standard revenue layer alongside hardware sales. Eaton leverages its integrated power management portfolio to bundle brake servicing with broader motor system contracts. Altra Industrial Motion anchors its position through specialized friction material R&D and broad aftermarket parts distribution. Dellner Bubenzer competes in heavy-duty crane and mining applications where brake reliability carries direct operational risk.
Industrial motor brakes are electromechanical or friction-based stopping devices engineered to decelerate, hold, or emergency-stop rotating motor shafts, typically rated for torque capacities from fractional Nm to over 100 kNm depending on application load. These systems employ spring-applied, electrically released architectures with asbestos-free friction linings to meet modern environmental and thermal performance standards. Electromagnetic brakes dominate light-to-medium duty factory automation due to rapid response times and compact integration with servo and stepper motor systems. Hydraulic brakes command premium positioning in mining and marine winch applications where sustained thermal dissipation under repeated high-inertia stops defines equipment selection. Pneumatic brakes occupy a narrowing but defensible niche in explosive atmosphere environments where spark-free actuation remains mandatory.
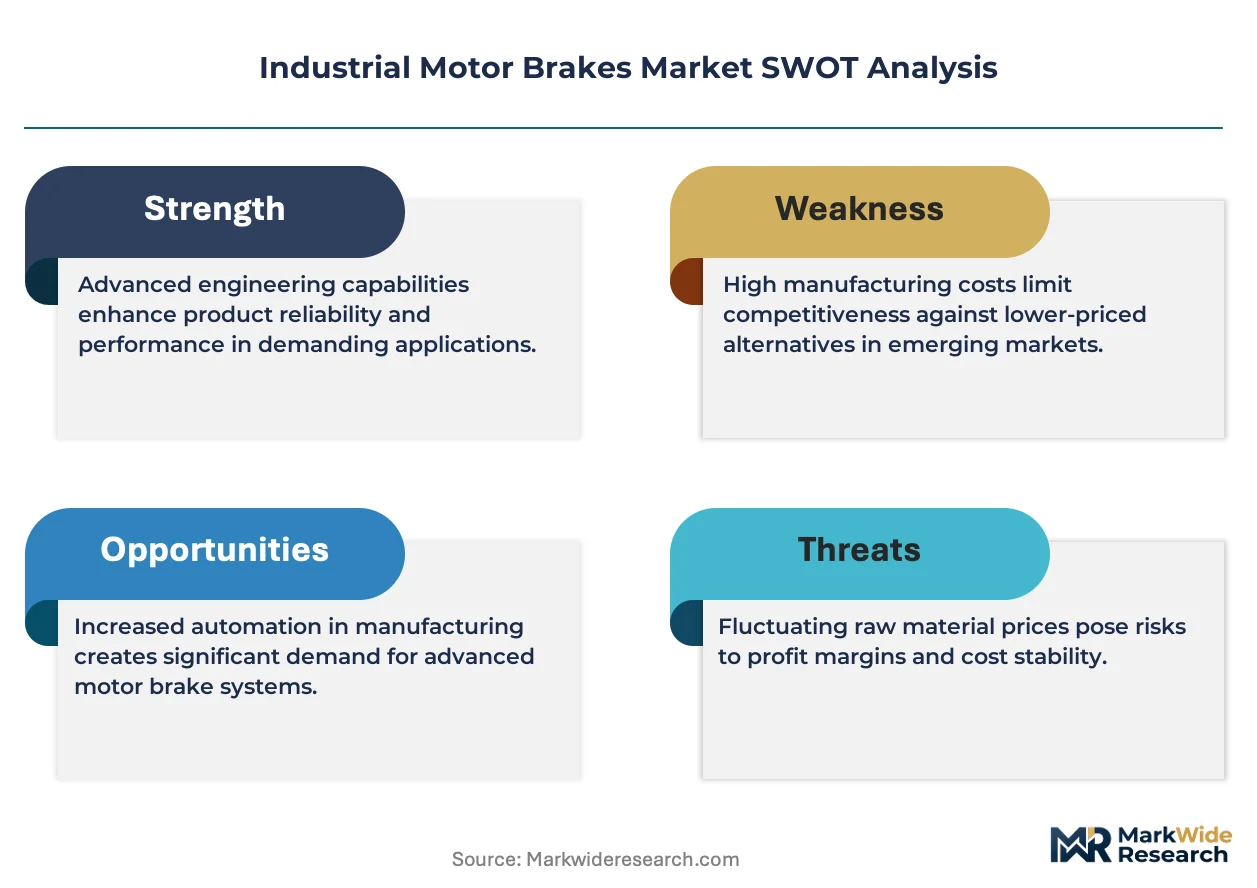
FDA machine safeguarding guidelines for pharmaceutical manufacturing equipment, OSHA mechanical power press standards, and IEC 60204-1 electrical safety of machinery collectively mandate redundant braking systems and documented stopping performance validation. These frameworks push end users toward certified brake-motor packages rather than aftermarket component assembly, tightening supplier qualification requirements. Stakeholders must monitor evolving functional safety standards under ISO 13849 and region-specific efficiency mandates to anticipate specification shifts before procurement cycles lock in vendor selection.
Market Dynamics
Spring-applied electromagnetic brake architectures are displacing pneumatic systems across automated material handling lines, compressing specification cycles and forcing OEMs to redesign motor-integrated packages around IEC 60204-1 safety validation protocols.
Growth Catalysts
- IEC 60204-1 Redundancy Mandates:Machine safety standards in Germany and France now require documented stopping performance validation, pushing end-users toward certified brake-motor bundles rather than component assembly.
- Servo Motor Integration:Factory automation in Japan and South Korea is accelerating demand for compact electromagnetic brakes with sub-50ms response times for precision positioning systems.
- Asbestos-Free Friction Materials:REACH-compliant linings with enhanced thermal dissipation are opening replacement cycles in legacy mining and marine winch installations across Scandinavia.
Market Restraints
- Rare Earth Magnet Cost Volatility:Neodymium price swings disrupt electromagnetic brake manufacturing cost structures, particularly for high-torque servo-integrated units.
- Hydraulic Brake Supply Concentration:Sustained thermal dissipation systems for mining applications depend on a narrow supplier base concentrated in German industrial clusters.
- Electromechanical Substitution Pressure:Regenerative braking in advanced variable frequency drives is capturing hold-duty applications previously served by mechanical friction systems.
Strategic Opportunities
- Predictive Wear Monitoring:IoT-enabled brake lining sensors paired with cloud analytics are creating recurring revenue streams in aftermarket maintenance contracts for crane operators.
- India Manufacturing Expansion:PLI scheme incentives for industrial automation equipment are attracting brake-motor package localization investments to serve domestic material handling demand.
- ISO 13849 Functional Safety Certification:Performance Level e validation is becoming a procurement gate for pharmaceutical packaging lines, rewarding early certifiers with specification lock-in.
Industry Challenges
- Embedded Systems Integration:Brake controller firmware must synchronize with multi-vendor servo drives, creating validation bottlenecks and extended commissioning timelines.
- Thermal Modeling Expertise Gap:Finite element analysis capabilities for high-inertia stop simulation remain scarce among regional system integrators serving heavy industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Motor Brakes Market |
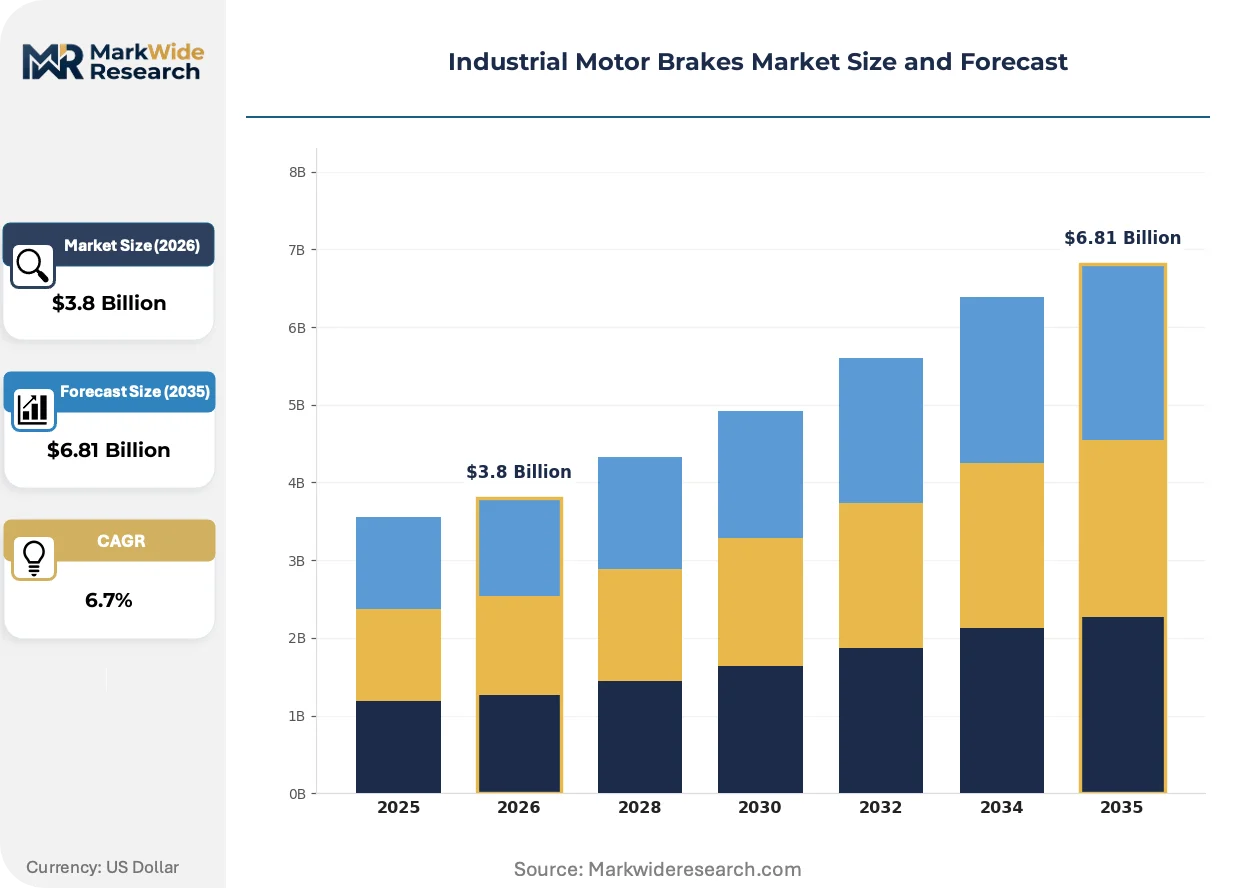
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Brakes, Hydraulic Brakes, Mechanical Brakes, Pneumatic Brakes Technology: AC Motors, DC Motors, Stepper Motors, Servo Motors Application: Conveyor Systems, Packaging Machinery, Cranes, Robotics End User: Manufacturing, Automotive, Aerospace, Mining |
| Companies Covered | Brook Crompton UK Ltd., AKEBONO BRAKE INDUSTRY Co., Ltd., Eaton, Sterling Controls, Ogura Industrial Corp., Altra Industrial Motion, Dellner Bubenzer, Toshiba International Corporation, Warner Electric, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Motor Brakes Market Shifts & Advancements
Intelligent brake systems with embedded condition monitoring are compressing maintenance intervals and rewiring supplier-customer relationships around data-driven service models rather than discrete hardware transactions.
Wireless torque monitoring using surface acoustic wave sensors is decentralizing condition data collection from centralized PLC architectures to edge-computing nodes mounted directly on brake housings. Mining operators in Australia are piloting these systems for real-time thermal load tracking. This architecture is decentralizing predictive maintenance responsibility from plant engineering departments to specialized brake OEM service networks.
The EU F-Gas Regulation is accelerating phase-out of hydraulic fluids with high global warming potential in marine winch applications. Equipment specifiers in Rotterdam and Hamburg ports are rewriting procurement criteria around biodegradable synthetic alternatives. Offshore crane brake systems face the most acute compliance pressure, with retrofit deadlines compressing supplier qualification windows.
Outcome-based contracting for guaranteed stopping performance is displacing traditional unit-price procurement in automotive press lines. Tier-1 suppliers in Stuttgart and Detroit are negotiating brake-system availability commitments with penalty clauses for unplanned downtime. This model is most advanced in Germany, where OEM bundling with servo motor systems already dominates specification behavior.
Industrial Motor Brakes Market Segmentation
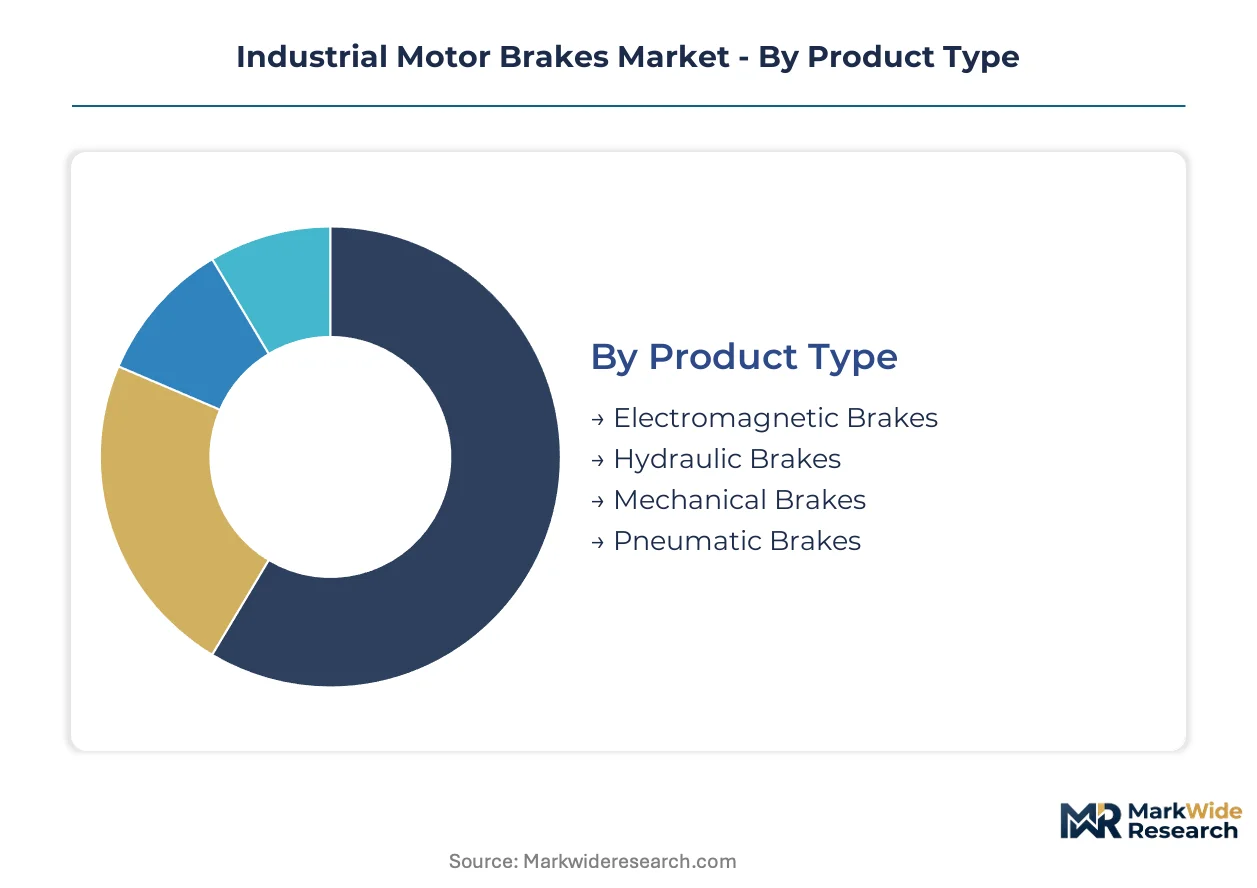
Brake specification in industrial automation hinges on torque density requirements, thermal cycling frequency, and integration complexity with motor control architectures. Procurement teams evaluate segments through the lens of functional safety certification tiers and total lifecycle service cost rather than unit price alone.
Product Type:
Equipment buyers prioritize stopping energy capacity and response latency when selecting brake architectures for specific duty cycles.
- Electromagnetic Brakes:Spring-applied, electrically released units with sub-50ms engagement times dominate precision positioning systems. Demand concentrates in Japanese and South Korean factory automation clusters where servo motor integration mandates compact form factors.
- Hydraulic Brakes:Oil-immersed multi-disc designs deliver sustained thermal dissipation for high-inertia stops. Mining operators in Australia and Chile specify these for dragline and shovel applications where brake failure carries direct production risk.
- Mechanical Brakes:Cam-operated or screw-based manual systems persist in legacy equipment retrofit markets.
- Pneumatic Brakes:Spark-free actuation retains defensible positioning in explosive atmosphere environments under ATEX directives.
Volume sits with electromagnetic architectures; growth tilts toward hydraulic systems in heavy-duty extraction industries.
Technology:
Motor control sophistication determines brake interface complexity and diagnostic capability requirements.
- Servo Motors:Closed-loop positioning systems with integrated encoders demand brakes with verified holding torque repeatability. German automotive press lines specify Performance Level e certified brake-motor bundles under ISO 13849.
- AC Motors:Induction motor platforms across material handling and pumping applications favor cost-optimized electromagnetic brakes with standard NEMA frame interfaces.
- DC Motors:Wound-field and permanent magnet designs in legacy manufacturing equipment drive replacement brake demand.
- Stepper Motors:Open-loop positioning in packaging and labeling machinery requires compact brakes with precise detent torque characteristics.
Mature AC motor brake configurations dominate installed base; servo-integrated units are climbing the fastest as precision automation expands.
Application:
Operational duty intensity and safety criticality shape brake specification across equipment categories.
- Cranes:Hoist and trolley braking systems face redundant safety mandates under OSHA and FEM standards. Port operators in Rotterdam and Singapore specify dual-circuit brakes with documented stopping distance validation.
- Conveyor Systems:Bulk material handling lines require controlled deceleration to prevent product spillage and mechanical shock.
- Packaging Machinery:High-cycle indexing equipment favors compact electromagnetic brakes with rapid cycling capability.
- Robotics:Collaborative robot joints and linear actuators integrate zero-backlash holding brakes for power-loss protection.
Crane applications anchor revenue concentration; robotics integration offers the steepest expansion trajectory as cobot deployment accelerates.
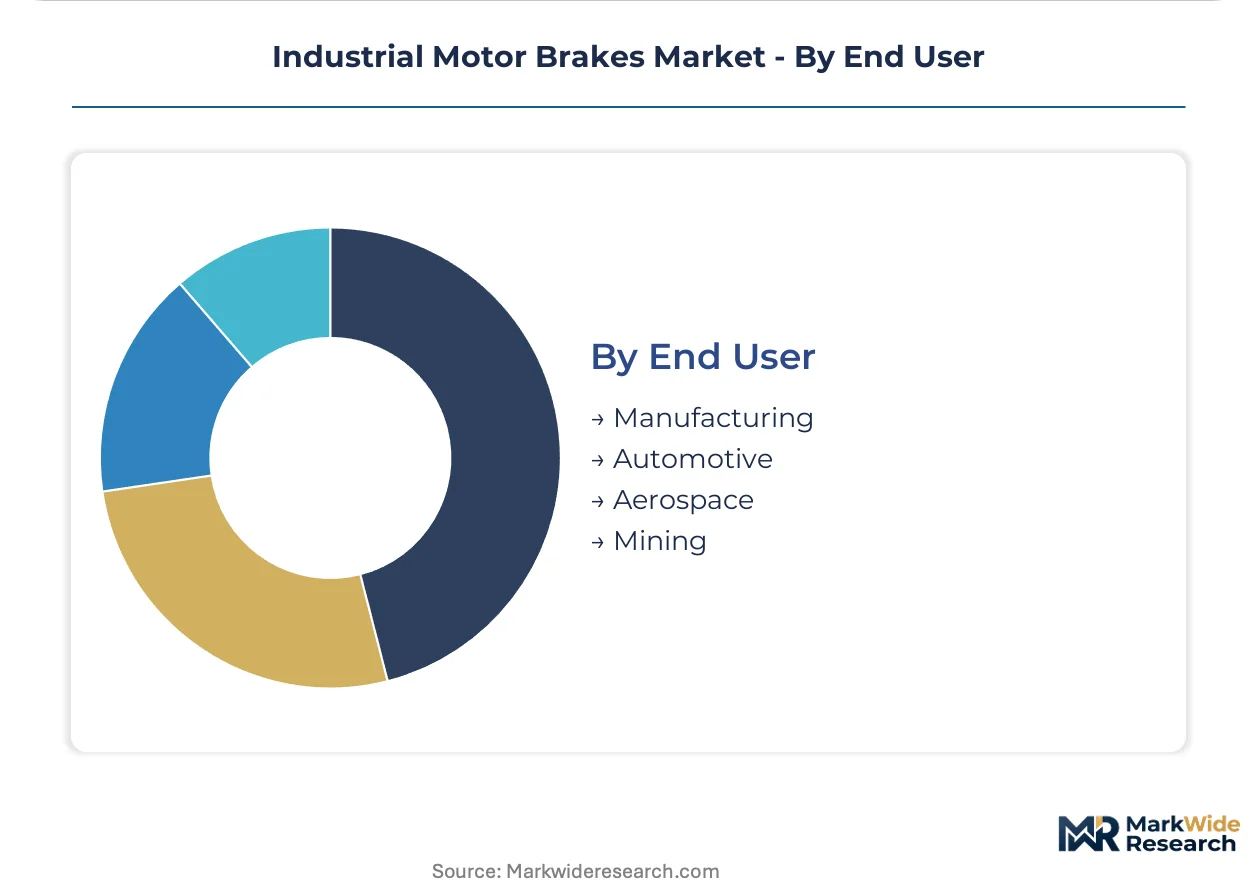
End User:
Capital expenditure cycles and regulatory exposure vary sharply across industrial sectors.
- Manufacturing:Discrete and process automation across automotive, electronics, and food processing drives recurring brake replacement demand. German OEMs bundle certified brake-motor packages to meet IEC 60204-1 machine safety requirements.
- Mining:Surface and underground extraction equipment subjects brakes to abrasive contamination and extreme thermal loading.
- Automotive:Press line and assembly system operators are adopting outcome-based contracting with guaranteed availability commitments.
- Aerospace:MRO facilities and manufacturing tooling require traceable brake certification for airworthiness documentation.
Manufacturing sector procurement dominates transaction volume; mining sector replacement intensity supports premium pricing for thermal-rated systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors industrial motor brake procurement intensity, with German automotive press lines demanding certified brake-motor bundles under IEC 60204-1 machine safety protocols. Demand concentrates in manufacturing corridors where servo automation density and regulatory exposure intersect.
Germany
Automotive OEMs in Stuttgart and Munich specify Performance Level e brake systems for press line automation. The country's Federal Ministry for Economic Affairs enforces Machinery Directive compliance through notified body certification. Bavaria's industrial automation cluster drives specification lock-in for integrated servo-brake packages.
United States
OSHA mechanical power press standards mandate redundant braking systems across automotive stamping operations in Detroit and Chicago. The Department of Labor enforces documented stopping performance validation through regional compliance inspections. Texas-based oilfield equipment manufacturers specify heavy-duty hydraulic brakes for drilling rig winch applications.
Japan
Factory automation in Nagoya and Osaka demands electromagnetic brakes with sub-50ms response times for precision positioning systems. METI promotes servo motor integration through industrial competitiveness grants. The Chubu region's robotics manufacturing corridor concentrates specification authority for collaborative robot brake systems.
China
MIIT efficiency mandates accelerate brake-motor package localization for domestic material handling equipment. The Yangtze River Delta manufacturing belt generates concentrated demand for cost-optimized electromagnetic brake configurations. Shanghai port operators specify redundant crane braking systems under national safety supervision protocols.
India
PLI scheme incentives attract brake-motor localization investments to serve domestic automation demand in Pune and Chennai. The Department of Heavy Industry administers capital subsidy programs for industrial machinery component manufacturing. Gujarat's automotive component corridor emerges as a procurement hub for certified brake assemblies.
Industrial Motor Brakes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the industrial motor brakes market, with integrated power management conglomerates holding scale advantages in aftermarket service bundling. The vendor base stratifies between diversified industrial groups, specialized friction material developers, and regional component fabricators. Two dominant archetypes prevail: full-stack motor system integrators leveraging installed base relationships, and niche specialists commanding premium positioning in safety-critical heavy industry applications. Competitive dynamics center on M&A-driven portfolio consolidation and predictive maintenance service model expansion.
Among diversified industrial conglomerates, Eaton and Altra Industrial Motion occupy positions spanning integrated power management and specialized motion control. Dellner Bubenzer represents the heavy-duty application specialist archetype, with naming convention suggesting European engineering heritage. These three entities exemplify contrasting strategic postures: diversified service bundling versus concentrated technical specialization in high-risk operational environments.
| Leading Market Players |
|---|
| Brook Crompton UK Ltd. |
| AKEBONO BRAKE INDUSTRY Co., Ltd. |
| Eaton |
| Sterling Controls |
| Ogura Industrial Corp. |
| Altra Industrial Motion |
| Dellner Bubenzer |
| Toshiba International Corporation |
| Warner Electric, Inc. |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-out mandates for high-global-warming-potential hydraulic fluids are gating qualified supply access and compressing premium-tier pricing windows for marine winch brake systems in Rotterdam and Hamburg port procurement cycles.
Pricing Analysis
Outcome-based contracting for guaranteed stopping performance anchors value-based pricing in German automotive press lines. Three-tier pricing structure across Performance Level e certified, standard IEC 60204-1 compliant, and economy non-certified configurations reflects certification grade and thermal duty rating differentiation. Cost compression in economy electromagnetic brake tiers is intensifying because rare earth magnet price volatility feeds through manufacturing cost structures. Tier-1 automotive OEMs exhibit lowest price sensitivity due to penalty clauses for unplanned downtime, while regional material handling integrators in India remain most price-sensitive.
Supply Chain Analysis
Container freight rate volatility from Asia to Europe disrupts just-in-time brake-motor package delivery schedules for German automotive OEMs. Manufacturing concentration in Germany, Japan, and China for high-torque servo-integrated units draws from specialized friction material suppliers in Scandinavia and rare earth magnet processors in China. Single-source vulnerability for neodymium supply creates exposure to export restriction shocks. Distribution runs through OEM direct procurement for certified brake-motor bundles and industrial distributor networks for aftermarket replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over asbestos-free friction material supply determines margin sustainability and thermal performance certification timelines.
For Market Incumbents: Lock in servo motor OEM specification authority through early ISO 13849 Performance Level e certification investment before procurement cycles freeze vendor selection. Deepen backward integration into specialized friction material production to insulate against REACH-compliant lining supply bottlenecks. Regenerative braking capture in advanced variable frequency drives threatens hold-duty mechanical brake volumes.
For New Entrants and Emerging Players: Predictive wear monitoring IoT sensors paired with cloud analytics offer a technology-first wedge into crane operator aftermarket maintenance contracts where incumbent service bundling remains underdeveloped. Target India PLI scheme subsidized manufacturing corridors for brake-motor package localization to serve domestic material handling automation demand. Pursue direct partnerships with port authority engineering departments bypassing established industrial distributor channels.
For Investors and Strategic Acquirers: First-mover ISO 13849 certification announcements from mid-tier brake specialists are the leading indicator that specification lock-in windows are closing and valuation premiums for certified assets are expanding. Five-to-ten year viability favors vertically integrated producers with captive friction material R&D and regional aftermarket parts distribution networks. Monitor EU F-Gas Regulation enforcement intensity in marine applications as signal for hydraulic brake retrofit cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance Level e Certification Investment | ISO 13849 validation gates German automotive press line procurement and locks out uncertified competitors. |
| Backward Integration into Friction Materials | REACH-compliant asbestos-free lining R&D captive supply insulates thermal performance margins from raw material volatility. |
| Predictive Maintenance Service Model Launch | IoT-enabled brake wear sensors create recurring revenue streams with crane operators in Australian mining corridors. |
| India PLI Scheme Manufacturing Localization | Domestic brake-motor package production serves Pune and Chennai material handling automation demand with import cost advantage. |
| Hydraulic Fluid Biodegradable Transition | EU F-Gas Regulation compliance for marine winch applications opens retrofit specification windows in Rotterdam and Hamburg ports. |
Research Methodology
Document review covered regulatory filings with OSHA and IEC standards bodies, trade association technical bulletins, and OEM procurement specifications, complemented by interviews with plant maintenance directors, servo system integration engineers, aftermarket service heads at industrial distributors, and brake-motor procurement teams at Tier-1 automotive suppliers. Secondary validation drew from customs trade data for friction material imports, SEC 10-K disclosures from diversified industrial conglomerates, and machinery safety certification databases. Bottom-up segment sizing triangulated against top-down industrial automation capex flow analysis.
Cross-referencing historical brake replacement cycle data against expert panel input on servo motor integration timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include brake architecture type, motor control technology interface, application duty intensity, end-user sector regulatory exposure, and regional automation density cluster. CAGRs were derived from installed base growth projections and replacement intensity assumptions, incorporating thermal cycling frequency degradation curves and functional safety mandate adoption rates as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced rare earth export restrictions, sudden shifts in machine safety standard enforcement intensity, and disruptive electromechanical brake substitution by regenerative drive systems. Forecasts reflect assumptions about certification timeline adherence and OEM bundling behavior that market participants may revise. Stakeholders should weight assumptions against their own operating context and regional regulatory inspection priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Power Scraper Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Charging Nitrogen Gas Systems Market