
 Global Lithotripsy Device Market | 2026-2036
Global Lithotripsy Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithotripsy Device Market Foresight
Preventive maintenance subscriptions for shock wave generators is decoupling capital sales from recurring revenue pools across the installed base. Dornier MedTech GmbH leverages its electromagnetic heritage to anchor replacement part streams in European university hospitals. Siemens Healthineers AG competes through embedded software analytics that predict tube degradation before failure. Boston Scientific Corporation extends its urology ecosystem by bundling disposable access sheaths with lithotripsy service contracts.
Lithotripsy devices generate focused acoustic or laser energy to fragment calculi within the urinary, biliary, or salivary tracts without incision, with electromagnetic systems typically operating at 18-24 kV discharge voltages and focal zones of 4-8 mm in diameter. Extracorporeal shock wave lithotripters occupy the mature volume tier where refurbishment cycles sustain aftermarket margins, while laser lithotripters capture premium positioning in flexible ureteroscopy workflows. Piezoelectric technology leads precision applications in pediatric and obese patient populations where focal accuracy reduces collateral tissue injury.
FDA premarket notification requirements for lithotripsy systems mandate acoustic output characterization and biological safety testing under 21 CFR 892.1550, while the EU MDR reclassification of active therapeutic devices has extended notified body review timelines for electromagnetic and electrohydraulic platforms. Japan's PMDA enforces JIS T 0601-1 electrical safety standards that filter non-compliant OEMs from tender participation. Stakeholders must monitor reimbursement parity between inpatient and ambulatory stone procedures as this determines site-of-care investment priority.
Market Dynamics
Electromagnetic shock wave generators are displacing electrohydraulic platforms in hospital procurement cycles, compressing replacement timelines and decoupling capital equipment sales from recurring service revenue pools.
Growth Catalysts
- EU MDR Reclassification:Extended notified body review timelines for electromagnetic lithotripters are filtering marginal competitors and consolidating procurement decisions around established OEMs with regulatory infrastructure.
- Ambulatory Surgical Center Expansion:Same-day stone treatment protocols in Germany, Japan, and Brazil are accelerating laser lithotripter installations outside traditional hospital settings.
- Piezoelectric Precision:Pediatric and obese patient populations where focal accuracy reduces collateral tissue injury are driving niche adoption of piezoelectric systems in academic medical centers.
Market Restraints
- Tube Degradation Costs:Electromagnetic generator cathode-anode assemblies require predictable replacement cycles that inflate total cost of ownership beyond initial capital outlay.
- Supply Concentration:High-voltage discharge components for shock wave systems concentrate among German and Japanese component specialists, exposing procurement to single-source fragility.
- Reimbursement Parity Gaps:Divergent inpatient and ambulatory stone procedure coding in multiple markets distorts site-of-care investment priority and extends capital approval cycles.
Strategic Opportunities
- Brazilian Installation Base:Underpenetrated tertiary hospital networks in São Paulo and Rio de Janeiro present whitespace for laser-based flexible ureteroscopy workflows.
- Embedded Predictive Analytics:Convergence of shock wave generator telemetry with machine learning is enabling preemptive maintenance scheduling that locks in multi-year service contracts.
- Japan PMDA Electrical Safety:JIS T 0601-1 compliance requirements create regulatory moats for OEMs willing to absorb certification costs, filtering tender participation.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Cross-functional expertise combining acoustic physics, high-voltage engineering, and urological clinical workflow remains concentrated in European and Japanese training programs.
- FDA 510(k) Acoustic Characterization:21 CFR 892.1550 biological safety testing requirements extend premarket notification timelines and compress competitive windows for platform refreshes.
- Legacy System Integration:Electromagnetic lithotripter refurbishment cycles must accommodate hospital information system architectures that lag current connectivity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithotripsy Device Market |
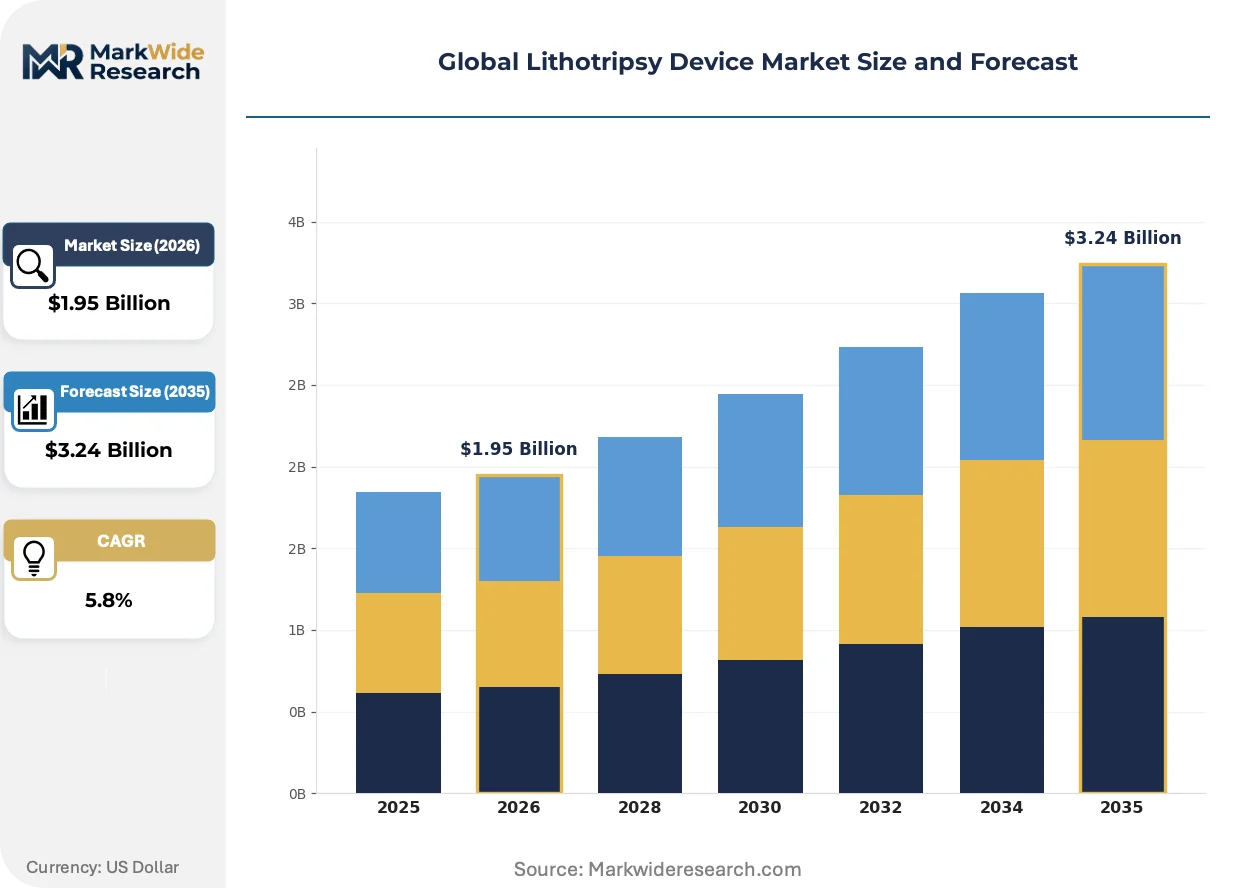
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracorporeal Shock Wave, Laser Lithotripter, Electromagnetic Lithotripter, Ultrasonic Lithotripter Application: Urinary Stone Treatment, Gallstone Management, Salivary Stone Removal, Pancreatic Stone Therapy End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Centers Technology: Electrohydraulic, Piezoelectric, Electromagnetic, Laser-Based |
| Companies Covered | Boston Scientific Corporation, Dornier MedTech GmbH, EDAP TMS S.A., DirexGroup, Olympus Corporation, Siemens Healthineers AG, Karl Storz SE & Co. KG, Lumenis Ltd., STORZ MEDICAL AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithotripsy Device Market Shifts & Advancements
Digital service unbundling and predictive maintenance architectures are rewriting how lithotripsy OEMs capture lifetime value from installed bases.
Holmium:YAG laser lithotripters with integrated suction and irrigation channels are rewriting procedural efficiency benchmarks in flexible ureteroscopy. Academic medical centers in Germany and Japan are replacing electrohydraulic platforms at accelerated refresh cycles. This displacement is compressing capital sales windows while expanding disposable sheath attach rates.
FDA premarket notification pathways for electromagnetic lithotripters are compressing trial timelines through streamlined acoustic output characterization protocols. Device manufacturers are front-loading biological safety documentation to preempt 510(k) review queries. Ambulatory surgical center applicants are the primary beneficiaries, gaining faster access to same-day stone treatment certification.
After-sales service contracts are unbundling from capital equipment purchases as hospital procurement departments demand transparent lifecycle cost modeling. Predictive tube degradation analytics embedded in generator firmware are displacing scheduled maintenance calendars. European university hospitals are the proving ground for this transition, with German procurement frameworks leading contractual restructuring.
Global Lithotripsy Device Market Segmentation
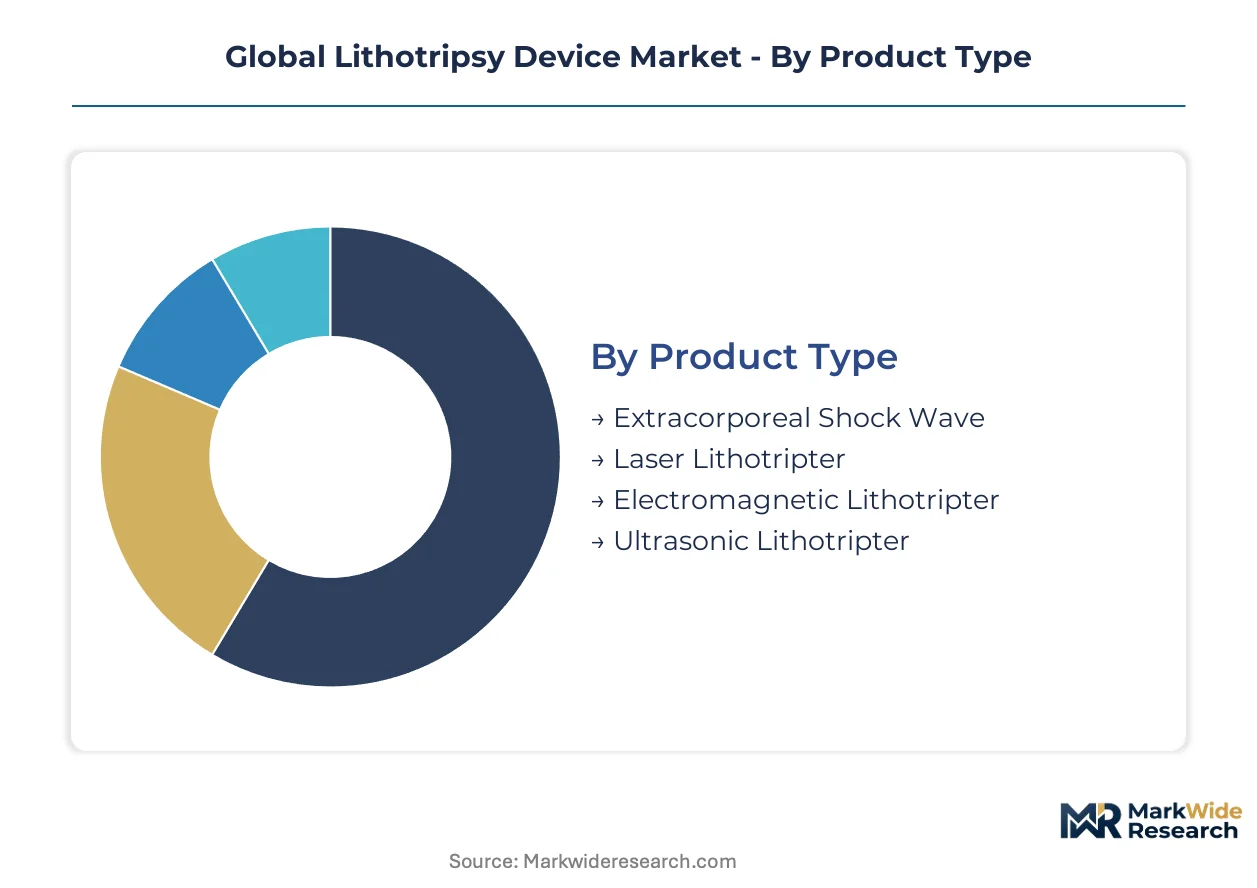
Segmentation reveals how lithotripsy device manufacturers allocate R&D budgets across divergent energy modalities and care settings. Procurement patterns vary sharply between capital-intensive hospital installations and disposable-heavy ambulatory workflows.
Product Type:
Supply concentration for high-voltage discharge components concentrates procurement leverage among electromagnetic and electrohydraulic platform specialists.
- Extracorporeal Shock Wave:These systems generate focused acoustic pulses outside the body to fragment urinary and biliary calculi without incision. Mature installed bases in Germany and Japan sustain refurbishment revenue streams as hospitals extend equipment lifecycles through preventive maintenance subscriptions.
- Laser Lithotripter:Holmium:YAG platforms deliver precise energy delivery through flexible ureteroscopes for same-day stone treatment. Ambulatory surgical centers in São Paulo and Rio de Janeiro are absorbing disproportionate installation volumes as Brazilian tertiary networks expand minimally invasive capacity.
- Electromagnetic Lithotripter:Coil-based shock wave generators operate at 18-24 kV discharge voltages with focal zones of 4-8 mm diameter. FDA 510(k) clearance timelines are compressing through streamlined acoustic output characterization protocols.
- Ultrasonic Lithotripter:Piezoelectric crystal arrays enable precision fragmentation with reduced collateral tissue injury. Pediatric and obese patient populations in academic medical centers drive niche adoption where focal accuracy is paramount.
Extracorporeal shock wave systems absorb the bulk of installed capacity; laser lithotripters are expanding most quickly.
Application:
Reimbursement parity between inpatient and ambulatory procedure coding determines site-of-care investment priority across each indication.
- Urinary Stone Treatment:Kidney and ureteral calculi fragmentation represents the dominant volume application. Flexible ureteroscopy workflows in German and Japanese hospitals are displacing percutaneous nephrolithotomy for stones under 20 mm diameter.
- Gallstone Management:Extracorporeal shock wave lithotripsy for cholelithiasis competes with laparoscopic cholecystectomy in cost-sensitive markets. European university hospitals maintain selective programs for high-surgical-risk patients.
- Salivary Stone Removal:Sialolithiasis treatment via intraoral lithotripsy occupies a narrow specialty niche. Otolaryngology departments in academic medical centers deploy piezoelectric systems for duct-preserving fragmentation.
- Pancreatic Stone Therapy:Chronic pancreatitis with main duct stones requires endoscopic retrograde cholangiopancreatography integration. Japanese tertiary centers lead procedural volume given higher prevalence of alcohol-related and idiopathic disease.
Urinary stone treatment commands the dominant revenue share; gallstone management is climbing the fastest as ambulatory protocols mature.
End User:
Capital approval cycles and total cost of ownership calculations diverge sharply between integrated health systems and independent surgical facilities.
- Hospitals:Integrated health systems in Germany and Brazil concentrate procurement of electromagnetic platforms with multi-year service contracts. Predictive tube degradation analytics embedded in generator firmware are displacing scheduled maintenance calendars.
- Specialty Clinics:Urology-focused facilities prioritize laser lithotripter throughput metrics and disposable attach rates. European procurement frameworks are unbundling after-sales service from capital equipment purchases.
- Ambulatory Surgical Centers:Same-day stone treatment protocols accelerate laser-based installations outside traditional hospital settings. FDA clearance pathway compression primarily benefits these applicants seeking faster certification timelines.
- Diagnostic Centers:Imaging-integrated stone detection and triage functions create workflow adjacencies. JIS T 0601-1 electrical safety compliance filters non-compliant OEMs from Japanese tender participation.
Hospitals retain the deepest installed base; ambulatory surgical centers are gaining share fastest as site-of-care migration accelerates.
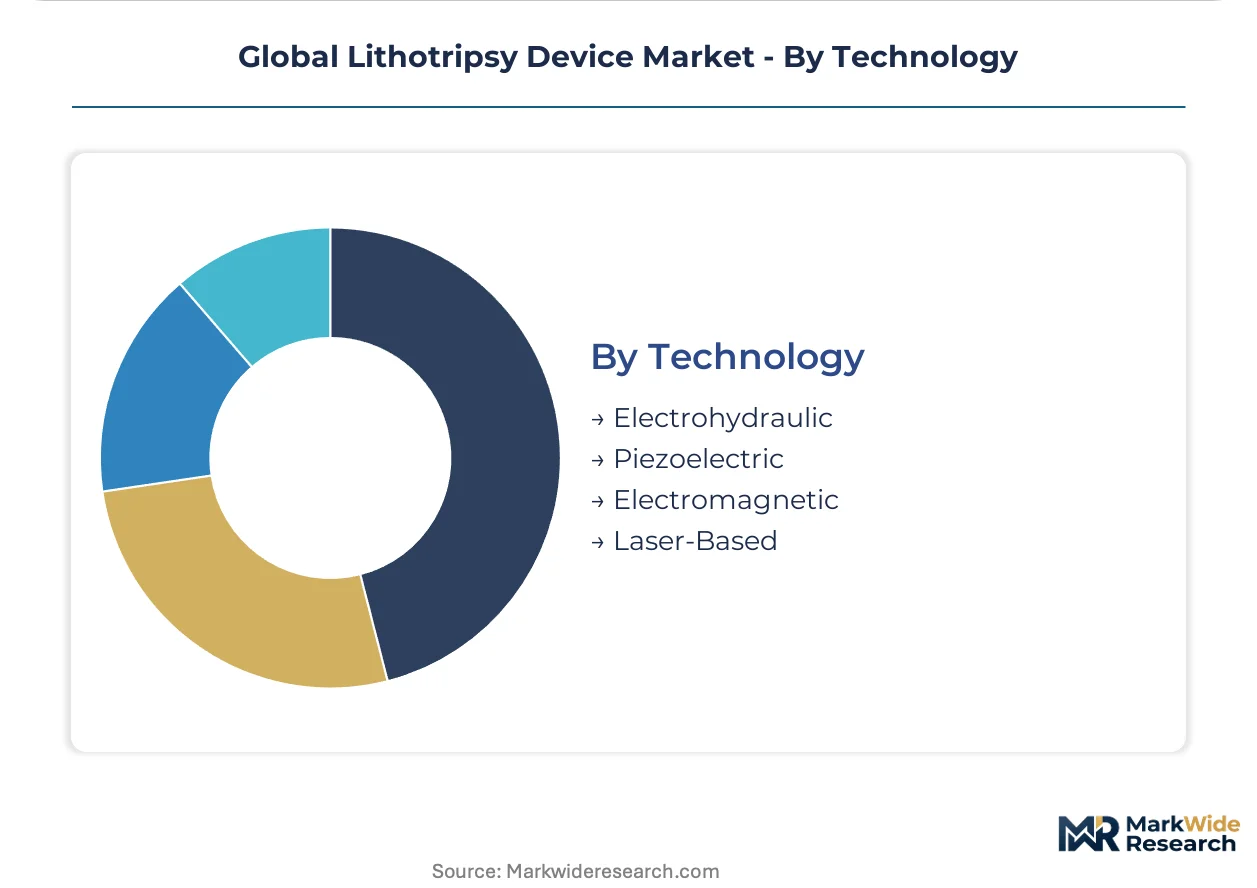
Technology:
Energy modality selection directly determines maintenance burden, consumable attach rates, and regulatory pathway complexity.
- Electrohydraulic:Spark-gap shock wave generation dominates mature installed bases requiring predictable electrode replacement cycles. Refurbishment economics sustain aftermarket margins as hospitals delay capital refresh decisions.
- Piezoelectric:Ceramic crystal arrays deliver precise focal zones for pediatric and obese populations where collateral tissue injury minimization is critical. Academic medical centers in Germany and Japan anchor demand.
- Electromagnetic:Coil-based acoustic generation is displacing electrohydraulic platforms in hospital procurement cycles. EU MDR reclassification has extended notified body review timelines, filtering marginal competitors.
- Laser-Based:Holmium:YAG wavelength absorption by urinary stones enables controlled fragmentation with integrated suction and irrigation. Brazilian and Japanese installation growth outpaces other geographies.
Electrohydraulic technology retains the largest legacy footprint; laser-based systems are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan concentrate lithotripsy device manufacturing capacity, while Brazil and the United States absorb disproportionate installation volumes as ambulatory stone treatment protocols expand. Production clusters in Bavaria and Baden-Württemberg supply electromagnetic generator components to hospital networks worldwide.
United States
Ambulatory surgical centers in Florida, Texas, and Arizona are accelerating laser lithotripter procurement for same-day stone treatment protocols. FDA 510(k) clearance pathways under 21 CFR 892.1550 are compressing premarket notification timelines for electromagnetic platforms. The Cleveland Clinic and Mayo Clinic anchor academic demand for piezoelectric precision systems in pediatric populations.
Germany
University hospitals in Munich and Heidelberg are replacing electrohydraulic platforms with electromagnetic systems at compressed refresh cycles. EU MDR reclassification of active therapeutic devices has extended notified body review timelines, filtering marginal competitors from tender participation. The Stuttgart industrial corridor concentrates high-voltage discharge component manufacturing for shock wave generators.
Japan
Tertiary centers in Tokyo and Osaka lead global procedural volume for pancreatic stone therapy given higher prevalence of alcohol-related chronic pancreatitis. PMDA enforces JIS T 0601-1 electrical safety standards that exclude non-compliant OEMs from public hospital tenders. The Nagoya medical device cluster anchors domestic production of Holmium:YAG laser platforms.
Brazil
Underpenetrated tertiary networks in São Paulo and Rio de Janeiro are absorbing disproportionate volumes of laser-based flexible ureteroscopy installations. ANVISA regulatory pathways for active therapeutic devices require in-country electrical safety certification that extends approval timelines for non-local manufacturers. The São Paulo metropolitan corridor concentrates private hospital investment in ambulatory stone treatment capacity.
China
Domestic hospital procurement of extracorporeal shock wave systems is intensifying as county-level medical facilities upgrade urology departments. NMPA Class III medical device registration mandates clinical trial data for electromagnetic lithotripters that extends approval cycles versus 510(k) equivalents. The Yangtze River Delta industrial corridor hosts emerging domestic manufacturers of piezoelectric crystal arrays.
Global Lithotripsy Device Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across lithotripsy device manufacturing, with integrated health systems favoring multi-year service contracts over discrete equipment purchases. The vendor base clusters around three strategic archetypes: electromagnetic heritage specialists leveraging replacement part streams, diversified medtech conglomerates bundling disposables with capital sales, and laser-focused pure-plays capturing ambulatory workflow premiums. Competitive positioning hinges on predictive maintenance analytics and regulatory infrastructure rather than hardware specifications alone. M&A activity targets service contract portfolios and embedded software capabilities.
Within the electromagnetic heritage tier, Dornier MedTech GmbH and Siemens Healthineers AG exemplify divergent approaches to installed base monetization. Dornier MedTech GmbH anchors replacement part streams in European university hospitals through preventive maintenance subscriptions. Siemens Healthineers AG occupies a position emphasizing embedded firmware analytics that predict tube degradation before failure. Boston Scientific Corporation represents the diversified conglomerate archetype, extending urology ecosystem reach through bundled disposable access sheaths.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Dornier MedTech GmbH |
| EDAP TMS S.A. |
| DirexGroup |
| Olympus Corporation |
| Siemens Healthineers AG |
| Karl Storz SE & Co. KG |
| Lumenis Ltd. |
| STORZ MEDICAL AG |
| Others |
Supply & Pricing Matrix
Electromagnetic generator cathode-anode assembly manufacturing is consolidating in Bavarian and Baden-Württemberg industrial corridors, simultaneously compressing procurement leverage for high-voltage discharge components and elevating service contract premiums for predictive maintenance subscriptions. This production-method transition forces hospital procurement departments toward transparent lifecycle cost modeling that decouples capital equipment purchases from recurring revenue streams.
Pricing Analysis
Margin tightening in electromagnetic lithotripter tiers reflects EU MDR reclassification compliance costs filtering marginal competitors from tender participation. Three-tier pricing structure across premium, standard, and economy levels stratifies by predictive analytics integration and after-sales bundling intensity. Pricing pressure stems from ambulatory surgical center procurement departments demanding unbundled service transparency. Specialty clinics exhibit highest price sensitivity; integrated German health systems absorb premium positioning for multi-year predictive maintenance contracts.
Supply Chain Analysis
Dual-sourcing requirements for high-voltage discharge components mandate German and Japanese supplier qualification, exposing procurement to single-source fragility in coil-based shock wave generator assemblies. Raw material dependencies center on ceramic piezoelectric crystals, holmium-doped YAG laser rods, and electromagnetic coil windings. Supply chain risk concentrates in tariff exposure for Japanese JIS T 0601-1 certified electrical components. Distribution runs through hospital procurement committees and GPO contracts managers with extended capital approval cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-voltage discharge component manufacturing capacity concentrates among Bavarian and Nagoya industrial clusters, propping service contract premiums as procurement leverage compresses for electromagnetic platform specialists.
For Market Incumbents: Deepen backward integration into ceramic piezoelectric crystal production to secure pediatric precision system supply chains against emerging Asian component specialists. Lock in multi-year predictive maintenance subscriptions through embedded firmware analytics that preempt tube degradation failures, defending installed base monetization from asset-light laser pure-plays capturing ambulatory workflow premiums.
For New Entrants and Emerging Players: Capture whitespace in Brazilian tertiary hospital networks across São Paulo and Rio de Janeiro metropolitan corridors where ANVISA electrical safety certification requirements extend approval timelines for non-local manufacturers. Target laser-based flexible ureteroscopy workflows in underpenetrated urology departments, penetrating through disposable access sheath bundling strategies that mirror established conglomerate ecosystem plays.
For Investors and Strategic Acquirers: Re-rating potential sits with electromagnetic heritage specialists possessing regulatory infrastructure moats given EU MDR extended notified body review timelines filtering competitive entry. Long-term viability favors OEMs with embedded software capabilities enabling preemptive maintenance scheduling that locks in recurring revenue streams. The signal to watch is reimbursement parity convergence between inpatient and ambulatory stone procedure coding across German and Japanese markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription | Embedded firmware analytics preempt tube degradation, securing multi-year service contracts with German university hospitals. |
| EU MDR Regulatory Infrastructure | Extended notified body review timelines filter marginal competitors, consolidating tender participation around established OEMs. |
| Laser Platform Integration | Holmium:YAG systems with suction-irrigation channels capture ambulatory surgical center same-day stone treatment protocols. |
| Disposable Sheath Bundling | Access sheath attach rates extend urology ecosystem reach beyond capital equipment transactions. |
| JIS T 0601-1 Certification | Japanese electrical safety compliance creates regulatory moats excluding non-compliant OEMs from public hospital tenders. |
Research Methodology
FDA 510(k) premarket notification filings, EU MDR technical documentation databases, and Japanese PMDA approval records formed the secondary backbone, cross-referenced with primary interviews involving hospital purchasing committee chairs, biomedical engineering directors, urology department heads, and GPO contracts managers. Bottom-up triangulation across electromagnetic and laser lithotripter installed base estimates combined with top-down validation against procurement database aggregates.
Historical trendline analysis of capital equipment refresh cycles and service contract attach rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include energy modality, site-of-care setting, and reimbursement pathway parity. CAGRs derived from equipment shipment trajectories and disposable consumption patterns, incorporating acoustic output characterization protocol streamlining and ambulatory surgical center certification velocity as lithotripsy-specific forecast inputs.
The model holds under stable regulatory pathway timelines and reimbursement coding parity; deviation in EU MDR notified body capacity constraints or Brazilian ANVISA electrical safety certification delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transportable Ventilator Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Smart Lenses Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Injection Practice Pad Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Snare Devices Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Global Vitreoretinal Surgery Devices Market