
 Elderly and Disabled Assistive Devices Market | 2026-2036
Elderly and Disabled Assistive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Elderly and Disabled Assistive Devices Market Intelligence
Buyer concentration among hospital purchasing networks and large rehabilitation chains is hardening, pressuring smaller distributors to consolidate or exit. Invacare Corporation leverages its vertical manufacturing footprint to control costs across wheelchair and respiratory portfolios. Sunrise Medical anchors European demand through specialized seating and custom mobility configurations. Sonova Group dominates hearing aid technology leadership with sustained R&D allocation toward rechargeable and AI-driven sound processing platforms.
Elderly and disabled assistive devices comprise mechanical, electromechanical, and digital apparatus engineered to restore, augment, or substitute impaired sensory, motor, or cognitive function, typically incorporating aluminum or carbon-fiber frames, lithium-ion power systems, and Class II medical-grade electronics. Their primary commercial purpose centers on enabling independent living, reducing caregiver burden, and preventing secondary injury or institutionalization. Mobility scooters and hearing aids command the deepest installed bases and most mature reimbursement pathways, while smart home devices and wearable monitors represent the fastest-expanding margin pools as technology shifts from analog to connected care ecosystems. Voice assistants and navigation aids attract venture funding but face fragmented payer acceptance.
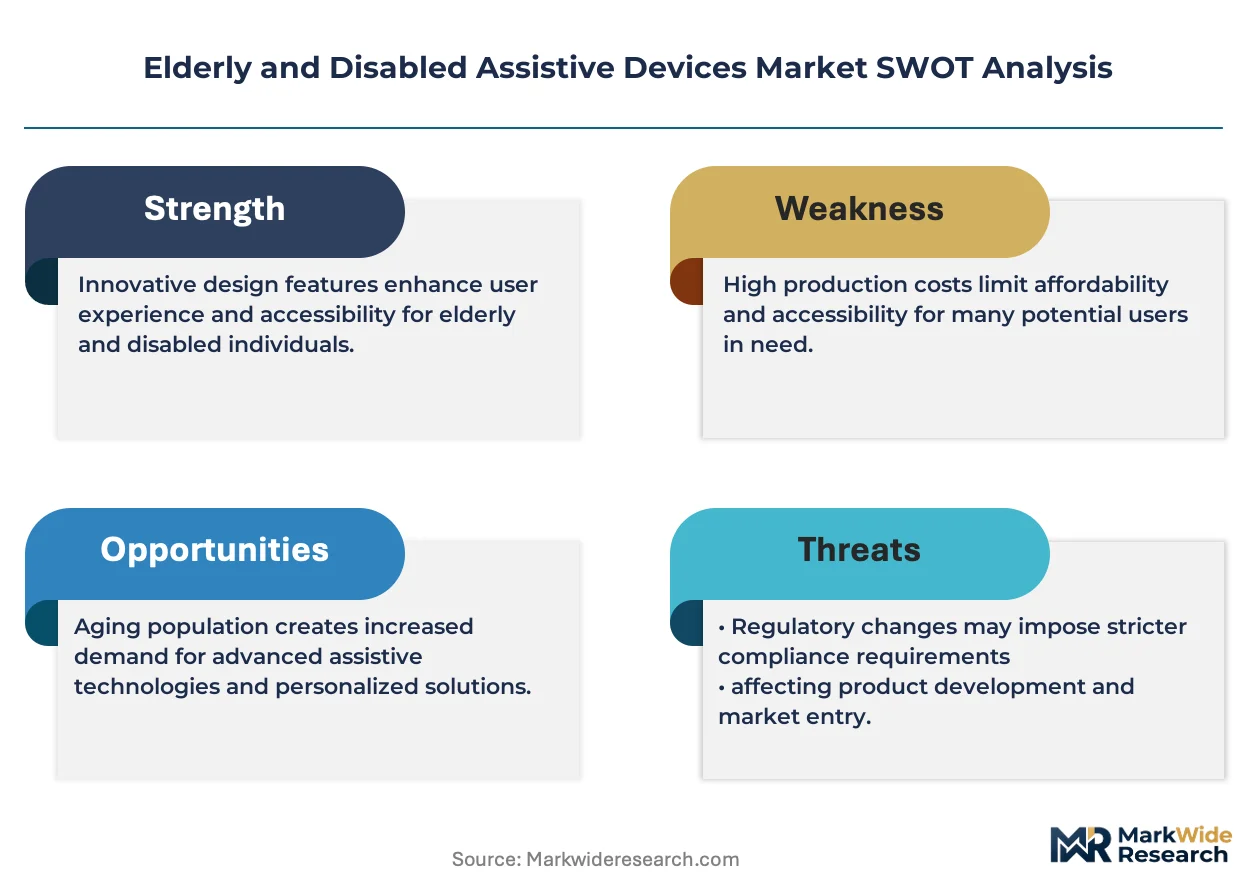
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and market access barriers for powered mobility and implantable hearing solutions. Japan's PMDA and METI standards add distinct electromagnetic compatibility and localized interface requirements that fragment certification costs for multinational suppliers. Stakeholders must monitor reimbursement rate negotiations between Medicare, statutory health insurers, and national health services, as these directly determine affordability thresholds and volume elasticity across patient segments.
Market Dynamics
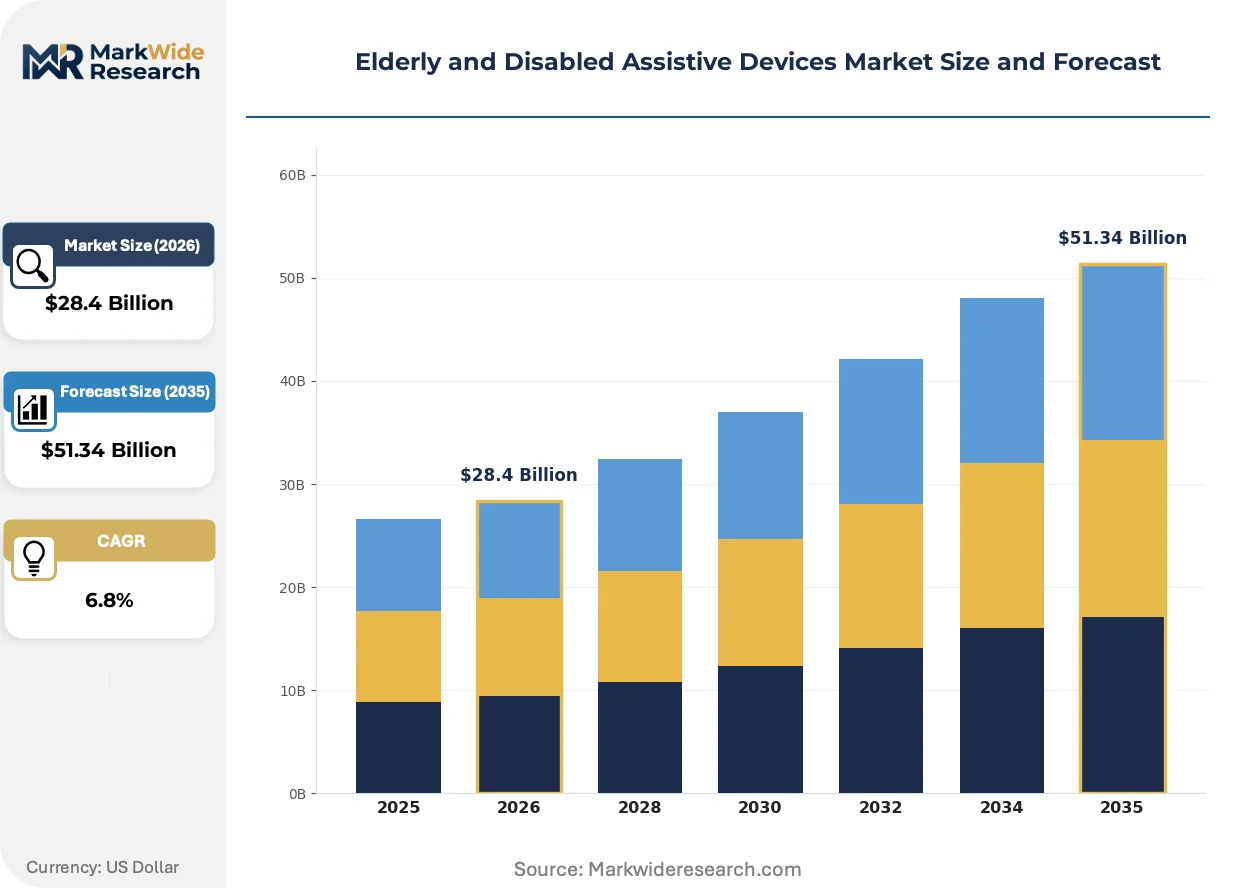
Reimbursement rate compression from Medicare and statutory health insurers is forcing manufacturers to absorb margin erosion while accelerating R&D cycles for connected-device differentiation. This structural pressure reshapes competitive positioning across powered mobility and hearing aid portfolios.
Growth Catalysts
- Japan's Silver Human Resource Centers:Municipal employment programs for retirees expand disposable income for sensory aids among the 75-plus demographic. Local governments subsidize hearing aid purchases through METI-coordinated voucher schemes.
- EU Medical Device Regulation (MDR):Harmonized CE marking pathways accelerate cross-border commercialization for German and Dutch wheelchair manufacturers. Centralized notified body oversight reduces redundant certification costs.
- Lithium-silicon battery chemistry:Energy density gains extend powered scooter range thresholds above 40 kilometers per charge. OEMs redesign chassis architectures around compact powerpack footprints.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependency for brushless drive motors exposes procurement to Chinese export quota volatility. Alternative ferrite formulations sacrifice torque density.
- FDA 510(k) backlog:Pre-market notification delays for novel hearing aid algorithms stretch submission-to-clearance timelines. Smaller developers exhaust runway awaiting determinations.
- Manual wheelchair substitution:Ultralight carbon-fiber frames priced below powered alternatives capture ambulatory users with residual upper-body function. Electromechanical premium positioning erodes at the margin.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives attract component manufacturing for hearing aid assembly. Duty exemptions on imported sub-assemblies reduce landed cost structures.
- Voice-first smart home integration:Assistive environmental controls converging with Alexa and Google Home ecosystems open retrofit markets. Aging-in-place renovations incorporate hands-free automation.
- Germany's Pflegeversicherung expansion:Long-term care insurance benefit increases for home-based assistive technology widen addressable patient pools. Reimbursement parity with institutional care redirects procurement.
Industry Challenges
- Biomedical engineering talent scarcity:Mechatronics specialists capable of integrating Class II electronics with orthopedic mechanical systems command premium compensation. Workforce development lags device complexity curves.
- ISO 13485 audit compression:Quality management system recertification cycles strain documentation resources as MDR transition overlaps with FDA QSR harmonization. Dual-track compliance consumes management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elderly and Disabled Assistive Devices Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Scooters, Wheelchairs, Hearing Aids, Bath Chairs Technology: Smart Home Devices, Wearable Monitors, Voice Assistants, Navigation Aids End User: Seniors, Physically Challenged, Hospitals, Rehabilitation Centers Distribution Channel: Online Retail, Specialty Stores, Medical Supply Outlets, Direct Sales |
| Companies Covered | Invacare Corporation, Sunrise Medical, Pride Mobility Products Corp., Sonova Group, Drive DeVilbiss Healthcare, Demant A/S, Starkey Laboratories, Inc., GN Hearing A/S, Carex Health Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elderly and Disabled Assistive Devices Market Strategic Shifts & Innovations
Digital signal processing architectures are migrating toward edge-computing platforms, compressing latency thresholds for real-time sensory augmentation. This hardware shift enables new form factors and battery trade-offs across hearing and mobility portfolios.
Deep neural network noise suppression is converging with rechargeable zinc-air battery chemistry in premium hearing aid platforms. Audiologist networks in Germany and the United States are fitting these configurations at replacement-cycle intervals below traditional five-year baselines. The technology compression is collapsing premium-mid-tier performance gaps and pressuring legacy analog amplifier inventories.
EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up data for implantable hearing solutions. Notified bodies in the Netherlands and Germany are rejecting submissions lacking real-world evidence protocols. Manufacturers are restructuring quality organizations around proactive vigilance systems rather than reactive complaint handling.
Hospital purchasing networks are consolidating assistive device procurement under centralized value-analysis committees, displacing individual clinician preference. Large rehabilitation chains in the United States negotiate enterprise pricing for wheelchair and seating portfolios. This concentration shifts vendor relationships toward long-term service agreements with outcome metrics.
Elderly and Disabled Assistive Devices Market Segmentation
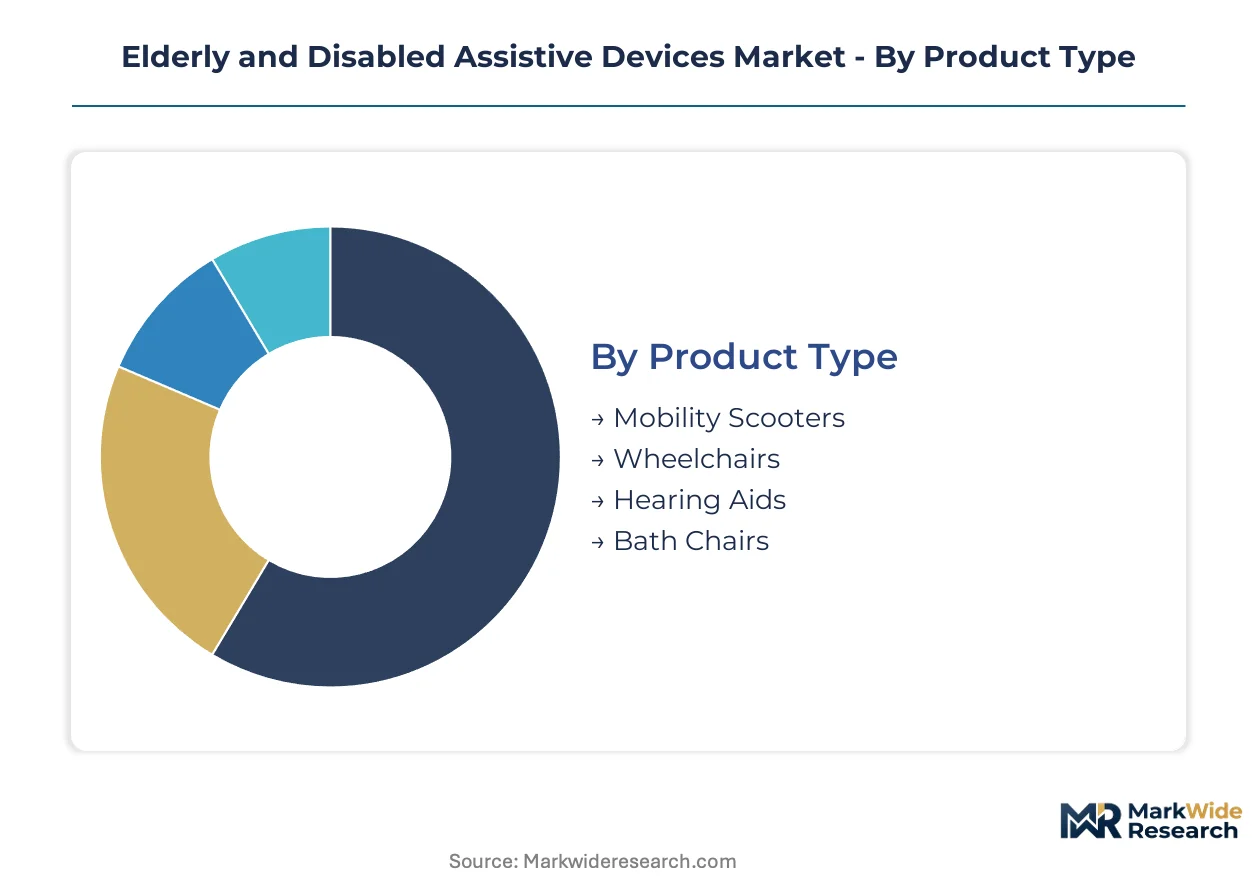
Assistive device segmentation reveals divergent margin structures across mechanical hardware and connected electronics. Product type and technology splits expose which categories absorb R&D investment versus which sustain volume through established reimbursement channels.
Product Type:
Volume concentrates in powered mobility and sensory correction devices, while premium positioning clusters around lightweight materials and custom configuration capabilities.
- Mobility Scooters:Three- and four-wheeled electromechanical platforms with tiller steering and lithium-ion powertrains. Demand concentrates in the United States and Germany where Medicare and statutory health insurers cover Class II medical-grade configurations for outdoor ambulation.
- Wheelchairs:Manual and powered frames employing aluminum or carbon-fiber construction with modular seating systems. Rehabilitation centers in Japan and the United States drive specification for pressure-mapping and tilt-in-space features that prevent secondary injury.
- Hearing Aids:Behind-the-ear and in-the-canal devices with digital signal processing and rechargeable power systems. METI voucher schemes in Japan and FDA 510(k) pathways in the United States shape commercial access for sensorineural amplification.
- Bath Chairs:Height-adjustable seating with corrosion-resistant frames for wet-environment safety. Home healthcare agencies specify these for aging-in-place bathroom modifications.
Mature deployment sits with Wheelchairs. Newer deployment is concentrated in Mobility Scooters.
Technology:
Application logic separates acute monitoring from environmental augmentation, with reimbursement gaps favoring out-of-pocket purchase for non-medical-grade connectivity.
- Smart Home Devices:Environmental control systems integrating lighting, climate, and security through centralized hubs. Voice-first interfaces from Alexa and Google Home ecosystems are gaining share fastest among aging-in-place renovations in the United States and Germany.
- Wearable Monitors:Biometric sensors tracking fall risk, cardiac rhythm, and medication adherence through wrist-worn or pendant form factors. Hospital discharge planners in Japan and the United States prescribe these for post-acute monitoring.
- Voice Assistants:Hands-free command interfaces for device control and emergency communication. Fragmented payer acceptance limits penetration to private-pay home automation markets.
- Navigation Aids:GPS-enabled guidance systems for visually impaired pedestrians. Municipal transit authorities in Germany pilot these for public infrastructure integration.
Established integration sits with Wearable Monitors. Experimental deployment clusters in Navigation Aids.
End User:
Customer type determines procurement authority, with institutional buyers negotiating enterprise pricing against individual patient segments reliant on reimbursement verification.
- Seniors:Adults aged 65 and older with age-related sensory, motor, or cognitive decline. Japan's Silver Human Resource Centers and Medicare eligibility in the United States define volume concentration for independent living aids.
- Physically Challenged:Individuals with congenital or acquired mobility impairments requiring permanent assistive configuration. German Pflegeversicherung and Japanese long-term care insurance expand addressable pools for home-based technology.
- Hospitals:Acute care facilities provisioning short-term mobility and sensory support for discharge planning. Centralized value-analysis committees in the United States consolidate wheelchair and seating procurement.
- Rehabilitation Centers:Outpatient and residential facilities delivering occupational and physical therapy. Specialized seating clinics in Germany and the Netherlands drive custom mobility specifications.
Institutional procurement dominates Hospitals. Consumer-directed purchasing is expanding fastest among Seniors.
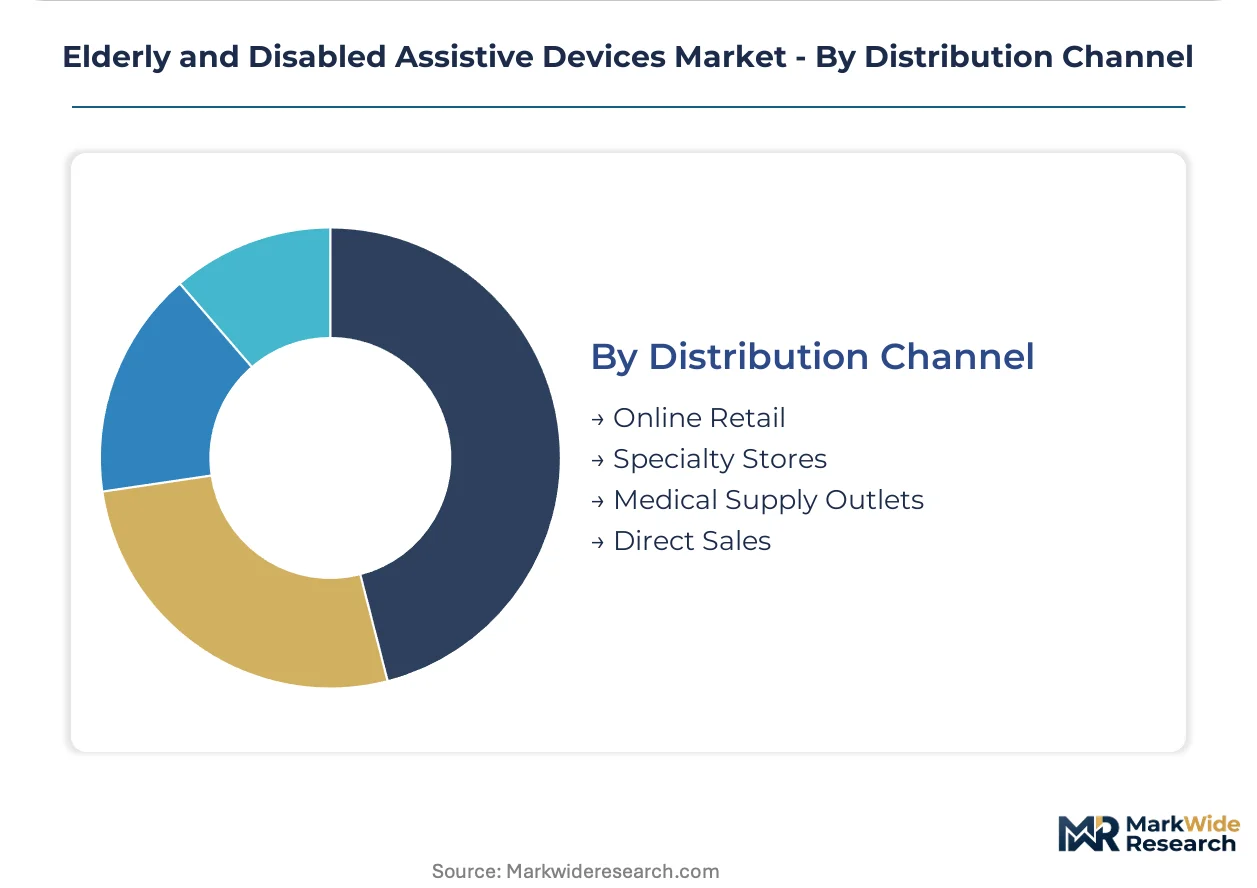
Distribution Channel:
Channel selection tracks product complexity and fitting requirements, with high-touch categories resisting pure digital migration.
- Online Retail:E-commerce platforms for standardized accessories and replacement parts. Amazon and specialized medical marketplaces capture bath chair and mobility scooter battery sales in the United States and Germany.
- Specialty Stores:Brick-and-mortar audiology and mobility showrooms with certified fitting services. Audiologist networks in Germany and the United States maintain channel control for programmable hearing aid dispensing.
- Medical Supply Outlets:Durable medical equipment dealers handling insurance documentation and delivery. Medicare competitive bidding in the United States compresses margins for wheelchair and respiratory product distribution.
- Direct Sales:Manufacturer-employed representatives for complex custom configurations. Sunrise Medical and Invacare deploy direct teams for rehabilitation center and hospital contract negotiation.
Traditional volume sits with Medical Supply Outlets. Channel shift is steepest toward Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where public reimbursement programs and aging demographics sustain volume leadership for mobility and sensory aids.
United States
Medicare competitive bidding and aging-in-place policies drive procurement of powered wheelchairs and hearing aids through hospital purchasing networks. FDA 510(k) clearance requirements shape product development timelines for Class II medical-grade electromechanical devices. Rehabilitation chains in the Midwest and Southeast negotiate enterprise pricing for custom seating configurations.
Germany
Pflegeversicherung expansion widens reimbursement pools for home-based assistive technology among the 75-plus demographic. EU Medical Device Regulation harmonizes CE marking pathways for wheelchair manufacturers across Baden-Württemberg and North Rhine-Westphalia. Specialized seating clinics in the Ruhr industrial region drive custom mobility specifications for long-term care patients.
Japan
Silver Human Resource Centers expand disposable income for sensory aids through METI-coordinated voucher schemes. PMDA electromagnetic compatibility standards fragment certification costs for powered mobility devices targeting the Kanto and Kansai metropolitan areas. Local governments in Osaka and Nagoya subsidize hearing aid purchases for retirees.
United Kingdom
National Health Service procurement frameworks centralize wheelchair and respiratory product distribution across England and Scotland. MHRA post-market surveillance requirements align with EU MDR transition timelines for implantable hearing solutions. Rehabilitation centers in Greater Manchester and the West Midlands specify pressure-mapping seating for pressure ulcer prevention.
India
Production-linked incentive schemes attract component manufacturing for hearing aid assembly in Maharashtra and Gujarat. CDSCO medical device rules create registration pathways for imported electromechanical mobility products. Duty exemptions on lithium-ion battery sub-assemblies reduce landed cost structures for powered scooter OEMs in the Delhi-NCR cluster.
Elderly and Disabled Assistive Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue connected-device differentiation and voice-first smart home integration. The vendor base organizes around three archetypes: diversified medical equipment conglomerates with vertical manufacturing footprints, specialized seating and mobility configurators with regional fabrication depth, and hearing technology specialists with sustained R&D allocation toward digital signal processing platforms. Dominant competitive moves include backward integration into lithium-ion powertrain components and strategic partnerships with audiologist networks for programmable device fitting.
Within the diversified equipment tier, Invacare Corporation and Drive DeVilbiss Healthcare exemplify scale-driven manufacturers with rehabilitation portfolio breadth. Sonova Group and Demant A/S occupy positions among hearing technology specialists, anchoring premium-tier digital amplification development. Sunrise Medical represents the specialized mobility configurator archetype, with European fabrication depth in custom seating systems.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical |
| Pride Mobility Products Corp. |
| Sonova Group |
| Drive DeVilbiss Healthcare |
| Demant A/S |
| Starkey Laboratories, Inc. |
| GN Hearing A/S |
| Carex Health Brands |
| Others |
Cost & Logistics Intelligence
Medicare competitive bidding and statutory health insurer rate negotiations in the United States and Germany are compressing reimbursement floors for powered wheelchairs and hearing aids, forcing manufacturers to absorb margin erosion through lithium-ion battery sourcing consolidation and aluminum frame fabrication automation. This demand-side pressure reshapes supplier relationships toward long-term component offtake agreements that lock in cost predictability.
Pricing Analysis
Volume concentrates in standard-tier manual wheelchairs and basic behind-the-ear hearing aids where Medicare and Pflegeversicherung reimbursement ceilings cap realized prices, while margins pool in premium custom seating configurations and AI-driven digital amplification platforms. Three-tier pricing structure across premium, standard, and economy levels separates programmable devices with audiologist fitting networks from direct-to-consumer alternatives. Cost compression in the standard tier is intensifying because hospital purchasing networks consolidate procurement under value-analysis committees. Home healthcare agencies and individual seniors exhibit highest price sensitivity, whereas rehabilitation centers and specialized seating clinics demonstrate lowest sensitivity due to outcome-based specification requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for lithium-ion powertrain components, while audiology networks and medical supply outlets distribute finished hearing aids and wheelchairs to end users. Manufacturing concentration centers on China for rare earth magnet processing, Taiwan for Class II medical-grade electronics, and Germany for precision aluminum extrusion. The supply chain draws from neodymium for brushless drive motors, lithium-silicon cells for energy density gains, and carbon-fiber prepreg for ultralight frame construction. Single-source vulnerability in Chinese rare earth export quotas exposes procurement to torque density trade-offs when ferrite alternatives substitute. Distribution runs through hospital purchasing networks, GPO contracts, and direct sales teams for custom configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical engineering talent scarcity constrains Class II electronics integration with orthopedic mechanical systems, propping pricing for mechatronics-capable suppliers while limiting competitive entry. This capacity bottleneck sustains margin premiums for vertically integrated incumbents.
For Market Incumbents: Hedge against reimbursement compression by backward integration into lithium-silicon battery cell assembly and captive carbon-fiber frame fabrication. Acquire audiologist network partnerships to lock programmable hearing aid dispensing channels against direct-to-consumer entrants. Defend positioning through ISO 13485 quality management recertification ahead of EU MDR and FDA QSR harmonization deadlines. For New Entrants and Emerging Players: Launch via voice-first smart home integration partnerships with Alexa and Google Home ecosystems to capture aging-in-place renovation markets in the United States and Germany. Target India's PLI scheme for hearing aid component manufacturing to exploit duty exemptions on imported sub-assemblies. Penetrate wearable monitors for post-acute hospital discharge planning where fragmented payer acceptance creates white-space opportunity. For Investors and Strategic Acquirers: The window for entry favors specialized seating configurators with European fabrication depth and hearing technology specialists with sustained R&D allocation toward edge-computing platforms. Long-term viability hinges on reimbursement rate negotiations between Medicare, statutory health insurers, and national health services across the analysis window. Monitor FDA 510(k) clearance timelines for novel hearing aid algorithms as an inflection indicator for smaller developer runway exhaustion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 post-market surveillance requirements accelerate notified body consolidation in Germany and the Netherlands. |
| Hospital System Partnership | Centralized value-analysis committees in the United States Midwest and Southeast displace individual clinician preference with enterprise pricing. |
| Software Companion Development | Deep neural network noise suppression converges with rechargeable zinc-air chemistry to collapse premium-mid-tier performance gaps. |
| Reimbursement Strategy | Pflegeversicherung benefit expansion in Germany redirects procurement parity from institutional care toward home-based assistive technology. |
| Backward Integration | In-house production of lithium-ion powertrain components insulates against Chinese rare earth export quota volatility. |
Research Approach
Multi-period observation of Medicare competitive bidding outcomes, Pflegeversicherung reimbursement rate adjustments, and METI voucher scheme utilization anchored the trend analysis, supplemented by interviews with hospital purchasing committee directors, GPO contracts managers, biomedical engineers, audiologist network operators, and durable medical equipment dealers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, CMS Medicare claims data, and hospital procurement databases. Bottom-up patient population modeling and top-down reimbursement flow analysis enabled triangulation across data sources.
Input-output matrices mapped mobility scooter and hearing aid unit economics against lithium-silicon battery cost curves, carbon-fiber frame fabrication scales, and audiology service bundling patterns across the analysis window. Segmentation dimensions included product type, technology application, end user category, and distribution channel. CAGRs were derived from elasticity modeling against reimbursement threshold changes and aging demographic projections. Forecast inputs incorporated ISO 13485 audit cycle compression and EU MDR transition timeline assumptions.
Reimbursement rate renegotiations, rare earth export quota disruptions, and FDA 510(k) backlog resolution are the dominant revision risks that could alter volume and value trajectories. Forecasts reflect documented assumptions regarding Medicare competitive bidding continuity and statutory health insurer benefit structures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Global Keratometers Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Medical Device Tester Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Global Robotic Wheelchairs Market