
 Italy Digital Radiology Market | 2026-2036
Italy Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Digital Radiology Market Insights
Radiologist workforce availability is collapsing across Italy's public hospital system, forcing administrators toward AI-assisted diagnostic platforms that compress study interpretation times. Siemens Healthineers leverages deep learning reconstruction algorithms to reduce scan durations without sacrificing image fidelity. GE Healthcare anchors its Italian presence through extensive service networks that sustain equipment uptime in under-resourced facilities. Philips competes by integrating cloud-based PACS architectures that enable remote reading across dispersed clinical sites.
Digital radiology encompasses the acquisition, processing, storage, and distribution of medical images through detector-based systems replacing analog film, with flat-panel detectors achieving spatial resolution below 150 micrometers and direct-conversion materials like amorphous selenium eliminating light scatter. CT scanners dominate capital expenditure flows among product types, as stroke protocols and trauma triage require sub-minute whole-body acquisition. Artificial Intelligence applications in image processing represent the fastest-expanding technology segment, automating lesion detection and protocol selection to offset staffing shortfalls. Hospitals absorb the majority of procurement volume, though outpatient facilities gain share as Italy's regional health systems decentralize elective diagnostic services.
Italy's Ministry of Health enforces CE-marked conformity under the EU Medical Device Regulation (MDR), while AIFA oversees post-market surveillance of software-as-medical-device functionalities embedded in imaging platforms. The PNRR's dedicated health digitization chapter mandates interoperability standards that shape vendor selection criteria and accelerate replacement of legacy analog installations. Stakeholders must monitor how regional health agencies allocate centrally funded modernization budgets across competing infrastructure priorities.
Market Dynamics
Italy's National Recovery and Resilience Plan (PNRR) is funneling capital into hospital digitization while radiologist shortages force administrators toward AI-assisted diagnostic platforms that compress interpretation times without expanding headcount.
Growth Catalysts
- PNRR Health Digitization Mandate:Centralized funding streams require interoperability standards that accelerate replacement of legacy analog installations across regional health systems.
- AI-Enhanced Reconstruction Algorithms:Deep learning methods reduce scan durations without sacrificing spatial resolution below 150 micrometers, enabling higher throughput in tertiary centers.
- Lombardy-Veneto Procurement Concentration:Hospital networks in northern Italy generate disproportionate demand volumes where patient flows and reimbursement rates justify capital deployment.
Market Restraints
- Amorphous Selenium Supply Concentration:Direct-conversion detector materials depend on limited upstream chemical processing capacity concentrated outside the EU.
- EU MDR Certification Friction:CE-marked conformity requirements under the Medical Device Regulation extend software-as-medical-device approval timelines for embedded AI functionalities.
- Flat-Panel Detector Cost Structure:Capital intensity of detector manufacturing constrains price elasticity for mid-tier hospital buyers in southern regions.
Strategic Opportunities
- Decentralized Outpatient Networks:Regional health systems in Tuscany and Emilia-Romagna are shifting elective diagnostics from hospitals to ambulatory facilities requiring compact digital systems.
- Cloud-Native PACS Architectures:Remote reading platforms enable radiologist resource pooling across dispersed clinical sites in under-resourced provinces.
- Stroke Protocol Automation:AI-driven lesion detection for trauma triage creates white space in emergency department workflow integration.
Industry Challenges
- Radiologist Workforce Compression:Public hospital staffing shortfalls limit utilization rates of installed imaging capacity despite equipment availability.
- Legacy Analog Integration Complexity:Interoperability gaps between new digital platforms and existing hospital information systems delay deployment timelines.
- AIFA Post-Market Surveillance Burden:Ongoing software validation requirements for AI-embedded devices consume vendor regulatory affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Digital Radiology Market |
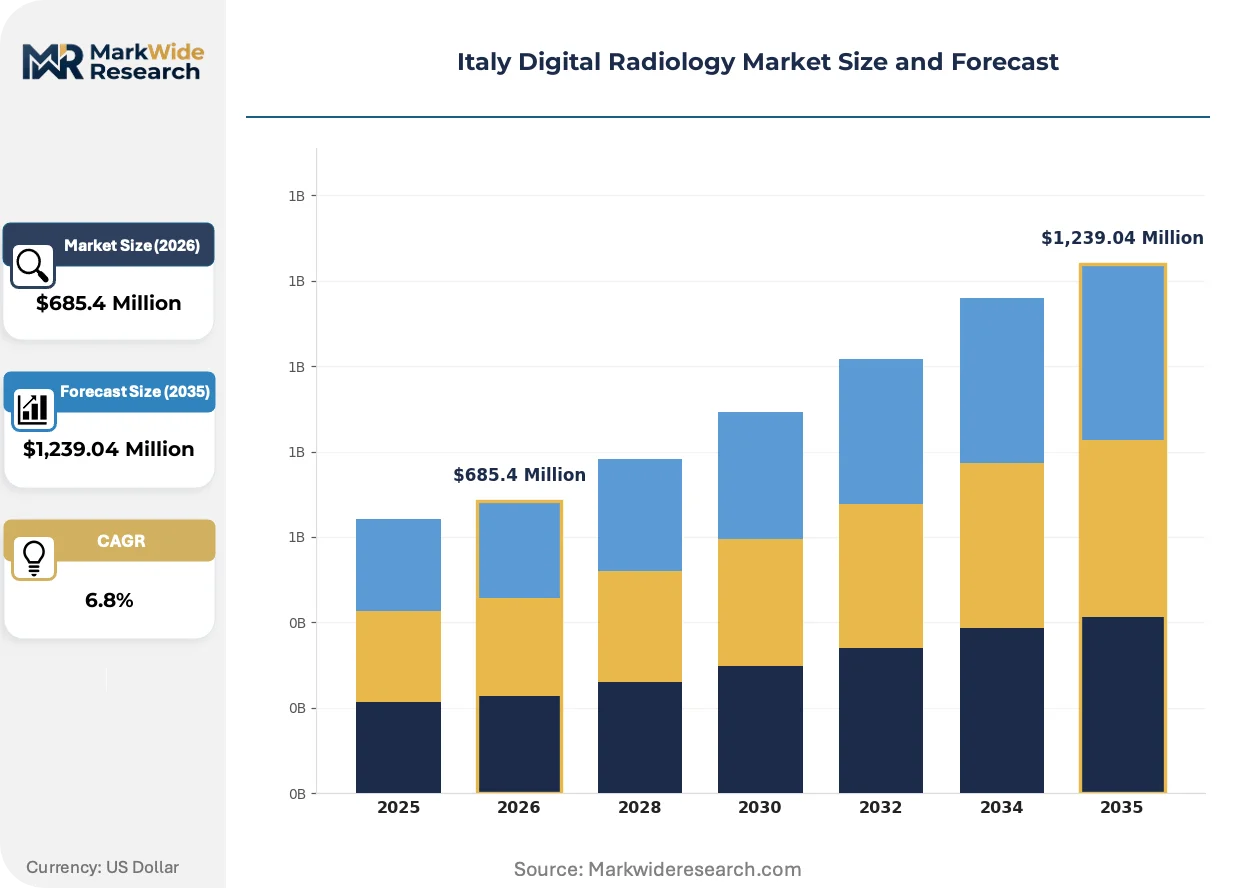
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, MRI Systems, CT Scanners, Ultrasound Equipment Technology: Image Processing, Artificial Intelligence, Cloud Storage, PACS End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Facilities Application: Oncology, Cardiovascular, Orthopedics, Neurology |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Fujifilm Holdings Corporation, Shimadzu Corporation, Carestream Health, Koninklijke Philips NV, Hologic Inc, Canon Inc, Esaote, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Digital Radiology Market Trends and Innovations
Deep learning reconstruction and cloud-based distribution architectures are compressing acquisition-to-diagnosis timelines while regulatory mandates reshape vendor compliance investments across Italian procurement channels.
Photon-counting CT detectors are supplanting energy-integrating systems in high-throughput tertiary centers. The technology discriminates tissue composition at lower radiation doses. Lombardy's university hospitals are prioritizing these platforms for oncology and cardiology protocols, compressing examination times while maintaining diagnostic yield.
MDR software classification rules are tightening oversight of AI-as-medical-device functionalities embedded in imaging platforms. Vendors must demonstrate clinical validation across intended use cases before CE marking. Stroke detection algorithms and automated lung nodule identification modules face heightened scrutiny, delaying product launches by 12-18 months.
Regional health agencies are consolidating procurement through framework agreements that unbundle equipment purchase from service contracts. Large hospital networks in Veneto negotiate multi-year managed service arrangements covering uptime guarantees and software updates. Small facilities in Calabria and Sicily lose bargaining leverage, concentrating vendor attention on northern accounts.
Italy Digital Radiology Market Segmentation
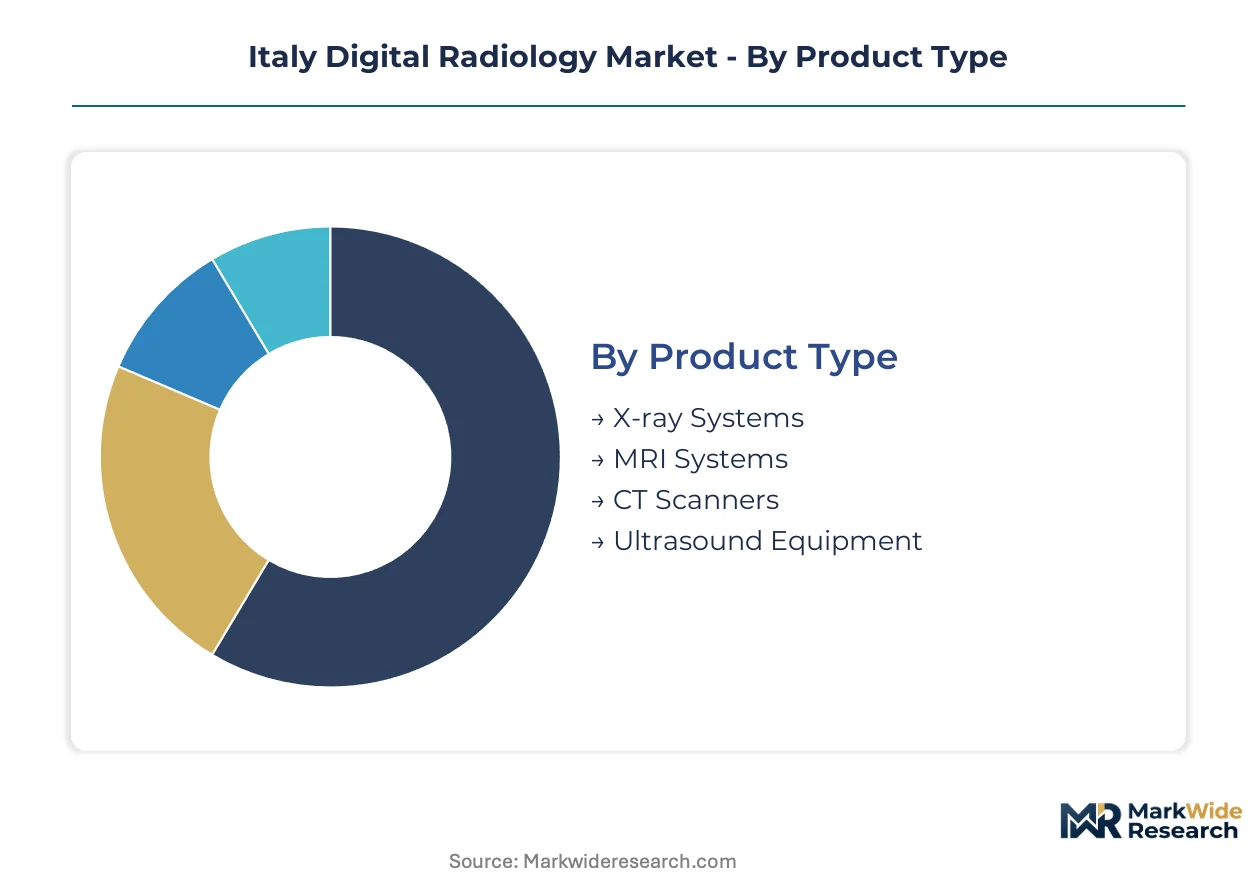
Segmentation reveals how procurement budgets fragment across hardware platforms, software layers, and clinical settings in Italy's hospital digitization wave. Understanding these splits exposes where vendors compete on specification versus service, and where public tenders concentrate purchasing power.
Product Type:
Margin pools concentrate in modalities requiring heavy infrastructure and recurring service contracts rather than portable units with limited attachment revenue.
- CT Scanners:Energy-integrating and photon-counting detector arrays enable sub-minute whole-body acquisition for stroke protocols and trauma triage. Lombardy's university hospitals and Veneto's regional networks absorb the bulk of procurement volume, driven by emergency department throughput requirements and PNRR-funded replacement cycles.
- X-ray Systems:Flat-panel detectors with direct-conversion amorphous selenium achieve spatial resolution below 150 micrometers while eliminating light scatter. Demand clusters in northern Italy's tertiary centers where high patient volumes justify capital deployment against compressed reimbursement timelines.
- MRI Systems:Superconducting magnet platforms with integrated coil arrays for neurovascular and musculoskeletal protocols.
- Ultrasound Equipment:Compact cart-based and handheld systems for point-of-care deployment in decentralized outpatient networks.
The dominant share belongs to CT Scanners, while X-ray Systems is closing the gap fastest through AI-enhanced reconstruction upgrades.
Technology:
Revenue attachment rates diverge sharply between one-time software licenses and recurring cloud infrastructure fees.
- Artificial Intelligence:Deep learning algorithms automate lesion detection, protocol selection, and image reconstruction to offset radiologist staffing shortfalls. Stroke detection and lung nodule identification modules face extended CE-marking timelines under EU MDR software classification rules, compressing vendor profit windows during regulatory delays.
- PACS:Picture archiving and communication systems integrate with hospital information systems to manage image storage, retrieval, and distribution workflows. Tuscany and Emilia-Romagna's regional health agencies prioritize cloud-native architectures that enable remote reading across dispersed clinical sites.
- Image Processing:Reconstruction algorithms and post-acquisition enhancement tools for noise reduction and contrast optimization.
- Cloud Storage:Scalable infrastructure for long-term image retention and cross-facility accessibility under interoperability mandates.
Artificial Intelligence commands the steepest expansion trajectory as workforce compression forces automation adoption, though PACS generates more predictable recurring revenue.
End User:
Procurement authority and payment security vary dramatically across Italy's fragmented regional health system structures.
- Hospitals:Tertiary and secondary acute care facilities with 24/7 emergency departments and high-throughput imaging departments. Lombardy and Veneto hospital networks leverage framework agreements to unbundle equipment purchase from multi-year managed service contracts covering uptime guarantees.
- Outpatient Facilities:Ambulatory diagnostic centers and private clinics performing elective imaging outside hospital walls. Regional decentralization policies in central Italy are shifting volume toward these sites, creating demand for compact digital systems with simplified operator interfaces.
- Diagnostic Centers:Specialized imaging facilities focused on high-volume screening and elective procedures.
- Research Institutes:University hospitals and clinical trial sites requiring advanced protocols for investigational applications.
Hospitals retain the dominant installed base, while Outpatient Facilities is gaining share fastest as regional health systems decentralize elective services.
Application:
Reimbursement intensity and examination complexity create divergent equipment specification requirements across clinical domains.
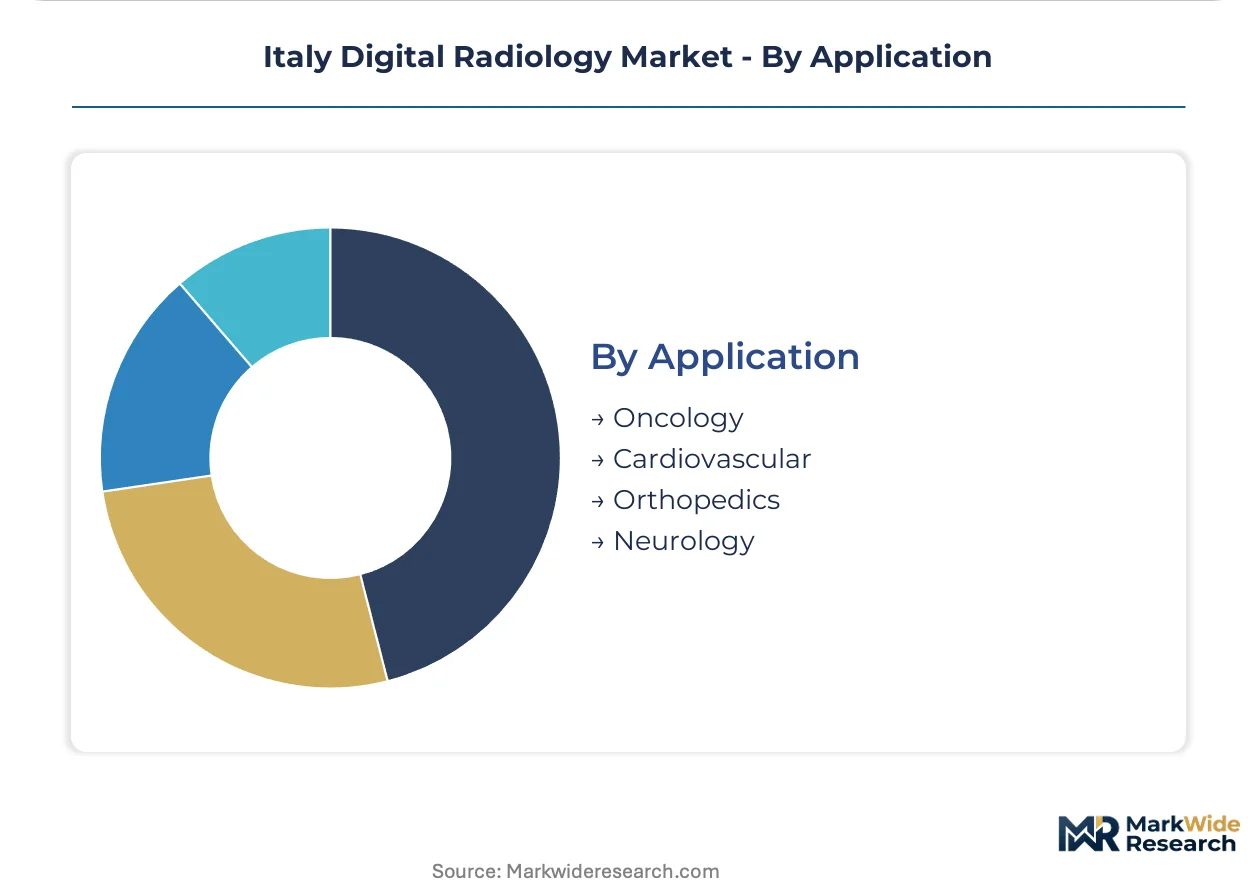
- Oncology:Staging and treatment response monitoring drives demand for multimodal imaging with quantitative biomarker extraction. Lombardy's IRCCS cancer institutes prioritize photon-counting CT for tissue characterization at reduced radiation doses, compressing examination times while maintaining diagnostic yield.
- Cardiovascular:Coronary CT angiography and cardiac MRI for structural and functional assessment. Northern Italy's high-prevalence cardiovascular disease corridors concentrate procurement of dual-source CT platforms capable of motion-free coronary imaging.
- Orthopedics:Musculoskeletal trauma, joint replacement planning, and sports medicine applications.
- Neurology:Stroke triage, dementia workup, and functional brain imaging protocols.
Oncology holds the dominant procedure volume, while Cardiovascular is climbing the fastest as population aging expands coronary assessment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital radiology deployment across Italy's regions diverges sharply between northern industrial corridors and southern provinces, with consumption patterns driven by hospital network density, regional health agency budgets, and proximity to university research centers rather than uniform national procurement.
Lombardy
Lombardy's IRCCS cancer institutes and university hospitals absorb the highest concentration of photon-counting CT procurement. The PNRR health digitization chapter mandates interoperability standards that accelerate replacement of legacy analog installations across Milan's hospital networks. Siemens Healthineers and GE Healthcare anchor extensive service operations in the region to sustain equipment uptime in high-throughput tertiary centers.
Veneto
Hospital networks in Veneto negotiate multi-year managed service arrangements covering uptime guarantees and software updates through framework agreements. Regional health agencies here consolidate procurement authority, unbundling equipment purchase from service contracts to maximize bargaining leverage. Verona and Padua medical centers prioritize AI-enhanced reconstruction platforms to offset radiologist staffing shortfalls.
Emilia-Romagna
Emilia-Romagna's regional health system decentralizes elective diagnostic services toward ambulatory facilities, creating demand for compact digital systems with simplified operator interfaces. Bologna's university hospital complex drives adoption of cloud-native PACS architectures enabling remote reading across dispersed clinical sites. Tuscany and Emilia-Romagna jointly prioritize interoperability standards under PNRR funding allocations.
Tuscany
Tuscany's regional health agencies channel public investment toward hospital digitization with explicit mandates for cross-facility image accessibility. Florence's care networks deploy cloud-based distribution architectures to pool radiologist resources across provincial hospitals. Compact digital X-ray systems gain traction in outpatient facilities as elective diagnostics shift from hospital walls.
Piedmont
Piedmont's industrial base supports a dense network of private diagnostic centers requiring high-resolution imaging for occupational health screening. Turin's university hospitals pilot stroke protocol automation integrating AI-driven lesion detection into emergency department workflows. Regional procurement patterns favor vendors offering extended service coverage across the Alpine corridor.
Italy Digital Radiology Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through bundled hardware-software-service offerings while mid-tier players compete on modular upgrades and regional service density. Siemens Healthineers, GE Healthcare, and Philips anchor the integrated segment with deep installed bases and multi-year managed service contracts. Specialist vendors concentrate on detector technology, AI-embedded reconstruction modules, or compact outpatient systems. Dominant competitive moves include framework agreement consolidation by regional health agencies and unbundling of equipment purchase from service contracts to optimize total cost of ownership.
Within the integrated systems tier, Siemens Healthineers AG and GE Healthcare exemplify vendors with extensive Italian service networks sustaining equipment uptime in under-resourced facilities. Koninklijke Philips NV occupies a position emphasizing cloud-native PACS architectures that enable remote reading across dispersed clinical sites. These three anchors represent divergent strategic bets on whether procurement authority will continue centralizing through regional framework agreements or fragment toward hospital-level technology selection.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| Carestream Health |
| Koninklijke Philips NV |
| Hologic Inc |
| Canon Inc |
| Esaote |
| Others |
Pricing and Supply Chain Analysis
EU MDR software classification rules gate both vendor qualification and price differentiation simultaneously, extending CE-marking timelines for AI-embedded imaging platforms while compressing profit windows during regulatory delays. Northern Italy's hospital networks exploit framework agreements to unbundle equipment purchase from service contracts, forcing vendors to compete on total cost of ownership rather than upfront capital expenditure alone.
Pricing Analysis
Long-term managed service arrangements dominate procurement in Lombardy and Veneto, where regional health agencies negotiate multi-year contracts covering uptime guarantees and software updates. Price differentiation stems from after-sales service bundling and detector technology tier—photon-counting CT platforms command premium positioning against energy-integrating systems. Cost compression in mid-tier X-ray systems intensifies as southern regions face capital constraints. Outpatient facilities in central Italy exhibit highest price sensitivity, while tertiary cancer institutes in Milan show lowest sensitivity due to PNRR-funded replacement cycles.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for amorphous selenium and flat-panel detector substrates sourced from East Asian chemical processors. Manufacturing concentrates in Germany, Japan, and South Korea for high-end CT gantries and superconducting magnet assemblies. Raw material dependencies include rare earth elements for MRI coils, selenium compounds for direct-conversion detectors, and precision ceramics for X-ray tube housings. Single-source vulnerability in amorphous selenium chemical processing outside the EU creates supply chain risk. Distribution runs through authorized service networks rather than direct hospital relationships, with Siemens Healthineers and GE Healthcare maintaining dense Italian technician pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native PACS vendors and AI-as-a-service platforms that displace traditional hardware-software bundles with modular, pay-per-use alternatives.
For Market Incumbents: Shield installed base erosion by deepening service contract attachment rates in under-resourced southern provinces where technician scarcity creates switching costs. Prioritize MDR certification investment for stroke detection algorithms to close regulatory gaps against emerging AI specialists. Vertical integration into cloud infrastructure reduces dependency on third-party hosting providers. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or Netherlands accelerates market entry ahead of MDR compliance backlogs. Target compact digital X-ray deployments in Tuscany and Emilia-Romagna ambulatory networks where regional decentralization creates white space. Go-to-market through GPO contracts with central Italian regional health agencies bypasses direct hospital sales complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native PACS sub-segments as software margins displace hardware-heavy business models. Five-to-ten year viability favors vendors with recurring revenue attachment above equipment sales. Acquisition targets include AI reconstruction module specialists with MDR-cleared algorithms. Monitor AIFA post-market surveillance enforcement intensity as inflection signal for regulatory compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR software classification compliance accelerates AI-embedded platform launches in Lombardy-Veneto procurement windows. |
| Hospital System Partnership | Multi-year managed service contracts with Veneto regional networks lock out competitor equipment replacement cycles. |
| Software Companion Development | Cloud-native PACS modules enable remote reading across Tuscany's dispersed provincial hospitals. |
| Reimbursement Strategy | Alignment with PNRR interoperability mandates shapes vendor selection criteria in framework agreements. |
| Backward Integration | In-house production of detector substrates reduces exposure to East Asian chemical processing bottlenecks. |
Research Methodology
Desk research of EU Medical Device Regulation guidance documents, AIFA post-market surveillance databases, and PNRR health digitization funding allocations preceded structured interviews with hospital procurement managers, biomedical engineering directors, regional health agency technology officers, and radiology department heads. Secondary validation drew from GPO contract databases, CE marking registries, and vendor service network disclosures. Bottom-up equipment installation tracking triangulated against top-down regional health expenditure flows.
Variance decomposition across product type, technology layer, end-user setting, and clinical application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves modeling AI adoption saturation and replacement cycle timing. Forecast inputs included radiologist workforce projection models and PNRR funding disbursement schedules by region.
Underlying assumptions cover MDR regulatory timeline stability, amorphous selenium supply continuity, and PNRR health digitization chapter execution rates, with deviation risk concentrated in AIFA software validation enforcement intensity and southern region funding absorption capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Gallium-68 Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Global Cardiac Imaging Software Market
Medical Imaging
AI Surgical Video Intelligence System Market