
 AI Fetal Ultrasound View Detection Software Market | 2026-2036
AI Fetal Ultrasound View Detection Software Market Size, Share, and Industry Trends Forecast 2026-2036
AI Fetal Ultrasound View Detection Software Market Insights
Israeli AI imaging startups is rebalancing competitive dynamics in fetal ultrasound software, forcing legacy manufacturers to accelerate algorithm development. GE Healthcare leverages deep learning archives from millions of scanned pregnancies to sustain clinical validation advantages. Koninklijke Philips anchors its position through integrated hardware-software ecosystems across European and North American hospital networks. Siemens Healthineers differentiates via real-time biometric measurement engines embedded in premium imaging consoles.
AI fetal ultrasound view detection software automates anatomical plane recognition during obstetric sonography, employing convolutional neural networks trained on standardized fetal biometry datasets to identify cardiac four-chamber views, transcerebellar planes, and femur lengths within two to five seconds per frame. The technology serves primarily to reduce operator-dependent variability in prenatal screening and accelerate anomaly detection workflows in high-volume maternal care settings. Embedded solutions dominate current installations as ultrasound OEMs integrate detection algorithms directly into imaging hardware, while cloud-based platforms represent the fastest-expanding segment as telemedicine protocols and teleradiology networks demand remote analysis capabilities. Obstetrics monitoring applications command the largest share of deployed instances, though anomaly detection commands premium pricing due to liability reduction value and subspecialist referral requirements.
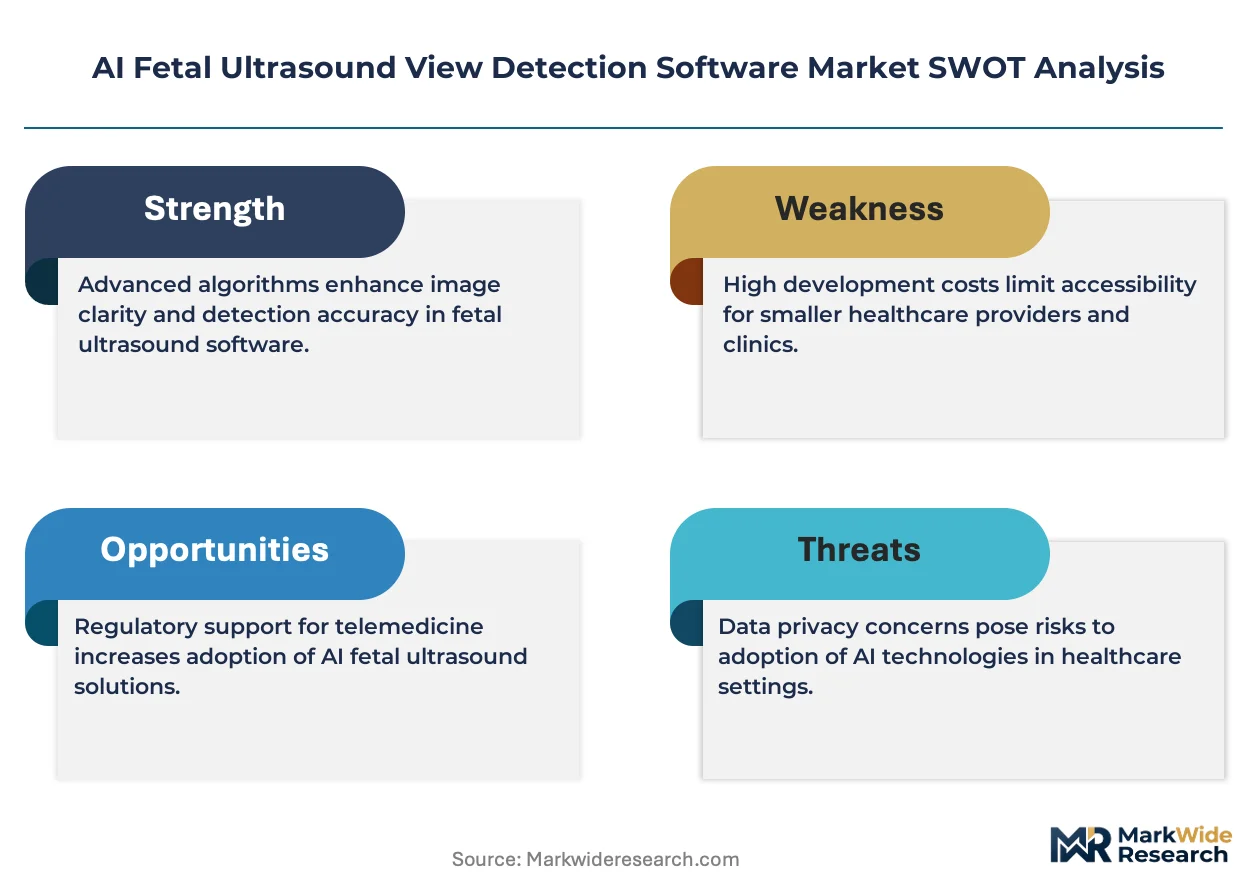
The FDA's software-as-a-medical-device framework and pre-certification pilot program determine market access timelines for algorithm updates, while the EU MDR and GDPR impose parallel clinical evidence and data governance burdens on vendors serving European maternal clinics. ISO 13485 quality management certification and IEC 62304 software lifecycle standards function as baseline procurement filters for health system tenders across developed markets. Stakeholders must weigh regulatory capital requirements against the pace of algorithm iteration as competitive differentiation increasingly depends on continuous learning from distributed clinical data.
Market Dynamics
Algorithmic standardization pressure from maternal-fetal medicine societies is compressing vendor differentiation windows, forcing continuous retraining cycles on distributed clinical datasets to maintain clearance-validated performance claims.
Growth Catalysts
- FDA Pre-Certification Pilot:Streamlined algorithm update pathways accelerate deployment of enhanced cardiac view detection models in US hospital networks.
- Convolutional Neural Network Architectures:Real-time inference capabilities on edge ultrasound hardware eliminate cloud latency for bedside screening workflows.
- European Maternal Clinic Consolidation:Multi-site health systems in Germany and France mandate AI-assisted standardization across obstetrics departments.
Market Restraints
- EU MDR Clinical Evidence Burden:Post-market surveillance requirements for software-as-a-medical-device extend validation timelines and capital lock-up periods.
- Ultrasound Hardware Oligopoly:Embedded algorithm deployment depends on licensing negotiations with three dominant imaging console manufacturers.
- Inter-Operator Variability in Ground Truth:Training dataset quality depends on subspecialist sonographer availability, creating annotation bottleneck constraints.
Strategic Opportunities
- India Tier-II City Penetration:Teleradiology networks connecting district hospitals to metropolitan maternal-fetal medicine centers create distributed AI interpretation demand.
- ISO 13485-Certified Cloud Platforms:Remote analysis capabilities unlock subscription revenue models for low-volume clinics lacking capital equipment budgets.
- GDPR-Compliant Federated Learning:Multi-institutional algorithm improvement without centralizing protected health information addresses data governance constraints.
Industry Challenges
- IEC 62304 Software Lifecycle Documentation:Continuous learning architectures conflict with locked algorithm baselines required for regulatory submission packages.
- Legacy PACS Integration Complexity:Hospital information system heterogeneity demands custom middleware development for each enterprise deployment.
- Fetal Biometry Annotation Specialist Shortage:Qualified maternal-fetal medicine subspecialists capable of ground-truth labeling command premium compensation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Fetal Ultrasound View Detection Software Market |
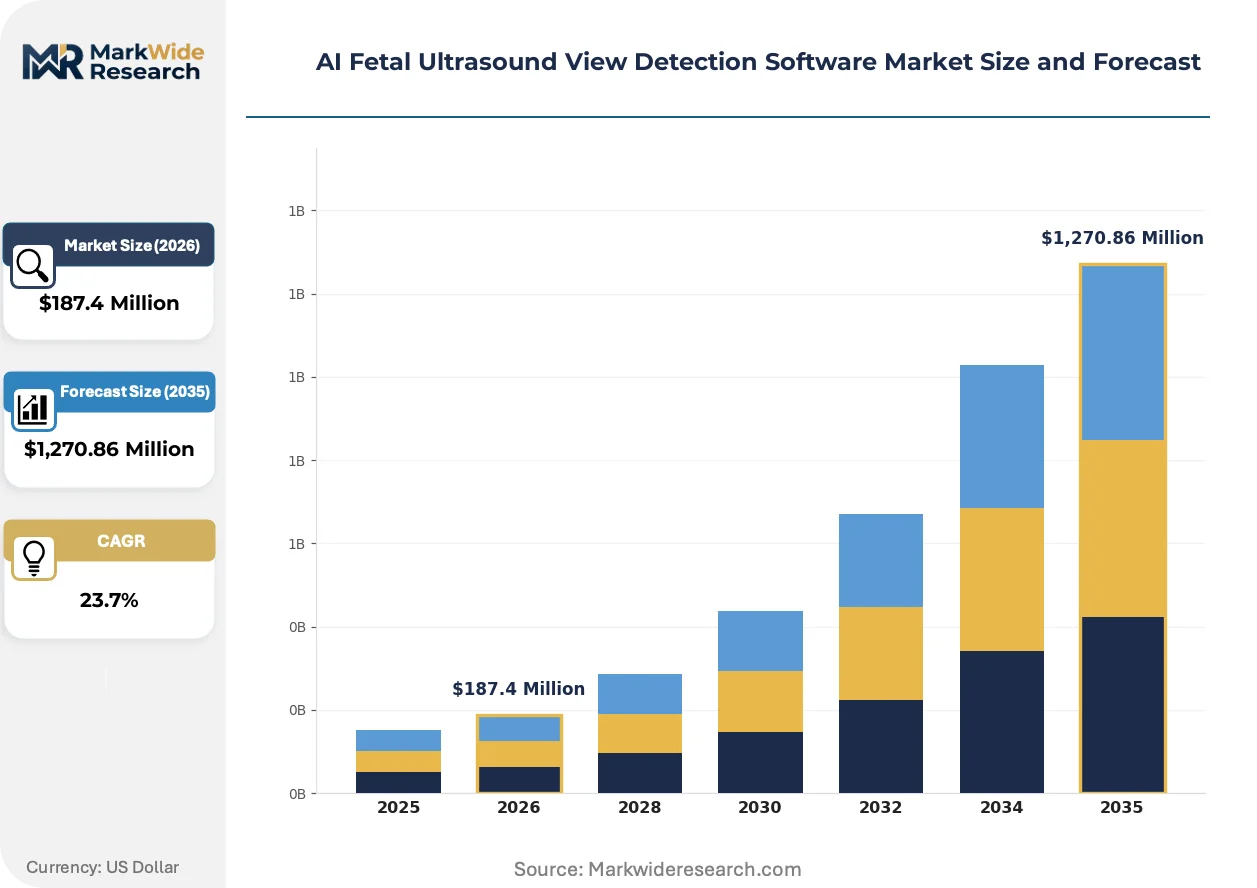
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Embedded Solution, Cloud-Based Platform, On-Premise Software Application: Obstetrics Monitoring, Prenatal Screening, Anomaly Detection, Growth Assessment, Biometric Measurement End User: Diagnostic Imaging Centers, Maternal Clinics, Research Institutions, Perinatal Care Units Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Server |
| Companies Covered | GE Healthcare, Koninklijke Philips, Siemens Healthineers, FUJIFILM, Samsung Medison, Mindray Medical, Butterfly Network, Sonio, EchoNous, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Fetal Ultrasound View Detection Software Market Trends and Innovations
Edge computing migration is redistributing computational load from centralized servers to ultrasound console processors, enabling sub-second anatomical plane recognition without network dependency.
Real-time biometric measurement engines are consolidating disparate detection tasks into unified inference pipelines. Maternal-fetal medicine departments in US academic medical centers deploy these integrated systems to compress screening examination duration. The technology is consolidating previously separate software modules into single-vendor embedded solutions.
EU AI Act risk classification rules for medical device software are reshaping conformity assessment obligations. High-risk algorithm categories trigger notified body involvement and post-market monitoring systems. Vendors serving European maternal clinics are restructuring quality management systems to accommodate these layered requirements.
Health system procurement committees now mandate ISO 13485 certification as a baseline qualification filter. Independent software vendors without manufacturing quality credentials face exclusion from enterprise tenders. This behavioral shift is most pronounced in US integrated delivery networks consolidating vendor panels.
AI Fetal Ultrasound View Detection Software Market Segmentation
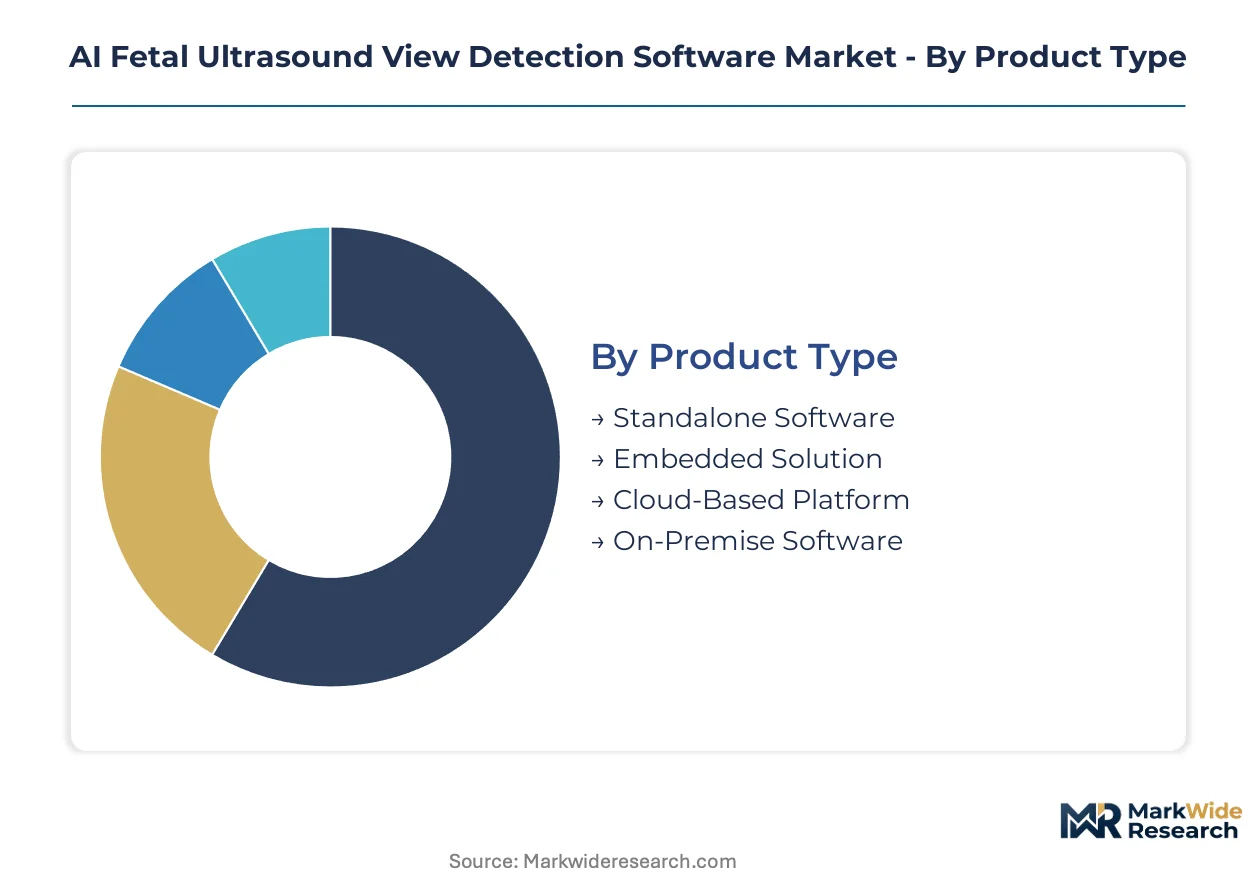
Segmentation in AI fetal ultrasound software reveals how deployment constraints and clinical workflows shape purchasing decisions. Ultrasound OEMs, maternal clinics, and teleradiology networks each prioritize different combinations of latency, integration depth, and regulatory validation.
Product Type:
Embedded solutions dominate current installations by volume, while cloud-based platforms command premium subscription pricing and faster update cycles.
- Embedded Solution:Algorithms ship pre-installed on ultrasound console firmware, eliminating separate procurement cycles and ensuring locked regulatory baselines. GE Healthcare and Philips integrate detection engines directly into high-volume maternal screening workflows across US hospital networks. Today's leader: Embedded Solution. Tomorrow's challenger: Cloud-Based Platform.
- Cloud-Based Platform:Remote inference architectures enable teleradiology interpretation across distributed clinic networks without capital equipment investment. Indian tier-II city maternal clinics and European multi-site health systems drive subscription adoption for centralized algorithm updates. Pricing scales with examination volume rather than hardware depreciation.
- Standalone Software:Discrete applications requiring separate installation on hospital workstations or PACS infrastructure.
- On-Premise Software:Local server deployments maintaining full data custody within institutional firewalls for GDPR-sensitive European installations.
Deployment modality determines update velocity and regulatory re-certification burden more than functional capability.
Application:
Obstetrics monitoring generates the highest examination volume, while anomaly detection justifies premium pricing through liability reduction and subspecialist referral requirements.
- Obstetrics Monitoring:Routine anatomical plane recognition during standard prenatal visits compresses examination duration and reduces operator-dependent variability. High-volume maternal clinics in Germany and France mandate AI-assisted standardization across departmental workflows. Today's anchor: Obstetrics Monitoring. Tomorrow's value concentrator: Anomaly Detection.
- Anomaly Detection:Cardiac four-chamber view identification and transcerebellar plane validation trigger maternal-fetal medicine subspecialist referrals. FDA pre-certification pathways for cardiac view algorithms accelerate deployment in US academic medical centers. Liability reduction value supports pricing premiums independent of hardware integration costs.
- Prenatal Screening:First and second-trimester combined screening protocols automating nuchal translucency and nasal bone measurements.
- Growth Assessment:Serial biometric tracking for fetal weight estimation and intrauterine growth restriction monitoring.
- Biometric Measurement:Automated femur length, head circumference, and abdominal circumference extraction for standardized reporting.
Clinical liability exposure and subspecialist scarcity create pricing power in detection applications that routine monitoring cannot replicate.
End User:
Procurement authority concentrates in health system IT committees for imaging centers, while maternal clinics retain discretionary software selection for screening workflows.
- Maternal Clinics:Independent obstetrics practices and hospital-based departments prioritize embedded solutions with minimal IT infrastructure requirements. US integrated delivery networks consolidating vendor panels drive ISO 13485 certification as baseline qualification filters. Today's volume leader: Maternal Clinics. Tomorrow's standard-setter: Diagnostic Imaging Centers.
- Diagnostic Imaging Centers:Multi-modality facilities require PACS-integrated AI interpretation across ultrasound, MRI, and CT workflows. Enterprise software procurement committees mandate middleware compatibility and centralized quality management systems.
- Perinatal Care Units:High-risk pregnancy centers demanding real-time biometric measurement engines with subspecialist validation protocols.
- Research Institutions:Academic medical centers contributing training data to federated learning networks in exchange for algorithm development partnerships.
End-user IT sophistication determines whether vendors compete on integration depth or standalone functionality.
Deployment:
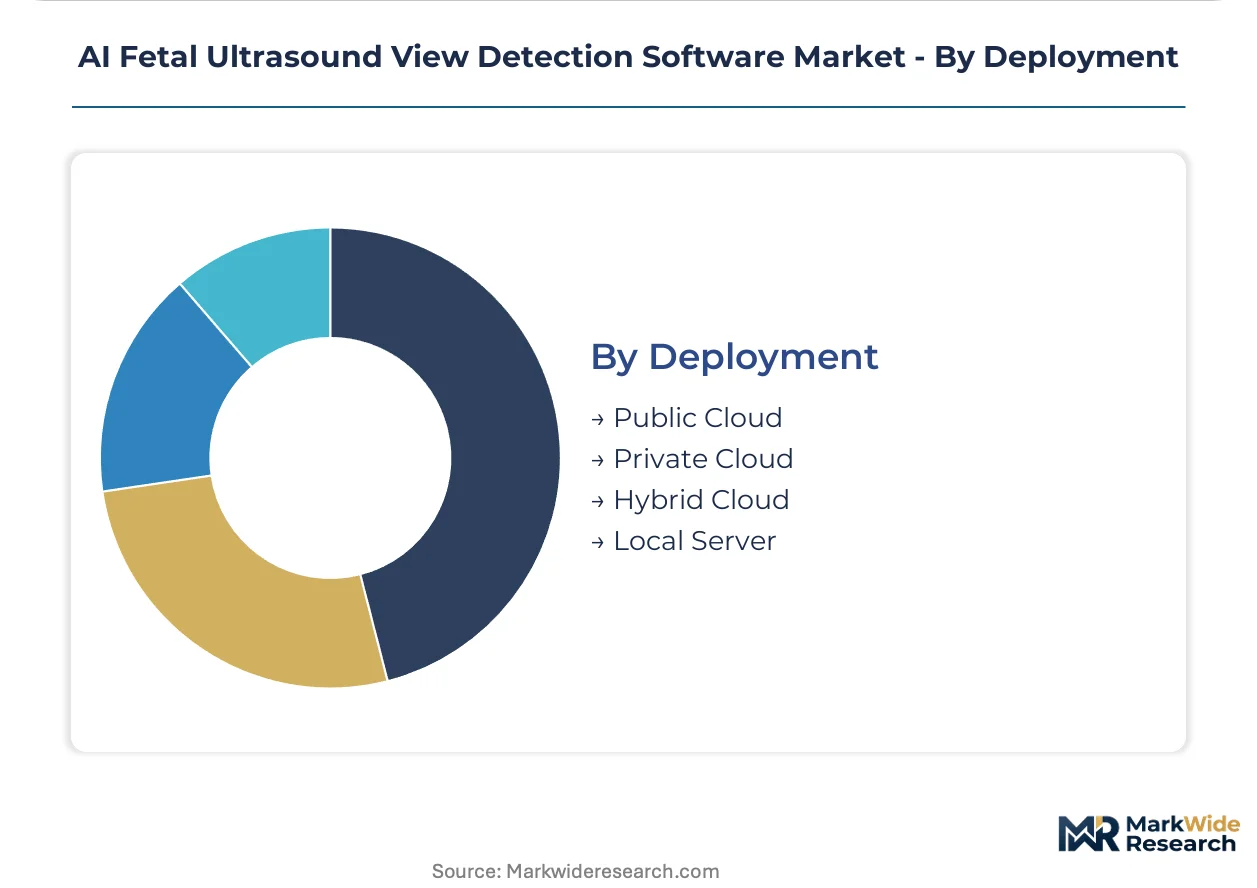
Latency requirements for real-time bedside screening favor local processing, while algorithm update frequency drives cloud migration in teleradiology networks.
- Public Cloud:Multi-tenant infrastructure enabling rapid scaling for teleradiology networks connecting Indian district hospitals to metropolitan maternal-fetal medicine centers. GDPR compliance constraints limit European adoption despite cost advantages. Today's expansion leader: Public Cloud. Tomorrow's governance-compliant alternative: Hybrid Cloud.
- Hybrid Cloud:Edge inference for real-time screening with cloud-based model retraining and centralized quality monitoring. EU AI Act risk classification rules favor architectures separating patient data from algorithm improvement pipelines.
- Private Cloud:Single-tenant deployments for health systems requiring dedicated infrastructure and customized SLA terms.
- Local Server:Air-gapped installations in military or government maternal health facilities with classified or restricted network policies.
Data residency regulations and examination latency requirements constrain cloud migration more than functional capability gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates enterprise procurement authority through integrated delivery networks, while Germany enforces AI-assisted standardization mandates across consolidated maternal-fetal medicine departments. Israel anchors algorithm development clusters for fetal cardiac view detection. India expands teleradiology networks connecting tier-II cities to metropolitan specialists.
United States
FDA pre-certification pilot programs accelerate cardiac view detection algorithm deployment across academic medical centers in Massachusetts and California. Health system consolidation in the Midwest and Southeast drives enterprise software procurement committees to mandate ISO 13485 certification as baseline qualification filters. Cleveland Clinic and Mayo Clinic networks anchor clinical validation partnerships for distributed learning architectures.
Germany
EU MDR post-market surveillance requirements extend software validation timelines for vendors serving Bavarian and North Rhine-Westphalia maternal clinic networks. The country's national pharmaceutical regulator enforces layered conformity assessment obligations under EU AI Act risk classification rules for high-risk obstetrics algorithms. Berlin-Brandenburg health systems mandate AI-assisted anatomical plane recognition across departmental workflows.
Israel
Algorithm development clusters in Tel Aviv and Haifa concentrate convolutional neural network expertise for fetal biometry applications. The country's national pharmaceutical regulator aligns with FDA breakthrough device pathways for prenatal screening innovations. Israeli startups force legacy ultrasound manufacturers to accelerate cardiac view detection model iteration cycles.
India
Teleradiology networks connecting district hospitals in Maharashtra and Karnataka to metropolitan maternal-fetal medicine centers in Mumbai and Bangalore create distributed AI interpretation demand. The country's national pharmaceutical regulator issues software-as-medical-device guidance parallel to FDA frameworks. Hyderabad and Chennai anchor cloud-based platform adoption for low-volume clinics lacking capital equipment budgets.
United Kingdom
NHS England procurement frameworks mandate interoperability standards for AI fetal ultrasound integration into PACS infrastructure across London and Southeast hospital networks. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit for software-as-medical-device products. Manchester and Birmingham academic medical centers contribute training data to federated learning networks.
AI Fetal Ultrasound View Detection Software Market Competitive Landscape
United States producers anchor the premium imaging console tier; Israeli specialists hold algorithm development positions. The market structures around three dominant ultrasound hardware manufacturers controlling embedded solution distribution, with independent software vendors competing for cloud-based platform contracts. Strategic archetypes include integrated hardware-software ecosystems, standalone AI specialists, and teleradiology service providers. Licensing negotiations with console manufacturers and federated learning partnerships constitute the dominant competitive moves.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips occupy positions exemplifying integrated hardware-software ecosystem archetypes. Siemens Healthineers represents the European engineering-intensive tier with embedded biometric measurement engines. These three anchors control embedded algorithm deployment pathways through proprietary console architectures, forcing independent vendors toward cloud-based and hybrid deployment modalities.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Siemens Healthineers |
| FUJIFILM |
| Samsung Medison |
| Mindray Medical |
| Butterfly Network |
| Sonio |
| EchoNous |
| Others |
Pricing and Supply Chain Analysis
Captive algorithm development within ultrasound console manufacturers anchors both supply security and pricing power across embedded solution tiers. GE Healthcare, Philips, and Siemens Healthineers leverage in-house convolutional neural network teams to control detection engine distribution, while independent vendors face licensing negotiations that compress margin structures.
Pricing Analysis
Capacity additions in Israel and India are reshaping price floors for cloud-based platforms serving tier-II maternal clinics. Embedded solutions command premium-mid-economy pricing differentiation based on FDA pre-certification tier and ISO 13485 certification status. Cost compression in the standalone software tier is intensifying because teleradiology networks negotiate volume-based SaaS contracts. District hospitals in Maharashtra and Karnataka exhibit highest price sensitivity; US academic medical centers show lowest sensitivity due to liability reduction value.
Supply Chain Analysis
Refurbishment flows for legacy ultrasound consoles in Germany and France extend hardware lifecycles, delaying embedded algorithm upgrade cycles. Taiwan, South Korea, and the United States concentrate GPU and edge processor manufacturing for real-time inference engines. Supply chains draw from specialized fetal biometry annotation labor pools in Israel and the United Kingdom, creating single-source vulnerability in ground-truth dataset generation. Distribution runs through ultrasound OEM direct sales forces for embedded solutions, while cloud platforms leverage channel partners for low-volume clinic penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in AI fetal ultrasound software rests on algorithm differentiation and cloud subscription scaling. Cost-down drivers include federated learning architectures that reduce annotation labor intensity.
For Market Incumbents: To counter Israeli AI imaging startups forcing accelerated cardiac view detection iteration, GE Healthcare and Philips should deepen backward integration into annotation specialist networks and secure exclusive clinical validation partnerships with US academic medical centers. FDA pre-certification pathway investment remains essential for maintaining clearance-validated performance claims. For New Entrants and Emerging Players: Capture white-space opportunity in Indian tier-II city teleradiology networks and GDPR-compliant federated learning platforms for European multi-site health systems. The most penetrable segment is cloud-based anomaly detection for low-volume maternal clinics lacking capital equipment budgets. Go-to-market angle: ISO 13485-certified remote analysis with subscription pricing scaled to examination volume. For Investors and Strategic Acquirers: Roll-up economics work for independent AI specialists with FDA-cleared cardiac view algorithms because health system consolidation is compressing vendor panels to pre-qualified suppliers. Long-term viability favors platforms with continuous learning architectures and distributed clinical data access. Signal to watch: EU AI Act notified body involvement timelines for high-risk obstetrics algorithm categories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway Investment | Streamlined algorithm updates accelerate cardiac view detection deployment across US hospital networks. |
| ISO 13485-Certified Cloud Platform Launch | Remote analysis capabilities unlock subscription revenue from low-volume European maternal clinics. |
| Federated Learning Partnership | Multi-institutional algorithm improvement without centralizing protected health information addresses GDPR constraints. |
| Clinical Validation Alliance with Academic Medical Center | Cleveland Clinic and Mayo Clinic networks anchor distributed learning architecture credibility. |
| Teleradiology Network Integration | Hyderabad and Chennai cloud adoption connects district hospitals to metropolitan maternal-fetal medicine specialists. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary sources included maternal-fetal medicine subspecialists, hospital procurement committee members, biomedical engineers at ultrasound OEMs, GPO contracts managers, and teleradiology network operators. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up examination volume estimates and top-down health system IT spending patterns were triangulated against vendor-reported deployment metrics.
Segment-weighting approaches distributed value and volume across embedded solution, cloud-based platform, and hybrid deployment modalities. Modeled dimensions included product type, application intensity, end-user IT sophistication, and regional regulatory cluster. CAGRs were derived from algorithm adoption curve analysis and health system procurement cycle timing. Forecast inputs incorporated FDA pre-certification pilot expansion assumptions and EU AI Act risk classification implementation trajectories.
Regulatory timeline delays, annotation specialist compensation inflation, and ultrasound hardware oligopoly licensing friction are the dominant revision risks. Forecasts reflect assumptions about maternal clinic consolidation velocity and teleradiology network scaling. Practitioners should monitor FDA software-as-medical-device framework updates and EU MDR post-market surveillance burden changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
South America MRI Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Mammography Detectors Market