
 Carotid Stenting Systems Market | 2026-2036
Carotid Stenting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Carotid Stenting Systems Market Analytics
The EU Medical Device Regulation (MDR) is repositioning European procurement criteria toward enhanced clinical follow-up and post-market surveillance for carotid implants. Abbott Laboratories leverages its structural heart portfolio to sustain catheter-based neurovascular access. Boston Scientific Corporation anchors its position through specialized interventional cardiology sales channels. Medtronic competes on integrated hospital contracting that bundles stroke care pathways with device supply.
Carotid stenting systems are nitinol or cobalt-chromium tubular scaffolds delivered endovascularly to maintain luminal patency in the carotid artery, typically measuring 6-10 mm in diameter and 20-40 mm in length, designed to prevent embolic stroke during and after deployment. Self-expanding stents occupy the largest procedural volume due to conformability against tortuous anatomy and established reimbursement codes in ambulatory settings. Balloon-expandable platforms lead in precision landing at the carotid bifurcation where radial strength matters. Endovascular delivery mode dominates hospital purchasing as physician training concentrates on transfemoral and transradial techniques.
FDA premarket notification and PMA pathways govern US market entry, while the EU MDR and CE marking framework impose stricter clinical evaluation requirements across European member states. Japan's PMDA maintains distinct pharmaceutical and medical device agency review timelines that shape launch sequencing for multinational manufacturers. Stakeholders must monitor evolving stroke society guidelines that oscillate between carotid endarterectomy and stenting recommendations based on ongoing randomized trial readouts.
Market Dynamics
Stroke prevention protocols are tilting toward catheter-based interventions as hospital systems consolidate vascular service lines and FDA premarket approval pathways demand richer real-world evidence portfolios from device sponsors.
Growth Catalysts
- Ambulatory surgical center expansion:United States reimbursement clarity for transcarotid artery revascularization is pulling procedures out of inpatient settings. Freestanding ASCs in Florida and Texas are adding dedicated neurovascular suites.
- EU MDR post-market surveillance mandates:Enhanced clinical follow-up requirements for carotid implants are favoring manufacturers with established registry infrastructure. Sponsors with active European registries capture tender advantages in Germany and France.
- Nitinol alloy advances:Superelastic nickel-titanium formulations with improved fatigue resistance are extending stent durability claims. Metallurgical improvements from specialized foundries are enabling thinner strut designs without sacrificing radial strength.
Market Restraints
- Platinum-iridium marker band cost volatility:Radiopaque element pricing swings are compressing gross margins on delivery systems. Device makers face hedging decisions on precious metal inventories.
- Single-source cobalt-chromium tubing:Specialty alloy suppliers in Switzerland and Germany control thin-wall seamless tube supply for balloon-expandable platforms. Geographic concentration creates vulnerability to export licensing delays.
- Carotid endarterectomy durability data:Long-term patency outcomes from surgical trials continue anchoring guideline recommendations. Stenting sponsors must fund expensive non-inferiority studies to displace incumbent therapy.
Strategic Opportunities
- Japan's super-aged prefectures:Hokkaido and rural Honshu regions show procedural volume gaps against Tokyo-Osaka corridors. PMDA streamlined review pathways reward early local clinical investment.
- Transradial access training networks:Specialized catheter configurations for smaller vessel entry are creating physician education partnerships. Teaching hospitals in the Netherlands are certifying interventionalists for wrist-based approaches.
- AI-enabled procedural planning:Machine learning tools for carotid bifurcation sizing are converging with stent selection software. Integration with preoperative imaging workstations is opening new software licensing revenue.
Industry Challenges
- Neurointerventionalist training pipeline:Fellowship programs produce fewer stroke-specialized operators than service line expansion requires. Academic medical centers face retention pressure from device company clinical specialist roles.
- Dual regulatory dossier preparation:Simultaneous FDA PMA and EU MDR technical documentation demands strain regulatory affairs teams. Divergent clinical evidence standards force parallel study designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotid Stenting Systems Market |
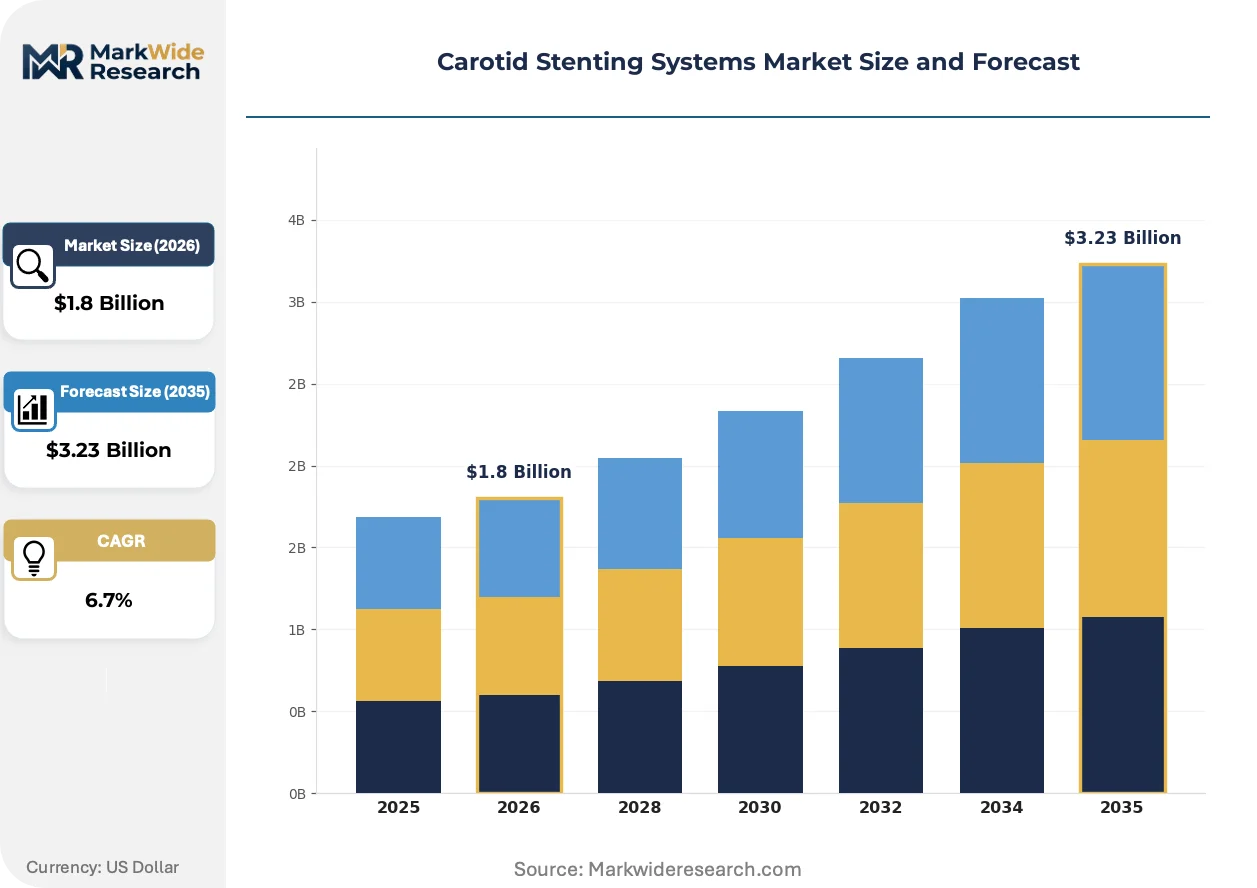
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding, Balloon-Expandable, Hybrid, Stent-Graft Delivery Mode: Percutaneous, Transluminal, Open Surgery, Endovascular End User: Hospitals, Specialized Clinics, Ambulatory Surgical Centers, Research Institutions Procedure Type: Elective, Emergency, Diagnostic, Therapeutic |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic, Cordis, Silk Road Medical, InspireMD, Terumo Corporation, MicroPort Scientific Corporation, BIOTRONIK SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotid Stenting Systems Market Evolving Landscape
Device architectures are converging around embolic protection integration as procedural safety metrics become the primary purchasing criterion for hospital value analysis committees.
Bioresorbable polymer embolic filters are unifying protection and delivery functions into single catheter systems. Interventional cardiologists in high-volume German stroke centers are adopting these platforms faster than traditional neurovascular specialists. The structural consequence is compressing the standalone protection device market while elevating bundled system pricing power.
Japan's PMDA revised pharmaceutical and medical device agency review timelines are compressing launch sequencing for multinational manufacturers. Sponsors must now synchronize Japanese clinical trial initiation with US pivotal studies to avoid sequential approval gaps. Small-diameter self-expanding platforms for Asian anatomies face accelerated review under the Sakigake designation pathway.
Hospital purchasing committees are consolidating vendor contracts around integrated stroke care pathways rather than discrete device procurement. Value analysis teams in California and Massachusetts health systems are unbundling historical device-procedure bundles and reconstituting them around episode-based metrics. This behavioral shift is most visible in integrated delivery networks where chief medical officers hold direct contracting authority.
Carotid Stenting Systems Market Segmentation
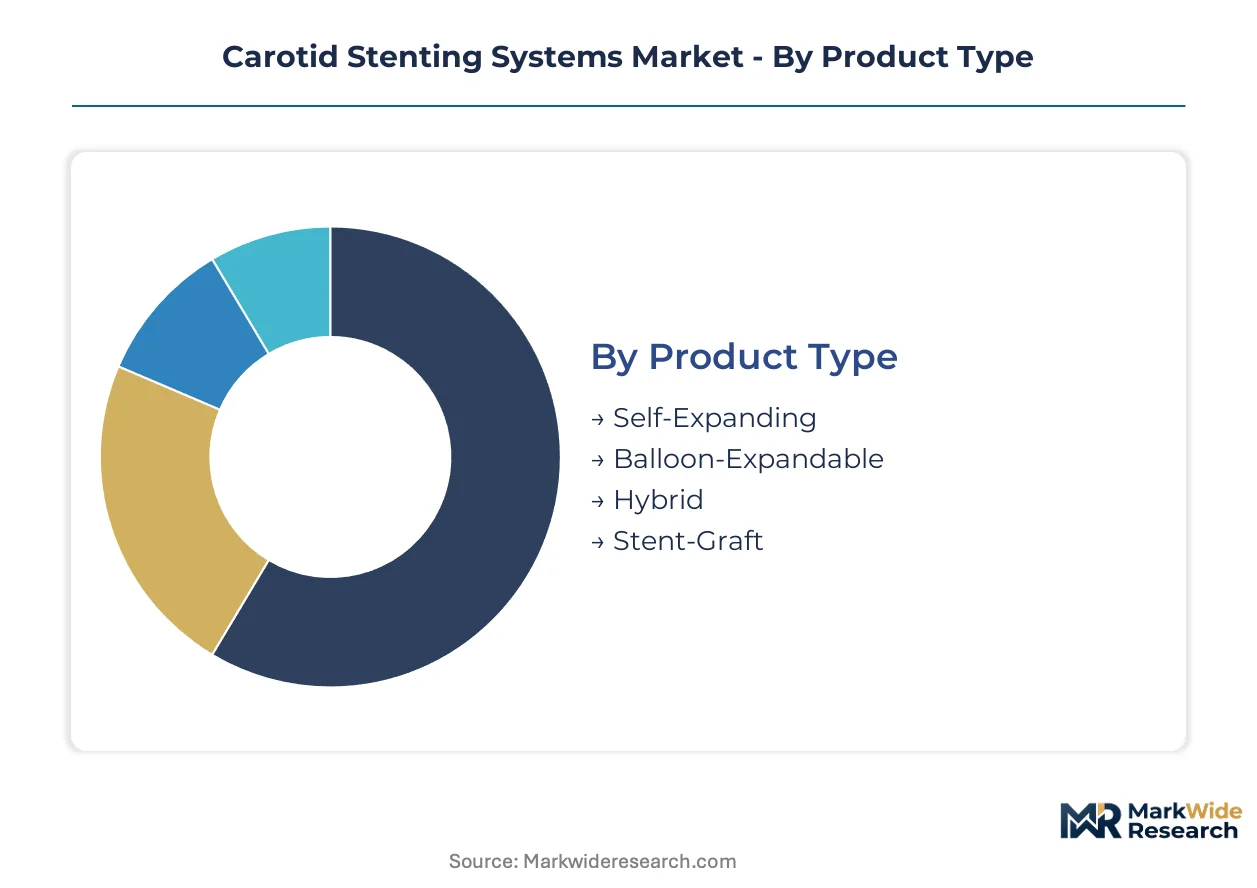
Carotid stenting systems fragment across four critical dimensions that shape procurement workflows and regulatory dossier requirements. Each category carries distinct FDA PMA pathway obligations, EU MDR technical documentation burdens, and PMDA review timelines that manufacturers must navigate simultaneously.
Product Type:
FDA premarket approval pathways impose divergent clinical evidence thresholds across these architectures, with self-expanding platforms facing the most established predicate device routes while hybrid configurations trigger novel device reviews.
- Self-Expanding:Nitinol superelastic scaffolds deploy without balloon inflation, conforming to tortuous carotid anatomy through thermal shape memory. Demand concentrates in ambulatory surgical centers across Florida and Texas where transfemoral techniques dominate and established reimbursement codes accelerate procurement cycles.
- Balloon-Expandable:Cobalt-chromium tubular structures deliver precise radial strength at the carotid bifurcation where landing zone accuracy prevents distal embolization. German stroke centers in Munich and Hamburg favor these platforms for high-risk surgical candidates where radial force trumps conformability.
- Hybrid:Combines self-expanding conformability with balloon-expandable precision zones for complex bifurcation disease.
- Stent-Graft:PTFE or ePTFE-covered scaffolds seal pseudoaneurysms and perforations in the extracranial carotid segment.
Self-expanding stents sit at the top of the volume ranking, with hybrid configurations climbing the fastest as Japanese regulators streamline review under Sakigake designation pathways.
Delivery Mode:
Cost tier differentiation separates capital-intensive endovascular suites from lower-threshold percutaneous approaches that ambulatory centers deploy without fixed imaging infrastructure.
- Percutaneous:Minimally invasive access through femoral or radial puncture without surgical cutdown, requiring only fluoroscopy and local anesthesia. ASCs in Texas and Arizona favor this mode for same-day discharge protocols that maximize facility throughput.
- Transluminal:Catheter passage through the arterial lumen with continuous wire support, enabling lesion crossing in heavily calcified vessels. Japanese interventionalists in rural Honshu prefectures prefer transluminal techniques where surgical backup remains distant.
- Open Surgery:Surgical exposure of the carotid artery with direct stent deployment under visualization, reserved for anatomical failures.
- Endovascular:Comprehensive catheter-based approach integrating imaging, navigation, and deployment within the vascular system.
Endovascular delivery commands the highest procedural reimbursement, with transluminal approaches gaining share fastest as transradial training networks expand across Dutch teaching hospitals.
End User:
Customer type determines contract structure, with integrated delivery networks bundling stroke care pathways while standalone ASCs negotiate device-procedure splits.
- Hospitals:Comprehensive stroke centers maintain 24-hour neurointerventional coverage, absorbing the highest device procurement volumes through integrated contracting. California health systems unbundle historical bundles and reconstitute them around episode-based metrics that chief medical officers directly control.
- Specialized Clinics:Dedicated vascular or neurovascular facilities concentrate procedural expertise without full emergency infrastructure. Massachusetts stroke clinics leverage specialized interventional cardiology sales channels that Boston Scientific anchors through dedicated field teams.
- Ambulatory Surgical Centers:Freestanding facilities exploit United States reimbursement clarity for transcarotid artery revascularization.
- Research Institutions:Academic medical centers generate registry data and train fellowship pipelines.
Hospitals retain the dominant procurement position, with ambulatory surgical centers expanding most quickly as United States reimbursement pulls procedures from inpatient settings.
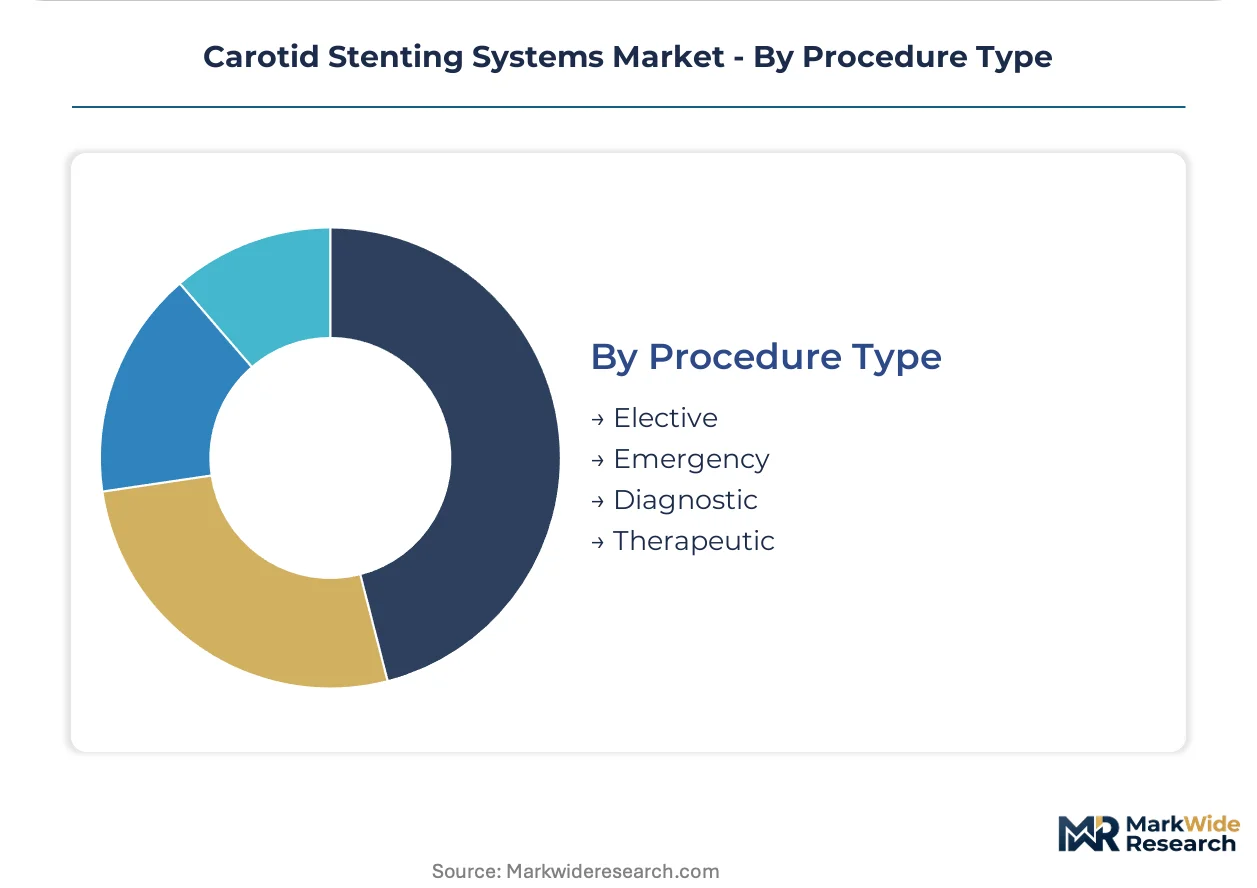
Procedure Type:
Maturity gradients separate well-established elective workflows from emergency protocols that demand 24-hour device inventory and specialized operator availability.
- Elective:Scheduled interventions for asymptomatic carotid stenosis or stable symptomatic disease, permitting preoperative planning and device selection. German hospital systems consolidate vascular service lines around elective volumes that support dedicated neurovascular suite utilization.
- Emergency:Urgent revascularization for acute stroke or crescendo transient ischemic attacks, requiring immediate device availability. Japanese super-aged prefectures in Hokkaido show volume gaps against Tokyo-Osaka corridors where emergency coverage concentrates.
- Diagnostic:Angiographic assessment with provisional stenting capability for incidentally identified lesions.
- Therapeutic:Definitive stent deployment as the primary treatment modality rather than diagnostic adjunct.
Elective procedures generate the highest margin per case, with emergency applications gaining share fastest as stroke systems of care compress door-to-device times across United States metropolitan clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurointerventionalist fellowship programs concentrate stroke-specialized operators in metropolitan hospital clusters across the United States, Germany, and Japan. These three markets absorb the dominant share of procedural volume as aging demographics and reimbursement clarity align. Each geography imposes distinct regulatory frameworks that shape device launch sequencing and commercial infrastructure requirements.
United States
Transcarotid artery revascularization reimbursement clarity pulls procedures into freestanding ambulatory surgical centers in Florida and Texas. FDA premarket approval pathways demand richer real-world evidence portfolios from device sponsors seeking PMA designation. California health systems unbundle historical device-procedure bundles and reconstitute them around episode-based metrics that chief medical officers directly control.
Germany
EU MDR post-market surveillance mandates favor manufacturers with established European registry infrastructure for tender advantages in Munich and Hamburg stroke centers. Balloon-expandable platforms dominate procurement for high-risk surgical candidates where radial force trumps conformability. German hospital systems consolidate vascular service lines around elective volumes that support dedicated neurovascular suite utilization.
Japan
PMDA streamlined review pathways reward early local clinical investment in Hokkaido and rural Honshu regions showing procedural volume gaps against Tokyo-Osaka corridors. Small-diameter self-expanding platforms for Asian anatomies face accelerated review under the Sakigake designation pathway. Japanese interventionalists in rural prefectures prefer transluminal techniques where surgical backup remains distant.
United Kingdom
NHS England specialized commissioning frameworks concentrate carotid stenting in comprehensive stroke centers with 24-hour neurointerventional coverage. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR implementation timelines for UK-specific device approvals. London and Southeast England academic medical centers generate registry data while facing retention pressure from device company clinical specialist roles.
Switzerland
Swissmedic maintains distinct review timelines that multinational manufacturers synchronize with EU MDR submissions to avoid sequential approval gaps. Specialty alloy suppliers in Switzerland control thin-wall seamless tube supply for balloon-expandable platforms, creating geographic concentration vulnerability. Swiss hospital purchasing committees evaluate bundled stroke care pathway contracts rather than discrete device procurement.
Carotid Stenting Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the carotid stenting systems market. The vendor base fragments across three tiers: integrated cardiovascular conglomerates with structural heart portfolios, specialized neurovascular pure-plays, and regional catheter fabricators serving Asian market entry. Consolidation pressure operates through integrated hospital contracting that bundles stroke care pathways with device supply, and through M&A targeting embolic protection technology assets.
Among diversified cardiovascular conglomerates, Abbott Laboratories, Boston Scientific Corporation, and Medtronic occupy positions defined by distinct channel strategies. Abbott leverages structural heart portfolio synergies for catheter-based neurovascular access. Boston Scientific anchors through specialized interventional cardiology sales channels with dedicated field teams. Medtronic competes on integrated hospital contracting that bundles comprehensive stroke care pathways. These three represent the dominant competitive archetype against which specialized neurovascular firms and regional Asian manufacturers define differentiation strategies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic |
| Cordis |
| Silk Road Medical |
| InspireMD |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| Others |
Value Network & Pricing Analysis
EU MDR post-market surveillance mandates for enhanced clinical follow-up and device traceability gate qualified supply access and premium-tier pricing power for carotid stenting systems. Manufacturers with established European registry infrastructure capture tender advantages while sponsors lacking compliant quality management systems face exclusion from German and French hospital procurement frameworks.
Pricing Analysis
Bundled stroke care pathway contracts versus unbundled device-procedure splits define the dominant pricing structure across hospital purchasing committees. Price differentiation rests on FDA PMA pathway completion status and EU MDR technical documentation depth, with fully certified platforms commanding premium positioning against predicate device equivalents. Cost compression in balloon-expandable segments is intensifying because platinum-iridium marker band volatility compresses gross margins on delivery systems. Integrated delivery networks in California and Massachusetts show least price sensitivity due to episode-based metric reconstitution, while freestanding ambulatory surgical centers in Florida and Texas negotiate most aggressively on per-unit device costs.
Supply Chain Analysis
Regional distribution centers in Switzerland and Germany anchor hub-and-spoke patterns for specialty alloy supply to balloon-expandable platform manufacturers. Raw material dependencies center on nitinol superelastic tubing from specialized foundries, cobalt-chromium thin-wall seamless tube from Swiss and German suppliers, and radiopaque platinum-iridium elements. Single-source concentration in Swiss-German alloy tubing creates vulnerability to export licensing delays and geopolitical friction. Distribution runs through manufacturer-direct hospital contracting and group purchasing organization channels, with stroke care pathway bundling consolidating vendor relationships around integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hospital value analysis committees prioritize procedural safety metrics and embolic protection integration over commoditized bare-metal platforms. The demand-shift toward bioresorbable polymer embolic filters and AI-enabled procedural planning software elevates premium specification requirements.
For Market Incumbents: Lock in registry infrastructure advantages by expanding European post-market surveillance datasets before EU MDR tender windows close in Germany and France. Defend against specialized neurovascular pure-plays by deepening captive supply of nitinol superelastic formulations through backward integration into metallurgical partnerships. Channel control through dedicated interventional cardiology field teams remains the critical lever for maintaining hospital contracting position. For New Entrants and Emerging Players: AI-enabled procedural planning software for carotid bifurcation sizing offers the most penetrable white-space target against incumbent hardware-dominated portfolios. Japan's super-aged prefectures in Hokkaido and rural Honshu present geographic entry opportunity given procedural volume gaps against Tokyo-Osaka corridors and PMDA Sakigake pathway acceleration for small-diameter platforms. Go-to-market execution should prioritize physician education partnerships with Dutch teaching hospitals certifying transradial access networks. For Investors and Strategic Acquirers: Roll-up economics work for specialized embolic protection technology assets because hospital purchasing committee consolidation around bundled stroke care pathways is compressing standalone device markets. Five-to-ten year viability favors platforms with integrated software-hardware combinations and active regulatory dossiers across FDA PMA and EU MDR pathways. The inflection signal to watch is transcarotid artery revascularization reimbursement expansion pulling procedural volume into ambulatory surgical center settings.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway Completion | PMA designation unlocks Medicare reimbursement codes and hospital value analysis committee access. |
| EU MDR Technical Documentation Investment | Enhanced clinical evaluation requirements gate tender participation in German and French stroke centers. |
| Hospital System Partnership | Integrated contracting with California and Massachusetts health systems bundles stroke care pathways. |
| Software Companion Development | AI-enabled procedural planning tools for carotid bifurcation sizing create new licensing revenue streams. |
| Reimbursement Strategy | Transcarotid artery revascularization coding clarity in Florida and Texas ASCs accelerates volume migration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build convergent validity across data streams. Primary fieldwork engaged neurointerventionalists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers across comprehensive stroke centers in the United States, Germany, and Japan. Secondary validation drew from FDA PMA filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedural volume modeling and top-down market sizing triangulated to produce segment-level estimates.
Comparable-period anchoring established baseline reference points from historical procedural volumes and device shipment patterns across the projection horizon. The analytical framework modeled segmentation across product architecture, delivery mode, end-user facility type, and procedure urgency classification. CAGRs were derived from trend extrapolation adjusted for regulatory pathway timing and reimbursement policy shifts. Forecast inputs incorporated nitinol alloy pricing trajectories, neurointerventionalist fellowship pipeline output rates, and stroke society guideline revision probabilities.
The model holds under stable FDA PMA review timelines and EU MDR implementation continuity; deviation in regulatory dossier requirements or precious metal cost volatility would shift volume and value outputs. Forecasts reflect documented assumptions regarding procedural migration to ambulatory settings and bundled contracting adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Gel Implants Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Rectal Catheters Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Inversion Table Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Skull Clamp Market
Medical Devices
Subcutaneous Drug Delivery Devices Market