
 Pedicle Screw Systems Market | 2026-2036
Pedicle Screw Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pedicle Screw Systems Market Analysis
Titanium forging capacity in Switzerland is hardening as a bottleneck for premium implant supply chains. Medtronic PLC leverages backward integration into raw material sourcing to sustain margin stability across volatile alloy markets. Zimmer Biomet anchors its competitive stance through specialized polyaxial screw geometries that dominate complex deformity correction workflows. Stryker Corporation differentiates via robotic navigation compatibility that tightens surgical precision thresholds.
Pedicle screw systems constitute threaded metallic implants inserted through the pedicle into vertebral bodies to provide posterior spinal stabilization, typically manufactured from titanium alloy or surgical-grade stainless steel with diameters ranging from 4.5 mm to 7.5 mm and lengths from 25 mm to 55 mm depending on vertebral level. These devices serve the primary commercial purpose of enabling rigid internal fixation during spinal fusion, deformity correction, trauma stabilization, and oncologic reconstruction procedures. Polyaxial screw heads now lead product type configurations due to intraoperative adaptability that reduces rod-contouring time, while titanium material grades capture the fastest-growing margin pool as osseointegration performance becomes a procurement discriminator. Spinal fusion applications occupy the largest revenue share within the indication landscape, though tumor surgery segments show accelerated uptake tied to en-bloc resection techniques.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations force manufacturers to maintain exhaustive biocompatibility and mechanical testing dossiers that extend product development timelines. ISO 5832 standards for implantable metallic materials and ASTM F136 specifications for wrought titanium alloys establish baseline material qualification thresholds that shape supplier selection and batch release protocols. Stakeholders must monitor evolving cybersecurity requirements for instrumented navigation systems as software-enabled pedicle screw placement tools attract heightened regulatory scrutiny.
Market Dynamics
Titanium alloy supply concentration in Swiss forging facilities is compressing implant availability timelines while EU MDR technical documentation requirements extend product development cycles, creating simultaneous pressure on working capital and regulatory compliance bandwidth.
Growth Catalysts
- Aging surgical candidate pools:Demographic expansion in the United States, Germany, and Japan generates sustained procedural volume for spinal fusion and deformity correction interventions.
- EU MDR compliance frameworks:Harmonized technical documentation standards streamline multi-country market access for manufacturers achieving notified body certification under consolidated requirements.
- Polyaxial screw head geometries:Intraoperative adaptability reduces rod-contouring time in complex deformity workflows, accelerating adoption in tertiary referral centers.
Market Restraints
- Titanium input cost volatility:Aerospace and defense sectors compete for wrought titanium alloy feedstock, compressing margin stability for implant manufacturers without captive sourcing arrangements.
- Swiss forging capacity constraints:Premium implant supply chains face bottleneck risk as specialized titanium forging facilities reach utilization thresholds.
- 510(k) premarket notification timelines:FDA biocompatibility and mechanical testing dossier requirements extend development-to-market intervals for novel screw geometries.
Strategic Opportunities
- En-bloc resection techniques:Oncologic reconstruction procedures in tumor surgery segments create demand expansion beyond traditional spinal fusion applications.
- Robotic navigation convergence:Software-enabled pedicle screw placement tools attract hospital capital expenditure as precision thresholds tighten.
- Osseointegration performance differentiation:Titanium material grades emerge as procurement discriminators for premium contract positioning.
Industry Challenges
- Cybersecurity validation for navigation systems:Software-enabled surgical tools attract heightened regulatory scrutiny requiring dedicated compliance infrastructure.
- ISO 5832 batch release protocols:Implantable metallic material qualification thresholds shape supplier selection and quality management system complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedicle Screw Systems Market |
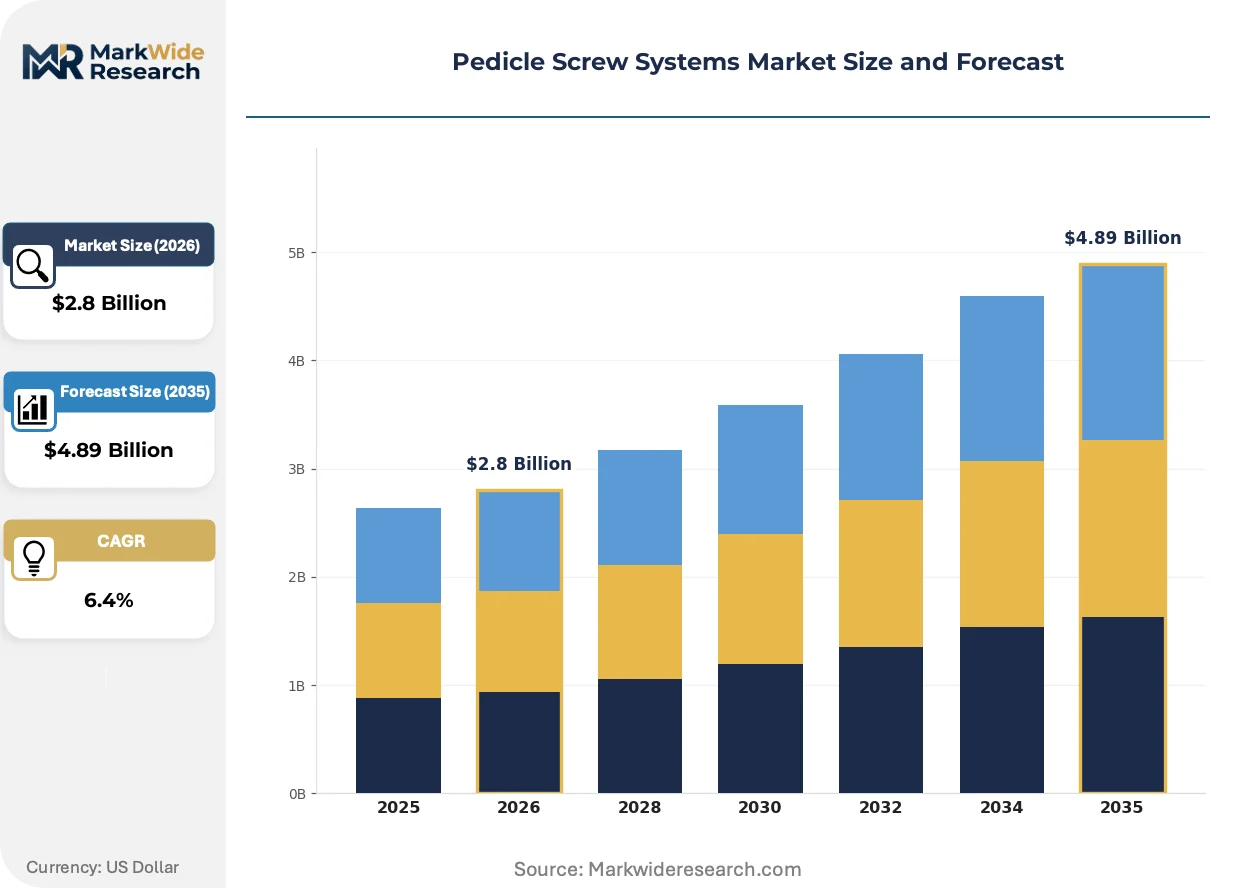
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Screw, Dynamic Screw, Polyaxial Screw, Monoaxial Screw Material: Stainless Steel, Titanium, Alloy, Polymer Application: Spinal Fusion, Deformity Correction, Trauma Repair, Tumor Surgery End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Research Institutions |
| Companies Covered | Zimmer Biomet, B. Braun Melsungen AG, Medtronic PLC, Alphatec Holdings Inc, Orthofix Medical Inc, Stryker Corporation, DePuy Synthes Companies of Johnson & Johnson, CoreLink Holding LLC, Globus Medical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedicle Screw Systems Market Emerging Trajectories
Three intersecting developments are restructuring competitive positioning: robotic surgical platforms, tightened cybersecurity mandates for connected devices, and evolving procurement criteria centered on osseointegration performance metrics.
Patient-specific 3D-printed titanium pedicle screw guides are overtaking standard navigation templates in complex deformity cases. Academic medical centers in Germany and Japan are adopting these guides for revision surgeries and congenital scoliosis corrections. This technology is overtaking conventional freehand and fluoroscopy-assisted techniques by reducing revision rates and intraoperative radiation exposure.
EU MDR Annex I general safety and performance requirements are forcing manufacturers to maintain exhaustive post-market surveillance systems for implantable spinal devices. Technical documentation obligations now cover entire product families rather than individual stock-keeping units, consolidating compliance costs among mid-tier suppliers. Class III device reclassification under MDR Article 52 is compressing timelines for legacy product recertification.
Hospital procurement committees are unbundling after-sales technical support from hardware contracts, creating direct accountability for screw-rod construct training and troubleshooting. This shift fragments vendor relationships as separate service providers capture education and maintenance revenue streams. The United States exhibits the most visible unbundling as integrated delivery networks centralize spinal implant purchasing decisions.
Pedicle Screw Systems Market Segmentation
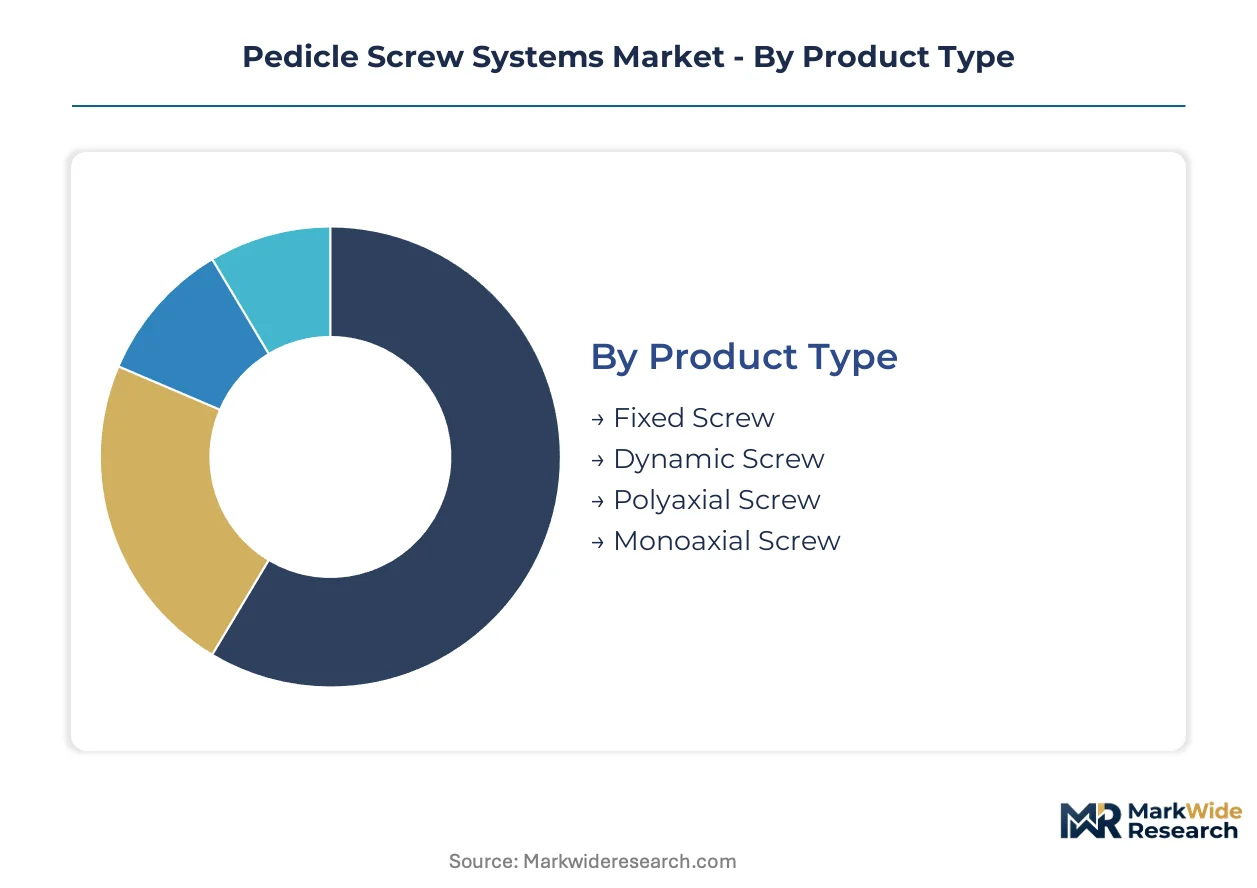
Pedicle screw systems fragment across four intersecting axes that determine procurement criteria, reimbursement pathways, and technical specification requirements. Understanding these segment boundaries clarifies how manufacturers align R&D investment with surgical workflow priorities and capital equipment budgets.
Product Type:
Head geometry defines intraoperative adaptability and rod engagement mechanics across screw platforms.
- Polyaxial Screw:Multiplanar head angulation permits up to 30 degrees of motion relative to the screw shaft, eliminating extensive rod contouring in complex deformity cases. Tertiary referral centers in the United States and Germany specify polyaxial configurations for adolescent idiopathic scoliosis corrections where anatomical variability demands intraoperative flexibility.
- Fixed Screw:Rigid head-to-shaft construction delivers maximum mechanical stability for straightforward lumbar fusion procedures. Community hospitals in Japan prioritize fixed screws for single-level degenerative disc disease where preoperative templating confirms standard trajectories.
- Dynamic Screw:Semiconstrained motion preservation interfaces with flexible stabilization rods to reduce adjacent segment stress. Academic medical centers in Switzerland evaluate dynamic systems for multi-level constructs where fusion mass preservation remains uncertain.
- Monoaxial Screw:Uniplanar angulation constraints balance stability against limited adjustability. Orthopedic clinics in select German regions specify monoaxial designs for trauma stabilization where cost containment outweighs polyaxial premium pricing.
Mature deployment sits with Fixed Screw configurations. Newer deployment is concentrated in Polyaxial Screw platforms.
Material:
Biocompatibility profiles and osseointegration kinetics separate procurement tiers across implant metallurgy.
- Titanium:Wrought titanium alloys per ASTM F136 specifications yield superior bone-implant interface formation through surface oxide layer chemistry. Swiss forging facilities supply premium-grade titanium to manufacturers targeting academic hospital contracts where osseointegration performance determines vendor selection.
- Stainless Steel:Surgical-grade 316L compositions maintain cost-positioning for high-volume standard procedures. Japanese regional hospitals specify stainless steel for elderly trauma patients where implant longevity requirements remain limited.
- Alloy:Cobalt-chrome and specialized titanium-zirconium blends address niche mechanical loading scenarios. German spine centers evaluate alloy alternatives for revision surgeries where bone quality degradation demands enhanced fatigue resistance.
- Polymer:PEEK and carbon fiber-reinforced composites enable radiolucent imaging during postoperative surveillance. Research institutions in the United States pilot polymer pedicle screws for tumor monitoring protocols where metal artifact reduction proves clinically decisive.
Volume concentration favors Stainless Steel. Steepest expansion trajectory belongs to Titanium.
Application:
Indication-specific biomechanical demands dictate screw diameter, length, and construct density requirements.
- Spinal Fusion:Rigid fixation across motion segments requires bilateral pedicle screw placement with rod connection. United States integrated delivery networks standardize fusion constructs for degenerative disc disease, driving the largest procedural volume segment.
- Deformity Correction:Long-segment constructs with multiple anchor points address three-dimensional spinal malalignment. German scoliosis centers deploy specialized screw densities exceeding standard fusion protocols.
- Trauma Repair:Acute stabilization of vertebral fractures demands expedient screw placement without extensive preoperative planning. Japanese emergency departments prioritize trauma-optimized screw lengths for burst fracture patterns.
- Tumor Surgery:En-bloc resection and vertebral body replacement create extended construct requirements. Swiss oncologic surgeons specify tumor-dedicated screw systems for metastatic disease stabilization.
Revenue scale peaks with Spinal Fusion. Gaining share fastest is Tumor Surgery.
End User:
Capital intensity and case-mix complexity determine purchasing authority and technical support expectations.
- Hospitals:Comprehensive surgical suites with in-house imaging and navigation infrastructure capture complex deformity and tumor procedures. United States hospital systems consolidate implant purchasing through value analysis committees.
- Ambulatory Surgical Centers:Streamlined single-level fusion workflows exploit reduced overhead structures. German outpatient spine centers expand ambulatory pedicle screw placement for selected degenerative indications.
- Orthopedic Clinics:Limited-procedure environments focus on diagnostic workup and postoperative surveillance rather than implant provision.
- Research Institutions:Academic medical centers with institutional review board oversight pilot novel screw designs and patient-specific guides.
Procurement volume concentrates in Hospitals. Expanding most quickly is Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss titanium forging facilities anchor premium implant supply chains across major surgical markets. Manufacturers source wrought alloy feedstock from specialized European metallurgy clusters to serve aging patient populations in three concentrated demand centers.
United States
FDA 510(k) clearance pathways shape product development timelines for spinal fusion devices. Integrated delivery networks in Texas and California consolidate purchasing authority through value analysis committees. Academic medical centers in Boston and New York deploy robotic navigation systems for complex deformity corrections.
Germany
EU MDR technical documentation requirements compress recertification timelines for legacy implant portfolios. Notified bodies in Berlin and Munich process Class III device submissions under consolidated harmonized standards. Scoliosis centers in Bavaria specify polyaxial screw densities exceeding standard fusion protocols for adolescent corrections.
Japan
PMDA regulatory reviews align with international standards while maintaining domestic clinical data requirements. Regional hospitals in Osaka and Tokyo prioritize stainless steel constructs for elderly trauma stabilization. Community surgical centers expand ambulatory fusion workflows for selected degenerative indications.
Switzerland
Swissmedic oversight of implantable devices intersects with specialized titanium forging capacity constraints. Medical technology clusters in Zurich and Basel supply premium-grade alloy to manufacturers targeting academic hospital contracts. Oncologic surgeons in Geneva specify tumor-dedicated screw systems for metastatic disease stabilization.
Pedicle Screw Systems Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance bandwidth and raw material sourcing depth. Market structure tilts toward consolidated tiers where backward integration into titanium supply chains separates premium-positioned vendors from assembly-dependent competitors. Three archetypes dominate: integrated metallurgy-to-implant manufacturers, specialized spinal device pure-plays, and diversified orthopedic conglomerates. Capacity expansion in Swiss forging facilities and M&A activity targeting navigation software capabilities represent the dominant competitive moves reshaping vendor positioning.
Among diversified orthopedic conglomerates, Zimmer Biomet, Medtronic PLC, and Stryker Corporation exemplify scale-driven archetypes that anchor competitive dynamics. These entities occupy positions where captive supply arrangements and multi-indication portfolios create defensive moats against titanium input volatility. Their market presence reflects the structural premium assigned to vendors with demonstrated navigation system compatibility and exhaustive regulatory dossier maintenance across FDA and EU MDR jurisdictions.
| Leading Market Players |
|---|
| Zimmer Biomet |
| B. Braun Melsungen AG |
| Medtronic PLC |
| Alphatec Holdings Inc |
| Orthofix Medical Inc |
| Stryker Corporation |
| DePuy Synthes Companies of Johnson & Johnson |
| CoreLink Holding LLC |
| Globus Medical Inc |
| Others |
Supply Flow & Price Mechanics
Family-owned Swiss forging specialists anchor premium titanium supply chains, translating metallurgical scarcity into pricing discipline that resists commoditization pressure from Asian stainless steel competitors. Their captive relationships with academic medical centers in Germany and Japan sustain premium positioning even as hospital procurement committees unbundle after-sales technical support from hardware contracts.
Pricing Analysis
Warranty and technical service bundling now fragments across vendor tiers, with integrated delivery networks in the United States extracting standalone education contracts while mid-tier suppliers absorb training costs to defend shelf position. Three-tier pricing structure across premium, standard, and economy levels stratifies by osseointegration performance certification and robotic navigation compatibility. Cost compression in standard stainless steel constructs intensifies because Japanese regional hospitals prioritize elderly trauma stabilization over implant longevity. Community surgical centers exhibit highest price sensitivity; academic medical centers with value analysis committees demonstrate lowest sensitivity due to outcome-based procurement criteria.
Supply Chain Analysis
Reverse logistics for explanted pedicle screws remain underdeveloped, with limited refurbishment pathways constraining circular material flows that could alleviate Swiss forging capacity bottlenecks. Geographic supply concentration centers on Switzerland for premium titanium forging, China for stainless steel processing, and Germany for precision machining of polyaxial screw heads. Raw material dependencies draw from aerospace-grade titanium alloy feedstock, surgical-grade 316L stainless steel bar stock, and cobalt-chrome rod for specialized fatigue-resistant applications. Single-source vulnerability pervades Swiss forging facilities where utilization thresholds compress implant availability timelines. Distribution runs through hospital value analysis committees in the United States, notified body-certified distributors in Germany, and regional medical device wholesalers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pedicle screw systems market occupies a technology-transition phase where patient-specific 3D-printed titanium guides displace conventional navigation templates in complex deformity workflows.
For Market Incumbents: Anticipate regulatory bandwidth compression as EU MDR Class III reclassification accelerates legacy product recertification timelines, forcing dossier consolidation investments. Defensive moves center on backward integration into Swiss titanium sourcing to secure alloy supply against aerospace sector competition, coupled with navigation software certification to tighten hospital capital equipment relationships. Capacity addition in Zurich-Basel metallurgy clusters represents the priority lever for margin stability. For New Entrants and Emerging Players: Enter via tumor surgery segments where en-bloc resection techniques expand construct requirements beyond established spinal fusion incumbents. White-space targets include polymer pedicle screws for radiolucent tumor monitoring in United States research institutions, and dynamic screw systems for motion preservation in Swiss academic evaluations. Ambulatory surgical centers in Germany offer the most penetrable end-user channel through streamlined single-level fusion workflows. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier spinal device pure-plays with EU MDR technical documentation gaps but intact surgeon training relationships in Germany. Long-term viability over the projection horizon hinges on navigation software compatibility and titanium supply chain depth rather than hardware scale alone. The signal to watch is hospital procurement committee unbundling velocity in United States integrated delivery networks.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Recertification | Notified body consolidation in Berlin and Munich compresses timelines for legacy portfolios. |
| Robotic Navigation Compatibility | Software-enabled placement tools attract hospital capital expenditure as precision thresholds tighten. |
| Patient-Specific 3D-Printed Guide Development | Academic medical centers in Germany and Japan adopt titanium guides for congenital scoliosis corrections. |
| Backward Integration into Titanium Sourcing | Captive supply arrangements defend margin stability against aerospace sector alloy competition. |
| Hospital System Partnership Expansion | Value analysis committees in Texas and California consolidate purchasing authority for complex deformity workflows. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. FDA 510(k) premarket notification databases, EU MDR technical documentation repositories, hospital procurement databases, and Swissmedic implantable device registries furnished validation layers. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures.
Segmentation granularity modeled product type configurations, material metallurgy grades, indication-specific biomechanical demands, and end-user capital intensity across the projection horizon. Analytical framework approach derived CAGRs from procedural volume trajectories, reimbursement pathway evolution, and technology substitution elasticities. Titanium alloy supply constraints, EU MDR compliance bandwidth, and robotic navigation adoption curves informed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Swiss forging capacity disruption or accelerated EU MDR enforcement timelines. Forecasts reflect assumptions regarding procedural volume elasticity to aging demographics and reimbursement stability for spinal fusion interventions. Practitioners should monitor PMDA regulatory alignment shifts in Japan and cybersecurity validation requirements for navigation systems as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Neurotech Devices Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Artificial Disc Market
Medical Devices
Medical Electrodes Market