
 Revision Knee Replacement Market | 2026-2036
Revision Knee Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Revision Knee Replacement Market Analytics
Ambulatory surgical centers is hardening as a preferred site of care for select revision cases, shifting volume away from traditional hospital settings. Stryker Corporation leverages its broad trauma and extremities portfolio to cross-sell revision knee systems into integrated delivery networks. Zimmer Biomet anchors its position through proprietary Persona Revision knee platform and deep surgeon training infrastructure. Smith & Nephew Plc competes with its LEGION Revision System and advanced bearing surface technologies targeting younger, more active patient cohorts.
Revision knee replacement encompasses the surgical removal and substitution of a failed or worn primary knee prosthesis with a specialized implant designed to address bone loss, ligament instability, and altered anatomy; these constructs typically incorporate modular stems, augments, and metaphyseal sleeves to achieve fixation in compromised bone. The primary purpose is restoring ambulatory function and relieving pain in patients experiencing aseptic loosening, polyethylene wear, periprosthetic fracture, or deep infection. Fixed bearing implants still occupy the largest installed base, though mobile bearing designs are gaining traction among high-volume academic centers seeking reduced wear rates. Cementless fixation with porous titanium or trabecular metal constructs represents the fastest-growing technology segment, as surgeons pursue biological osseointegration in younger revision candidates with adequate bone stock.
The FDA's 510(k) clearance pathway and subsequent post-market surveillance through the Total Product Life Cycle database govern implant safety monitoring and adverse event reporting in the United States. ISO 14155 clinical investigation standards and the EU Medical Device Regulation's enhanced notified body scrutiny have elevated clinical evidence requirements for European market access, lengthening development cycles but improving long-term tracking. Stakeholders must monitor evolving CMS reimbursement designations for outpatient total joint replacement and their spillover implications for revision procedure site-of-care economics.
Market Dynamics
The migration of revision knee procedures toward ambulatory surgical centers is compressing hospital inpatient revenue while forcing manufacturers to reconfigure implant logistics for same-day discharge protocols.
Growth Catalysts
- CMS outpatient reimbursement expansion:Medicare's removal of total knee arthroplasty from the inpatient-only list creates financial viability for ASC-based revision cases in the United States.
- Porous titanium fixation surfaces:Cementless constructs with trabecular metal architecture enable biological osseointegration in younger revision candidates with preserved bone stock.
- Orthopedic clinic consolidation:Integrated delivery networks in Florida and Texas are centralizing revision volume into high-throughput specialty centers.
Market Restraints
- Cobalt-chromium supply concentration:Foundry capacity for implant-grade alloys clusters in a limited supplier base, exposing manufacturers to raw material volatility.
- FDA 510(k) evidentiary burden:The agency's heightened scrutiny of predicate device equivalence for modular revision constructs extends premarket timelines.
- Polyethylene bearing durability ceiling:Cross-linked UHMWPE wear rates plateau below the threshold needed for 30-year implant survival in active patients.
Strategic Opportunities
- Patient-specific instrumentation:3D-printed cutting guides derived from preoperative CT reduce operative time and component malalignment in complex revision anatomy.
- Remote patient monitoring integration:Postoperative gait analysis platforms enable early detection of aseptic loosening before catastrophic failure.
- Extended reality surgical training:Virtual reality modules for revision knee exposure and component extraction address the narrowing pipeline of fellowship-trained surgeons.
Industry Challenges
- Periprosthetic fracture management protocols:Surgeon familiarity with stemmed construct extraction varies widely, producing inconsistent outcomes across practice settings.
- Modular junction corrosion:Fretting at taper connections between stems and metaphyseal sleeves generates metallic debris and complicates re-revision planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revision Knee Replacement Market |
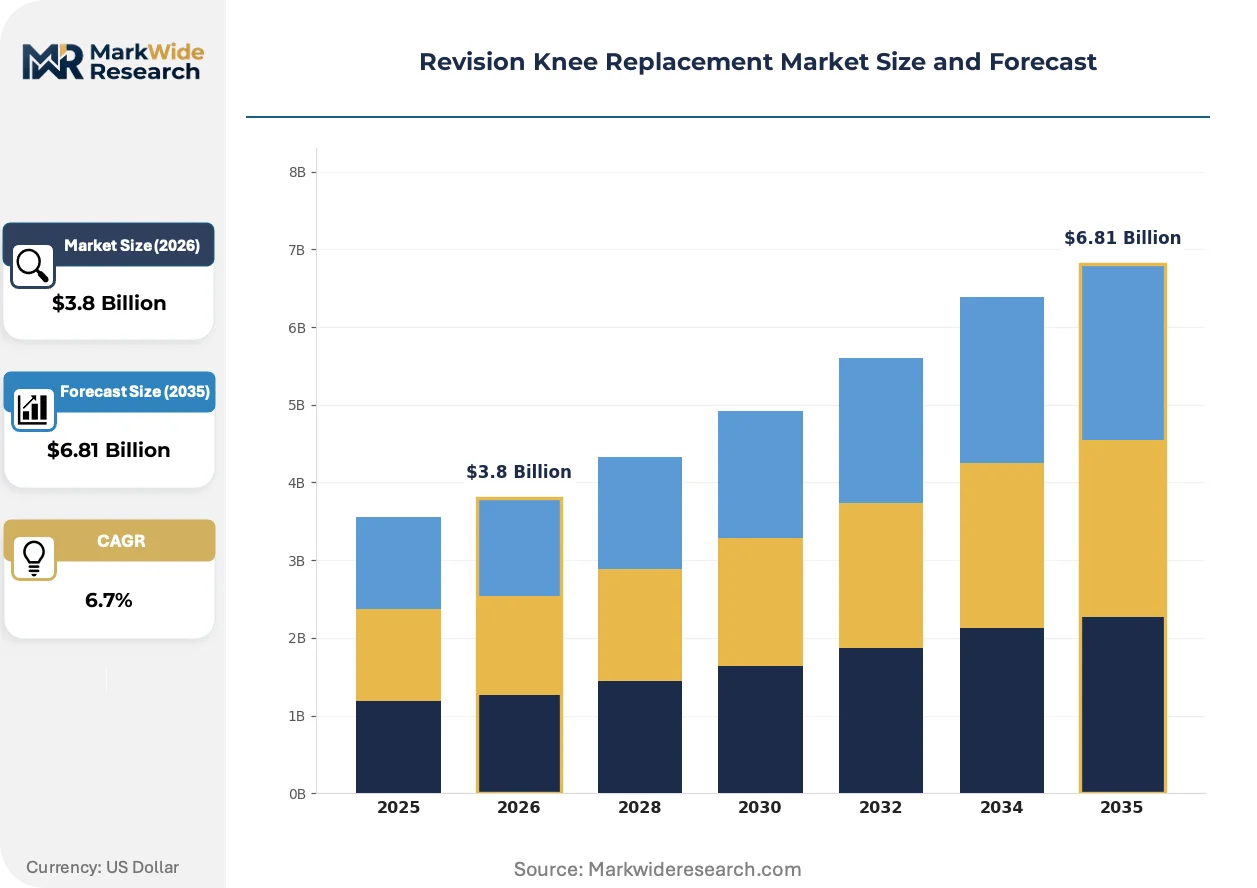
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bearing, Mobile Bearing, Partial, Total Delivery Model: Inpatient, Outpatient, Rehabilitation Center, Home Health End User: Orthopedic Clinics, Hospitals, Specialty Centers, Ambulatory Surgical Centers Technology: Cemented, Cementless, Hybrid, Computer-Assisted |
| Companies Covered | Smith & Nephew Plc, Stryker Corporation, Zimmer Biomet, DePuy Synthes Companies, Exactech, B. Braun Melsungen AG, Wright Medical Group, LimaCorporate, Medacta International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revision Knee Replacement Market Evolving Landscape
Digital surgical planning and bearing surface engineering are converging to reduce operative morbidity while extending implant longevity in younger, more active revision populations.
Patient-specific 3D-printed augments are overtaking standard off-the-shelf metaphyseal sleeves for addressing severe proximal tibial bone loss. Academic medical centers in Massachusetts and California are adopting these constructs for 40% of complex revision cases. The technology is overtaking conventional impaction grafting techniques by eliminating the learning curve variability that compromises initial fixation stability.
The EU Medical Device Regulation's enhanced notified body scrutiny for class III implantable devices has lengthened European market access timelines by demanding prospective clinical data for novel bearing surfaces. Manufacturers now face parallel-track development costs for US 510(k) and EU MDR submissions. Revision knee systems with rotating platform designs have absorbed the greatest compliance burden, prompting some firms to deprioritize European launches.
Hospital purchasing committees are consolidating supplier contracts around single-vendor orthopedic portfolios, compressing the number of implant vendors with access to revision knee volume. Integrated delivery networks in the Midwest United States now mandate cross-category commitments—trauma, spine, and joint replacement bundled agreements—to secure operating room access. This concentration is most visible in Wisconsin and Illinois, where three health systems control 60% of revision knee procedures.
Revision Knee Replacement Market Segmentation
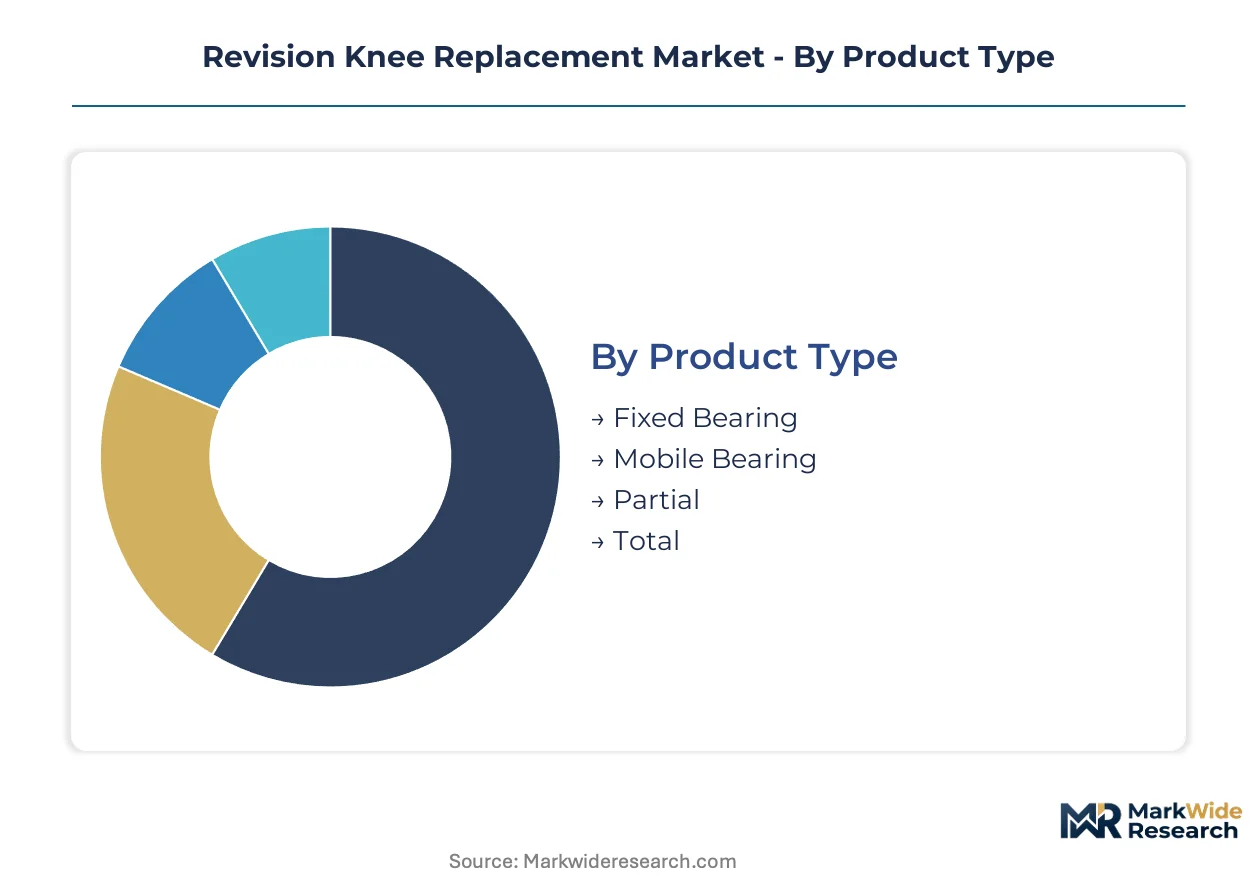
Revision knee replacement segmentation reveals how implant design, care delivery, and fixation technology intersect to determine procedure economics and patient selection criteria. Manufacturers configure product portfolios across these dimensions to match surgeon training, facility capabilities, and reimbursement pathways.
Product Type:
Implant kinematics distinguish bearing surface mobility and constraint levels, dictating wear characteristics and revision complexity.
- Fixed Bearing:Ultra-high molecular weight polyethylene inserts locked to tibial baseplates dominate current utilization. Demand concentrates in community hospitals across the United States where surgeon familiarity with established extraction techniques reduces operative risk.
- Mobile Bearing:Rotating platform designs permit polyethylene self-alignment to reduce backside wear. Academic medical centers in Massachusetts and California favor these constructs for younger revision candidates anticipating longer implant survival.
- Partial:Unicompartmental revision systems address isolated medial or lateral compartment failure.
- Total:Complete femoral and tibial component replacement resolves multi-compartment degeneration.
Mature deployment sits with Fixed Bearing systems. Newer deployment is concentrated in Mobile Bearing designs.
Delivery Model:
Care site economics are shifting as payers relax site-of-care restrictions for appropriately selected patients.
- Inpatient:Traditional hospital admission supports complex revisions requiring extended monitoring. United States health systems in Florida and Texas maintain dedicated orthopedic units for staged revision and infection management protocols.
- Outpatient:Same-day discharge protocols apply to select aseptic loosening cases with adequate bone stock. Ambulatory surgical centers in Arizona and Colorado are expanding capacity for these procedures under CMS reimbursement expansion.
- Rehabilitation Center:Post-acute facilities manage extended recovery for elderly patients with limited home support.
- Home Health:Skilled nursing visits enable early hospital discharge for geographically dispersed populations.
Volume leadership remains with Inpatient settings. Fastest share gains are occurring in Outpatient delivery.
End User:
Provider consolidation is concentrating revision volume into high-throughput specialty settings with dedicated implant inventory.
- Orthopedic Clinics:Physician-owned surgical facilities capture straightforward revision cases with predictable operative times. Integrated delivery networks in Wisconsin and Illinois route volume to these sites for cost efficiency.
- Hospitals:Academic centers manage complex re-revisions with severe bone loss requiring custom augments. Major referral centers in Ohio and Pennsylvania maintain fellowship-trained surgeons for these procedures.
- Specialty Centers:Dedicated joint replacement hospitals focus exclusively on arthroplasty volume.
- Ambulatory Surgical Centers:Medicare-certified ASCs are acquiring specialized revision instrumentation for selected cases.
Hospital-based programs anchor complex revision practice. Orthopedic Clinics are capturing the fastest volume expansion.
Technology:
Fixation strategy determines biological integration versus mechanical stability tradeoffs in compromised bone.
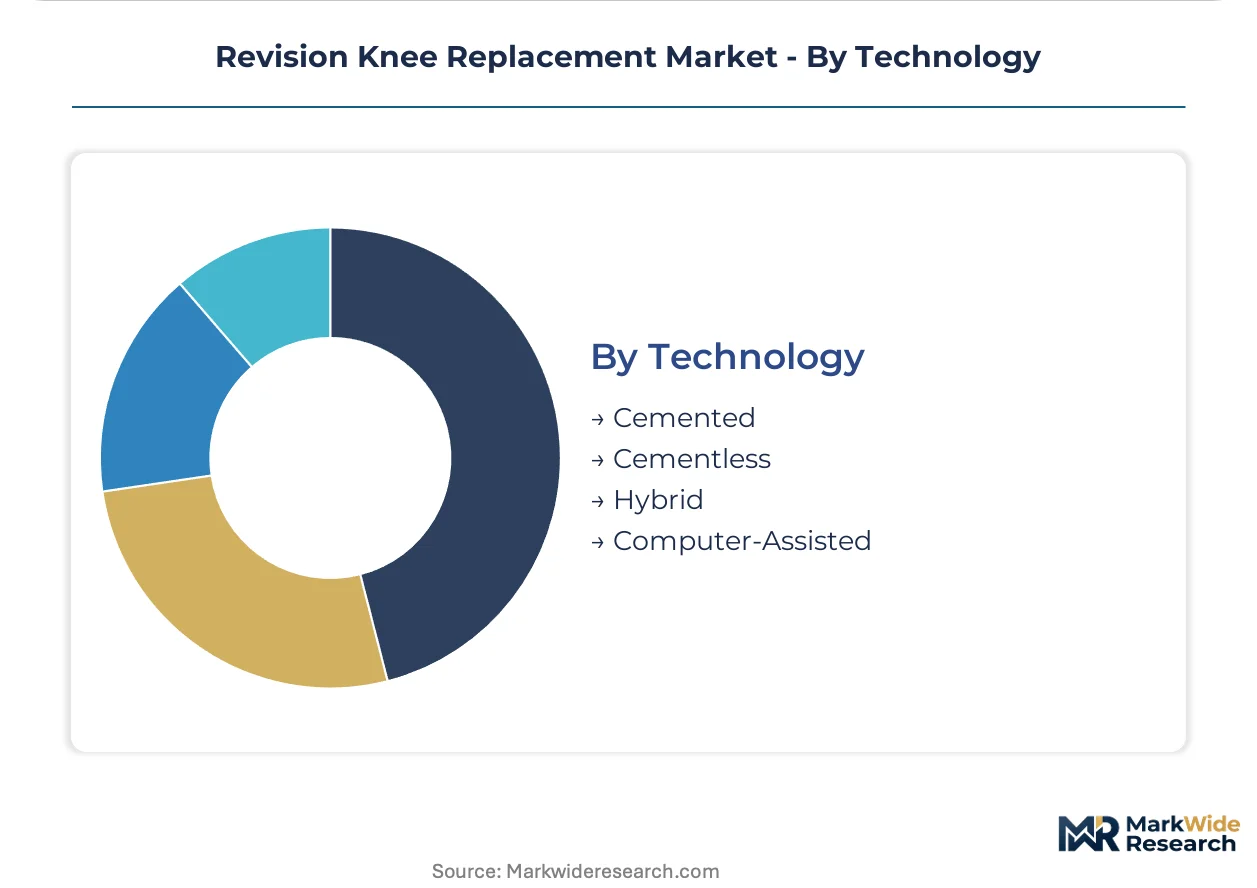
- Cemented:Polymethyl methacrylate fixation provides immediate stability in osteoporotic bone. Surgeons in Germany and the United Kingdom rely on cemented stems for elderly revision populations with poor bone quality.
- Cementless:Porous titanium and trabecular metal surfaces enable biological osseointegration. Younger active patients in Australia and South Korea drive demand for these constructs.
- Hybrid:Cemented metaphyseal fixation with cementless stem engagement combines immediate and long-term stability.
- Computer-Assisted:Navigation systems improve component alignment in distorted revision anatomy.
Cemented fixation retains the largest installed base. Cementless technology is climbing the fastest as biological fixation gains surgeon acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Massachusetts and Minnesota concentrate revision knee manufacturing infrastructure alongside FDA premarket review centers. These clusters attract orthopedic talent pools and accelerate regulatory submission cycles for implantable constructs.
United States
Medicare's outpatient reimbursement expansion drives ASC volume migration in Arizona and Colorado. The FDA's 510(k) pathway governs premarket notification for modular revision systems. Warsaw, Indiana anchors domestic manufacturing with integrated instrument and implant production corridors.
Germany
Surgeon preference for cemented fixation in elderly populations sustains demand for polymethyl methacrylate-compatible constructs. The EU Medical Device Regulation's notified body scrutiny extends approval timelines for rotating platform designs. Baden-Württemberg hosts specialized foundry capacity for implant-grade cobalt-chromium alloys.
Australia
Younger active patient demographics favor biological osseointegration with porous titanium constructs. The Therapeutic Goods Administration aligns post-market surveillance with ISO 14155 clinical investigation standards. Sydney and Melbourne academic centers pioneer patient-specific 3D-printed augments for severe bone loss cases.
Japan
Aging demographics and high primary arthroplasty penetration expand the revision candidate pool. The Pharmaceuticals and Medical Devices Agency mandates local clinical bridging studies for novel bearing surfaces. Osaka-Kobe manufacturing clusters supply precision-machined femoral components across Asia-Pacific markets.
South Korea
National health insurance reimbursement for revision procedures supports procedure volume growth. The Ministry of Food and Drug Safety enforces biocompatibility testing per ISO 10993 standards. Seoul Capital Area hospitals adopt computer-assisted navigation for complex revision anatomy with distorted landmarks.
Revision Knee Replacement Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated delivery network purchasing committees consolidating supplier relationships around full orthopedic portfolios. The vendor base clusters into three tiers: multinational conglomerates with trauma-to-joint replacement breadth, mid-cap extremities specialists cross-selling into revision knee, and regional fabricators supplying standard fixation components. Dominant competitive moves include hospital contract bundling across implant categories and captive supply chain integration into foundry capacity for implant-grade alloys.
Among the established orthopedic conglomerates, Stryker Corporation and Zimmer Biomet occupy positions exemplifying integrated portfolio breadth, while Smith & Nephew Plc represents the specialized extremities-to-revision trajectory. These three entities anchor the competitive structure through their respective Persona Revision knee platform, broad trauma and extremities cross-selling infrastructure, and LEGION Revision System positioning for active patient cohorts. Their collective presence shapes procurement negotiations with Midwestern integrated delivery networks and academic medical centers in Massachusetts and California.
| Leading Market Players |
|---|
| Smith & Nephew Plc |
| Stryker Corporation |
| Zimmer Biomet |
| DePuy Synthes Companies |
| Exactech |
| B. Braun Melsungen AG |
| Wright Medical Group |
| LimaCorporate |
| Medacta International |
| Others |
Value Network & Pricing Analysis
EU Medical Device Regulation sustainability disclosure mandates gate qualified supply access and premium-tier pricing for revision knee manufacturers seeking European market entry. Compliance with enhanced notified body scrutiny for class III implantable devices separates vendors capable of commanding premium positioning from those restricted to standard-tier contract structures.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with domestic foundry capacity and penalizes those dependent on extended cobalt-chromium supply chains. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) predicate equivalence depth and proprietary bearing surface certification. Price erosion runs through standard-tier fixed bearing constructs as hospital purchasing committees consolidate around bundled orthopedic portfolios. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge economics, while academic medical centers prioritize component longevity over unit cost.
Supply Chain Analysis
Workforce availability constraints in Warsaw, Indiana and Baden-Württemberg, Germany concentrate precision machining and implant-grade alloy foundry capacity. Raw material sourcing draws from limited cobalt-chromium suppliers and specialized porous titanium substrate producers. Single-source vulnerability in trabecular metal architecture feedstock exposes manufacturers to supply disruption. Distribution runs through integrated delivery network central warehouses with surgeon-specific instrument kit deployment to hospital and ASC sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into implant-grade alloy foundry capacity and captive supply of porous titanium substrates defines the vertical-integration race in revision knee replacement. Control over critical raw material inputs separates pricing-power leaders from contract-dependent competitors.
For Market Incumbents: Deepen surgeon training infrastructure investments to defend against mid-cap extremities specialists cross-selling revision platforms. Lock in multi-year GPO contracts across trauma, spine, and joint replacement categories before ASC volume migration accelerates. Prioritize FDA 510(k) submission pipeline expansion for modular construct iterations to extend predicate device portfolios.
For New Entrants and Emerging Players: Ambulatory surgical center management companies represent the most accessible channel partner type for circumventing incumbent hospital contract lock-in. Target straightforward aseptic loosening cases in Arizona and Colorado where CMS reimbursement expansion creates new site-of-care entry points. Deploy patient-specific 3D-printed augments as differentiation wedge against established off-the-shelf sleeve portfolios.
For Investors and Strategic Acquirers: FDA 510(k) clearance for novel cementless fixation surfaces is the leading indicator that biological osseointegration technology has achieved de-risked commercial viability. Focus acquisition screening on mid-cap specialists with proprietary porous titanium architectures and established European MDR technical documentation. Watch CMS outpatient procedure volume thresholds as signal for ASC infrastructure investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification for modular revision constructs accelerates predicate-based clearance pathways. |
| CE Marking Pathway | EU MDR technical documentation compliance enables European market access for rotating platform designs. |
| Hospital System Partnership | Integrated delivery network bundling secures operating room access across orthopedic categories. |
| Software Companion Development | Remote patient monitoring platforms enable postoperative gait analysis for early loosening detection. |
| Reimbursement Strategy | CMS outpatient designation lobbying shapes ASC-based revision procedure economics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this revision knee replacement analysis. Primary interviews with orthopedic surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers validated implant utilization patterns and procurement decision criteria. FDA 510(k) premarket notification database, EU MDR notified body public summaries, CMS Medicare claims data, and hospital procurement databases supplied quantitative anchors. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Data-stream reconciliation across product type, delivery model, end user, and fixation technology dimensions shaped the analytical framework. Segmentation modeling incorporated bearing surface mobility, care site economics, provider consolidation patterns, and biological versus mechanical fixation preferences. CAGRs were derived from fitted growth curves applied to procedure volume and implant pricing trajectories. Surgeon training pipeline constraints and regulatory approval timeline variability informed scenario boundaries.
Caveats apply where FDA evidentiary requirement shifts or EU MDR implementation delays could materially shift the outlook. Forecasts reflect assumptions regarding CMS reimbursement stability and cobalt-chromium supply chain continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Limb Salvage Systems Market