
 Unicompartmental Knee Prosthesis Market | 2026-2036
Unicompartmental Knee Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Unicompartmental Knee Prosthesis Market Outlook
MDR is restructuring the European cost-of-entry calculus for unicompartmental knee prosthesis manufacturers, demanding expanded clinical evidence portfolios and notified body recertification. Zimmer Biomet leverages its established European regulatory infrastructure to navigate these compliance thresholds. Stryker Corporation anchors its position through R&D intensity in cementless fixation platforms. Smith & Nephew plc differentiates via specialized mobile bearing geometries.
A unicompartmental knee prosthesis replaces a single diseased compartment—medial, lateral, or patellofemoral—of the knee joint with a metallic femoral component articulating against a polyethylene tibial insert, typically manufactured through cobalt chrome casting and ultra-high molecular weight polyethylene machining. Mobile bearing designs permit greater rotational freedom and reduced contact stress compared with fixed bearing alternatives, though fixed bearing constructs retain manufacturing simplicity and broader surgeon familiarity. Cementless technology is gaining structural momentum as osseointegration coatings improve, while patient specific instrumentation reshapes preoperative planning workflows across hospital systems.
FDA 510(k) pathways govern US market access, requiring substantial equivalence demonstrations that shape product development timelines, while the EU MDR and ISO 14155 clinical investigation standards enforce escalating evidence burdens across European jurisdictions. Japan's PMDA maintains distinct biocompatibility testing protocols that condition entry for foreign manufacturers. Stakeholders must monitor regulatory divergence between major markets to optimize parallel submission strategies and avoid fragmented approval timelines.
Market Dynamics
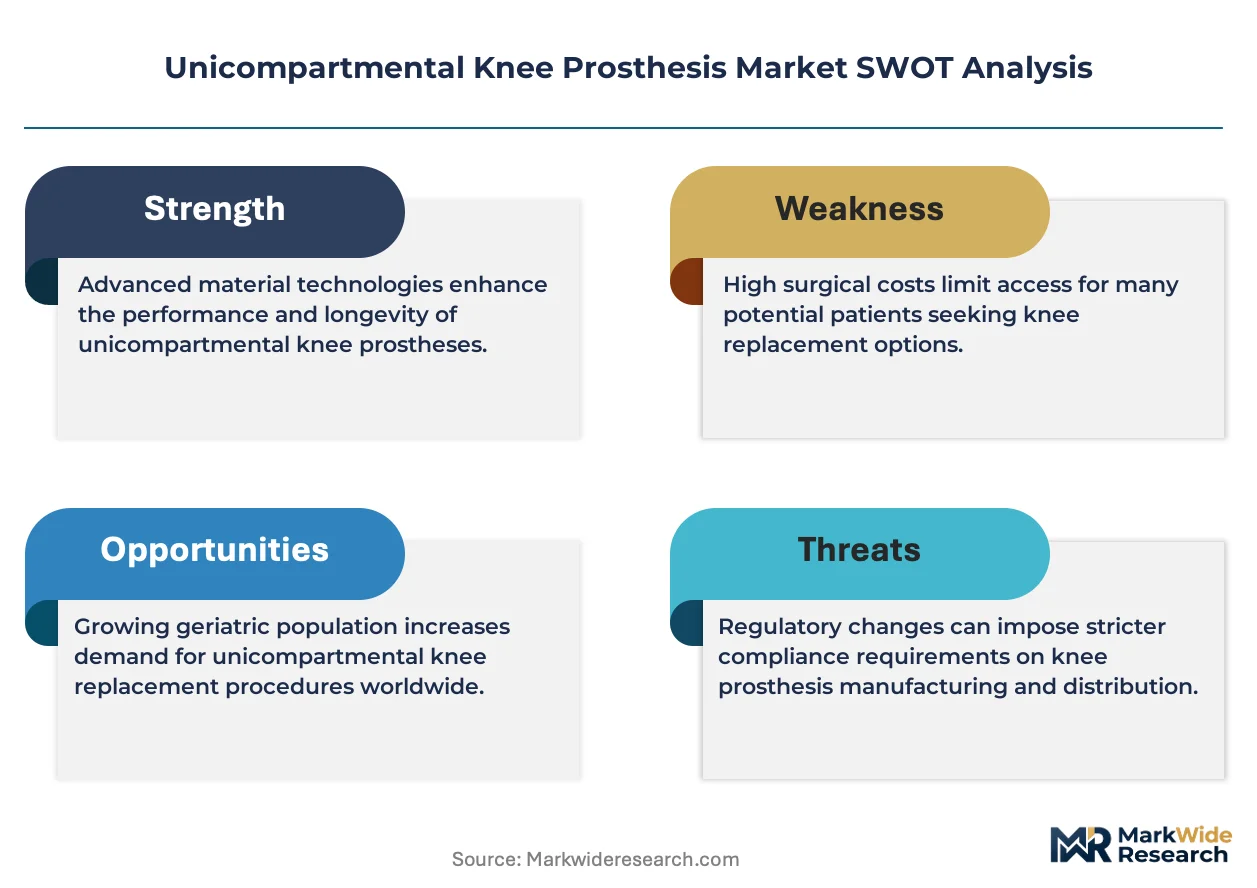
The EU Medical Device Regulation is restructuring market entry economics for unicompartmental knee prosthesis manufacturers, forcing portfolio-wide clinical evidence regeneration and notified body recertification that favors incumbents with established regulatory infrastructure.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient facilities in the United States are building dedicated orthopedic surgery suites, creating procedural volume pull-through for partial knee interventions.
- REACH compliance harmonization:European cobalt chrome and polyethylene material standards are converging, reducing formulation fragmentation and accelerating cross-border supply scaling.
- Cementless fixation coatings:Porous titanium and hydroxyapatite surface technologies are improving osseointegration rates, expanding eligible patient demographics toward younger, more active cohorts.
Market Restraints
- Cobalt chrome price volatility:Mining concentration in the Democratic Republic of Congo and processing bottlenecks in China create input cost instability for femoral component foundries.
- Notified body capacity constraints:EU MDR implementation has collapsed the number of certified auditors, extending recertification timelines to 18-24 months for legacy device portfolios.
- Total knee arthroplasty substitution:Improved polyethylene durability in bicompartmental systems is compressing the clinical indication window for partial knee solutions.
Strategic Opportunities
- Japan PMDA pathway optimization:Biocompatibility testing protocol alignment between ISO 10993 and Japanese standards is opening streamlined entry for manufacturers with existing European technical files.
- Patient-specific instrumentation convergence:Preoperative CT-to-implant workflow integration with robotic surgical platforms is creating bundled procedure economics in German hospital systems.
- Mobile bearing geometry expansion:Rotational freedom advantages in lateral compartment applications represent underexploited design white space beyond dominant medial offerings.
Industry Challenges
- Polyethylene sterilization validation:Gamma versus ethylene oxide method disputes are prolonging 510(k) submission preparation and triggering FDA information request cycles.
- Surgeon retraining requirements:Fixed-to-mobile bearing technique transitions demand cadaveric lab investments and proctoring networks that strain mid-tier manufacturer commercial budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unicompartmental Knee Prosthesis Market |
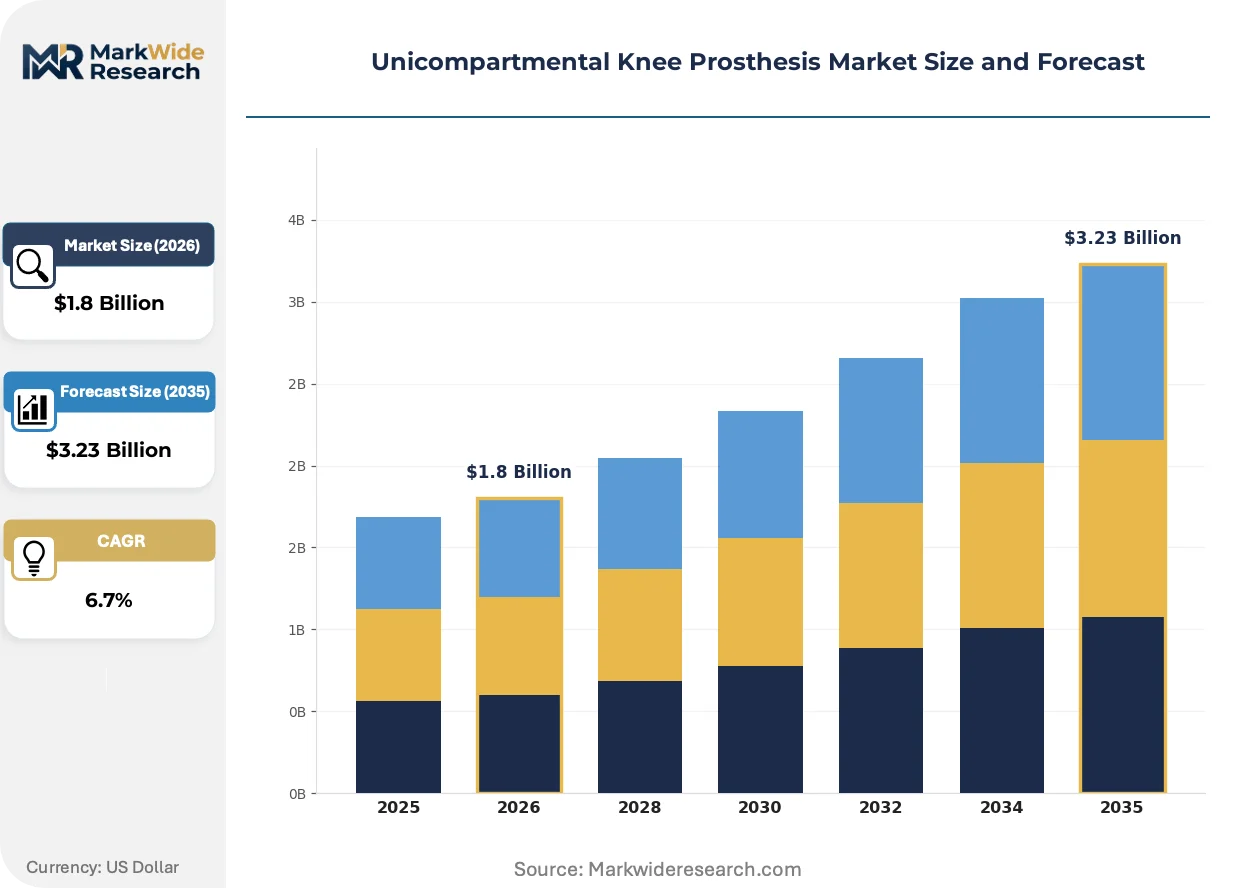
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bearing, Mobile Bearing, Partial Domed, Revision System End User: Hospitals, Clinics, Ambulatory Surgical Centers, Rehabilitation Facilities Technology: Cemented, Cementless, Hybrid, Patient Specific Material: Polyethylene, Cobalt Chrome, Titanium, Others |
| Companies Covered | Zimmer Biomet, Stryker Corporation, Smith & Nephew plc, Johnson & Johnson MedTech, Medacta International, Exactech, Inc., Arthrex, Inc., Enovis Corporation, Amplitude Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unicompartmental Knee Prosthesis Market Strategic Shifts
Three distinct vectors are restructuring competitive positioning in unicompartmental knee prosthesis development: surgical workflow decentralization, evidence-generation regulatory escalation, and procurement model consolidation around value-based frameworks.
Robotic-assisted surgical planning is decentralizing preoperative templating authority from centralized radiology departments to orthopedic surgeon workstations. Ambulatory surgical centers in Florida and Texas are deploying compact CT-integrated planning systems that compress case scheduling from weeks to days. This shift is fragmenting historical hospital radiology dependencies and enabling direct-to-facility implant logistics.
EU MDR Article 61 clinical evidence requirements are forcing manufacturers to regenerate equivalence arguments for legacy predicate devices. The notified body recertification burden is compressing active product portfolios as firms sunset marginal SKUs to concentrate resources on high-volume lines. German manufacturers with established PMCF study infrastructure are accelerating market share consolidation against late-adapting competitors.
Hospital procurement committees are consolidating vendor relationships around single-source agreements that bundle implants with instrumentation and revision liability coverage. Integrated delivery networks in California and New York are displacing traditional distributor intermediaries with direct manufacturer contracts that exchange volume commitments for price protection mechanisms. This concentration is most visible in metropolitan health systems with captive ambulatory surgery capacity.
Unicompartmental Knee Prosthesis Market Segmentation
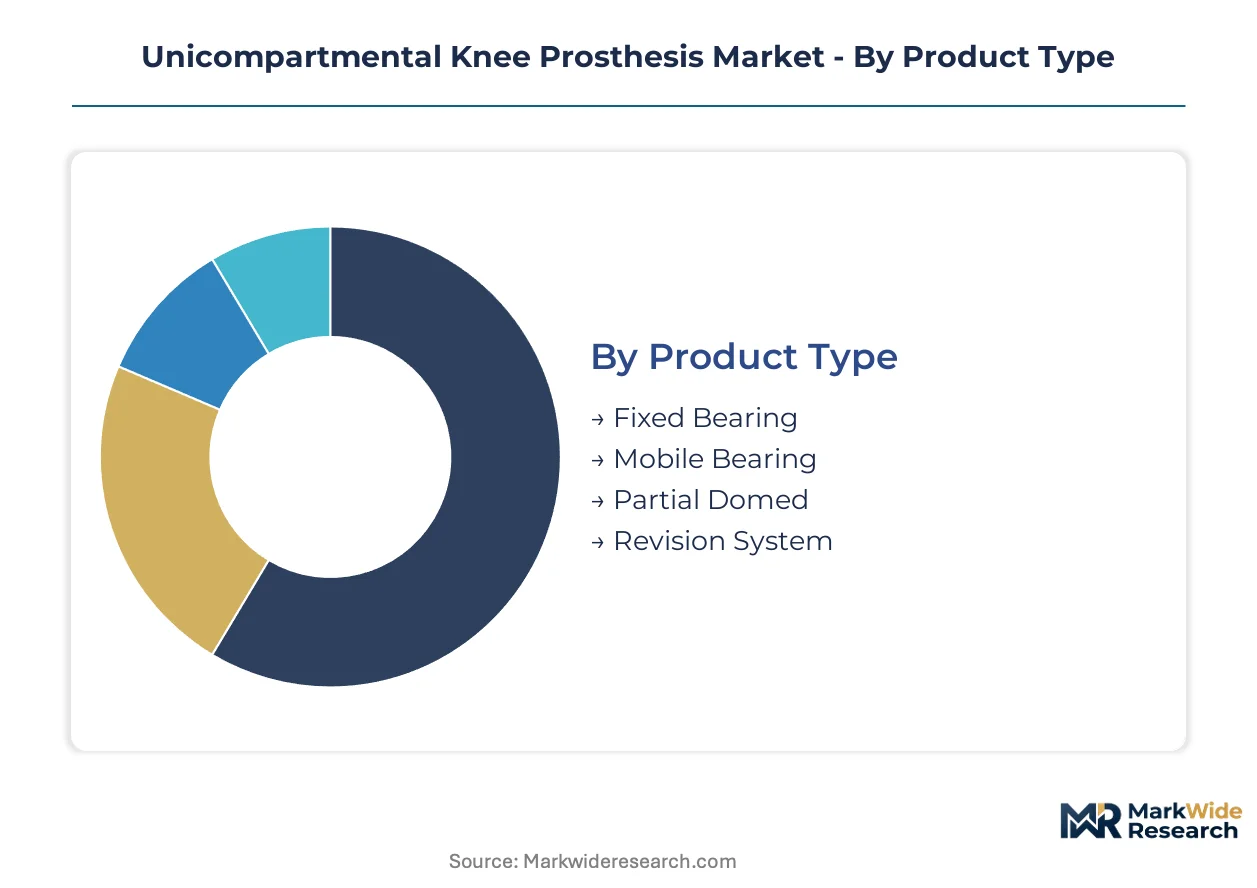
Segmentation in unicompartmental knee prosthesis markets reveals how surgical setting economics, fixation philosophy, and material science converge to shape procurement decisions. Manufacturers configure product portfolios across these dimensions to match reimbursement pathways and surgeon training investments.
Product Type:
Fixed bearing designs operate as standalone constructs with locked tibial inserts, while mobile bearing systems embed rotational freedom into the articulating interface.
- Fixed Bearing:Locked polyethylene tibial inserts against metallic femoral components deliver manufacturing simplicity and established surgical technique familiarity. Hospital systems in Germany and the United States concentrate procurement here due to lower instrumentation costs and broader surgeon training penetration.
- Mobile Bearing:Rotating platform designs permit polyethylene insert rotation relative to the tibial tray, reducing contact stress and wear debris generation. Ambulatory surgical centers in Florida and Texas are expanding adoption for younger, higher-activity patients seeking longevity advantages.
- Partial Domed:Patellofemoral compartment solutions with spherical articulating surfaces address isolated anterior knee pathology.
- Revision System:Augmented fixation and modularity components enable conversion from failed primary unicompartmental constructs.
Fixed bearing leads volumes today; mobile bearing is gaining share fastest.
End User:
Cost tier stratification separates high-acuity inpatient settings from streamlined outpatient economics.
- Hospitals:Inpatient orthopedic departments manage complex comorbidities and revision contingencies with full ancillary support.
- Clinics:Office-based surgical facilities concentrate on diagnostic workup and postoperative monitoring.
- Ambulatory Surgical Centers:Dedicated orthopedic suites with compact CT-integrated planning systems compress case scheduling from weeks to days in Texas and Florida markets.
- Rehabilitation Facilities:Post-acute settings manage functional recovery protocols and long-term outcome tracking.
Ambulatory surgical centers are climbing the fastest as outpatient migration accelerates.
Technology:
Application intensity varies from cemented standard-of-care to patient-specific workflow integration.
- Cemented:Polymethylmethacrylate fixation remains the dominant technique with established long-term survival data and familiar surgical workflows.
- Cementless:Porous titanium and hydroxyapatite coatings enable biological osseointegration, expanding eligible demographics toward younger, more active cohorts in German hospital systems.
- Hybrid:Cemented tibial and cementless femoral combinations address specific bone quality variations.
- Patient Specific:CT-derived instrumentation and implant geometries integrate with robotic surgical platforms to create bundled procedure economics.
Cemented technology anchors current volumes; patient specific instrumentation shows steepest expansion trajectory.
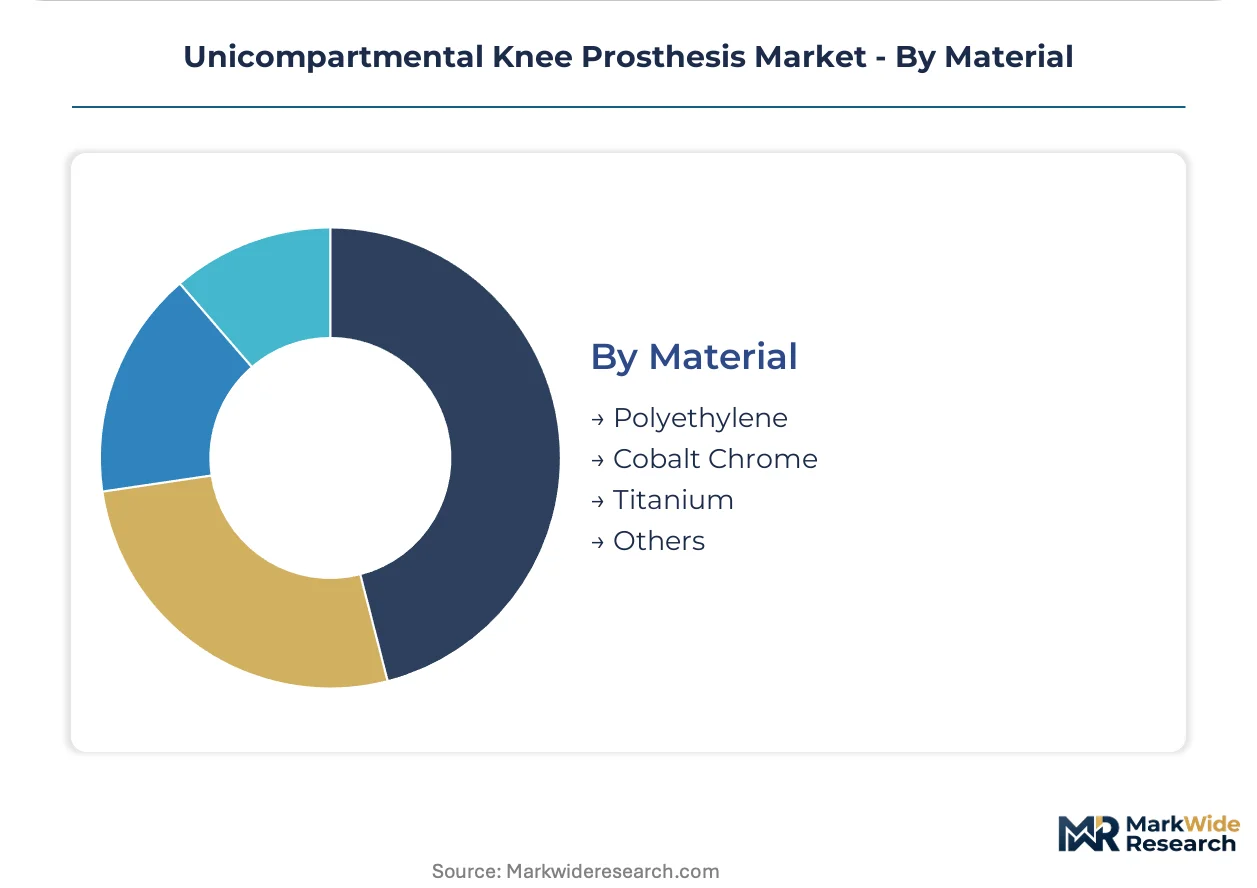
Material:
Supply concentration and REACH compliance harmonization are reshaping material selection economics.
- Polyethylene:Ultra-high molecular weight polyethylene machining produces tibial inserts with wear-resistant properties. Gamma versus ethylene oxide sterilization disputes are prolonging FDA 510(k) preparation cycles.
- Cobalt Chrome:Casting and forging of cobalt-chromium-molybdenum alloys delivers femoral component strength and biocompatibility. Mining concentration in the Democratic Republic of Congo and Chinese processing bottlenecks create input cost instability.
- Titanium:Porous additive manufacturing and plasma-sprayed surfaces enable cementless fixation platforms with improved osseointegration rates.
- Others:Oxidized zirconium and ceramic composites address niche wear and biocompatibility requirements.
Polyethylene and cobalt chrome dominate current procurement; titanium is expanding most quickly as cementless adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The unicompartmental knee prosthesis industry traces its commercial origins to 1970s European orthopedic manufacturing, with German engineering centers establishing the foundational design architectures and precision machining standards that persist in modern cobalt chrome casting and polyethylene insert production.
United States
Outpatient migration drives procedural volume expansion, with Florida and Texas ambulatory surgical centers deploying compact CT-integrated planning systems that compress case scheduling timelines. FDA 510(k) pathways govern market access through substantial equivalence demonstrations that shape product development timelines. Hospital procurement committees in California and New York consolidate vendor relationships around single-source agreements bundling implants with instrumentation.
Germany
German hospital systems anchor European demand concentration, with cementless fixation platforms gaining structural momentum as osseointegration coatings improve. EU MDR Article 61 clinical evidence requirements force manufacturers to regenerate equivalence arguments for legacy predicate devices. The Rhine-Ruhr and Bavarian industrial clusters host established regulatory infrastructure and PMCF study capabilities that accelerate market share consolidation.
Japan
PMDA biocompatibility testing protocols condition entry for foreign manufacturers, with protocol alignment between ISO 10993 and Japanese standards opening streamlined entry pathways. METI oversees medical device reimbursement classifications that influence hospital procurement decisions. The Kanto region surrounding Tokyo concentrates orthopedic surgical volume and specialized training institutions.
United Kingdom
NHS procurement frameworks emphasize value-based assessment criteria for partial knee interventions, with integrated care systems consolidating orthopedic service lines. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for manufacturers maintaining dual market access. The Oxford and London metropolitan areas host specialized revision surgery centers managing complex conversion cases.
Australia
TGA medical device approval pathways maintain distinct evidentiary requirements that condition market entry timelines, with prosthesis list reimbursement determinations influencing private hospital procurement. The Sydney and Melbourne metropolitan corridors concentrate orthopedic surgical training programs and robotic-assisted surgical platform deployments. State-based health technology assessment processes create fragmented adoption timelines across jurisdictions.
Unicompartmental Knee Prosthesis Market Competitive Environment
The competitive structure tilts toward diversified orthopedic conglomerates with established regulatory infrastructure and specialized mid-tier manufacturers with focused fixation technology portfolios. Incumbents leverage scale advantages in notified body relationship management and clinical evidence generation, while smaller participants concentrate on single-technology differentiation in mobile bearing or cementless platforms. Dominant competitive moves include portfolio rationalization to concentrate resources on high-volume product lines and strategic partnerships with robotic surgical platform developers to secure bundled procedure economics.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker Corporation occupy positions representing established European regulatory infrastructure and R&D intensity in fixation platforms respectively. Smith & Nephew plc exemplifies specialized differentiation through focused bearing geometry expertise. Medacta International and Exactech, Inc. sit within the mid-tier specialist tier, representing Swiss and US-based fabricators with concentrated product portfolios. These five entities collectively illustrate the competitive spectrum spanning diversified scale advantages against specialized technology focus.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| Smith & Nephew plc |
| Johnson & Johnson MedTech |
| Medacta International |
| Exactech, Inc. |
| Arthrex, Inc. |
| Enovis Corporation |
| Amplitude Surgical |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up orthopedic conglomerates have consolidated manufacturing footprints across cobalt chrome foundries and polyethylene machining centers, compressing procurement costs while enforcing disciplined three-tier pricing structures across premium, standard, and economy implant tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and surgeon training certification status, with premium tiers commanding position through robotic platform bundling and extended revision liability coverage. Price differentiation rests on ISO 14155 clinical data completeness and mobile bearing geometry complexity. Cost compression in standard tiers is intensifying because ambulatory surgical centers in Florida and Texas are consolidating vendor relationships around volume-commitment contracts. Hospital procurement committees exhibit highest price sensitivity, while integrated delivery networks with captive surgery capacity prioritize total procedure economics over per-implant cost.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating concentrates component sourcing across German precision machining clusters, Chinese cobalt processing facilities, and US-based porous titanium additive manufacturing centers. Raw material dependencies center on Democratic Republic of Congo-mined cobalt, ultra-high molecular weight polyethylene resin from South Korean petrochemical complexes, and hydroxyapatite coatings from Japanese bioceramic specialists. Single-source vulnerability runs through Chinese cobalt refining capacity, where processing bottlenecks create input cost instability. Distribution runs through direct manufacturer contracts with hospital procurement committees, displacing traditional distributor intermediaries in metropolitan health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in unicompartmental knee prosthesis markets is anchored by cementless fixation platform premiums and patient-specific instrumentation bundling, which shift procurement value capture toward workflow-integrated solutions and away from commoditized implant transactions.
For Market Incumbents: Extend regulatory infrastructure advantages by accelerating EU MDR Article 61 clinical evidence regeneration for legacy predicate devices, concentrating portfolio resources on high-volume mobile bearing lines while sunsetting marginal SKUs that strain notified body recertification timelines. Cementless fixation R&D intensity represents the critical defensive lever against total knee arthroplasty substitution pressure.
For New Entrants and Emerging Players: Cementless fixation coating innovation offers the most penetrable technology-first wedge, particularly in German hospital systems where osseointegration platforms are gaining structural momentum among younger patient cohorts. Lateral compartment mobile bearing geometries represent underexploited design white space beyond dominant medial offerings. A robotic surgical platform partnership strategy secures bundled procedure economics without requiring full distribution infrastructure buildout.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialists with concentrated mobile bearing or cementless technology portfolios but underdeveloped regulatory infrastructure. Long-term viability over a multi-year window hinges on EU MDR compliance completion and PMDA pathway optimization for Japanese market entry. The signal to watch is notified body recertification timeline compression, which would accelerate market share consolidation toward first-mover compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Regeneration | PMCF study infrastructure investments accelerate notified body recertification timelines for legacy device portfolios. |
| Cementless Fixation Platform Expansion | Porous titanium and hydroxyapatite coatings expand eligible demographics toward younger, more active patient cohorts. |
| Robotic Surgical Platform Partnership | CT-to-implant workflow integration creates bundled procedure economics in German and US hospital systems. |
| Patient-Specific Instrumentation Development | Preoperative planning software companions differentiate procurement value beyond commoditized implant hardware. |
| Ambulatory Surgical Center Direct Contracting | Volume-commitment agreements with Florida and Texas outpatient facilities bypass traditional distributor markups. |
Study Parameters
Multiple input streams — surgeon interviews, hospital procurement committee discussions, biomedical engineering consultations, and GPO contracts manager briefings — were reconciled against FDA 510(k) filings, EU MDR technical documentation databases, PMDA submission records, and hospital procurement database extracts. Secondary validation drew from SEC orthopedic segment disclosures, trade customs data for cobalt chrome and polyethylene resin flows, and CMS Medicare procedure volume statistics. Bottom-up implant shipment modeling and top-down healthcare expenditure triangulation anchored market size estimation across the analysis window.
Data-stream reconciliation applied segmentation modeling across fixation technology, bearing geometry, surgical setting, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from procedure volume elasticity modeling against demographic aging trajectories and ambulatory surgical center capacity expansion rates. Cementless adoption curves and patient-specific instrumentation penetration timelines served as primary forecast sensitivity inputs.
The model holds under stable EU MDR implementation timelines and REACH compliance harmonization; deviation in notified body capacity constraints or cobalt supply disruptions would shift volume and value trajectories. A model refresh is warranted upon material change in FDA sterilization validation disputes or Japanese PMDA biocompatibility protocol alignment progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Knee Implants Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market