
 Global Optical Lens Market | 2026-2036
Global Optical Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Lens Market Foresight
Precision optics engineering talent is bifurcating the competitive landscape as Asian universities expand photonics programs faster than Western institutions. EssilorLuxottica leverages its integrated retail-lab network to sustain margin capture across prescription fulfillment. Carl Zeiss AG anchors high-end industrial microscopy through captive glass-melting facilities in Germany. HOYA Corporation dominates blue-light filtering substrates for digital device users across East Asian markets.
An optical lens is a transparent component with precisely curved surfaces that refract light to focus, magnify, or correct images, typically manufactured through precision grinding, polishing, or molding to tolerances within fractions of a wavelength. These components serve as the functional core of vision correction systems, imaging equipment, and photonic instruments where wavefront accuracy determines performance. Progressive lenses now command the highest value pool in vision correction as aging populations reject visible multifocal lines. Plastic substrates lead volume in consumer eyewear while high-index materials capture premium positioning for strong prescriptions. Camera application demand is accelerating fastest as computational photography requires aspherical and freeform geometries.
FDA device classifications, EU MDR conformity requirements, and Japan's PMDA quality standards collectively govern market access for medical and consumer optical lenses. REACH restrictions on cadmium and lead in coatings force reformulation of anti-reflective stacks across European supply chains. Stakeholders must monitor how ISO 9342-1 tolerances evolve for freeform surfaces as personalized lens design displaces conventional semifinished blanks.
Market Dynamics
Computational photography is forcing lens architectures toward aspherical and freeform geometries that traditional grinding cannot achieve economically, compressing margins for conventional spherical lens suppliers while rewarding precision molding specialists.
Growth Catalysts
- Multi-lens smartphone arrays:Camera module manufacturers embed three to seven lenses per device, multiplying unit demand per handset shipped.
- EU Green Deal coating mandates:REACH restrictions on heavy metals accelerate reformulation of anti-reflective stacks, creating first-mover advantage for compliant suppliers.
- Vietnam-Thailand production corridors:Assembly relocation from established bases concentrates investment in Southeast Asian precision optics parks with tax incentives.
Market Restraints
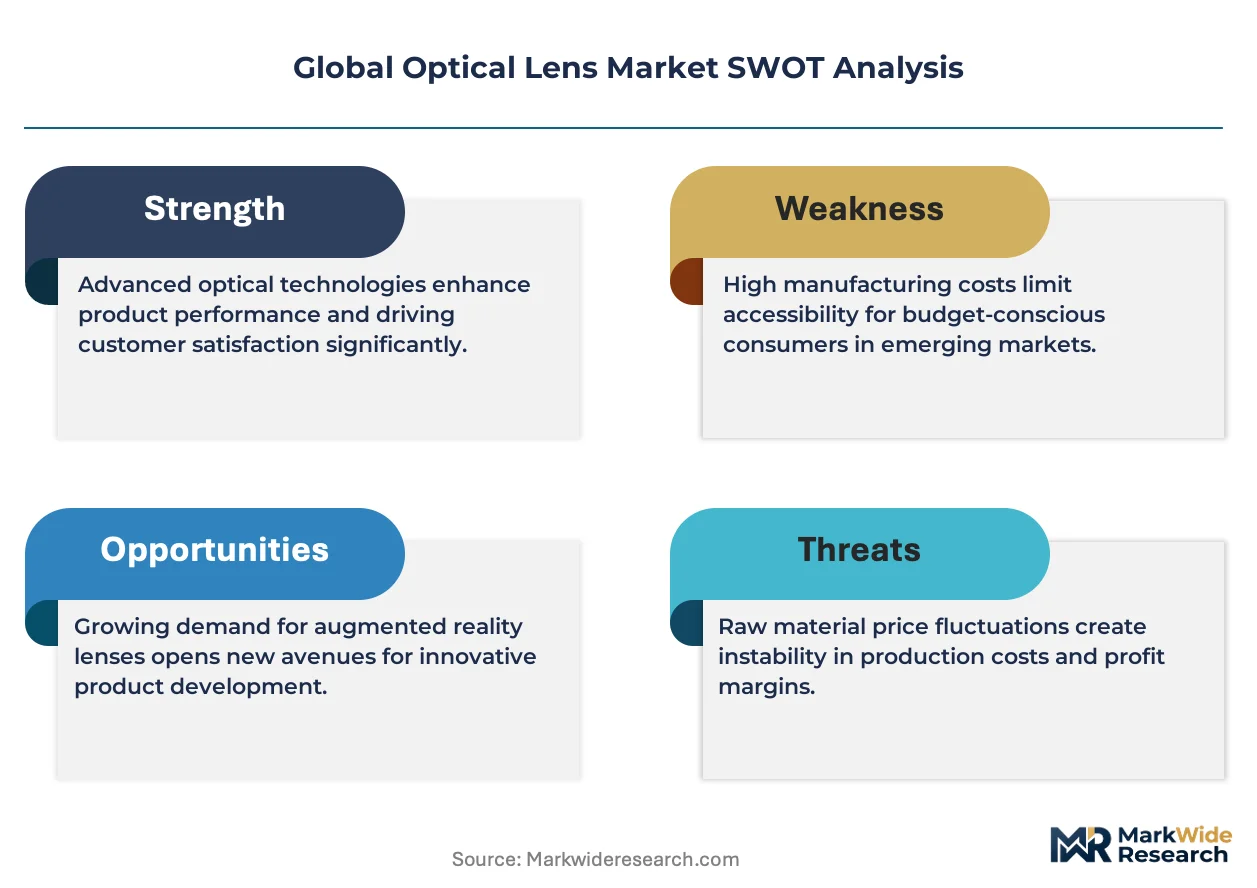
- High-purity optical glass supply:German and Japanese captive melting facilities control premium substrate access, limiting new entrants to commoditized plastic alternatives.
- REACH cadmium-lead phaseout:European coating reformulation adds 12-18 months to product qualification cycles for medical device lenses.
- Computational software substitution:Algorithmic image correction in smartphone post-processing reduces hardware lens complexity requirements for mid-tier devices.
Strategic Opportunities
- India vision correction penetration:Organized retail expansion and National Health Mission screening programs unlock underpenetrated prescription lens demand in tier-2 cities.
- AR-VR headset waveguides:Diffractive optics manufacturing capabilities developed for consumer electronics transfer to emerging spatial computing platforms.
- Blue-light filtering substrate standardization:Japan PMDA and Korea MFDS device classifications create regulatory tailwind for digital eye strain solutions across East Asian markets.
Industry Challenges
- Freeform surface metrology talent:ISO 9342-1 tolerance evolution outpaces university photonics program output, creating recruitment bottlenecks for personalized lens design labs.
- Multi-regulatory certification overlap:FDA device classification, EU MDR conformity, and Japan PMDA quality standards impose parallel compliance costs for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Lens Market |
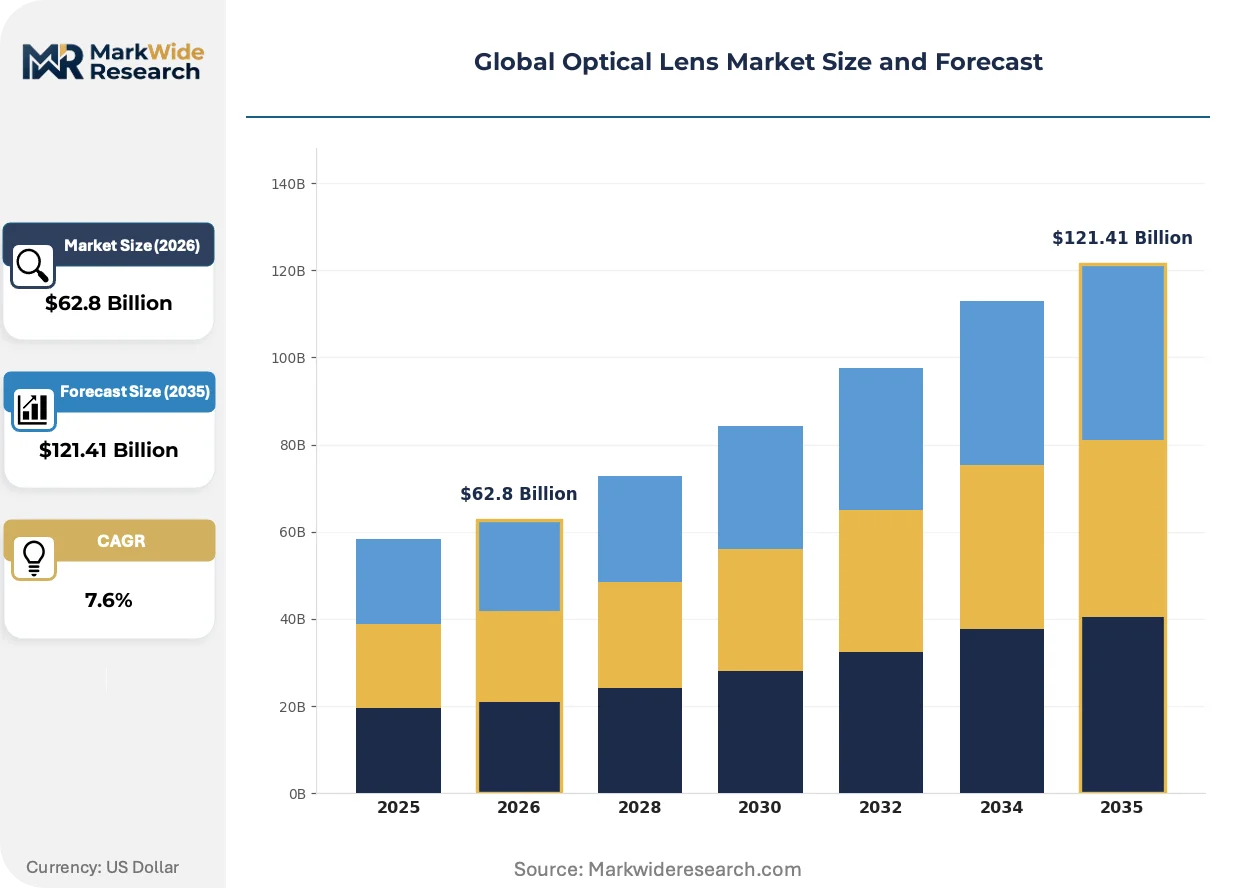
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $121.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Trifocal, Progressive, Photochromic, Polarized Material: Plastic, Glass, Polycarbonate, Trivex, High-Index, Acrylic Application: Eyeglasses, Cameras, Microscopes, Telescopes, Binoculars, Projectors End User: Optometrists, Photographers, Laboratory Technicians, Researchers, Sports Professionals, Imaging Specialists |
| Companies Covered | Nikon Corporation, Rodenstock, EssilorLuxottica, Seiko, Tokai Optical, Carl Zeiss AG, Bausch Health Companies, Thorlabs, HOYA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Lens Market Shifts & Advancements
Wavefront engineering capabilities are bifurcating manufacturer tiers as precision requirements diverge between mass-market molded optics and sub-wavelength tolerance instruments.
Precision glass molding is supplanting traditional grinding and polishing for smartphone camera lenses, automotive sensors, and medical endoscopes. Tier-one electronics contract manufacturers now specify molded aspheres for 80% of new camera module designs. This shift compresses cycle times from weeks to days while concentrating equipment investment among Japanese and German toolmakers.
EU MDR conformity requirements for medical device lenses tightened post-market surveillance obligations and clinical evidence standards. European notified bodies now demand extended follow-up data for implantable and prolonged-use optical devices. Ophthalmic manufacturers serving EU markets respond by consolidating regulatory affairs functions and accelerating notified body relationship investments.
Direct-to-consumer lens fulfillment is fragmenting traditional optometry channel control. Online vision testing platforms and remote prescription verification tools enable bypass of conventional optical retail. This pattern concentrates in North American and Northern European markets where regulatory frameworks permit remote refraction, compressing wholesale margins for lens laboratories dependent on independent optometrist networks.
Global Optical Lens Market Segmentation
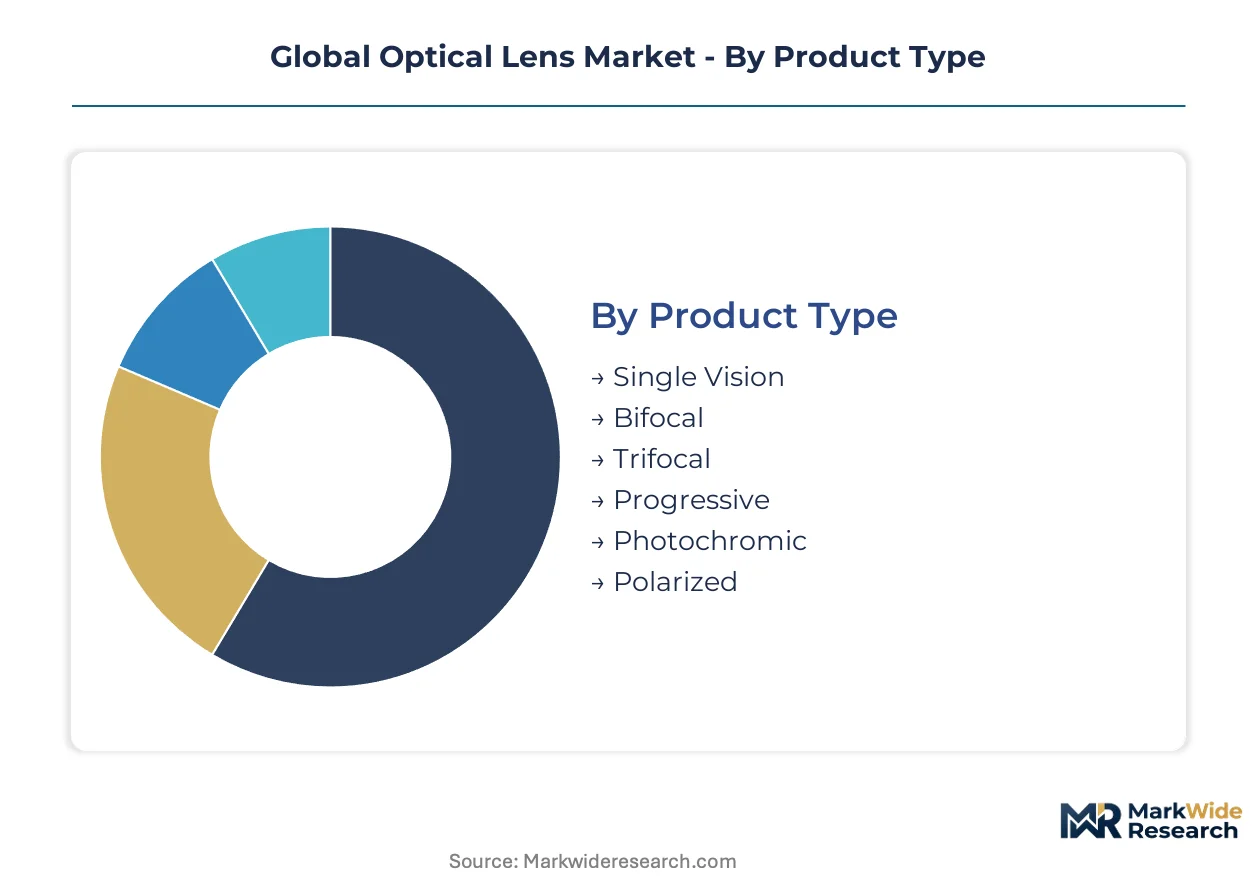
Segmentation reveals how substitution pressures and manufacturing economics reshape competitive boundaries across optical lens supply chains. Material choices increasingly determine margin architecture as molding technologies displace traditional grinding.
Product Type:
Computational photography and software-corrected vision are forcing substitution re-evaluation across prescription and imaging segments.
- Progressive:Multifocal surfaces without visible lines address presbyopia through continuous power gradients. Aging demographics in Germany and Japan sustain premium positioning despite higher fitting complexity.
- Single Vision:Uniform optical power across the entire lens surface serves myopia and hyperopia correction. Volume concentrates in India and Vietnam as organized retail penetrates tier-2 cities.
- Bifocal:Two distinct optical zones separated by a visible line serve near and distance vision. Demand softens as progressive designs capture preference among presbyopic users.
- Trifocal:Three power zones accommodate near, intermediate, and distance vision. Niche positioning persists among specific occupational users.
- Photochromic:Light-adaptive molecules embedded in substrate darken under UV exposure. Transitions Optical maintains technology leadership through proprietary dye chemistry.
- Polarized:Laminated filter layers block horizontal glare for outdoor and driving applications. Maui Jim and Oakley anchor premium positioning in sports eyewear channels.
Single Vision anchors the volume base while Progressive gains share at the steepest rate.
Material:
Cost tier stratification separates commodity substrates from performance materials commanding 3-5x price multiples.
- Plastic:CR-39 resin dominates consumer eyewear through grindability and tint compatibility. EssilorLuxottica and HOYA operate captive CR-39 polymerization plants in Thailand.
- High-Index:Refractive indices above 1.60 enable thinner profiles for strong prescriptions. Japanese and German glass-melting facilities control premium substrate access.
- Polycarbonate:Impact-resistant thermoplastic serves safety eyewear and pediatric applications. FDA device classifications mandate polycarbonate for industrial protective lenses.
- Glass:Schott AG and Ohara Corporation maintain captive melting for precision instruments. REACH cadmium-lead restrictions accelerate coating reformulation for European medical devices.
- Trivex:PPG Industries' urethane-based material combines impact resistance with optical clarity. Military and tactical applications sustain niche demand.
- Acrylic:PMMA substrates serve disposable and low-cost magnifying applications. Injection molding enables high-volume production of reading aids.
Plastic commands absolute volume leadership while High-Index climbs the fastest among premium tiers.
Application:
Customer type divergence separates mass-market fulfillment from specialized instrument integration.
- Cameras:Aspherical and freeform geometries enable computational photography architectures. Largan Precision and Sunny Optical concentrate molded glass capacity in Vietnam.
- Eyeglasses:Prescription fulfillment integrates surfacing, coating, and edging into retail-lab networks. EU MDR conformity requirements tightened post-market surveillance for prolonged-use devices.
- Microscopes:Sub-wavelength tolerances demand captive glass-melting and precision polishing. Carl Zeiss AG anchors industrial and life sciences segments through Oberkochen facilities.
- Telescopes:Large-diameter optics require specialized annealing and stress-relief protocols. Amateur astronomy and defense applications sustain low-volume demand.
- Binoculars:Porro and roof prism configurations demand phase-corrected coatings. Birding and hunting channels support mid-tier pricing.
- Projectors:Condenser and projection lenses serve cinema and corporate display installations. Laser phosphor and LED illumination shift thermal load requirements.
Eyeglasses anchors the volume base while Cameras expands most quickly through smartphone module proliferation.
End User:
Procurement authority concentration varies from fragmented independent practitioners to consolidated electronics contract manufacturers.
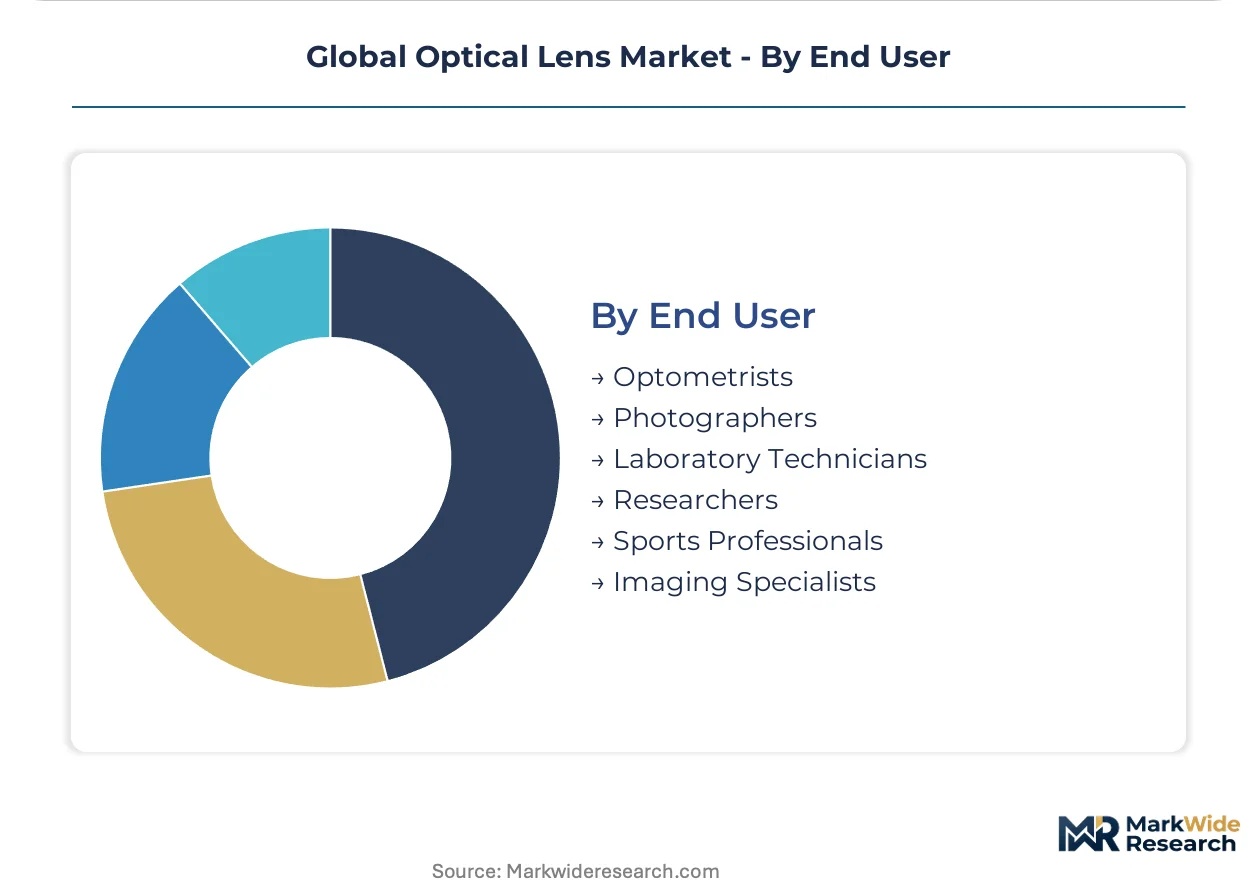
- Optometrists:Independent practitioners and retail chains control prescription lens dispensing. Direct-to-consumer platforms fragment traditional channel control in North America.
- Photographers:Professional and enthusiast segments demand interchangeable lens systems. Canon and Nikon specify molded aspheres for mirrorless camera lines.
- Imaging Specialists:Machine vision and medical imaging integrators specify custom optical assemblies. ISO 9342-1 tolerances govern freeform surface qualification.
- Researchers:Academic and government laboratories procure precision instruments through grant-funded channels. National Science Foundation and European Research Council funding cycles drive demand timing.
- Laboratory Technicians:Clinical and industrial labs operate microscopes and analytical instruments. Preventive maintenance contracts sustain replacement lens demand.
- Sports Professionals:Performance eyewear serves cycling, skiing, and water sports applications. Polarized and photochromic configurations dominate this channel.
Optometrists anchor the volume base while Imaging Specialists gains share fastest through automation and medical device expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device classifications anchor the United States as the dominant geography for medical optical lens compliance, with EU MDR and Japan PMDA standards creating parallel certification corridors that shape competitive access across developed markets.
United States
Smartphone camera module demand from Apple and Google suppliers drives precision molding investment. FDA Class II device classifications govern extended-wear contact lenses and intraocular implants. Rochester, New York maintains historical optics manufacturing density through University of Rochester photonics programs.
Germany
Industrial microscopy and automotive sensor applications sustain high-index glass substrate demand. REACH cadmium-lead restrictions force coating reformulation for European medical device exports. Oberkochen and Jena concentrate captive glass-melting facilities and precision polishing capabilities.
Japan
Aging demographics sustain progressive lens premium positioning through independent optometry channels. PMDA quality standards and JIS tolerances govern freeform surface qualification for personalized lens design. Hamamatsu photonics corridor anchors machine vision and medical imaging component supply.
Vietnam
Electronics contract manufacturers relocate camera module assembly from established East Asian bases. Corporate income tax incentives in precision optics parks attract molding equipment investment. Bac Ninh and Hai Phong industrial zones concentrate lens grinding and coating operations.
India
National Health Mission vision screening programs unlock underpenetrated prescription demand in tier-2 cities. BIS certification requirements and CDSCO medical device rules govern market access for imported lenses. Gujarat and Tamil Nadu organized retail expansion concentrates surfacing laboratory networks.
Global Optical Lens Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the optical lens supply chain. The market structures around three tiers: integrated retail-lab networks controlling prescription fulfillment, captive substrate specialists commanding premium glass access, and precision molding houses serving electronics contract manufacturers. Consolidation pressure concentrates among prescription lens laboratories while imaging component supply fragments across specialized toolmakers. Dominant competitive moves include backward integration into polymerization plants and strategic partnerships with smartphone original equipment manufacturers.
Within the integrated retail-lab archetype, EssilorLuxottica and HOYA Corporation exemplify players combining prescription lens manufacturing with point-of-sale network control. Carl Zeiss AG occupies a position representing the captive substrate specialist archetype, with German and Japanese glass-melting heritage anchoring high-index material access. Nikon Corporation and Seiko sit within the precision instrument tier, translating optical engineering capabilities across photography and industrial inspection applications.
| Leading Market Players |
|---|
| Nikon Corporation |
| Rodenstock |
| EssilorLuxottica |
| Seiko |
| Tokai Optical |
| Carl Zeiss AG |
| Bausch Health Companies |
| Thorlabs |
| HOYA Corporation |
| Others |
Supply & Pricing Matrix
Captive glass-melting scale economies in Germany and Japan establish price floors that commoditized plastic substrate producers cannot undercut, concentrating margin capture among substrate specialists while forcing grinding-dependent laboratories toward precision molding partnerships or exit.
Pricing Analysis
Geographic price spreads of 3-5x separate German high-index glass substrates from Vietnamese-molded plastic alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by material refractive index and coating complexity. Pricing pressure stems from computational photography reducing hardware lens counts in mid-tier smartphones. Independent optometrists exhibit highest price sensitivity, while imaging specialists accept premium positioning for sub-wavelength tolerance instruments.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam lanes and container availability constraints on intra-Asia routes elevate inbound logistics costs for European coating chemical shipments. Supply concentrates in Vietnam, Thailand, and Germany, with precision molding equipment anchored in Japanese and German toolmaker networks. Raw material dependencies include high-purity silica sand, rare-earth coating dopants, and CR-39 resin monomers. Single-source vulnerability from Schott AG and Ohara Corporation captive melting creates supply risk for medical device lens substrates. Distribution runs through electronics contract manufacturer specifications for camera modules and retail-lab networks for prescription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational photography and algorithmic image correction pose substitution threats that hardware lens suppliers must navigate through performance differentiation and regulatory-captured medical segments.
For Market Incumbents: Compound captive substrate advantages by deepening control over high-index glass melting and precision molding equipment supply. Accelerate REACH-compliant coating reformulation to capture first-mover qualification status in European medical device channels. Defend against software substitution by embedding wavefront engineering capabilities into personalized lens design workflows. For New Entrants and Emerging Players: Anchor in India tier-2 city vision correction penetration where organized retail expansion outpaces incumbent laboratory network coverage. Target blue-light filtering substrate standardization gaps across East Asian digital device markets. Pursue go-to-market partnerships with smartphone original equipment manufacturers seeking secondary source molded asphere supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated retail-lab networks controlling prescription fulfillment channels. Long-term viability over the projection horizon favors substrate specialists with captive melting heritage and precision molding houses serving electronics contract manufacturers. Monitor FDA device classification enforcement intensity as inflection indicator for medical optical lens margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization Plants | EssilorLuxottica and HOYA captive CR-39 production in Thailand secures cost control over commodity substrate supply. |
| Precision Molding Equipment Partnership | Japanese and German toolmaker alliances enable Vietnamese contract manufacturers to meet smartphone aspheric specifications. |
| REACH-Compliant Coating Reformulation | European heavy metal phaseout creates qualification barrier that first-mover suppliers convert into medical device market share. |
| Direct-to-Consumer Platform Launch | Online vision testing and remote prescription verification fragment traditional optometry channel control in North America. |
| Freeform Surface Metrology Talent Acquisition | ISO 9342-1 tolerance evolution outpaces university photonics program output, creating recruitment competition among personalized lens design labs. |
Research Methodology
A standing panel of ophthalmic laboratory directors, smartphone camera module procurement managers, precision optics tooling engineers, and regulatory affairs specialists provided ongoing calibration against secondary validation from SEC 10-K filings, EU MDR notified body guidance documents, Japanese PMDA quality circulars, and Vietnam industrial zone investment disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic anchors.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions spanned product type, material substrate, application category, and end-user procurement authority. CAGRs derived from fitted growth curves applied to disclosed capacity expansions and demand elasticity parameters specific to smartphone camera module proliferation and aging demographic vision correction penetration.
Material uncertainties — regulatory timeline shifts for REACH cadmium-lead phaseout, computational photography substitution acceleration, and precision molding equipment delivery delays — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Camera Module Lens Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Fixed Focal Length Lenses Market
Optics
Fiber Optic Development Tools Market
Optics
Germanium Lens Market
Optics
Europe Laser Interferometer Market
Optics
Anomaloscope Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Optical Receivers Market
Optics
Optical Profilometer Market
Optics
3D Optical Microscope Market
Optics
Beam Expanders Market
Optics
Asia Pacific Fiber Optics Market
Optics
Sports Optics Market
Optics
Optical Fiber Raw Material Market
Optics
Europe Smart Glass Market